
 Fixed Cutter Bits Market | 2026-2036
Fixed Cutter Bits Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Cutter Bits Market Foresight
Drilling contractors is bifurcating from exploration companies as the dominant procurement voice in fixed cutter bits. Baker Hughes leverages integrated drilling services to anchor long-term supply relationships with independent operators. Schlumberger Limited differentiates through proprietary polycrystalline diamond compact technology that extends bit life in abrasive formations. National Oilwell Varco controls manufacturing scale across multiple cutter substrate grades.
Fixed cutter bits are downhole drilling tools that shear rock through tungsten carbide or diamond-enhanced cutting elements bonded to steel or matrix bodies, typically operating at rotational speeds exceeding 100 RPM and weight-on-bit loads measured in thousands of pounds. Their primary purpose is to maintain directional precision and rate of penetration across abrasive and interbedded formations. PDC cutters lead the product type landscape due to superior wear resistance in shale applications, while directional drilling represents the fastest-growing application segment as lateral lengths extend. Matrix tooth configurations retain margin pools in geothermal and hard-rock environments where thermal degradation threatens polycrystalline structures.
API specification Q2 governs material traceability and quality management for domestic oilfield equipment, while ISO 10424-1 establishes international design and performance benchmarks for rotary drilling equipment. The EPA's methane emissions rules indirectly shape bit selection by rewarding faster drilling cycles that reduce rig-time emissions. Stakeholders must monitor how NHTSA-derived supply chain disclosure requirements and emerging SEC climate rules affect capital allocation toward drilling efficiency technologies.
Market Dynamics
Drilling contractors now command procurement decisions as exploration companies retreat from direct bit sourcing, concentrating purchasing power among fewer integrated service buyers and compressing supplier margins through bundled service contracts.
Growth Catalysts
- PDC cutter innovation:Polycrystalline diamond compact technology extends bit life in abrasive Permian Basin formations, reducing tripping frequency and rig-time costs for lateral drilling programs.
- EPA methane rules:Faster drilling cycles reduce fugitive emissions per well, rewarding operators who deploy premium fixed cutter bits that sustain higher rate-of-penetration across extended-reach laterals.
- Permian Basin concentration:Texas and New Mexico shale operators account for dominant demand pull, with drilling intensity in the Delaware and Midland sub-basins driving repeat purchase volumes.
Market Restraints
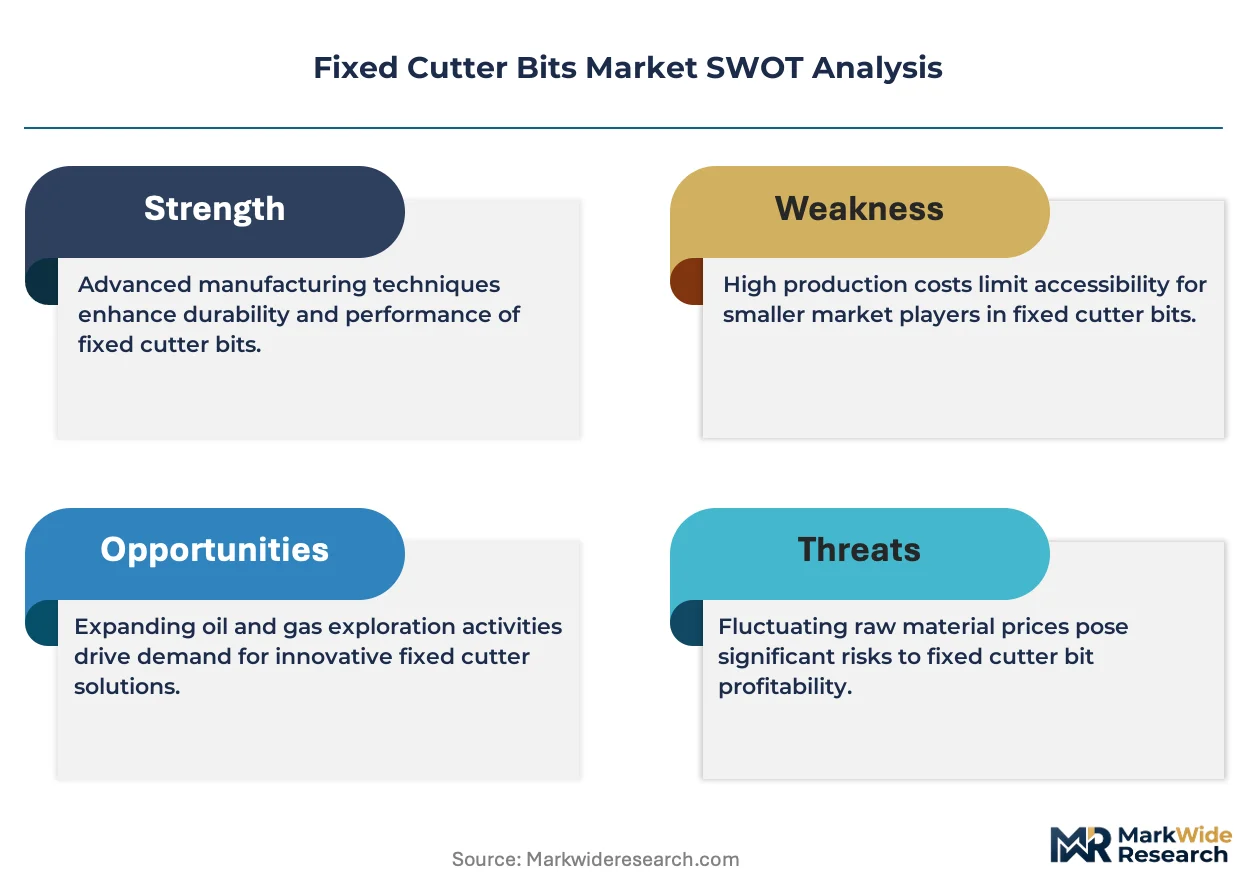
- Tungsten carbide price volatility:Sintered carbide substrate costs fluctuate with Chinese export quotas and mining supply disruptions, squeezing margin predictability for matrix-body bit manufacturers.
- API Q2 certification backlog:Material traceability requirements under the American Petroleum Institute specification create 12-18 month qualification timelines for new cutter substrate grades, freezing product development pipelines.
- Thermal degradation limits:Polycrystalline diamond structures suffer graphitization above 750°C, excluding PDC bits from geothermal and volcanic formation applications where matrix tooth configurations retain sole viability.
Strategic Opportunities
- Haynesville Shale underpenetration:Louisiana and East Texas gas-directed drilling lags oil-focused basins in PDC adoption intensity, presenting conversion upside as lateral lengths extend and bit economics improve.
- Real-time downhole analytics:Integration of vibration sensors and cutter wear telemetry with bit design enables predictive replacement scheduling, opening subscription-based service revenue streams.
- IRA clean drilling incentives:US tax credits for methane emissions reduction reward rapid drilling technologies, positioning premium fixed cutter bits as qualifying equipment for operator credit claims.
Industry Challenges
- ISO 10424-1 testing bottlenecks:International rotary drilling equipment standards require full-scale rig testing for design validation, constraining new product introduction velocity and R&D capital efficiency.
- Matrix-body welding skill scarcity:Tungsten carbide infiltration and furnace brazing expertise concentrates among aging specialist technicians, limiting manufacturing scale-up and quality consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Cutter Bits Market |
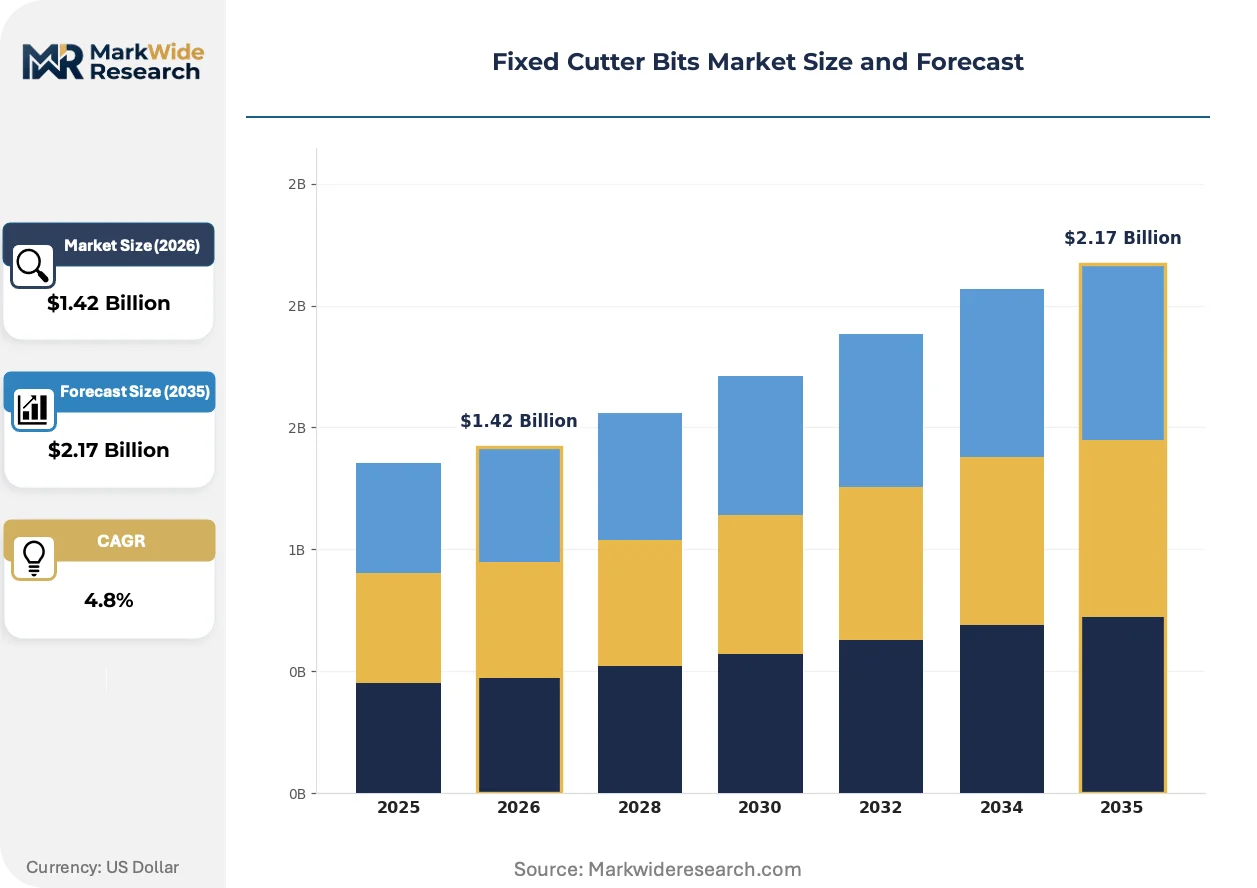
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Tooth, Matrix Tooth, Shear Cutter, PDC Cutter, Tungsten Carbide, Diamond Impregnated Application: Directional Drilling, Vertical Drilling, Horizontal Drilling, Extended Reach Drilling, Offshore Operations, Well Re-entry End User: Exploration Companies, Drilling Contractors, Well Servicing Firms, Oilfield Equipment Providers, Geological Surveyors, Field Operators Technology: Polycrystalline Diamond, Tungsten Carbide Inserts, Steel Alloy, Heat Treatment, Surface Coating, Wear Resistance |
| Companies Covered | Baker Hughes, Schlumberger Limited, National Oilwell Varco, Halliburton, Sandvik AB, Ulterra Drilling Technologies, Varel International, Archway Engineering, Infinity Tool Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Cutter Bits Market Shifts & Advancements
Fixed cutter bit engineering is pivoting toward data-integrated durability systems, with sensor-enabled cutters and predictive wear algorithms compressing replacement cycles and reshaping supplier-operator contractual relationships.
Thermally stable polycrystalline (TSP) cutter technology is supplanting conventional PDC structures in high-temperature drilling windows. Operators in the Anadarko Basin and Oklahoma STACK play are specifying TSP-enhanced bits for 400°F-plus bottom-hole conditions. The shift is compressing addressable market share for standard PDC designs in deeper, hotter unconventional targets.
EPA's methane emissions performance standards are tightening drilling efficiency benchmarks for US onshore operations. Operators must demonstrate reduced rig-time per completed lateral to comply with emissions intensity thresholds. This regulatory pressure is accelerating specification upgrades toward premium cutter grades that sustain penetration rates across interbedded formations.
Integrated drilling service contracts are displacing standalone bit procurement across independent operator segments. Baker Hughes and Schlumberger subsidiaries now bundle bit supply with directional drilling and logging services, capturing multi-year commitments. This bundling concentrates most visible in the Permian Basin, where capital-constrained independents prioritize all-in rate over component-level sourcing.
Fixed Cutter Bits Market Segmentation
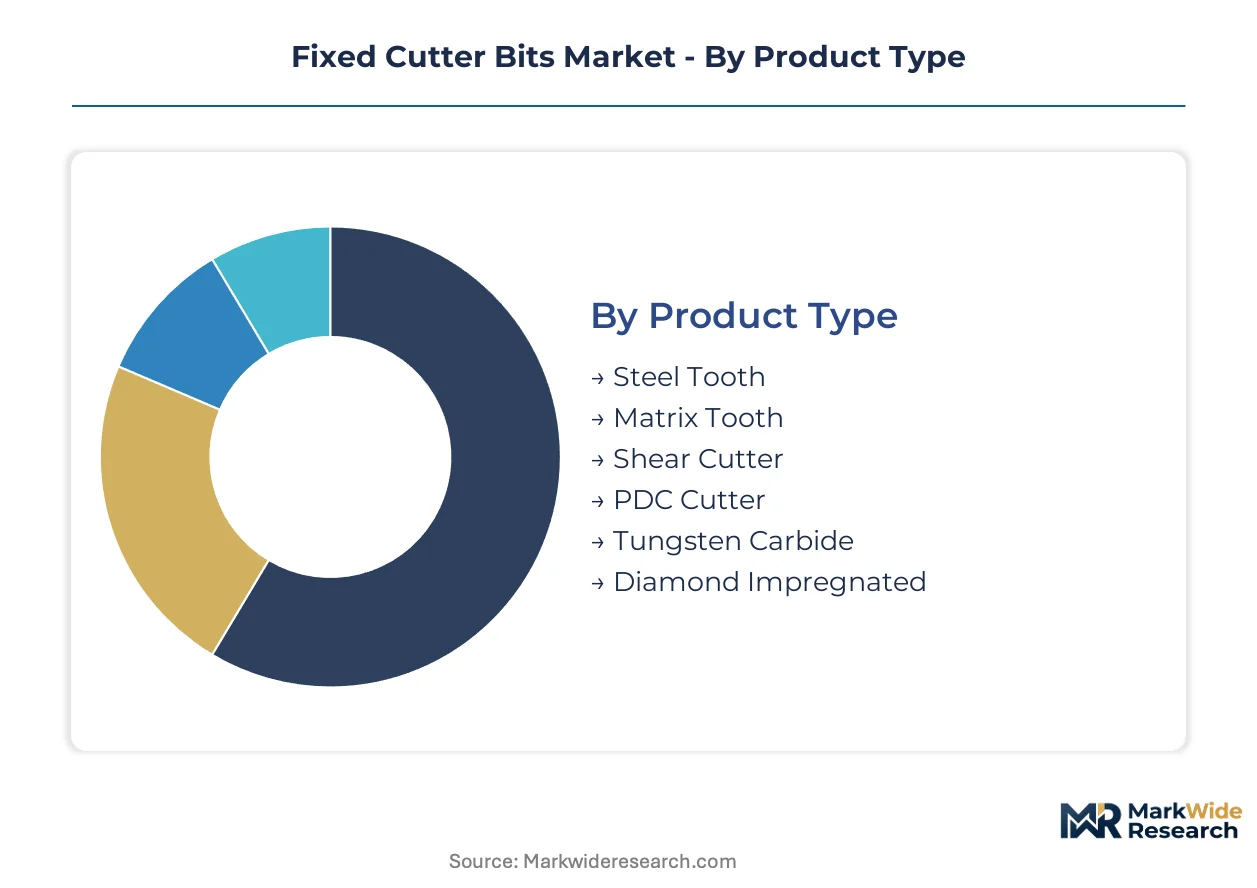
Fixed cutter bit procurement decisions fragment across multiple technical and commercial dimensions. Material specifications, drilling objectives, and operator procurement models each create distinct addressable segments with divergent margin profiles and qualification requirements.
Product Type:
API Q2 and ISO 10424-1 impose divergent material traceability burdens across substrate categories, with diamond-enhanced structures facing extended certification timelines versus conventional steel configurations.
- PDC Cutter:Polycrystalline diamond compact cutters bond synthetic diamond grit to tungsten carbide substrates through high-pressure high-temperature synthesis. Permian Basin operators in Texas and New Mexico specify these for extended-reach laterals where abrasion resistance dictates economic returns.
- Matrix Tooth:Tungsten carbide particles infiltrated with copper-nickel alloy binders form erosion-resistant cutting structures. Geothermal drilling in volcanic formations and deep hard-rock environments relies exclusively on matrix configurations where polycrystalline graphitization risks exclude PDC alternatives.
- Steel Tooth:Milled or forged steel cutting structures with surface hardening treatments serve vertical drilling programs in soft to medium formations.
- Shear Cutter:Single-crystal or synthetic diamond elements bonded to carbide posts provide aggressive cutting action in shale intervals.
- Tungsten Carbide:Cemented carbide inserts pressed into steel bodies balance cost and durability for routine development drilling.
- Diamond Impregnated:Natural or synthetic diamond grit distributed through metal matrix bonds targets ultra-hard abrasive formations.
PDC Cutter handles the majority of throughput; Matrix Tooth is expanding most quickly in high-temperature applications where thermal stability requirements intensify.
Application:
Drilling trajectory complexity determines cutter specification intensity, with lateral displacement distance and dogleg severity driving premium substrate selection.
- Directional Drilling:Steerable motor or rotary steerable systems demand bits that maintain gauge integrity through curved hole sections while delivering consistent rate of penetration. Delaware and Midland sub-basin operators push lateral lengths beyond 15,000 feet, concentrating demand for durable steerable configurations.
- Horizontal Drilling:Long lateral sections through interbedded shale require cutters that resist impact damage across formation transitions. Haynesville Shale gas-directed programs in Louisiana and East Texas are accelerating horizontal adoption as lateral economics improve.
- Vertical Drilling:Straight-hole development targets in conventional reservoirs employ simpler steel-tooth or basic PDC designs.
- Extended Reach Drilling:High step-out ratios from surface locations to reservoir contact stress bit durability through extended rotating hours.
- Offshore Operations:Platform or subsea drilling demands corrosion-resistant materials and premium quality assurance protocols.
- Well Re-entry:Sidetracking from existing wellbores requires milling-capable cutting structures to navigate casing exits.
Directional Drilling commands dominant procurement volumes; Horizontal Drilling is gaining share fastest as unconventional lateral lengths extend across US shale basins.
End User:
Procurement authority has shifted decisively toward service companies as exploration companies outsource integrated drilling management.
- Drilling Contractors:Integrated service providers now specify, procure, and deploy bits as part of bundled drilling contracts. Baker Hughes and Schlumberger subsidiaries leverage long-term supply relationships with Permian independents to anchor multi-year procurement commitments.
- Exploration Companies:Direct bit sourcing has retreated to specialized ultra-deepwater or international frontier programs where proprietary performance requirements persist.
- Well Servicing Firms:Workover and intervention specialists maintain discrete bit inventories for plug milling and window cutting operations.
- Oilfield Equipment Providers:Rental tool companies supply bits on day-rate arrangements for short-term drilling programs.
- Geological Surveyors:Scientific and government drilling programs specify bits for core recovery and stratigraphic testing.
- Field Operators:Small independent producers retain direct procurement for single-well or farm-out drilling arrangements.
Drilling Contractors handle the majority of throughput; Well Servicing Firms are climbing the fastest on share as plug-and-perf intensity rises in mature shale fields.
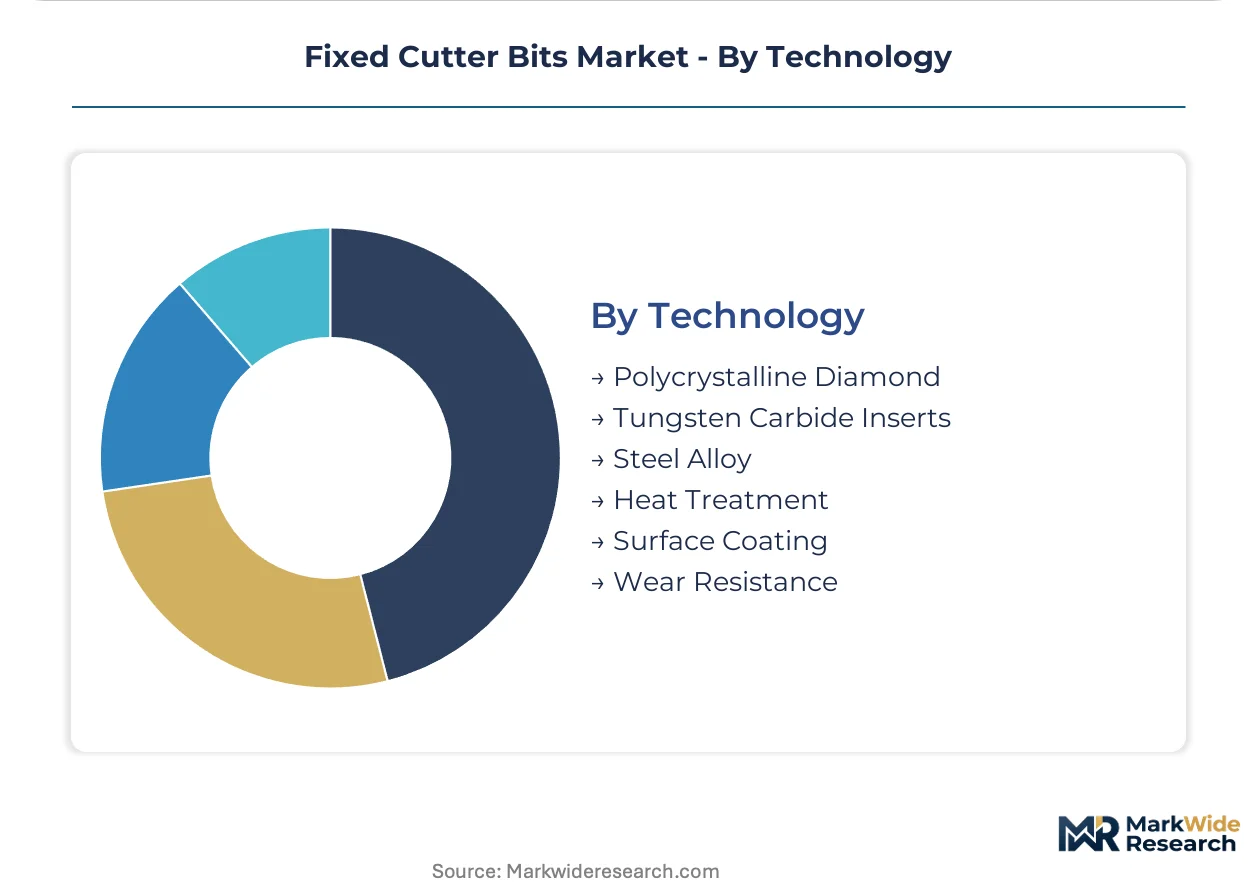
Technology:
Substrate innovation cycles differentiate competitive positioning, with thermal stability and wear prediction emerging as distinct technology investment vectors.
- Polycrystalline Diamond:HPHT-sintered diamond-to-diamond bonds with metallic catalyst removal enable 400°F-plus operating windows. Anadarko Basin and Oklahoma STACK plays specify thermally stable polycrystalline variants for deep hot unconventional targets.
- Surface Coating:Chemical vapor deposition diamond or hard-facing overlays extend cutter life through friction reduction and chemical protection. Real-time wear telemetry integration is opening predictive replacement service models.
- Tungsten Carbide Inserts:Conventional cemented carbide buttons and chisels retain cost-positioned applications in vertical development programs.
- Steel Alloy:Through-hardened or surface-hardened steel bodies provide economical platforms for replaceable cutter systems.
- Heat Treatment:Controlled quenching and tempering protocols optimize steel body toughness for impact resistance.
- Wear Resistance:Composite material engineering and geometric optimization reduce abrasive degradation rates.
Polycrystalline Diamond handles the majority of throughput; Surface Coating is the fastest mover on share as sensor integration enables outcome-based service contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US-based manufacturers dominate export flows to Latin American shale operators, while Chinese tungsten carbide substrate suppliers anchor raw material corridors into Middle Eastern drilling programs.
United States
Permian Basin drilling intensity in Texas and New Mexico drives premium PDC bit consumption as lateral lengths stretch beyond 15,000 feet. EPA methane emissions performance standards reward faster drilling cycles that reduce rig-time emissions. The Delaware and Midland sub-basins concentrate procurement volumes among integrated service contractors.
Canada
Montney Formation gas-directed drilling in British Columbia and Alberta sustains demand for thermally stable cutter configurations in high-pressure environments. The country's federal methane regulations align with provincial carbon pricing schemes that favor efficiency technologies. Calgary-based drilling contractors anchor procurement decisions for northern Alberta oil sands thermal projects.
Saudi Arabia
Horizontal drilling expansion in the Marjan and Zuluf field developments drives specification upgrades toward extended-reach bit designs. The national oil company's localization mandates under the In-Kingdom Total Value Add program require domestic manufacturing partnerships. Dammam's industrial corridor hosts joint ventures assembling matrix-body bits for offshore Red Sea programs.
China
Sichuan Basin shale gas development accelerates PDC adoption as operators replicate US unconventional techniques at scale. The Ministry of Ecology and Environment enforces drilling efficiency benchmarks that compress well construction timelines. Chongqing's manufacturing cluster supplies tungsten carbide substrates to domestic bit fabricators and export markets.
Brazil
Pre-salt carbonate drilling in the Santos Basin demands matrix-tooth configurations resistant to abrasive volcanic formations. The national petroleum regulator's local content requirements shape supplier qualification protocols for offshore rig tenders. Rio de Janeiro's equipment supply chain serves deepwater exploration programs with extended product development cycles.
Fixed Cutter Bits Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and manufacturing scale dimensions. The supplier base concentrates among integrated oilfield service conglomerates and focused cutter technology developers. Three archetypes dominate: diversified energy technology conglomerates, specialized downhole tool manufacturers, and regional fabrication specialists. Consolidation pressures favor bundled service contracts while niche players defend positions through substrate innovation and geographic focus.
Within the integrated service tier, Baker Hughes and Schlumberger occupy positions as archetypal full-service providers. Halliburton exemplifies the diversified energy technology conglomerate model. Ulterra Drilling Technologies represents focused specialists competing through cutter substrate differentiation rather than service bundling.
| Leading Market Players |
|---|
| Baker Hughes |
| Schlumberger Limited |
| National Oilwell Varco |
| Halliburton |
| Sandvik AB |
| Ulterra Drilling Technologies |
| Varel International |
| Archway Engineering |
| Infinity Tool Manufacturing |
| Others |
Supply & Pricing Matrix
API specification Q2 and ISO 10424-1 certification timelines gate both supplier qualification and price differentiation simultaneously, compressing margin pools for uncertified substrate grades while rewarding integrated manufacturers with pricing power across premium cutter tiers. Drilling contractors exploit this bifurcation through bundled procurement contracts that collapse component-level price transparency.
Pricing Analysis
Next-generation thermally stable polycrystalline cutters command 40-60% premiums over conventional PDC structures, while prior-generation steel-tooth configurations retreat to commodity pricing in vertical drilling applications. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and thermal performance rating, with API Q2-qualified substrates capturing margin premiums. Pricing pressure stems from bundled service contracts that mask bit-level economics, compressing standalone supplier margins. Independent operators exhibit highest price sensitivity, while integrated service contractors prioritize rate-of-penetration guarantees over unit cost.
Supply Chain Analysis
China anchors tungsten carbide substrate production, with Chongqing manufacturing clusters feeding domestic bit fabricators and export markets across Asia-Pacific and Middle Eastern drilling programs. Sintered carbide powders, synthetic diamond grit, and copper-nickel infiltration alloys constitute critical input dependencies. Single-source vulnerability concentrates in Chinese export quota regimes that disrupt carbide pricing predictability. Distribution runs through integrated oilfield service conglomerates that bundle bit supply with directional drilling and logging services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority has consolidated among integrated drilling contractors, fragmenting direct exploration company demand and compressing supplier pricing power through multi-year bundled commitments.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into tungsten carbide substrate production, securing supply continuity against Chinese export volatility. Deepen API Q2 certification pipelines to extend qualification timelines that freeze competitor product development. Prioritize real-time downhole analytics integration to shift revenue toward subscription-based predictive replacement services, defending margin pools against standalone bit commoditization. For New Entrants and Emerging Players: Lead with thermal stability specialization targeting geothermal and deep hard-rock applications where polycrystalline graphitization risks exclude incumbent PDC designs. Target Haynesville Shale gas-directed drilling in Louisiana and East Texas, where lateral length extension and bit economics improvement create conversion upside from underpenetrated matrix-tooth configurations. Pursue joint venture partnerships with regional fabrication specialists to bypass ISO 10424-1 testing bottlenecks. For Investors and Strategic Acquirers: EPA methane emissions performance standards reshape the acquisition landscape by rewarding rapid drilling technologies with tax credit eligibility, elevating premium fixed cutter bit manufacturers as qualifying equipment suppliers. Target specialists with thermally stable polycrystalline cutter portfolios and sensor-integrated durability systems, positioned for 5-10 year regulatory tailwinds. Monitor IRA clean drilling incentive utilization rates as inflection indicators for capital allocation toward drilling efficiency technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbide Substrates | Captive tungsten carbide supply insulates margins from Chinese export quota volatility. |
| Sensor-Integrated Cutter Development | Vibration telemetry enables predictive replacement scheduling and subscription revenue streams. |
| Thermal Stability Certification Investment | TSP cutter qualification opens geothermal and deep unconventional targets excluded from standard PDC. |
| Haynesville Shale Market Development | Louisiana and East Texas gas-directed drilling lags oil basins in PDC adoption intensity. |
| Integrated Service Contract Expansion | Bundled bit supply with directional drilling captures multi-year commitments from Permian independents. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drilling contractors, bit procurement managers, and downhole tool engineers; and secondary validation through API certification databases, EPA emissions filings, and customs trade records. Primary fieldwork captured procurement decision frameworks across integrated service providers and independent operators. Secondary sources included SEC 10-K disclosures from listed oilfield service conglomerates, tungsten carbide import statistics, and unconventional drilling activity reports. Bottom-up segment sizing triangulated against top-down market value estimates.
Across the analysis window, forecasts employed a multi-dimensional analytical framework spanning product type, application trajectory, end-user procurement model, and substrate technology generation. CAGRs derived from regression analysis of historical bit consumption against drilling rig counts, lateral length trends, and regulatory compliance timelines. Industry-specific inputs incorporated EPA methane rule stringency projections, Permian Basin drilling intensity forecasts, and tungsten carbide price elasticity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained unconventional drilling economics, stable Chinese raw material export regimes, or continued EPA emissions enforcement would require recalibration. Forecasts reflect documented assumptions regarding lateral length extension rates and bundled service contract penetration. Recalibration cycles align with material shifts in regulatory stringency, raw material supply disruptions, or substrate technology breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Indexable Tool Inserts Market
Tools
Entrenching Tool Market
Tools
Turning Tools Market
Tools
Lathe Machines Market
Tools
Gouging Torch Market
Tools
Cutting Tools Market
Tools
Book Binding Machines Market
Tools
Cutting Equipment, Accessories and Consumables Market
Tools
Power Drill Market
Tools
Flooring Tools Market
Tools
Manual Cutting Equipment Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Tile Cutter Market
Tools
Nut Runner Market
Tools
Global Diamond Tools Market
Tools
Wood Router Market