

Overload Protection Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Overload Protection Tools Market Insights
CE marking under the EU's Machinery Directive is decoupling low-cost Asian imports from premium European channels by mandating third-party conformity assessment for safety-related control circuits. ABB leverages captive semiconductor fabrication to secure microcontroller supply for its digital relay lines. Schneider Electric anchors its position through deep channel control across European electrical distribution networks.
Overload protection tools are electromechanical or solid-state devices engineered to interrupt current flow when load thresholds exceed calibrated ratings, typically specified in ampere ranges from fractions to thousands of amps. Their primary purpose is preventing thermal damage to motors, transformers, and conductors in industrial power systems. Solid state relays are capturing margin pools in data center applications where microsecond response times justify premium pricing over electromechanical alternatives. Thermal relays retain volume dominance in manufacturing plants due to proven reliability under heavy cyclic loading.
FERC interconnection standards in the United States, REACH substance restrictions in Europe, and BIS certification requirements in India collectively shape product material selection, testing protocols, and market access timelines. The EU F-Gas Regulation indirectly amplifies relay demand by accelerating HVAC system replacements that incorporate integrated overload protection. Stakeholders must decide whether to prioritize microcontroller-based architectures for predictive maintenance integration or preserve analog portfolios for cost-sensitive retrofit markets.
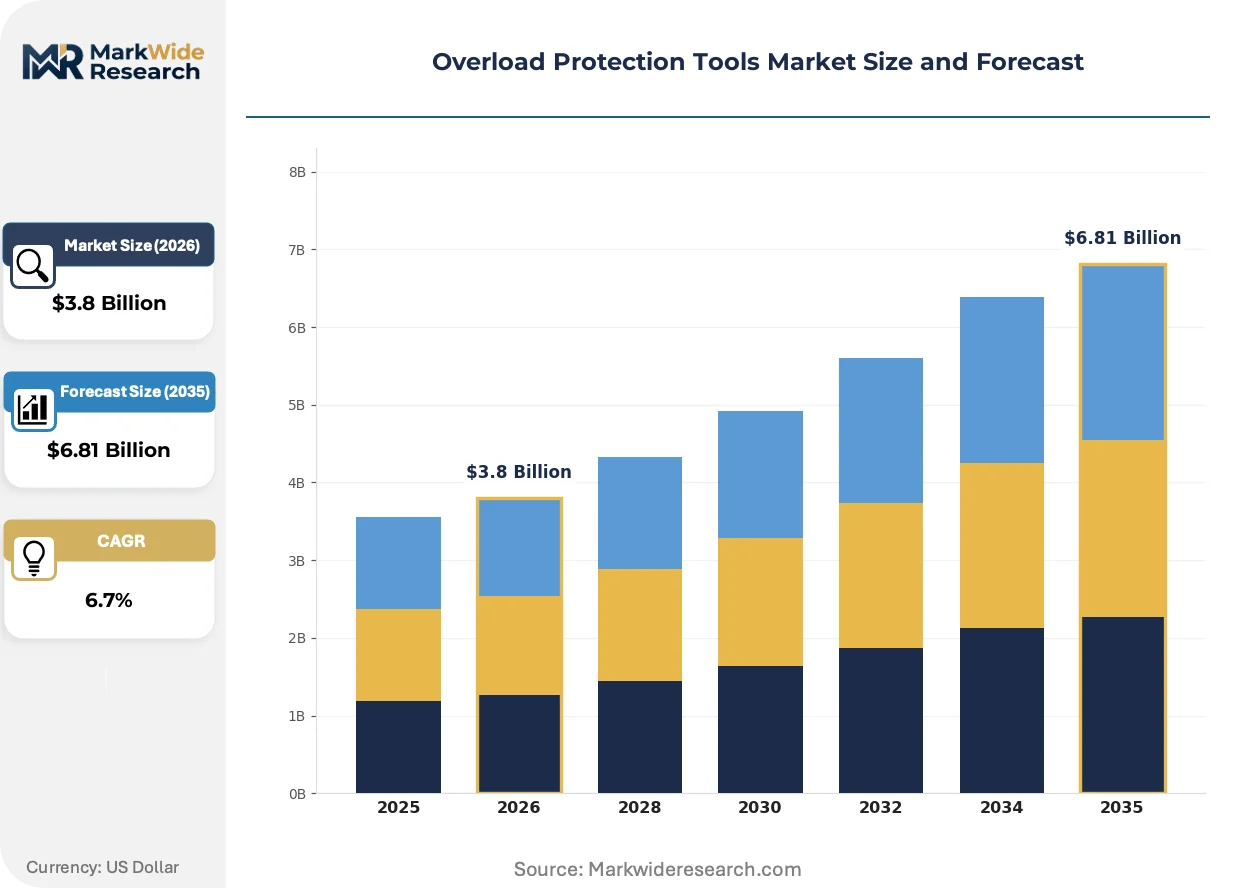
Market Dynamics
Factory electrification across German manufacturing clusters is compressing relay replacement cycles from seven years to four, while EU Green Deal efficiency mandates force simultaneous upgrades of both motors and their protection systems.
Growth Catalysts
- EU F-Gas Regulation:Accelerated HVAC system replacements in France and Italy are expanding the installed base of integrated overload protection modules in commercial refrigeration and heat pump applications.
- Data center construction:Hyperscale facilities in Frankfurt and Amsterdam are specifying solid-state relays for microsecond fault isolation to protect server rack power distribution.
- CE marking enforcement:Third-party conformity assessment requirements under the Machinery Directive are filtering uncertified Asian imports from premium European electrical distribution channels.
Market Restraints
- Semiconductor supply concentration:Microcontroller shortages from Taiwanese foundries are extending lead times for digital relay production lines beyond 26 weeks.
- Copper price volatility:Bimetallic strip thermal relays face margin compression from London Metal Exchange copper fluctuations affecting coil and contact materials.
- Electromechanical reliability threshold:Solid-state alternatives cannot match thermal relay endurance under heavy cyclic loading in foundry and stamping press environments.
Strategic Opportunities
- Predictive maintenance integration:Microcontroller-based architectures with Modbus and Profinet connectivity are capturing retrofit demand from German automotive tier-one suppliers seeking condition monitoring capabilities.
- CEE countries industrialization:Poland and Czech Republic manufacturing expansion is creating first-time installation demand for motor protection relays in greenfield automotive component plants.
- Energy performance contracting:French and Dutch ESCO models are bundling relay upgrades with motor efficiency retrofits, shifting procurement from capital expenditure to operating expenditure frameworks.
Industry Challenges
- Embedded software certification:Functional safety validation to IEC 61508 for safety-related control circuits is extending product development timelines by 8-14 months.
- Legacy system integration:Analog relay replacement in 1980s-era German steel mills requires custom mounting adapter engineering to fit modern digital units into existing MCC bucket configurations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overload Protection Tools Market Trends and Innovations
Digitalization of motor protection is collapsing the distinction between standalone relays and edge computing nodes, embedding diagnostic algorithms directly into switching devices.
Silicon carbide power semiconductors are integrating into next-generation solid-state overload relays, enabling higher switching frequencies and reduced thermal losses in compact form factors. Data center operators in Frankfurt and Amsterdam are piloting these units for 480V three-phase distribution protection. The technology is integrating thermal modeling algorithms that predict winding temperature without physical sensors, compressing hardware requirements in space-constrained installations.
REACH substance restrictions on cadmium and lead are forcing reformulation of bimetallic strip alloys and contact plating materials in thermal relay manufacturing. German component suppliers are qualifying silver-tin oxide alternatives to traditional silver-cadmium oxide for arc quenching. Medium-voltage motor protection relay categories face the most severe compliance timeline pressure, with full material substitution required by 2026 for continued EU market access.
Buying committees at German automotive OEMs are consolidating vendor relationships from twelve relay suppliers to three preferred partners with full lifecycle service capabilities. Direct procurement from ABB and Schneider Electric is displacing traditional electrical distributor intermediaries for high-volume manufacturing plant contracts. This concentration is most visible in Baden-Württemberg and Bavaria, where BMW, Mercedes-Benz, and Porsche powertrain facilities are standardizing on single-source digital relay platforms with integrated predictive analytics.
Overload Protection Tools Market Segmentation
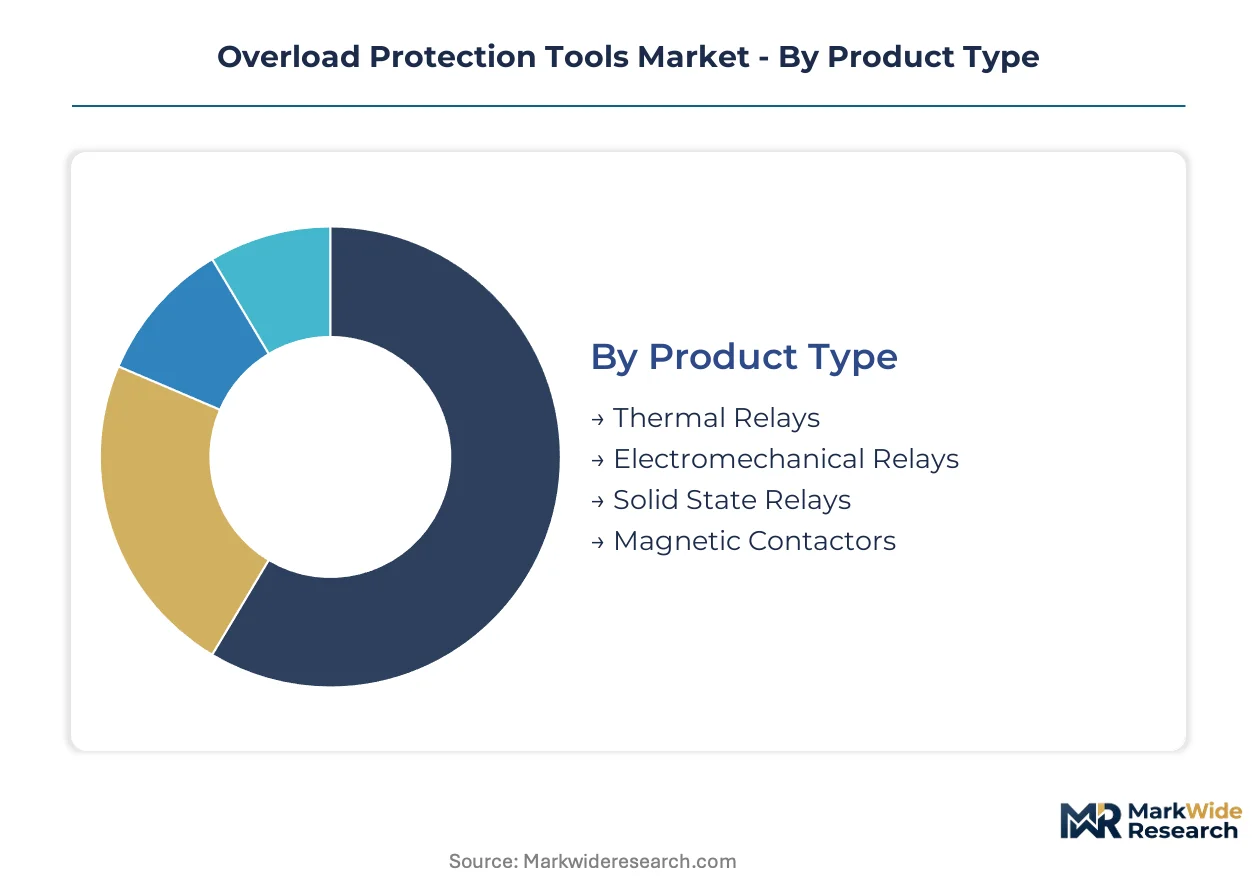
Overload protection tools fragment across four critical dimensions that determine procurement priorities, certification pathways, and margin structures. Product type and technology choices dictate compliance burdens under machinery safety directives, while application and end-user segments shape channel access and pricing power.
Product Type:
CE marking under the EU Machinery Directive imposes third-party conformity assessment on all safety-related control circuits, with thermal and electromechanical variants facing additional material restrictions under REACH.
- Thermal Relays:Bimetallic strip devices calibrated to trip at specific temperature thresholds. Manufacturing plants in Germany's Baden-Württemberg automotive cluster specify these for heavy cyclic loading in stamping press lines where endurance trumps response speed.
- Electromechanical Relays:Coil-actuated switching mechanisms with mechanical contact separation. Power generation utilities across France and Italy deploy these for medium-voltage motor protection where arc quenching reliability justifies maintenance-intensive designs.
- Solid State Relays:Semiconductor-based switching with zero-crossing detection and microsecond response times. Data center operators in Frankfurt and Amsterdam specify these for server rack protection where thermal losses and switching speed determine total cost of ownership.
- Magnetic Contactors:Electromagnetically operated switching devices designed for high-current motor starting applications. Construction firms across Poland and Czech Republic install these in greenfield manufacturing facilities where first-time motor protection demand is climbing fastest.
Leading the category by volume: Thermal Relays. Growing fastest: Solid State Relays.
Technology:
Development timelines stretch longest for microcontroller architectures requiring IEC 61508 functional safety validation, while analog portfolios preserve margin in cost-sensitive retrofit channels.
- Microcontroller Based:Embedded processing platforms enabling Modbus and Profinet connectivity for predictive maintenance integration. German automotive tier-one suppliers specify these for condition monitoring capabilities that compress downtime in just-in-time production environments.
- Microprocessor Based:Higher-compute architectures supporting complex thermal modeling algorithms without physical sensors. HVAC OEMs in France integrate these into heat pump systems to meet EU F-Gas Regulation efficiency mandates.
- Digital:Fixed-logic implementations offering deterministic trip characteristics without software certification burdens. Dutch ESCO models bundle these with motor efficiency retrofits under energy performance contracting frameworks.
- Analog:Discrete component designs with no firmware dependencies. 1980s-era German steel mills require custom mounting adapters to fit these into existing MCC bucket configurations during phased upgrades.
Volume concentration: Analog. Steepest expansion trajectory: Microcontroller Based.
Application:
Margin pools concentrate where response time requirements or integration complexity justify premium pricing over commodity alternatives.
- Electrical Panels:Distribution enclosures housing multiple protection devices. Construction firms across Czech Republic specify these in automotive component plant expansions where centralized protection reduces installation complexity.
- Motor Protection:Dedicated relay systems for rotating equipment thermal management. Manufacturing plants in Germany compress replacement cycles from seven years to four as factory electrification intensifies.
- HVAC Systems:Integrated protection modules for refrigeration compressors and heat pumps. France and Italy accelerate system replacements under EU F-Gas Regulation, expanding the installed base of combined motor-protector units.
- Conveyor Systems:Distributed protection across material handling networks. Polish logistics hubs specify these for automated warehouse expansions where sequential motor starting demands coordinated overload coordination.
Revenue weight: Motor Protection. Climbing fastest: HVAC Systems.
End User:
Procurement authority is consolidating from twelve suppliers to three preferred partners with full lifecycle service capabilities at German automotive OEMs.
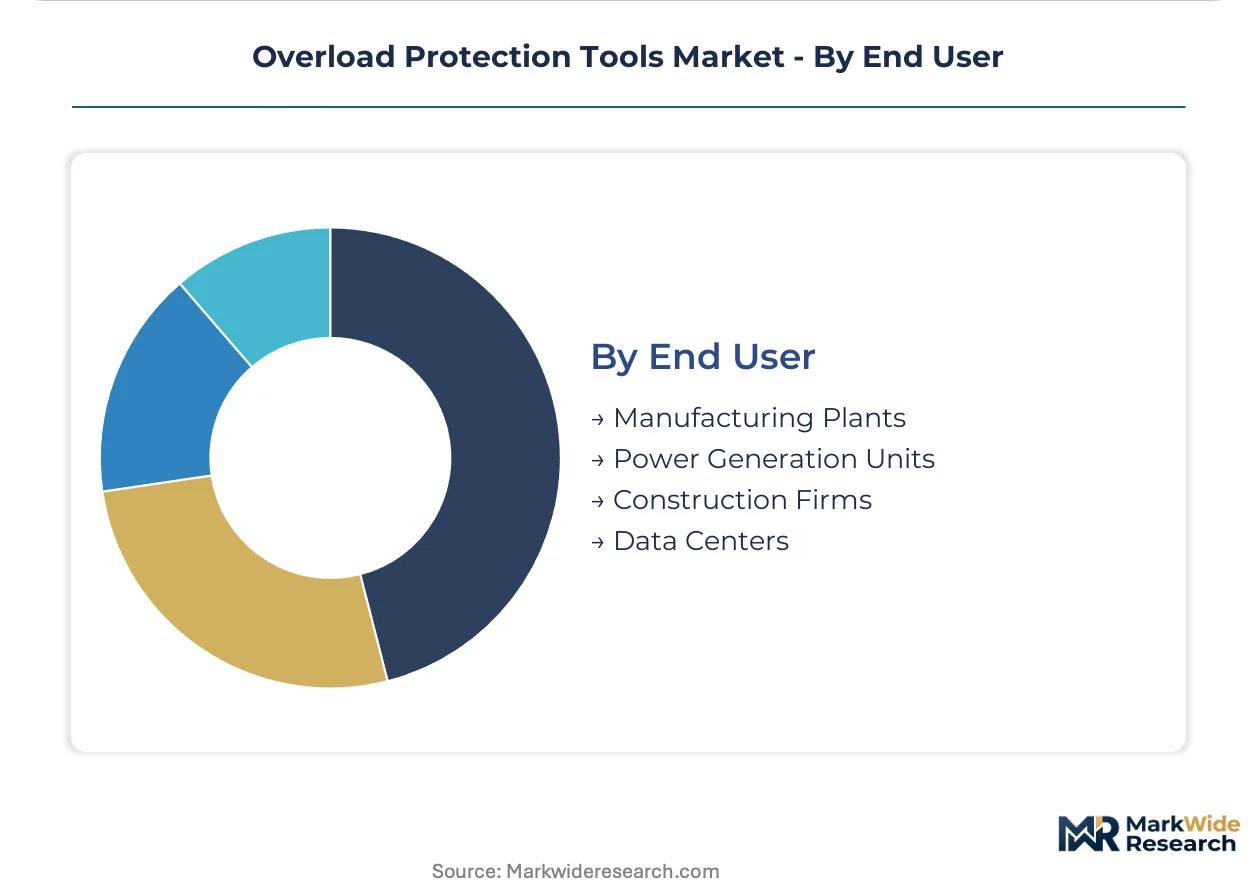
- Manufacturing Plants:Discrete and process industry facilities with high motor density. BMW, Mercedes-Benz, and Porsche powertrain facilities in Bavaria standardize on single-source digital relay platforms with integrated predictive analytics.
- Power Generation Units:Utility-scale generation and grid infrastructure. Italian utilities specify medium-voltage motor protection relays facing severe REACH compliance timeline pressure for cadmium-free contact materials.
- Construction Firms:Project-based contractors installing temporary and permanent electrical systems. Greenfield automotive component plants across CEE countries create first-time installation demand without legacy system constraints.
- Data Centers:Hyperscale and colocation facilities with 24/7 uptime requirements. Frankfurt and Amsterdam operators pilot silicon carbide solid-state relays for 480V three-phase distribution protection.
Volume leadership: Manufacturing Plants. Gaining share fastest: Data Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory electrification concentrates procurement authority in Germany's automotive manufacturing belt, while data center construction in the Netherlands and France drives solid-state relay specifications. Regulatory divergence across jurisdictions fragments certification pathways and shapes local competitive dynamics.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria compress motor protection relay replacement cycles from seven to four years as powertrain electrification intensifies. EU Green Deal efficiency mandates under the Machinery Directive force simultaneous motor and protection system upgrades. BMW, Mercedes-Benz, and Porsche facilities in Stuttgart and Munich standardize on single-source digital platforms with predictive analytics integration.
France
Energy Service Companies (ESCOs) bundle relay upgrades with motor efficiency retrofits under performance contracting frameworks that shift procurement from capital to operating expenditure. EU F-Gas Regulation accelerates HVAC system replacements, expanding integrated overload protection modules in commercial refrigeration. Industrial clusters around Lyon and Grenoble specify microcontroller-based relays for heat pump manufacturing.
United States
FERC interconnection standards shape material selection and testing protocols for medium-voltage motor protection in utility-scale installations. Power generation utilities across Texas and the Midwest deploy electromechanical relays where arc quenching reliability justifies maintenance-intensive designs. Semiconductor supply concentration from Taiwanese foundries extends lead times for digital relay production beyond twenty-six weeks.
India
BIS certification requirements create market access timelines that filter uncertified imports from premium electrical distribution channels. Greenfield automotive component plants in Maharashtra and Tamil Nadu generate first-time installation demand without legacy system constraints. Construction firms specify magnetic contactors for high-current motor starting in expanding manufacturing facilities.
Netherlands
Hyperscale data center operators in Amsterdam pilot silicon carbide solid-state relays for 480V three-phase distribution protection where microsecond fault isolation protects server rack power distribution. REACH substance restrictions on cadmium and lead force reformulation of contact plating materials in thermal relay manufacturing. Dutch ESCO models accelerate retrofit demand through bundled energy efficiency contracting.
Overload Protection Tools Market Competitive Landscape
European producers anchor the premium tier through deep channel control across electrical distribution networks; Asian fabricators hold volume positions in cost-sensitive retrofit segments. The vendor base concentrates around three preferred partners with full lifecycle service capabilities at German automotive OEMs. Strategic archetypes include integrated industrial conglomerates with captive semiconductor supply, specialized relay manufacturers with deep application expertise, and electrical distributors building private-label portfolios. Competitive moves center on backward integration into microcontroller sourcing and geographic expansion through energy performance contracting partnerships.
Within the integrated conglomerate tier, ABB leverages captive semiconductor fabrication to secure microcontroller supply for digital relay lines, while Schneider Electric anchors its position through channel control across European electrical distribution networks. Siemens occupies a position bridging industrial automation and power distribution, exemplifying the scale-driven archetype with cross-portfolio bundling capabilities. These three represent the consolidation trajectory as buying committees reduce vendor relationships from twelve suppliers to three preferred partners with predictive maintenance integration and full lifecycle service capabilities.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Eaton |
| Rockwell Automation |
| Mitsubishi Electric |
| Emerson |
| Honeywell |
| Littelfuse |
| Others |
Pricing and Supply Chain Analysis
Captive semiconductor fabrication anchors supply security for digital relay architectures while simultaneously defending premium pricing tiers against margin erosion from commodity thermal alternatives. ABB's in-house microcontroller production insulates its digital lines from Taiwanese foundry volatility, translating supply certainty into pricing power over distributors serving German automotive OEMs.
Pricing Analysis
Volume concentrates in analog thermal relays where copper coil costs and bimetallic strip commodities compress margins, while solid-state variants command premium positioning through microsecond response specifications for data center buyers. Price differentiation separates CE-marked safety-certified units from uncertified Asian imports, with German automotive OEMs showing lowest sensitivity due to bundled lifecycle service contracts. Pricing pressure stems from London Metal Exchange copper volatility affecting thermal relay manufacturing costs, with foundry and stamping press operators in Baden-Württemberg remaining most price-sensitive due to heavy cyclic loading replacement frequency.
Supply Chain Analysis
CE marking and IEC 61508 functional safety certification gate European market access, filtering supply sources to qualified producers with third-party conformity assessment capabilities. Microcontroller supply draws from Taiwan, South Korea, and captive German fabrication, while copper and silver-tin oxide contact materials hinge on commodity markets. Single-source vulnerability concentrates in Taiwanese foundry capacity for digital relay production. Distribution runs through specialized electrical distributors and direct procurement channels to large manufacturing plant accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH substance restrictions and CE marking under the Machinery Directive erect barrier-to-entry moats favoring incumbent European producers with established certification infrastructure.
For Market Incumbents: Acquire microcontroller design capabilities or secure captive foundry arrangements to insulate digital relay lines from semiconductor supply concentration. Deepen channel control across French and Dutch ESCO networks before energy performance contracting models consolidate procurement authority. Defend against Asian commodity entrants by accelerating predictive maintenance software integration that uncertified competitors cannot replicate. For New Entrants and Emerging Players: Electrical distributors with private-label ambitions represent the most accessible channel for building initial volume without direct OEM procurement committee access. Target greenfield automotive component plants in Poland and Czech Republic where first-time installation demand lacks legacy system integration burdens. ESCO partnership structures offer operating-expenditure procurement frameworks that bypass capital budget approval cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated industrial conglomerates seeking predictive maintenance software capabilities and European regulatory compliance infrastructure. Long-term viability favors targets with IEC 61508 certification completion and established relationships with German automotive buying committees. Watch for inflection when semiconductor supply normalization collapses lead time premiums currently supporting pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microcontroller Supply | Captive semiconductor fabrication insulates ABB from Taiwanese foundry lead time volatility. |
| Predictive Maintenance Software Development | Modbus and Profinet connectivity captures German automotive tier-one retrofit demand. |
| REACH-Compliant Material Substitution | Silver-tin oxide contact plating qualifies thermal relays for continued EU market access. |
| ESCO Partnership Formation | Energy performance contracting in France shifts relay procurement to operating expenditure frameworks. |
| Solid-State Relay Platform Launch | Silicon carbide integration targets Frankfurt and Amsterdam data center microsecond fault isolation specifications. |
Research Methodology
Independent corroboration across plant engineers at German automotive facilities, procurement leads at French ESCOs, and distribution channel partners in the Netherlands underwrites the qualitative findings. Primary interviews with maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation from SEC filings, customs and trade data, and FERC interconnection standards documentation. Bottom-up installation demand modeling and top-down industrial automation spending analysis triangulate volume estimates.
Comparable-period anchoring to historical motor protection relay replacement cycles and factory electrification investment waves structured the forecast window across the analysis window. Segmentation dimensions modeled include product type, technology architecture, application environment, and end-user procurement authority. CAGRs derived from regression analysis against industrial production indices and HVAC system replacement schedules under EU F-Gas Regulation. Forecast inputs incorporated semiconductor supply lead time trajectories and copper price volatility assumptions.
Caveats apply where Taiwanese foundry capacity constraints or REACH substance restriction enforcement delays could materially shift the outlook. Forecasts reflect assumptions regarding German automotive OEM consolidation to three preferred partners and continued CE marking enforcement filtering uncertified imports. A model refresh is warranted upon material change in semiconductor supply normalization timelines or EU Machinery Directive amendment proposals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.