
 Caulking Gun Market | 2026-2036
Caulking Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Caulking Gun Market Analysis
EPA energy-efficiency mandates for building envelopes is consolidating material application standards across residential and commercial job sites. Milwaukee Electric Tool Corporation leverages its M18 battery ecosystem to dominate cordless dispensing platforms. Albion Engineering Company sustains its position through specialized high-thrust designs for industrial sealants. DeWalt competes across price tiers with integrated ONE-KEY inventory management features.
A caulking gun is a handheld dispensing device that extrudes viscous sealants, adhesives, or caulking compounds through a cylindrical barrel using mechanical, pneumatic, or electromechanical force, typically achieving thrust ratios from 7:1 to 26:1 depending on material viscosity. The tool serves construction, automotive, and marine professionals requiring controlled, continuous bead application for waterproofing, air sealing, and structural bonding. Battery-operated units now lead product type growth as lithium-ion platforms extend runtime and reduce operator fatigue on large-scale projects. Construction anchors the largest application segment, though marine and automotive applications generate premium pricing due to corrosion-resistant specifications and precision tolerances. Heavy-duty and compact size variants capture disproportionate margin pools by addressing opposite ends of the workload spectrum.
FCC certification governs radio-frequency features in connected tool models, while OSHA lockout/tagout standards shape pneumatic system safety requirements for jobsite deployment. EPA regulations on volatile organic compound emissions in sealant formulations indirectly drive tool specification as thicker, low-VOC materials demand higher thrust mechanics. ISO 9001 quality management and IEC 62841 safety standards for motor-operated hand tools further condition market access for international suppliers. Stakeholders must monitor how evolving building energy codes in key jurisdictions redefine the performance threshold between manual and powered dispensing systems.
Market Dynamics
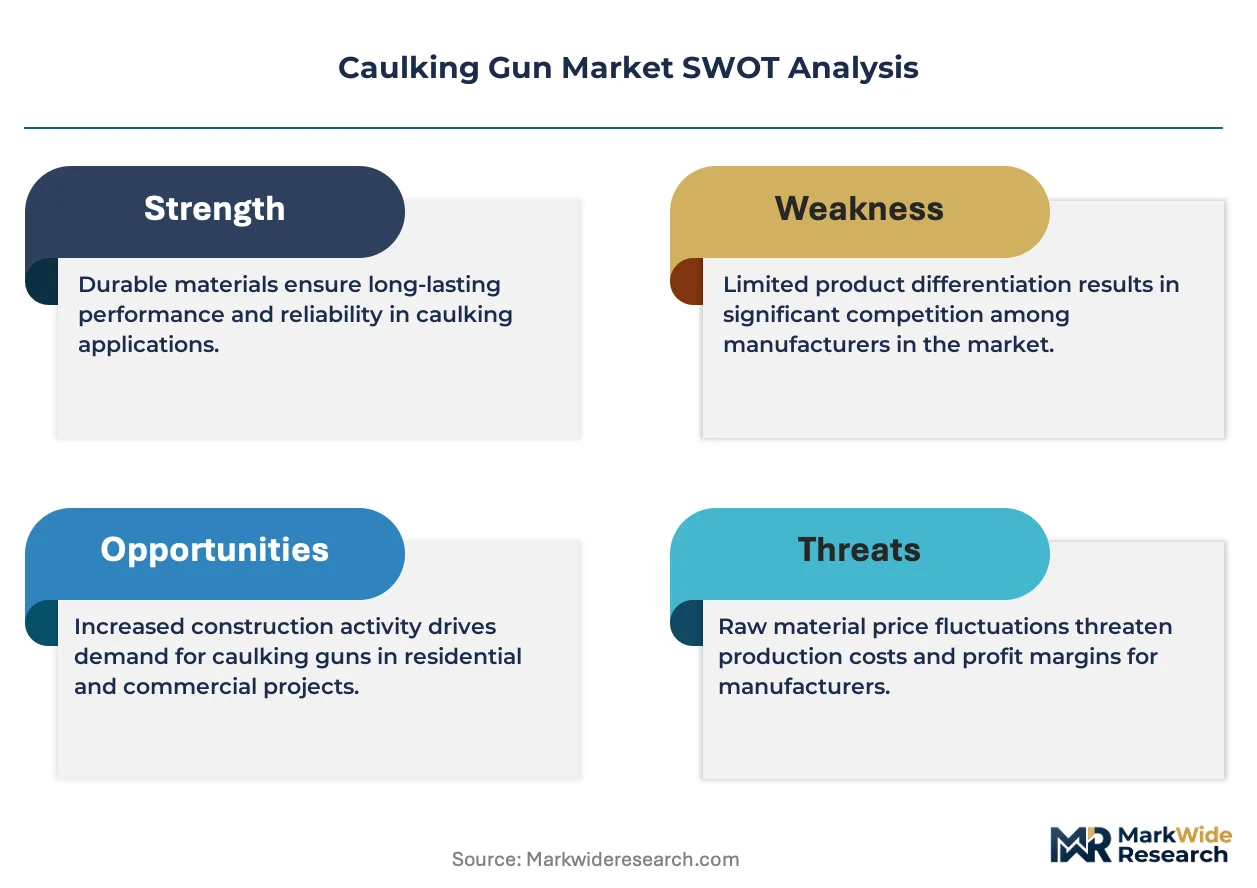
Cordless lithium-ion platforms are compressing the performance threshold between manual and powered dispensing systems, forcing incumbent suppliers to reposition mechanical product lines as entry-tier offerings while battery ecosystems capture contractor loyalty.
Growth Catalysts
- Building envelope energy codes:EPA mandates for air sealing and thermal bridging control are mandating continuous bead application standards across residential and commercial construction in the United States. This specification creep favors powered dispensing accuracy.
- Lithium-ion battery maturation:Cell chemistry improvements have extended runtime per charge cycle, reducing operator fatigue during large-scale sealant application. Contractors now specify cordless units for multi-day envelope work.
- Renovation spending concentration:Elevated retrofit activity in Germany and China is sustaining replacement demand for high-thrust models capable of extruding modern low-VOC formulations with elevated viscosity profiles.
Market Restraints
- Raw material volatility:Engineering-grade polymers and die-cast aluminum components face input cost pressure from energy-intensive smelting and petrochemical feedstock fluctuations.
- Battery cell supply concentration:Cylindrical lithium-ion cell production clusters in East Asian manufacturing hubs create geographic concentration risk for cordless platform suppliers dependent on single-source cathode chemistry.
- Manual tool substitution persistence:Small-scale residential contractors and DIY segments retain preference for mechanical units in low-viscosity silicone and latex applications where thrust requirements remain modest.
Strategic Opportunities
- Connected tool integration:Bluetooth-enabled inventory tracking and usage analytics are converging with contractor fleet management software, creating attach-rate potential for subscription service layers.
- Marine and automotive specification:Corrosion-resistant stainless steel barrel designs for saltwater and chemical exposure environments command premium positioning outside commoditized construction channels.
- CE marking pathway expansion:Harmonized EU machinery safety standards are reducing certification friction for powered hand tool market entry across member states.
Industry Challenges
- Cross-training requirements:Battery platform adoption demands technician proficiency in cell diagnostics, thermal management, and firmware update protocols unfamiliar to mechanical tool service networks.
- Certification timeline compression:IEC 62841 safety standard revisions for motor-operated hand tools are accelerating retesting obligations for existing product portfolios.
- Sealant-tool compatibility complexity:Low-VOC formulation chemistry shifts are creating unpredictable extrusion performance that complicates thrust ratio specification and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caulking Gun Market |
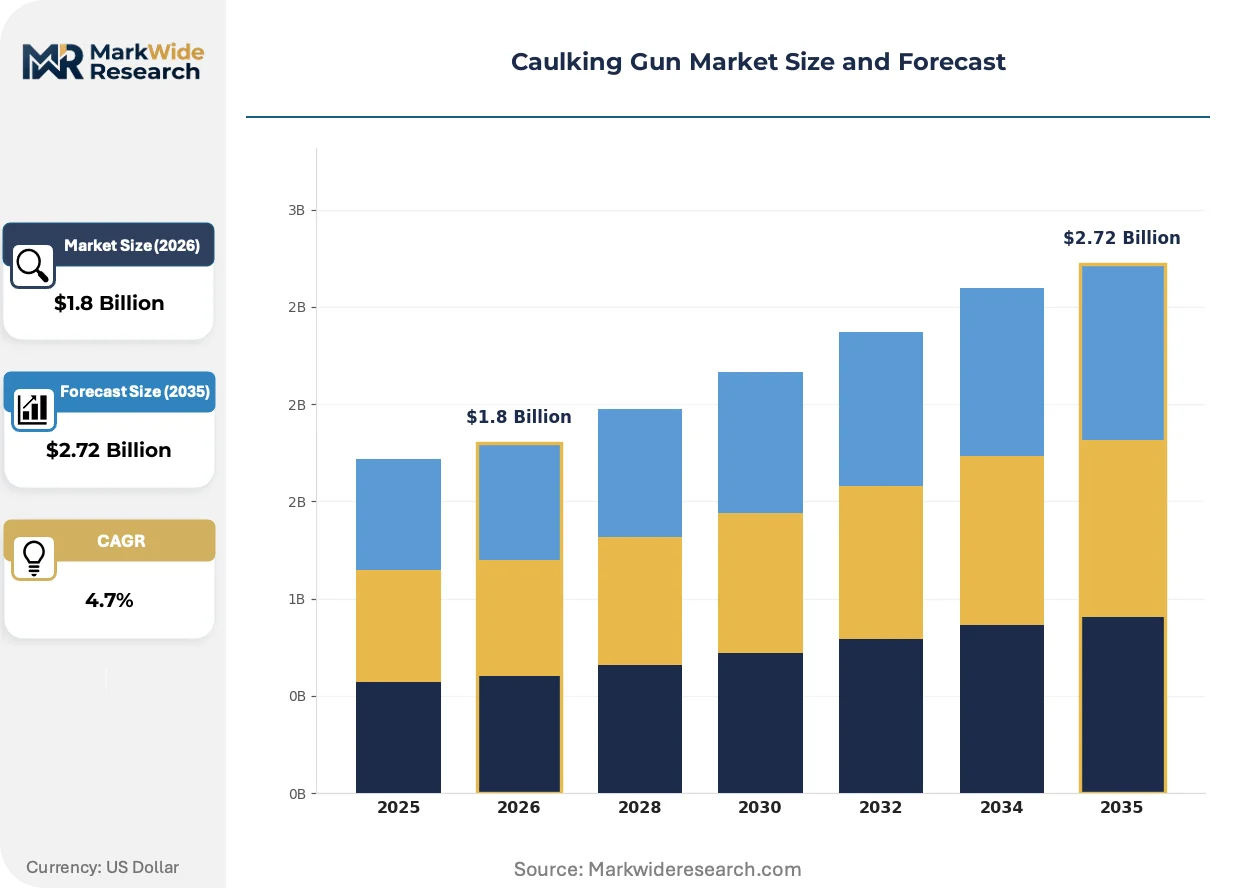
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Pneumatic, Electric, Battery-operated Application: Construction, Automotive, Marine, Household End User: Contractors, DIY Enthusiasts, Maintenance Professionals, Architects Size: Standard, Mini, Heavy-duty, Compact |
| Companies Covered | Milwaukee Electric Tool Corporation, Albion Engineering Company, DeWalt (Stanley Black & Decker Inc.), Newborn Brothers Co. Inc., Dripless Inc., Makita Corporation, Hilti Group, Tajima Tool Corporation, Bosch Power Tools GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caulking Gun Market Emerging Trajectories
Electrification of handheld dispensing tools is reshaping contractor equipment procurement patterns while regulatory pressure on building performance standards tightens application tolerances. Three developments are compressing competitive positioning across product tiers.
Brushless DC motor architecture is converging with sealed gearbox designs to deliver sustained torque output without thermal derating during extended sealant runs. Commercial envelope contractors in the United States are specifying these configurations for multi-story air barrier installation where downtime carries labor cost penalties. The technology is enabling cordless units to displace pneumatic systems previously dominant in high-volume commercial applications.
REACH restrictions on hexavalent chromium surface treatments are forcing suppliers to migrate toward zinc-nickel plating and ceramic coating alternatives for barrel and piston rod corrosion protection. This regulatory shift elevates processing costs for European-market SKUs while creating specification divergence from North American product lines. German industrial sealant applicators are absorbing the transition cost premium to maintain CE compliance for cross-border project mobility.
Outcome-based procurement models are replacing transactional tool purchasing among large mechanical contractors managing dispersed crews. Fleet analytics platforms track sealant volume dispensed, trigger preventive maintenance intervals, and standardize consumable replenishment across job sites. This behavior shift is most visible in United States commercial construction where general contractors consolidate subcontractor equipment specifications to reduce variance in building envelope warranty claims.
Caulking Gun Market Segmentation
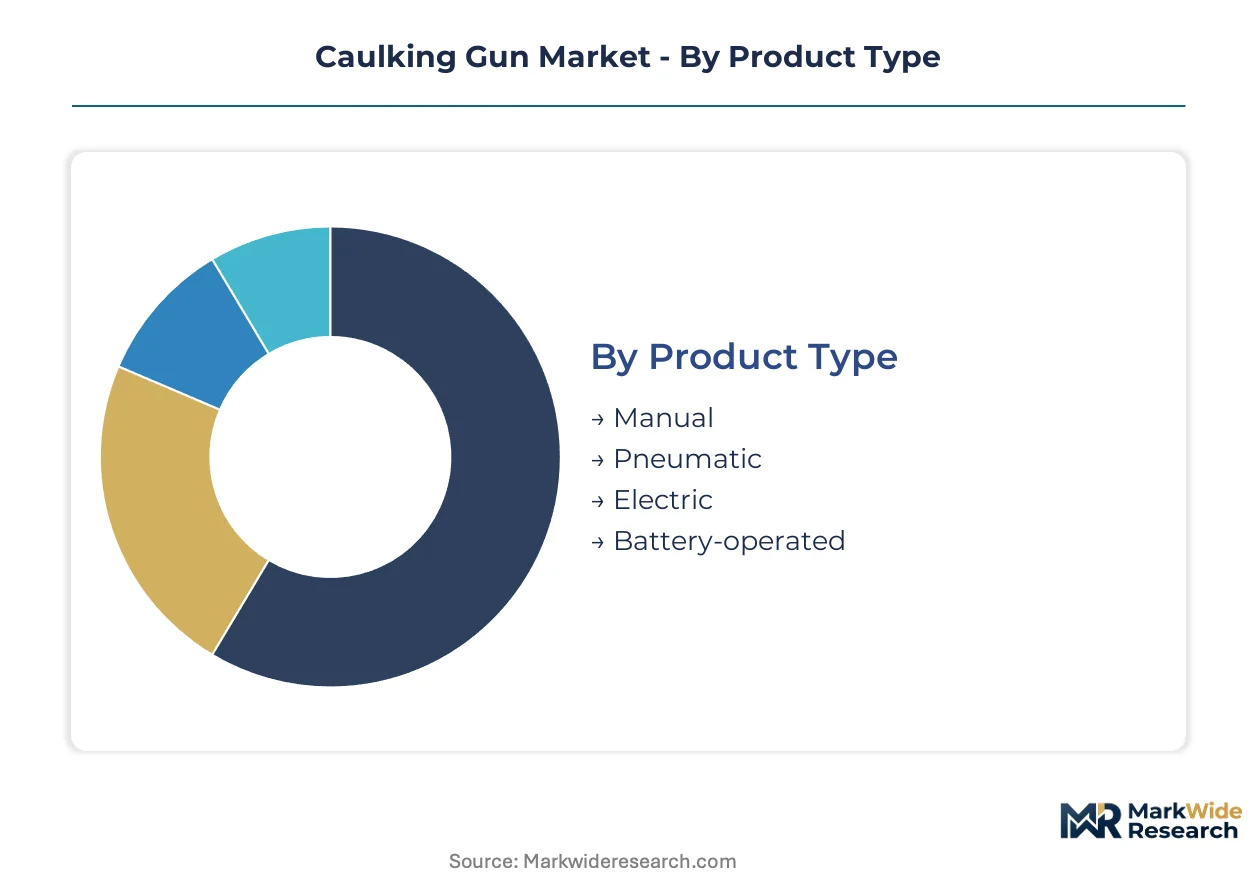
Segmentation in the caulking gun market reveals distinct upgrade cycles across power platforms and user categories. Replacement demand concentrates where building envelope codes tighten and where battery ecosystems mature. Understanding these patterns helps suppliers align product roadmaps with contractor procurement behaviors.
Product Type:
Upgrade cycles vary dramatically by power source, with cordless platforms compressing replacement intervals through battery obsolescence while mechanical tools endure for decades.
- Manual:Ratchet and smooth-rod designs deliver thrust ratios from 7:1 to 12:1 through leveraged mechanical advantage. Demand persists among residential contractors in Germany performing silicone bead touch-ups where pneumatic hose deployment proves cumbersome.
- Battery-operated:Brushless DC motors paired with 18V lithium-ion platforms achieve 26:1 thrust ratios without thermal derating. United States commercial envelope contractors specify these units for multi-story air barrier installation where OSHA lockout/tagout requirements complicate pneumatic system deployment.
- Pneumatic:Compressed-air systems deliver sustained high-volume output through 3/8-inch NPT connections. Automotive assembly plants in China retain these configurations for chassis seam sealing where fixed workstation layouts accommodate air line infrastructure.
- Electric:Corded AC motors provide consistent torque for industrial sealant dispensing without battery management complexity. Maintenance professionals in marine shipyards favor these units for below-deck waterproofing where charging station access remains limited.
Manual tools sit at the top of the volume ranking, with battery-operated models climbing the fastest.
Application:
Application segments diverge by specification tolerance, with corrosion-resistant marine grades and precision automotive variants commanding premium positioning outside commoditized construction channels.
- Construction:Building envelope air sealing and waterproofing dominate volume, driven by EPA energy-efficiency mandates for continuous bead application standards across residential and commercial job sites.
- Marine:Stainless steel barrel specifications resist saltwater corrosion during hull sealing and deck caulking operations. German yacht builders specify IEC 62841-compliant powered units for warranty-eligible work.
- Automotive:Precision tolerances for windshield urethane and body seam applications require calibrated thrust control. Assembly plants in China integrate these tools with torque-monitoring quality systems.
- Household:Light-duty silicone and latex applications favor compact manual units. DIY enthusiasts in the United States purchase these through home improvement retail channels for bathroom and kitchen refresh projects.
Construction anchors absolute volume, while marine applications generate the steepest margin expansion trajectory.
End User:
Procurement authority concentrates differently across user types, with fleet managers consolidating specifications while individual tradespeople retain tool selection autonomy.
- Contractors:Commercial mechanical contractors in the United States deploy connected tool platforms with Bluetooth-enabled inventory tracking across dispersed crews.
- Maintenance Professionals:Facility management teams in Germany specify heavy-duty pneumatic units for industrial roof membrane maintenance where high-viscosity bitumen formulations demand sustained thrust.
- DIY Enthusiasts:Price-sensitive homeowners purchase entry-tier manual units through mass retail channels for intermittent sealant application.
- Architects:Specification writers increasingly mandate powered dispensing systems in construction documents to ensure warranty-compliant building envelope performance.
Contractors drive the largest revenue pool, with architects gaining specification influence fastest.
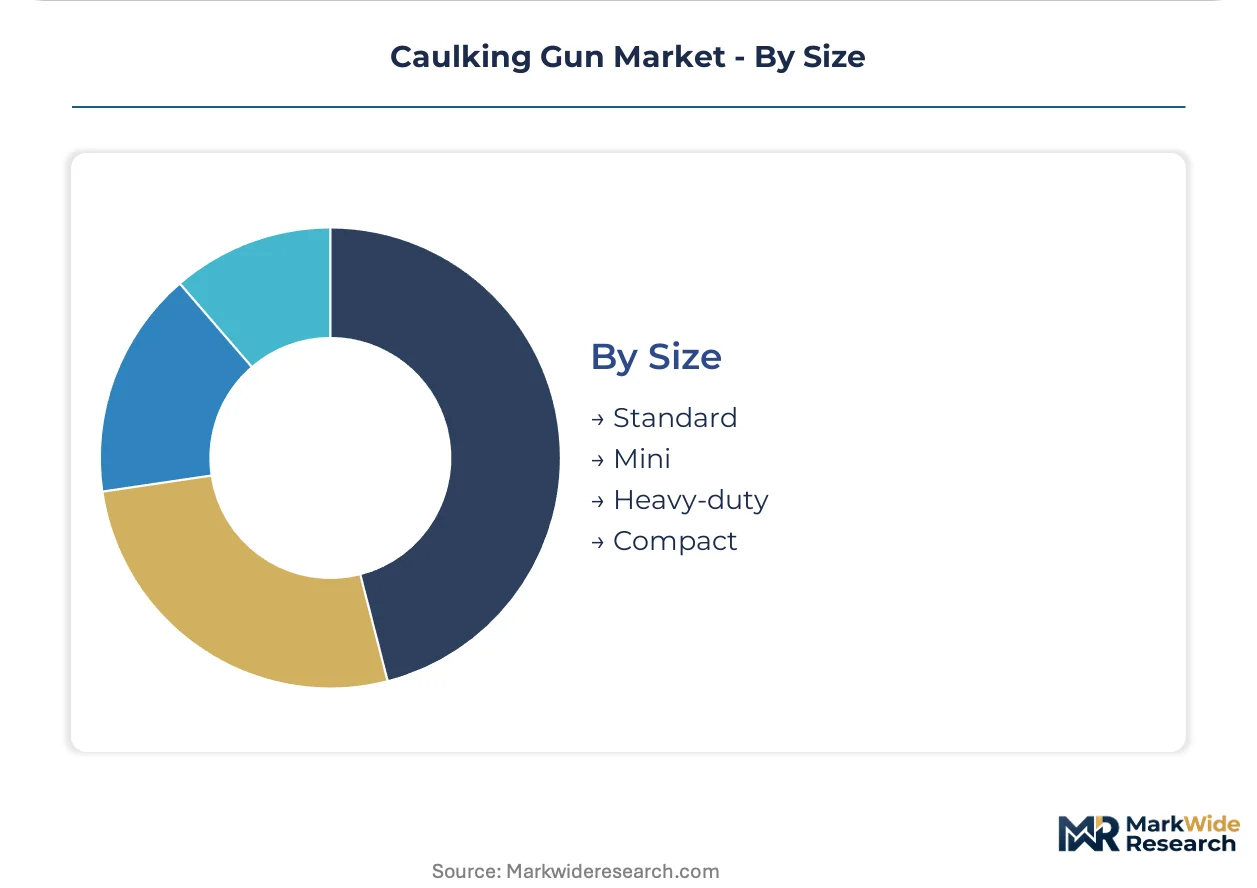
Size:
Physical form factor determines workload suitability, with opposite ends of the size spectrum capturing disproportionate margin pools through specialized engineering.
- Heavy-duty:Reinforced frames and oversized pistons handle high-viscosity polyurethane and epoxy formulations. Industrial sealant applicators in China deploy these for infrastructure expansion joint work.
- Compact:Reduced barrel lengths and pistol-grip ergonomics enable overhead application and confined space access. Marine maintenance crews in Germany favor these for engine compartment sealing.
- Standard:10-ounce cartridge capacity suits general-purpose construction applications across residential and light commercial projects.
- Mini:Sub-6-inch barrel lengths target precision bead work in automotive trim and electronics potting applications.
Standard size maintains volume leadership, with compact variants expanding most quickly in marine and MRO segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled tradespeople and industrial sealant applicators cluster in jurisdictions where building envelope codes tighten and renovation spending remains elevated. Contractor licensing requirements and energy-efficiency mandates reshape tool procurement patterns across distinct national markets.
United States
Commercial envelope contractors drive specification upgrades as EPA energy-efficiency mandates tighten air sealing standards for multi-story construction. OSHA lockout/tagout requirements complicate pneumatic system deployment on federal job sites. Chicago and Pacific Northwest metro areas concentrate demand for brushless DC motor platforms capable of sustained thermal performance.
Germany
Industrial roof membrane maintenance teams specify heavy-duty pneumatic units for high-viscosity bitumen formulations in commercial building stock. REACH restrictions on hexavalent chromium surface treatments force plating chemistry transitions for CE-compliant SKUs. Bavarian yacht builders anchor premium demand for IEC 62841-certified powered dispensing systems in warranty-eligible marine work.
China
Infrastructure expansion joint projects sustain demand for reinforced heavy-duty frames capable of extruding polyurethane and epoxy formulations. GB standards for motor-operated hand tools condition market access for domestic and international suppliers. Yangtze River Delta automotive assembly plants integrate precision dispensing tools with chassis seam sealing quality systems.
Japan
Compact tool variants gain traction among marine maintenance crews performing engine compartment sealing in confined shipboard spaces. METI industrial efficiency guidelines encourage battery platform standardization across construction equipment fleets. Osaka-Kobe shipbuilding corridors concentrate demand for corrosion-resistant stainless steel barrel specifications.
Caulking Gun Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct price-performance tiers. The vendor base stratifies between battery ecosystem providers, pneumatic system specialists, and mechanical tool traditionalists. Three archetypes dominate: platform-integrated power tool conglomerates, sealant-application specialists, and regional fabrication houses serving price-sensitive channels. Consolidation pressure favors M&A activity among battery platform operators, while capacity expansion concentrates in East Asian manufacturing hubs serving cordless motor assembly.
Among platform-integrated power tool conglomerates, Milwaukee Electric Tool Corporation and DeWalt occupy positions defined by battery ecosystem lock-in and connected tool service layers. Albion Engineering Company exemplifies the specialist archetype through focused engineering on high-thrust dispensing mechanics. These three anchors represent divergent strategic postures: ecosystem breadth versus application depth versus industrial-grade precision.
| Leading Market Players |
|---|
| Milwaukee Electric Tool Corporation |
| Albion Engineering Company |
| DeWalt (Stanley Black & Decker Inc.) |
| Newborn Brothers Co. Inc. |
| Dripless Inc. |
| Makita Corporation |
| Hilti Group |
| Tajima Tool Corporation |
| Bosch Power Tools GmbH |
| Others |
Supply Flow & Price Mechanics
EPA volatile organic compound emission limits for sealant formulations gate qualified supply access and premium-tier pricing power, as manufacturers must certify low-VOC compatibility while contractors absorb higher thrust-tool costs for compliant material application. This regulatory filter concentrates margin capture among suppliers with certified industrial-grade portfolios.
Pricing Analysis
Bundled fleet-management subscriptions separate from unbundled per-unit transactional sales across contractor procurement channels. Three-tier pricing structure across premium brushless-motor platforms, standard cordless units, and economy manual tools reflects thrust ratio capability and battery ecosystem lock-in depth. Cost compression in entry-tier mechanical models intensifies as Asian fabrication houses scale die-cast aluminum component output. Small-scale residential contractors exhibit highest price sensitivity, while commercial mechanical contractors prioritize total-cost-of-ownership metrics over acquisition price.
Supply Chain Analysis
Warehouse-distribution layers operate through regional hub-and-spoke patterns anchored in United States Midwest distribution centers and Rhine-Ruhr logistics corridors serving German industrial clusters. Manufacturing concentrates in China, Taiwan, and Vietnam for lithium-ion cell assembly and motor winding operations. Engineering-grade polymers and die-cast aluminum feedstock draw from petrochemical complexes and energy-intensive smelting facilities. Single-source cathode chemistry vulnerability in cylindrical cell production creates geographic concentration risk. Distribution runs through construction equipment distributors and direct OEM fleet sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in this market rests on lithium-ion platform standardization reducing battery replacement costs while premium-tier brushless-motor specifications capture specification upgrades from tightening building envelope codes.
For Market Incumbents: Deploy battery ecosystem lock-in as the primary defensive lever. Integrate ONE-KEY or equivalent Bluetooth-enabled inventory tracking to raise switching costs for contractor fleets. Expand M18 and comparable platform-compatible tool attachments to deepen share-of-wallet. Counter emerging pure-play dispensing specialists through certified industrial-grade product line extensions. For New Entrants and Emerging Players: Launch via marine and automotive specification channels where corrosion-resistant stainless steel barrel designs command premium positioning outside commoditized construction markets. Target Bavarian yacht builders and Yangtze River Delta automotive assembly plants with IEC 62841-compliant powered units. Pursue direct technical sales engagement with quality-system-integrated procurement teams rather than distributor-dependent routes. For Investors and Strategic Acquirers: Roll-up economics work for battery platform operators because contractor fleet standardization creates predictable replacement demand and attach-rate expansion for subscription service layers. Focus on targets with established cordless motor assembly capacity and existing CE marking pathways. Watch EPA building envelope code revision announcements as the signal indicating specification acceleration toward powered dispensing systems.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Ecosystem Expansion | Milwaukee's M18 compatibility locks contractor fleets into recurring battery and attachment purchases. |
| Connected Tool Service Layer Development | Bluetooth-enabled usage analytics integrate with fleet management software for preventive maintenance revenue. |
| CE Marking Pathway Investment | Harmonized EU machinery safety standards reduce certification friction for powered hand tool market entry. |
| Marine-Grade Corrosion-Resistant Specification | Stainless steel barrel designs for saltwater exposure command premium pricing outside construction channels. |
| Brushless DC Motor Architecture Adoption | Sealed gearbox configurations eliminate thermal derating during extended sealant runs on multi-story projects. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with commercial envelope contractors, fleet procurement managers, industrial sealant applicators, and power tool distribution channel heads with secondary validation from EPA regulatory filings, OSHA lockout/tagout standard updates, IEC 62841 safety documentation, and customs trade data on die-cast aluminum component flows. Bottom-up segment sizing and top-down market triangulation cross-checked volume assumptions.
Segment-weighting approaches distributed value and unit forecasts across product type, application, end user, and size dimensions throughout the projection horizon. CAGRs derived from regression analysis against building permit issuance trends, renovation spending indices, and battery platform adoption curves. Modeled inputs included lithium-ion cell cost decline trajectories and building envelope code stringency indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material volatility shocks or accelerated regulatory revision timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Electric Power Tools Market
Tools
Rotary Hammer Drill Market
Tools
Digital Cutting Machine Market
Tools
Auger Drill Bits Market
Tools
Diamond Hole Saw Market
Tools
Boring Tools Market
Tools
Nail Gun Market
Tools
Engraver Machine Market
Tools
Cordless Blind Rivet Gun Market
Tools
Tool Pliers Market
Tools
Wood-Burning Tool Market
Tools
Vinyl Bending Machine Market
Tools
Screw Fastener Market
Tools
Indexable Inserts Market
Tools
Sand Control Tools Market
Tools
Surface Planer Market