

Cordless Trim Routers Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Trim Routers Market Insights
Specialty woodworking retailers and direct-to-contractor platforms is reshaping how cordless trim routers reach professional buyers. Bosch leverages its battery ecosystem to lock in repeat purchases across multiple tool categories. Makita anchors its position through dense dealer networks in North American metropolitan markets. DeWalt competes aggressively on brushless motor performance metrics that resonate with high-volume cabinet shops.
Cordless trim routers are handheld power tools that spin a collet-mounted bit at speeds typically ranging from 10,000 to 30,000 RPM to shape, edge, or groove wood and composite materials. These tools serve furniture makers and finish carpenters who require maneuverability without tethering to wall outlets. Compact and precision units command margin premiums in the product type dimension as custom builders prioritize control over raw power. Lithium-ion and brushless motor configurations within the power source category attract the fastest upgrade cycles from professionals retiring older NiMH platforms.
FCC certification governs electromagnetic emissions from variable-speed electronic controllers sold in the United States. OSHA workplace safety standards influence guard design and dust collection integration for professional jobsite use. The EU's CE marking and Machinery Directive (MDR) shape export compliance costs for Asian manufacturers targeting European professional channels. Stakeholders must monitor how battery platform standardization across tool ecosystems determines customer switching costs and aftermarket loyalty.
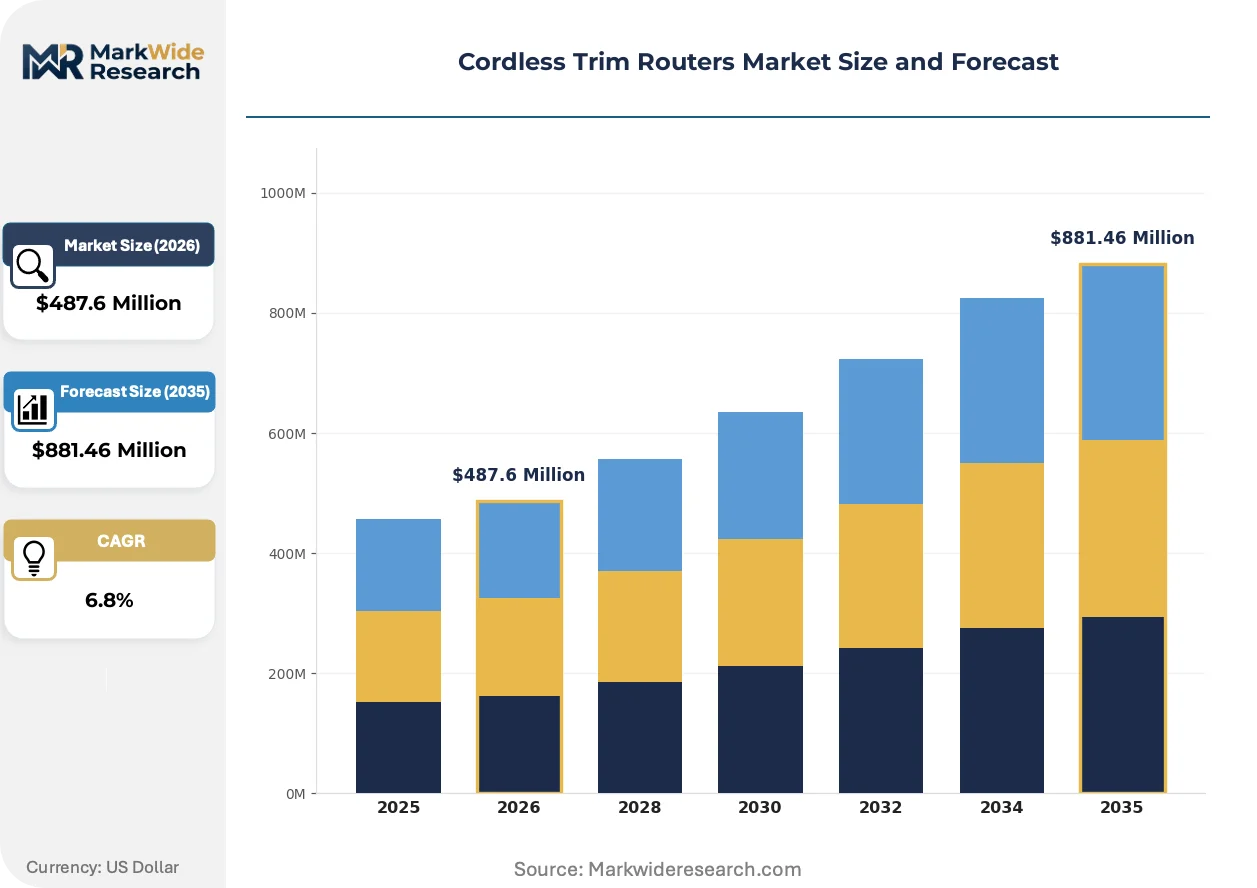
Market Dynamics
Brushless motor platforms are collapsing runtime limitations that once tethered trim routers to corded alternatives, forcing professional buyers to accelerate replacement cycles across workshop inventories.
Growth Catalysts
- EU F-Gas Regulation:REACH directives on battery chemistry are compelling manufacturers to redesign power packs with cleaner lithium formulations, opening premium positioning for compliant suppliers in German and French professional channels.
- Furniture manufacturing clusters:Custom cabinet shops in North Carolina and Osaka are consolidating tool purchases around single battery ecosystems to reduce charger redundancy and simplify fleet management.
- Brushless commutation:Electronic motor control is extending per-charge output by 40-60% versus brushed predecessors, erasing the performance gap with corded units in hardwood routing applications.
Market Restraints
- Lithium carbonate volatility:Cell-grade lithium supply from South American salares and Australian hard-rock mines fluctuates with EV battery demand, compressing margin stability for tool OEMs locked into fixed-price retail contracts.
- Semiconductor lead times:Variable-speed controller ICs from Taiwanese foundries remain constrained, delaying production ramps for new brushless SKUs targeted at holiday buying seasons.
- Corded residual preference:High-volume millwork operations in industrial zones with stable grid access continue specifying AC routers for continuous-duty edgebanding, limiting cordless penetration in factory settings.
Strategic Opportunities
- Direct-to-contractor platforms:Specialized woodworking e-commerce channels in the United States are capturing specification influence previously held by distributor salesforces, enabling margin capture through subscription-based blade and bit replenishment.
- EU Green Deal procurement:Public infrastructure and municipal furniture contracts across Denmark and the Netherlands are mandating cordless equipment to eliminate trailing cable hazards on renovation sites, creating specification pull-through for compliant suppliers.
- Compact laminate trimmers:Convergence of 12V battery platforms with sub-compact chassis designs is opening countertop installation and solid-surface fabrication segments previously served by pneumatic tools.
Industry Challenges
- Brushless motor repair expertise:Field service networks lack technicians trained in Hall sensor diagnostics and stator rewinding, forcing premature replacement of otherwise salvageable drive units and eroding total-cost-of-ownership claims.
- Cross-platform battery incompatibility:Proprietary cell formats across major ecosystems prevent interchangeability, stranding contractor investments when switching brands and complicating fleet standardization decisions for multi-trade general contractors.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Trim Routers Market Trends and Innovations
Electronic speed control integration and connectivity modules are transforming cordless trim routers from standalone cutting tools into networked workshop assets, embedding telemetry for bit wear monitoring and usage-based maintenance scheduling.
Sensorless brushless drive architecture is collapsing the cost and complexity gap between entry-level and professional-grade routers, enabling mid-market manufacturers to spec electronic soft-start and constant-speed-under-load features previously reserved for premium SKUs. Cabinet shops in the United States are adopting these units for production edge profiling where torque consistency determines finish quality. The technology is collapsing tier boundaries that once separated hobbyist from professional product lines, forcing incumbents to defend positioning through battery ecosystem lock-in rather than motor performance alone.
REACH substance restrictions on SVHCs in battery housings and electronic enclosures are compelling Asian contract manufacturers to qualify halogen-free thermoplastics and recycled PC-ABS blends for EU-bound production. Compliance costs are compressing margins on economy-tier SKUs while creating certification barriers for new market entrants lacking established supply chain audit trails. German and Dutch importers are responding by consolidating supplier relationships with vertically integrated molders capable of documenting full material provenance.
Specialty woodworking retailers are ceding specification influence to jobsite procurement apps that aggregate real-time inventory availability across distributor warehouses, enabling project managers to source replacement routers within hours rather than days. Finish carpentry crews in Japan and the United States are adopting these platforms for emergency tool replacement during fixed-duration installation contracts. The shift is most visible in metropolitan markets where same-day courier networks support tool-and-accessory bundling that traditional dealer counters cannot match.
Cordless Trim Routers Market Segmentation
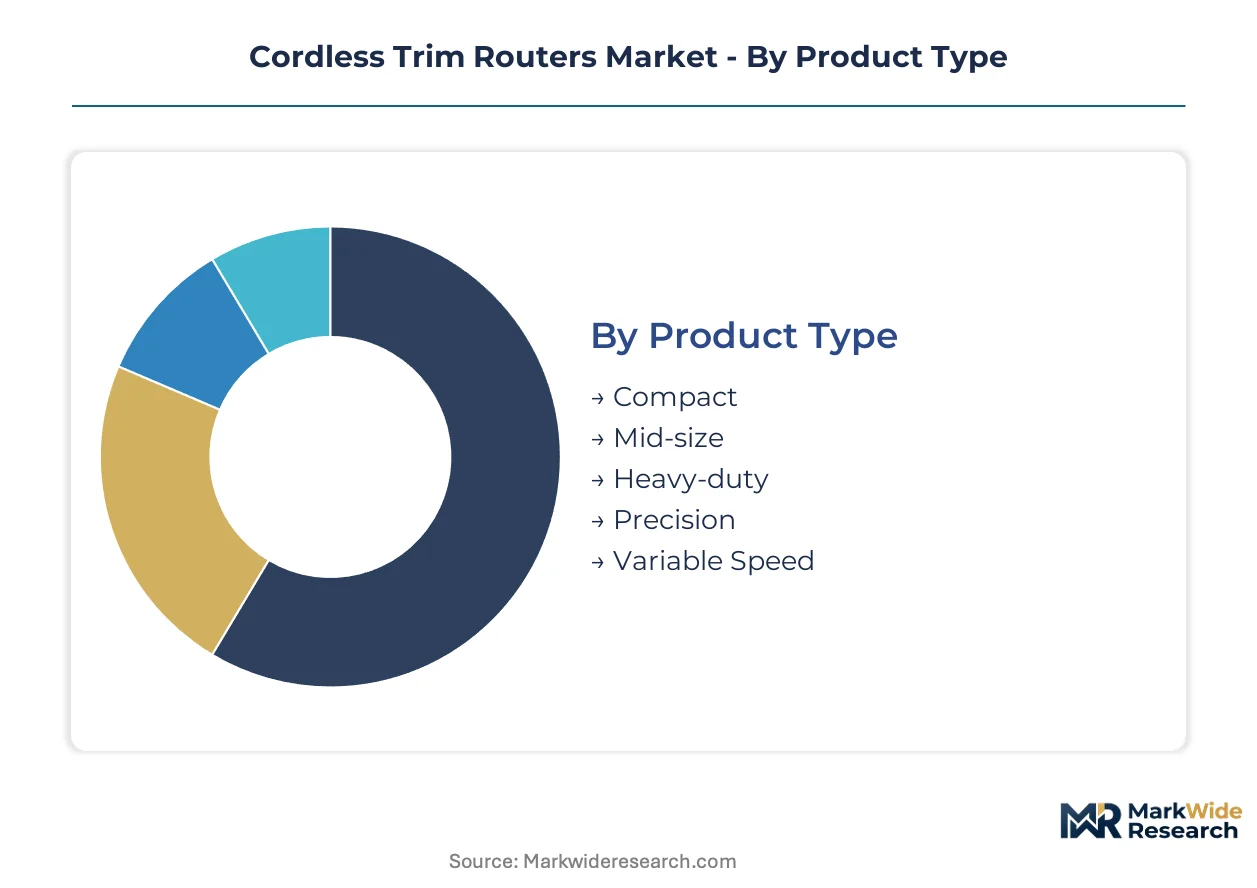
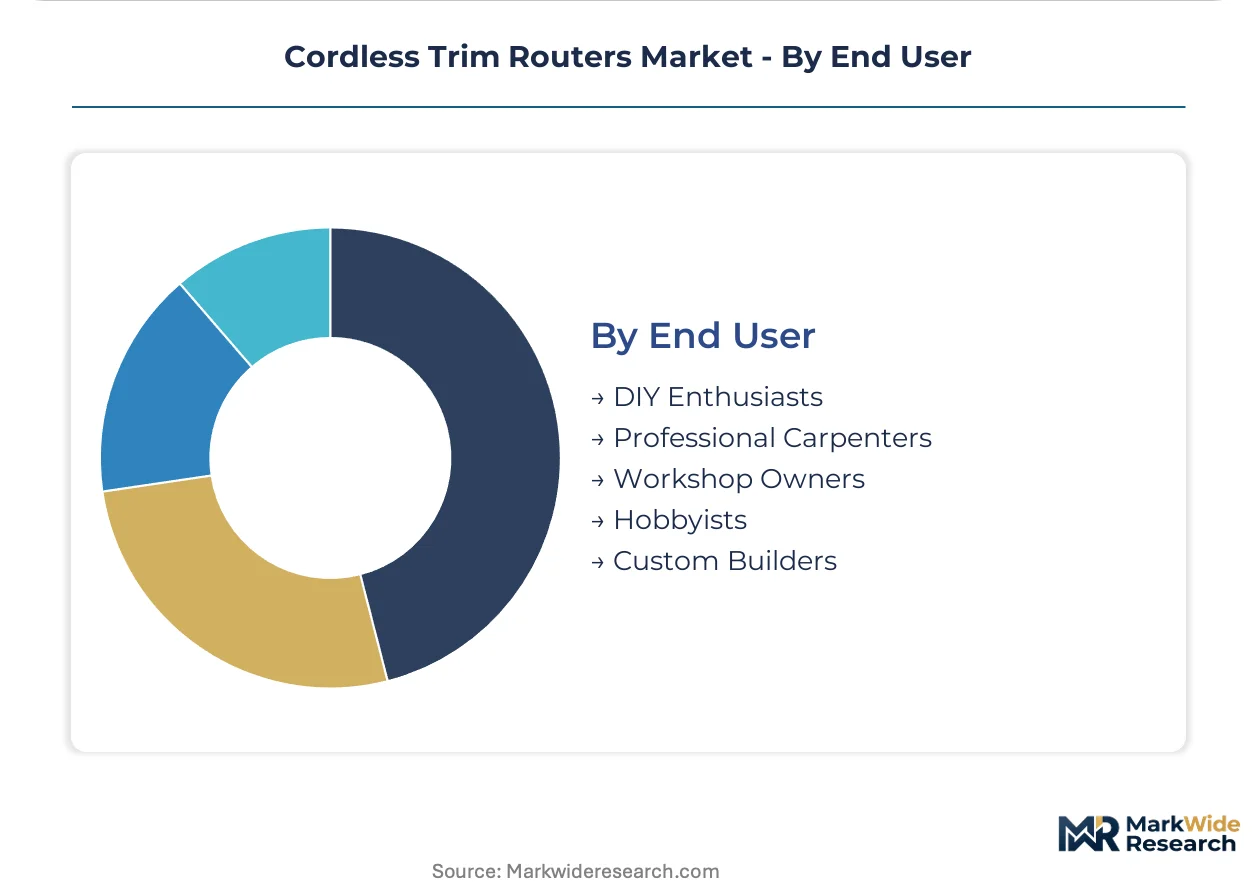
Segmentation in cordless trim routers reveals how battery platform ecosystems and precision requirements fragment purchasing behavior across workshop tiers. Tool OEMs calibrate service networks and accessory bundling differently for each slice.
Product Type:
After-sales intensity escalates with unit complexity, as precision and variable-speed models demand calibration services that compact units rarely require.
- Compact:Ultra-light chassis designs prioritize single-handed edge trimming and laminate work in tight quarters. Demand clusters with countertop installers in Osaka and kitchen renovation contractors across North Carolina who value maneuverability over plunge capacity.
- Precision:Fixed-base and micro-adjustment systems deliver sub-millimeter depth control for inlay and joinery work. German custom furniture makers and high-end cabinet shops in the United States specify these units for heirloom-grade output where tolerance stack-up is unacceptable.
- Mid-size:Balanced power-to-weight ratio suits general carpentry crews needing versatility across trim and light plunge operations.
- Heavy-duty:Reinforced housings and larger collets handle hardwood stock removal and production edge profiling.
- Variable Speed:Electronic controllers enable bit-specific RPM matching for plastics, aluminum, and exotic veneers.
By volume, Compact leads. By growth pace, Precision is climbing the fastest.
Power Source:
Cost tier stratification separates professional-grade lithium-ion platforms from entry-level alternatives still common in developing markets.
- Battery Powered:Cordless architecture eliminates trip hazards and enables mobile work across scaffolding and finished surfaces. Municipal procurement in Denmark and the Netherlands now mandates battery-powered equipment for public renovation contracts, accelerating fleet conversions.
- Brushless Motor:Electronic commutation extends runtime and eliminates brush maintenance intervals that plague high-volume shops. Japanese finish carpentry crews and US cabinet manufacturers are retiring brushed units faster than forecasted as Hall-sensor reliability improves.
- Lithium-ion:Cell chemistry dominates professional channels with energy density enabling compact pack designs.
- NiMH:Nickel-metal hydride persists in price-sensitive hobbyist tiers and replacement battery markets.
- High-capacity Cells:Extended-range packs support full-shift operation without mid-day charging interruptions.
By installed base, Lithium-ion dominates. By upgrade velocity, Brushless Motor is gaining share fastest.
Application:
Application focus determines bit inventory breadth and consumable attach rates that drive aftermarket revenue per unit sold.
- Woodworking:General material shaping across softwood, hardwood, and engineered substrates constitutes the core use case. Professional carpenters in Germany and the United States purchase these units as primary edge-forming tools, with bit wear driving recurring accessory sales.
- Cabinetry:Production edgebanding and door profile machining demand sustained accuracy under dust-heavy conditions. North Carolina and Osaka manufacturing clusters specify dust-sealed motors and quick-change collet systems to minimize downtime in high-volume environments.
- Furniture Making:Bespoke and production furniture requires plunge capability and template routing precision.
- Model Construction:Scale modelers and architectural fabricators need ultra-low vibration and fine bit compatibility.
- Crafting:Hobbyist makers prioritize affordability and basic edge treatment over industrial durability.
By unit shipments, Woodworking leads. By margin contribution, Cabinetry shows the steepest expansion trajectory.
End User:
Customer type governs purchase frequency, warranty claim rates, and brand loyalty duration across the ownership lifecycle.
- Professional Carpenters:Daily-use contractors demand tool durability and same-day service turnaround to protect billable hours. These buyers in Japan and the United States consolidate purchases around single battery ecosystems to simplify fleet management and reduce charger redundancy on multi-tool jobsites.
- Custom Builders:High-end residential specialists require precision routing for architectural millwork and built-in installations. German and Dutch custom builders specify premium compact and precision models, with specification influence shifting toward direct-to-contractor platforms that aggregate inventory availability.
- DIY Enthusiasts:Home improvement hobbyists purchase intermittently and prioritize price over service network density.
- Workshop Owners:Commercial rental and shared maker spaces need vandal-resistant designs and usage-tracking features.
- Hobbyists:Occasional users tolerate longer charge times and shorter runtime in exchange for lower acquisition cost.
By absolute volume, DIY Enthusiasts lead. By lifetime value per customer, Custom Builders are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety standards in the United States establish the regulatory baseline that professional-grade cordless trim routers must meet for electromagnetic emissions and dust collection integration. German and Japanese markets anchor premium demand through dense dealer networks and precision-focused custom builder segments.
United States
North Carolina furniture manufacturing clusters drive specification pull-through for brushless motor platforms with extended runtime. FCC certification governs variable-speed electronic controllers for electromagnetic compliance. Cabinet shops in High Point and Thomasville consolidate purchases around single battery ecosystems to reduce charger redundancy.
Germany
Custom furniture makers in Baden-Württemberg and Bavaria demand sub-millimeter depth control for heirloom-grade joinery output. The EU's F-Gas Regulation and REACH directives compel manufacturers to redesign power packs with cleaner lithium formulations. Stuttgart and Munich metropolitan areas show fastest adoption of precision fixed-base models through specialty woodworking retailers.
Japan
Finish carpentry crews in Osaka and Tokyo prioritize maneuverability for architectural millwork in tight residential quarters. METI energy efficiency guidelines shape motor efficiency benchmarks for professional-grade tools. The Kansai manufacturing cluster exhibits rapid upgrade cycles from brushed to brushless platforms as Hall-sensor reliability improves.
Netherlands
Municipal procurement contracts now mandate cordless equipment to eliminate trailing cable hazards on public renovation sites. EU Green Deal procurement frameworks accelerate fleet conversions among infrastructure contractors. Amsterdam and Rotterdam metropolitan markets demonstrate specification pull-through for compliant suppliers in commercial furniture installation segments.
Denmark
Public infrastructure contracts drive demand for battery-powered equipment across municipal furniture and renovation projects. CE marking and Machinery Directive compliance costs filter economy-tier suppliers from professional channels. Copenhagen-area custom builders specify premium compact models through direct-to-contractor platforms with same-day courier support.
Cordless Trim Routers Market Competitive Landscape
Full-line power tool conglomerates and precision-focused specialty manufacturers split the market into distinct competitive spheres with minimal overlap in customer access methods. The vendor base concentrates around three strategic archetypes: ecosystem-locked battery platform owners, precision-specialist German engineering houses, and value-tier Asian fabricators. Dominant competitive moves include proprietary battery ecosystem expansion to increase switching costs and direct-to-contractor platform development to bypass traditional distributor networks.
Within the ecosystem-locked tier, Bosch GmbH and Makita Corporation represent archetypal full-line manufacturers anchoring professional demand through battery platform standardization. Stanley Black & Decker, Inc. occupies a position spanning multiple price tiers through portfolio breadth. These players exemplify how aftermarket loyalty and charger redundancy reduction drive contractor consolidation behavior across workshop inventories.
| Leading Market Players |
|---|
| Bosch |
| Stanley Black & Decker |
| Makita |
| Milwaukee Tool |
| DeWalt |
| Ryobi |
| Festool |
| Metabo HPT |
| Skil |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese lithium-ion cell manufacturing is compressing pack costs for tool OEMs while simultaneously eroding supplier pricing power across premium battery platforms. German and Japanese manufacturers respond by anchoring premium positioning through brushless motor performance differentiation rather than competing on cell economics alone.
Pricing Analysis
German precision models command 35-50% premiums over equivalent US-market SKUs due to CE marking compliance costs and denser dealer service networks. Three-tier pricing structure across premium, standard, and economy levels separates brushless professional units from brushed mid-market alternatives and NiMH hobbyist tiers. Pricing pressure stems from lithium carbonate volatility transmitted through fixed-price retail contracts. DIY enthusiasts exhibit highest price sensitivity while custom builders prioritize total-cost-of-ownership over acquisition cost.
Supply Chain Analysis
Extended payment terms from Taiwanese semiconductor foundries are straining working capital for variable-speed controller procurement. Cell-grade lithium draws from Chilean salares and Australian hard-rock mines while brushless motors source from Chinese and Japanese stator winding facilities. Single-source vulnerability concentrates in Hall-sensor IC supply from Taiwanese fabs. Distribution runs through specialty woodworking retailers and direct-to-contractor platforms with diverging margin capture profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless motor repair expertise scarcity is constraining aftermarket service capacity and eroding total-cost-of-ownership claims for premium-tier suppliers. The gap between field technician training pipelines and electronic drive complexity widens as sensorless architectures proliferate.
For Market Incumbents:Pre-empt Hall-sensor diagnostic capability gaps by certifying regional service networks before sensorless architectures collapse tier boundaries. Lock in contractor loyalty through battery ecosystem expansion rather than motor performance alone. Defend against mid-market sensorless entrants by bundling calibration services with precision-model sales.
For New Entrants and Emerging Players:Scandinavian municipal procurement channels show underpenetration by established battery ecosystems despite EU Green Deal mandate pull-through. Target Denmark and Netherlands infrastructure contractors with REACH-compliant compact models priced below Festool and Bosch professional tiers. Bypass dealer networks entirely through jobsite procurement app partnerships.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among direct-to-contractor platforms with subscription-based blade and bit replenishment. Battery platform owners with dense charger install bases offer superior long-term viability over standalone motor specialists. Monitor brushless motor controller IC lead times as inflection indicator for production ramp capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Ecosystem Expansion | Increases contractor switching costs and anchors aftermarket loyalty across multiple tool categories. |
| Direct-to-Contractor Platform Development | Bypasses traditional distributor networks and captures margin through subscription consumable replenishment. |
| REACH-Compliant Supply Chain Qualification | Creates certification barriers for new entrants lacking established material provenance audit trails. |
| Brushless Motor Repair Network Certification | Addresses field service expertise gaps that erode total-cost-of-ownership claims for premium units. |
| Sensorless Drive Architecture Adoption | Collapses cost gap between entry-level and professional tiers, forcing incumbents to defend through ecosystem lock-in. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tool OEM product managers, aftermarket service directors, and specialty woodworking retailer buyers; and secondary validation against customs trade records, SEC 10-K filings from listed power tool conglomerates, and EU regulatory compliance databases. Bottom-up unit shipment estimates triangulated against top-down battery pack production data from cell manufacturers.
Forecast inputs span product type, power source configuration, application focus, and end-user tier across the analysis window. CAGRs derive from segment-level growth rate blending weighted by current revenue contribution. Industry-specific inputs include brushless motor adoption velocity in cabinet shop replacement cycles and municipal procurement mandate implementation timelines.
Practitioners should monitor lithium carbonate spot price movements and Taiwanese foundry capacity utilization for early signals of margin compression or production constraint. Forecasts reflect assumptions regarding REACH compliance cost trajectories and battery platform standardization momentum. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.