
 Gear Hobbing Cutter Market | 2026-2036
Gear Hobbing Cutter Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Hobbing Cutter Market Insights
Equipment leasing and tool-as-a-service financing is narrowing the capital barrier for mid-sized gear shops seeking premium hobbing technology. Gleason Corporation leverages its global service network to sustain recurring revenue from cutter resharpening programs. KLINGELNBERG GmbH anchors its position through integrated measuring and cutting system bundles. Mitsubishi Heavy Industries competes by dominating high-volume automotive powertrain contracts across Asia.
A gear hobbing cutter is a cylindrical cutting tool with helical gashes bearing precision-formed cutting edges, typically manufactured from high-speed steel or carbide substrates via grinding and coating processes, designed to generate involute gear tooth profiles through continuous generating motion between cutter and workpiece. Continuous hobs command the largest volume share due to throughput advantages in automotive mass production, while carbide material grades capture expanding margin pools as hardened gear finishing requirements intensify. Powder metallurgy substrates represent the fastest-growing material category, driven by tool life demands in dry machining environments.
Germany's KBA enforces precision standards affecting cutter certification for automotive supply chains, while REACH restricts cobalt and tungsten sourcing in European-manufactured substrates. China's GB standards and MIIT industrial upgrading directives shape domestic procurement criteria for imported versus locally produced hobs. Stakeholders must monitor how dual carbon goals in China and EU Green Deal material traceability rules will redistribute competitive advantage between substrate technologies and regional supply bases.
Market Dynamics
Carbide hobs are displacing high-speed steel across automotive powertrain machining as hardened gear finishing requirements intensify, while REACH material compliance and China's dual carbon goals simultaneously reshape substrate sourcing decisions and supplier certification pathways.
Growth Catalysts
- EV Transmission Volume:Automotive Tier-1 suppliers in Germany and Japan are expanding carbide hob adoption for electric vehicle gearbox production, creating sustained demand for precision cutting tools capable of machining hardened steel components.
- Powder Metallurgy Substrates:REACH restrictions on cobalt and tungsten sourcing are accelerating powder metallurgy development, enabling European manufacturers to maintain tool life performance while meeting EU Green Deal material traceability requirements.
- Dry Machining Environments:Environmental regulations across multiple jurisdictions are eliminating flood coolant systems, driving demand for thermally stable cutter substrates that perform without liquid cooling infrastructure.
Market Restraints
- Tungsten Supply Concentration:Primary tungsten ore processing concentrates in China, exposing non-Chinese hob manufacturers to export quota volatility and strategic material access risks.
- Carbide Cost Structure:Cobalt binder prices fluctuate with battery industry demand, compressing margins for premium cutter grades dependent on cobalt-rich cemented carbide formulations.
- Grinding Equipment Lead Times:Precision hob grinding machinery availability constrains capacity expansion, with specialized CNC tool grinders requiring 12-18 month delivery schedules from European and Japanese suppliers.
Strategic Opportunities
- Tool-as-a-Service Models:Equipment leasing and cutter lifecycle management programs are emerging as financing alternatives, lowering capital barriers for mid-sized gear shops seeking premium hobbing technology without ownership burden.
- Resharpening Service Networks:Cutter reconditioning and coating renewal services create recurring revenue streams, with manufacturers capturing margin from tool life extension rather than sole new cutter sales.
- Integrated Metrology Bundles:Combining cutting systems with in-process gear measurement equipment addresses quality verification bottlenecks, particularly in high-mix low-volume production environments.
Industry Challenges
- Precision Grinding Specialist Shortage:Master-level CNC tool grinding expertise remains scarce, with training programs failing to replenish retiring skilled technicians capable of complex hob profile generation.
- Multi-Standard Certification Complexity:Germany's KBA precision standards, China's GB certification requirements, and ISO gear accuracy classes create overlapping compliance burdens for suppliers serving multinational automotive chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Hobbing Cutter Market |
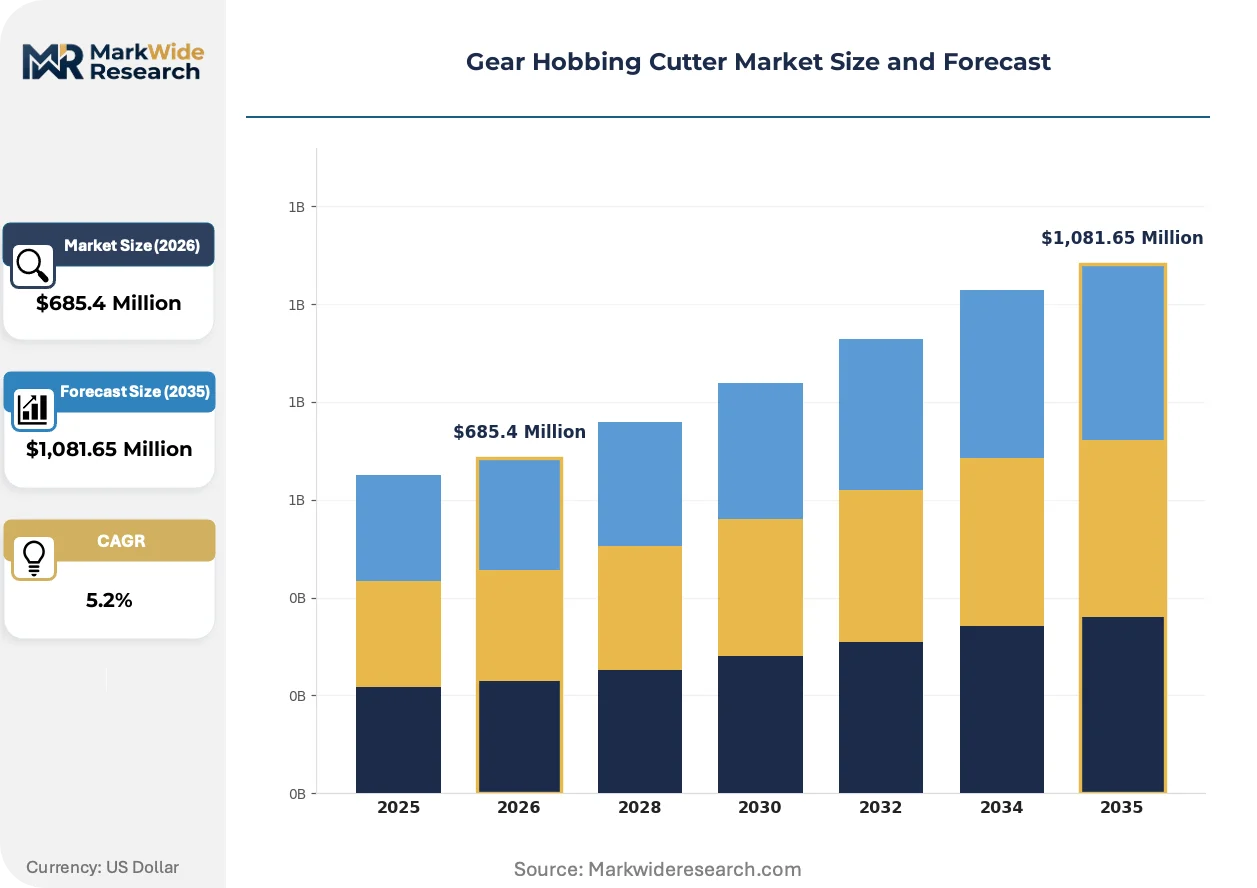
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Hob, Continuous Hob, Stack Hob, Modular Hob, Helical Hob Material: High-Speed Steel, Carbide, Cermet, Powder Metallurgy, Ceramic Application: Power Transmission, Aerospace Machinery, Heavy Equipment, Packaging Machines, Printing Equipment End User: Gear Manufacturers, Precision Tool Makers, Aerospace Suppliers, Industrial Equipment Producers, Automotive Tier-1s |
| Companies Covered | Liebherr Group, Gleason Corporation, KLINGELNBERG GmbH, Mitsubishi Heavy Industries, Star SU LLC, LMT Tools GmbH and Co., Reishauer AG, Kapp Niles, Samputensili Machine Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Hobbing Cutter Market Trends and Innovations
Digital thread integration between cutter design, manufacturing, and performance monitoring is collapsing traditional feedback loops, while regulatory chemistry restrictions and service model reinvention simultaneously reshape competitive positioning.
Multi-layer PVD coating architectures incorporating aluminum-chromium-nitride and silicon-based interlayers are extending tool life in interrupted cutting conditions. Automotive powertrain suppliers in Japan and Germany are adopting these coatings for continuous generating applications at elevated speeds. The technology is migrating from aerospace specialty suppliers into mainstream automotive Tier-1 machining departments.
REACH Annex XVII restrictions on cobalt compounds are forcing substrate reformulation across European manufacturing bases. Powder metallurgy high-speed steel grades with reduced cobalt content are achieving parity with traditional grades in dry cutting applications. German hob manufacturers are responding by certifying alternative binder systems through KBA automotive supply chain qualification protocols.
Performance-based cutter procurement is replacing capital equipment purchase models in mid-sized gear production facilities. Machine shops in China's Yangtze River Delta cluster are contracting hob availability per machined gear rather than owning cutter inventories. This shift transfers tool life risk to suppliers while compressing working capital requirements for buyers.
Gear Hobbing Cutter Market Segmentation
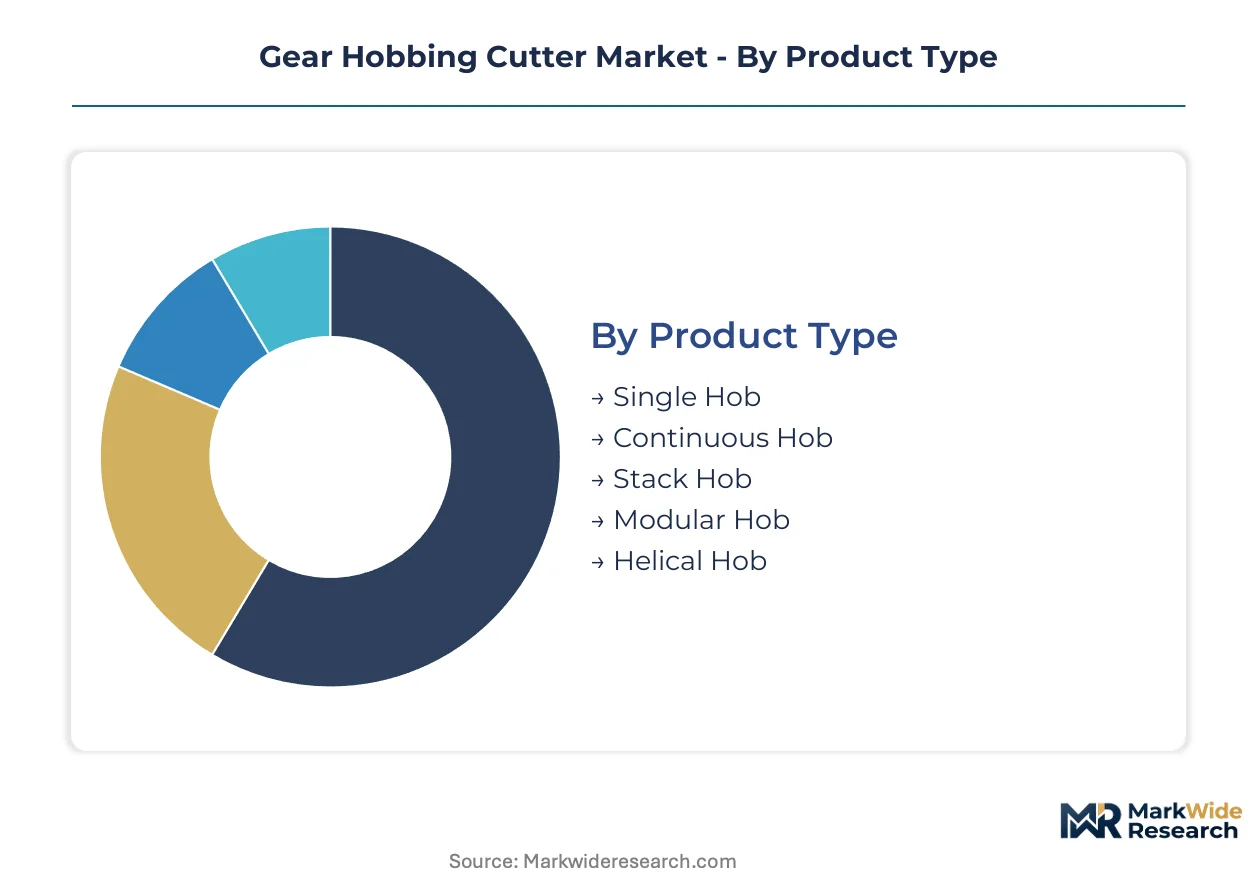
Segmentation in the gear hobbing cutter market reveals how cutter geometry, substrate chemistry, and end-use precision requirements create distinct procurement patterns across automotive, aerospace, and industrial machinery supply chains.
Product Type:
Use-case spectrum spans from single-piece prototype machining to continuous mass production, with geometry complexity and changeover flexibility driving selection criteria across different volume environments.
- Continuous Hob:Cylindrical cutters with uninterrupted helical cutting edges enable synchronized generating motion for high-throughput automotive gear production. Demand concentrates in Germany and Japan where EV transmission Tier-1s require hardened steel finishing at elevated speeds without tool change interruption.
- Modular Hob:Segment-based construction permits rapid profile interchangeability and localized insert replacement, reducing tooling inventory for high-mix gear shops. China's Yangtze River Delta machine tool cluster shows expanding procurement as contract manufacturers balance flexibility against capital constraints.
- Single Hob:Dedicated-profile cutters for specific gear modules serve prototype and repair applications.
- Stack Hob:Multiple cutter discs mounted on common arbors process gear sets simultaneously in heavy equipment manufacturing.
- Helical Hob:Optimized tooth geometry addresses helical gear applications in power transmission systems.
The dominant share belongs to Continuous Hob, while Modular Hob is closing the gap fastest.
Material:
Cost tier stratification separates commodity substrates from premium grades, with thermal stability and dry machining compatibility commanding price premiums in regulated environments.
- Carbide:Cemented tungsten-carbide substrates with cobalt binders deliver hardness exceeding 1600 HV for hardened gear finishing above 55 HRC. Automotive Tier-1s in Germany specify carbide hobs for EV transmission production where case-hardened components require consistent dimensional accuracy across extended cutting cycles.
- Powder Metallurgy:Atomized and sintered high-speed steel grades achieve uniform carbide distribution impossible in conventional wrought materials. REACH Annex XVII restrictions on cobalt compounds accelerate European manufacturer adoption as KBA automotive certification protocols validate alternative binder chemistries.
- High-Speed Steel:Conventional wrought grades remain prevalent in general-purpose gear machining.
- Cermet:Titanium-carbonitride based ceramics offer intermediate hardness for semi-finishing operations.
- Ceramic:Silicon-nitride and alumina-based substrates serve specialized high-speed dry machining in aerospace applications.
Carbide captures the largest revenue pool, though Powder Metallurgy exhibits the steepest expansion trajectory as regulatory chemistry constraints reshape European sourcing decisions.
Application:
Volume concentration follows capital equipment intensity, with power transmission and aerospace machinery commanding disproportionate precision tooling expenditure relative to unit counts.
- Power Transmission:Gearboxes for wind turbines, industrial drives, and automotive differentials require precision involute profiles across hardened steel components. Germany's KBA precision standards enforce cutter certification protocols that filter supplier qualification for this segment.
- Aerospace Machinery:Helicopter rotor transmissions and jet engine accessory drives demand AGMA Q14+ accuracy classes with full material traceability. Japanese METI industrial standards and JIS certification requirements shape procurement criteria for aerospace-grade hobs.
- Heavy Equipment:Mining and construction machinery gearboxes prioritize tool life over ultimate precision.
- Packaging Machines:Moderate-speed gear trains for filling and labeling equipment use standardized cutter geometries.
- Printing Equipment:Precision registration drives in commercial printing machinery require specialized profile accuracy.
Power Transmission maintains volume leadership, while Aerospace Machinery gains share fastest on precision premiumization and regulatory qualification barriers.
End User:
Customer type determines procurement sophistication, with integrated automotive suppliers and aerospace contractors driving specification complexity versus independent gear shops.
- Automotive Tier-1s:Transmission specialists in Germany and Japan specify carbide hobs with multi-layer PVD coatings for EV powertrain production. These buyers impose KBA and METI certification requirements that exclude non-qualified suppliers from contract eligibility.
- Gear Manufacturers:Independent job shops across China's Yangtze River Delta cluster increasingly adopt tool-as-a-service contracts rather than cutter ownership, transferring tool life risk to suppliers while compressing working capital requirements.
- Precision Tool Makers:Cutter producers serving secondary tooling markets require resharpening-compatible substrate grades.
- Aerospace Suppliers:Tier-2 and Tier-3 contractors follow prime contractor specifications with full material traceability documentation.
- Industrial Equipment Producers:In-house gear production for construction and agricultural machinery prioritizes cost efficiency over ultimate precision.
Automotive Tier-1s dominate procurement value, while Gear Manufacturers expand fastest through service model reinvention and financing alternative adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal material traceability requirements and China's dual carbon goals are redistributing competitive advantage between substrate technologies and regional supply bases. Procurement patterns now cluster around jurisdictions with qualified certification pathways and concentrated machine tool infrastructure.
Germany
Automotive Tier-1 transmission suppliers specify carbide hobs with KBA-certified precision grades for EV powertrain production. REACH Annex XVII restrictions on cobalt compounds force substrate reformulation across manufacturing bases. Bavaria's gear manufacturing corridor anchors European demand for hardened steel finishing tools.
China
MIIT industrial upgrading directives shape domestic procurement criteria favoring locally produced hobs over imports. GB standards certification creates qualification barriers for foreign suppliers. The Yangtze River Delta machine tool cluster adopts tool-as-a-service contracts, transferring tool life risk from gear shops to cutter suppliers.
Japan
METI industrial standards and JIS certification requirements govern aerospace-grade hob procurement for helicopter rotor and jet engine accessory drives. Automotive powertrain specialists dominate high-volume contracts across Asia. Nagoya's precision tooling district concentrates coating technology development for elevated-speed continuous generating applications.
United States
EPA environmental regulations and OSHA workplace standards influence dry machining adoption in automotive supply chains. The Midwest manufacturing belt sustains demand for modular hobs serving high-mix production environments. Michigan and Ohio-based gear shops prioritize resharpening-compatible substrate grades to extend cutter lifecycle value.
India
BIS certification requirements and PLI scheme incentives for advanced manufacturing equipment shape import substitution strategies. The country's national automotive regulator enforces precision standards affecting cutter qualification for commercial vehicle transmission production. Maharashtra and Gujarat industrial corridors expand carbide hob adoption for two-wheeler and tractor gearbox machining.
Gear Hobbing Cutter Market Competitive Landscape
On the supply side, the industry is tiered between integrated cutting system bundlers, specialized precision grinding houses, and regional service network operators. Strategic archetypes include metrology-integrated solution providers, resharpening service network builders, and powder metallurgy substrate specialists. Dominant competitive moves center on cutter lifecycle management program expansion and strategic partnerships for coating technology access.
Among European precision tooling houses, KLINGELNBERG GmbH and Reishauer AG exemplify the metrology-integrated archetype, occupying positions where measurement system bundling creates switching costs. Gleason Corporation anchors the service network tier through global resharpening infrastructure. Mitsubishi Heavy Industries sits within the scale-driven segment, representing high-volume automotive powertrain contract concentration. LMT Tools GmbH and Co. occupies the specialized substrate formulation space, reflecting powder metallurgy development imperatives under REACH compliance pressure.
| Leading Market Players |
|---|
| Liebherr Group |
| Gleason Corporation |
| KLINGELNBERG GmbH |
| Mitsubishi Heavy Industries |
| Star SU LLC |
| LMT Tools GmbH and Co. |
| Reishauer AG |
| Kapp Niles |
| Samputensili Machine Tools |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta machine tool cluster absorbs significant carbide substrate capacity, translating tungsten supply leverage into downstream pricing power for precision hobs serving EV transmission Tier-1s. REACH compliance costs in European manufacturing bases feed through to premium grades, while tool-as-a-service contracts in China compress working capital burdens and reshape buyer-seller power dynamics.
Pricing Analysis
Certification level creates the primary spread, with KBA-qualified hobs commanding substantial premiums over uncertified alternatives in German automotive supply chains. Three-tier pricing structure across premium, standard, and economy levels reflects substrate chemistry, coating architecture, and resharpening service bundling. Cost compression in standard-grade carbide hobs intensifies because cobalt binder prices fluctuate with battery industry demand. Independent gear manufacturers in China's Yangtze River Delta cluster exhibit highest price sensitivity, while German automotive Tier-1s prioritize performance guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized precision grinding houses in Germany, Japan, and Switzerland that control CNC tool grinder capacity. Raw material dependencies center on tungsten ore processing from China, cobalt binder compounds subject to REACH Annex XVII restrictions, and specialized PVD coating precursors. Single-source vulnerability concentrates in precision hob grinding machinery, with European and Japanese equipment suppliers commanding 12-18 month delivery schedules. Distribution runs through direct OEM relationships for automotive Tier-1s, regional distributor networks for independent gear shops, and integrated service contracts for tool-as-a-service adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gear hobbing cutter demand tracks automotive powertrain capital expenditure cycles, with EV transmission investment now driving the upswing phase. Recovery durability hinges on hardened gear finishing requirements intensifying across German and Japanese automotive supply chains.
For Market Incumbents: Build switching-cost moats through integrated metrology bundling that locks automotive Tier-1s into measurement-compatible cutter ecosystems. KLINGELNBERG GmbH exemplifies this archetype by combining cutting systems with in-process gear verification equipment. Defend against powder metallurgy substrate specialists by securing KBA certification pathways for alternative binder chemistries ahead of REACH enforcement tightening. Capacity addition in China's Yangtze River Delta cluster captures tool-as-a-service contract growth. For New Entrants and Emerging Players: Build out resharpening service networks in North American Midwest manufacturing belt, where gear shops prioritize lifecycle value over new cutter acquisition. Modular hob systems for high-mix production environments offer the most penetrable white space, with changeover flexibility commanding premiums in contract manufacturing settings. Go-to-market positioning as coating technology specialists, leveraging multi-layer PVD architectures for dry machining applications, bypasses capital-intensive grinding equipment barriers. For Investors and Strategic Acquirers: Long-term, this sits as a cyclical compounder play because cutter consumption correlates with installed machine tool hours and resharpening recurrence generates recurring revenue visibility. Acquisition targets should concentrate on regional service network operators with established automotive certification pathways, particularly those positioned in China's Yangtze River Delta or Germany's Bavarian gear corridor. Monitor tungsten export quota announcements from Chinese authorities as the critical inflection signal for substrate cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Technology Partnership | Multi-layer PVD access from Japanese suppliers extends tool life in dry machining environments. |
| Resharpening Network Expansion | Regional service hubs in Michigan and Ohio capture cutter lifecycle value from Midwest gear shops. |
| Powder Metallurgy Certification | KBA validation of reduced-cobalt substrates ensures REACH compliance without performance sacrifice. |
| Tool-as-a-Service Launch | Availability-based contracts in China's Yangtze River Delta transfer tool life risk from buyers. |
| Integrated Metrology Bundling | Measurement system lock-in creates switching costs for German automotive Tier-1 transmission suppliers. |
Research Methodology
The analysis maps carbide substrate grades, powder metallurgy formulations, coating architectures, and cutter geometry types, each validated through cutter grinding specialists, automotive Tier-1 procurement directors, gear manufacturer operations managers, and precision tooling distributors. Primary interviews with these stakeholders combined with secondary validation from customs/trade data, MIIT industrial policy directives, KBA certification registries, and SEC filings from listed machine tool manufacturers. Bottom-up segment sizing triangulates against top-down industry expenditure estimates.
Assumptions held fixed include REACH Annex XVII enforcement timelines, Chinese dual carbon policy implementation pace, and KBA precision standard maintenance across the analysis window. Segmentation dimensions modeled encompass substrate material, cutter geometry type, end-use application, and regional certification cluster. CAGRs derive from installed machine tool base expansion, cutter consumption per gear produced, and resharpening frequency shifts under dry machining adoption. Industry-specific forecast inputs include EV transmission production schedules and tungsten concentrate availability from Chinese processors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by powder metallurgy substrate specialists or integrated metrology bundlers would shift outcomes beyond projected ranges. Quarterly review of tungsten export quotas, KBA certification backlog durations, and tool-as-a-service contract signings in China's Yangtze River Delta is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Pipe Alignment Clamps Market
Tools
Foam Cutting Machine Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Workholding Tools Market
Tools
Woodpecker Tools Market
Tools
Rivet Gun Market
Tools
L Allen Wrench Market
Tools
Portable Pressure Washer Market
Tools
Portable Heat Press Machine Market
Tools
Rotary Hammer Drill Market
Tools
Boring Tools Market
Tools
Dumpy Level Market
Tools
Sand Control Tools Market
Tools
Global Vertical Grinding Machine Market
Tools
Rotary Knife Cutters Market
Tools
Woodworking Power Tools Market