
 US Hitter Based Hand Tools Market | 2026-2036
US Hitter Based Hand Tools Market Size, Share, and Industry Trends Forecast 2026-2036
US Hitter Based Hand Tools Market Analytics
Professional contractors is reorganizing demand patterns in the US hitter based hand tools space as DIY enthusiasm moderates post-pandemic. Stanley Black & Decker, Inc. leverages its broad retail footprint to maintain shelf dominance across home improvement chains. Snap-On Incorporated anchors its position through mobile distribution networks serving automotive technicians. Apex Tool Group LLC competes aggressively in the industrial maintenance channel with specialized striking tools.
Hitter based hand tools encompass manually operated impact devices including hammers, mallets, chisels, and clubs designed to deliver controlled striking force through hardened steel or alloy heads mounted on wood, fiberglass, or composite handles, typically heat-treated to 45-60 HRC for durability and shock resistance. These tools serve fundamental material-shaping, fastening, and demolition functions across construction, manufacturing, and repair operations where pneumatic or powered alternatives remain impractical. Hammers dominate volume shipments due to universal applicability in framing and finishing work, while composite material handles represent the fastest-growing configuration as ergonomics and vibration-dampening properties gain priority. Distribution through wholesalers captures the largest margin pool by serving bulk procurement needs of national construction firms and fleet maintenance operations.
OSHA regulations governing hand and power tool safety establish baseline performance requirements for striking-tool design and workplace usage protocols. ANSI standards for hammers and mallets specify hardness ratings, handle attachment strength, and labeling requirements that manufacturers must satisfy for commercial acceptance. The FTC monitors labeling claims regarding tool origin and material composition, affecting import sourcing strategies. Stakeholders must monitor evolving state-level right-to-repair legislation and its potential to expand tool refurbishment markets versus new unit sales.
Market Dynamics
Professional contractors in Texas and Florida are compressing replacement cycles as hurricane recovery and infrastructure spending concentrate demand, while OSHA tightening ANSI strike-tool specifications forces material certification upgrades across supply chains.
Growth Catalysts
- Residential construction rebound:Single-family housing starts in the Sun Belt are accelerating framing and finishing work, pulling hammer and mallet demand through wholesale channels serving national builders.
- ANSI/ASME B107.54:Updated strike-tool specifications mandate improved handle attachment testing, creating replacement demand for non-compliant inventory in distributor warehouses.
- Fiberglass composite handles:Vibration-dampening properties and reduced worker fatigue claims are displacing wood handles in professional contractor preference rankings.
Market Restraints
- Steel price volatility:Tool-grade alloy input costs fluctuate with scrap metal markets, compressing margin stability for heat-treatment operations in domestic foundries.
- Import concentration:Low-cost forged heads from Southeast Asian suppliers dominate economy-tier retail shelves, limiting pricing power for domestic manufacturers.
- Powered tool substitution:Cordless rotary hammers and pneumatic nailers encroach on demolition and fastening applications where manual striking once prevailed.
Strategic Opportunities
- Right-to-repair legislation:State-level mandates in California and New York could expand refurbishment services and aftermarket handle replacement markets versus new unit sales.
- Ergonomic certification:OSHA Voluntary Protection Programs favor tools with documented musculoskeletal stress reduction, creating premium positioning for vibration-isolated designs.
- Mobile distribution networks:Direct-to-job-site van sales bypass traditional wholesale markups for fleet maintenance operations and municipal repair crews.
Industry Challenges
- Heat-treatment skill shortage:Achieving consistent 45-60 HRC hardness ratings requires experienced metallurgists, and foundry workforce aging limits quality-control capacity expansion.
- Multi-standard compliance:Simultaneous adherence to ANSI strike-tool specs, OSHA hand-tool safety protocols, and state-level labeling laws extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hitter Based Hand Tools Market |
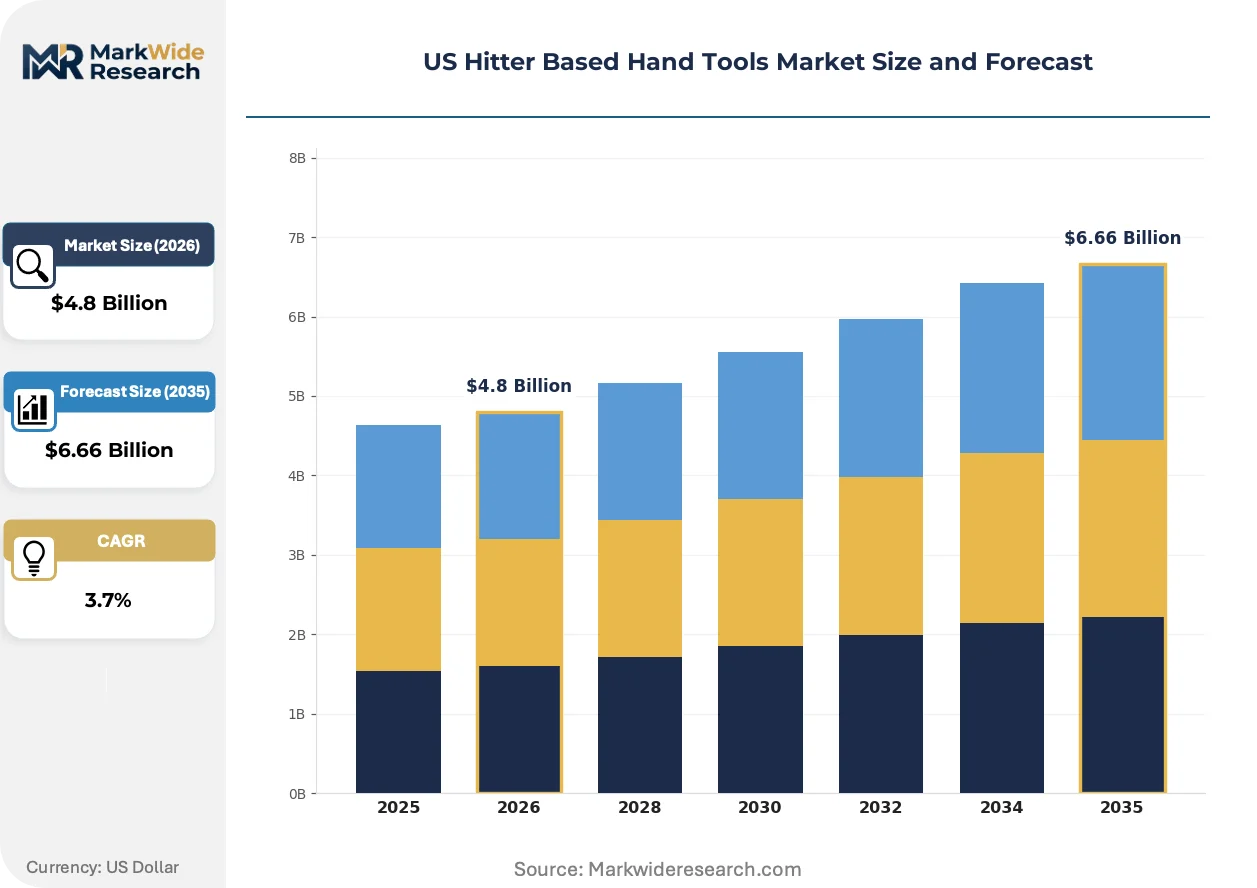
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hammers, Mallets, Chisels, Clubs Material: Steel, Aluminum, Wood, Composite End User: Construction, Automotive, DIY Enthusiasts, Maintenance Distribution Channel: Retail Stores, Online Sales, Wholesalers, Distributors |
| Companies Covered | Stanley Black & Decker, Inc., Techtronic Industries Co. Ltd., Snap-On Incorporated, Apex Tool Group LLC, Vaughan Manufacturing, The Ames Companies, Inc., Q.E.P. Co., Inc., ABC Hammers, Hardcore Hammers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hitter Based Hand Tools Market Evolving Landscape
Material science advances and regulatory pressure on worker safety are reconfiguring how striking tools are specified, purchased, and deployed across construction and maintenance operations.
Composite handle construction is fragmenting traditional wood-and-steel configurations. Multi-material layups combining fiberglass cores with rubber overmolds deliver superior shock absorption. Professional framers in Florida and Texas are specifying these configurations for hurricane reconstruction crews working extended shifts. The technology is fragmenting procurement patterns as contractors bypass standard retail SKUs for custom-configured fleet orders.
OSHA's updated Hand and Power Tool Safety guidelines emphasize documented hazard assessment for repetitive striking tasks. Construction firms now face inspection scrutiny for tool condition monitoring and replacement protocols. General contractors in high-growth states are responding by consolidating supplier relationships to ensure traceable certification documentation.
Wholesale buyers are unbundling after-sales service from product procurement. Large construction fleets now negotiate separate maintenance contracts for handle replacement and head reconditioning rather than accepting bundled warranty terms. This pattern is most visible in Texas municipal infrastructure departments and Florida utility maintenance operations managing distributed tool inventories across multiple staging yards.
US Hitter Based Hand Tools Market Segmentation
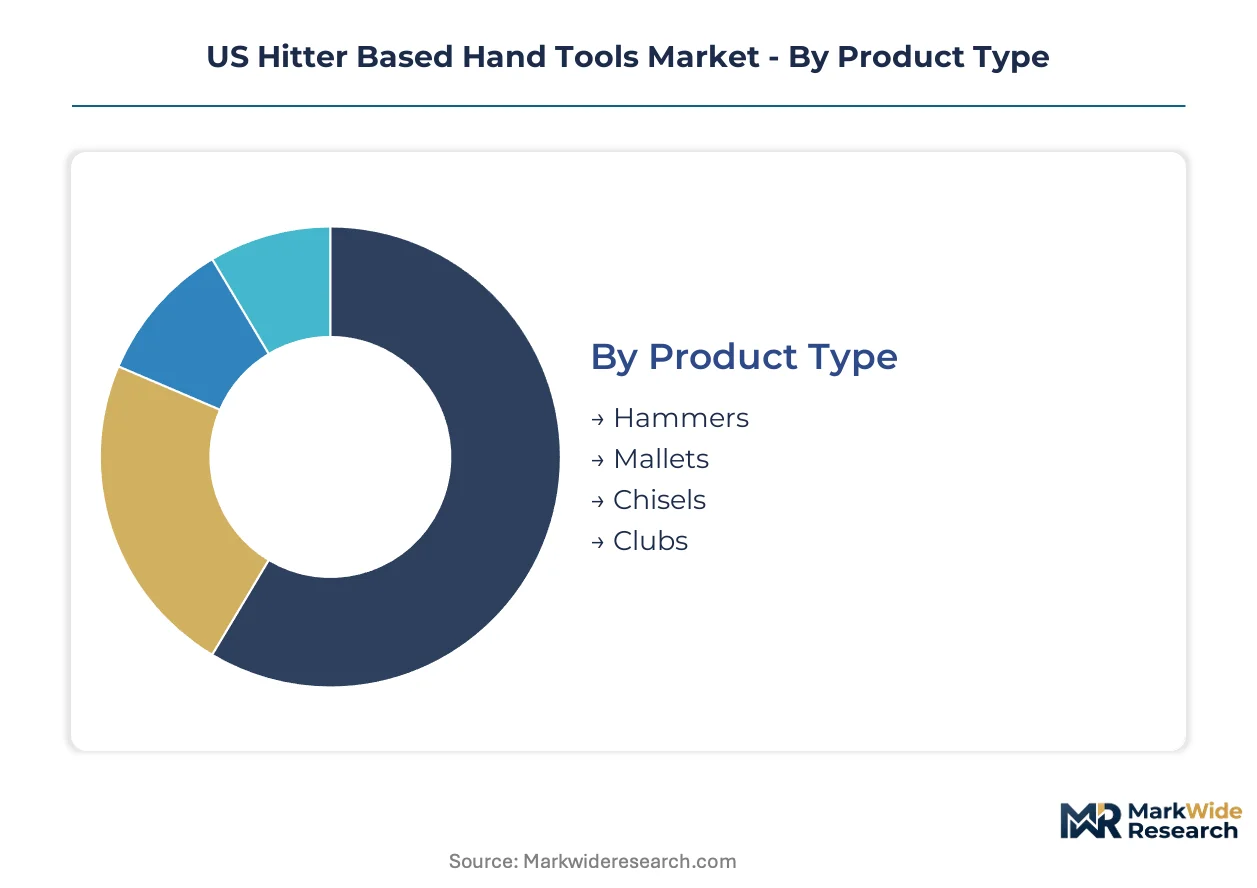
Segmentation in the US hitter based hand tools market reveals how procurement authority, material specifications, and channel economics fragment purchasing behavior. Contractors, fleet managers, and retail buyers operate on fundamentally different selection criteria, forcing manufacturers to maintain parallel product lines and certification documentation.
Product Type:
Margin pools concentrate in specialized striking configurations where heat-treatment precision commands premium positioning against commodity forged alternatives.
- Hammers:Claw hammers, framing hammers, and ball-peen variants dominate volume shipments through hardened steel heads heat-treated to 50-60 HRC. Texas residential construction crews and Florida hurricane recovery contractors are specifying fiberglass-handled framing hammers for extended demolition shifts.
- Mallets:Dead-blow and rubber-faced configurations serve finish carpentry and automotive assembly where marring prevention matters. Demand clusters in Florida marine repair yards and Texas oilfield maintenance operations requiring non-sparking aluminum or brass faces.
- Chisels:Cold chisels, wood chisels, and masonry variants with 45-55 HRC cutting edges serve material removal tasks. Cold chisels see concentrated procurement from Texas pipeline maintenance crews.
- Clubs:Sledgehammers and splitting mauls deliver high-impact force for demolition and driving stakes. Florida utility restoration teams rotate these through mobile distribution networks for storm response staging yards.
Hammers hold installed capacity. Mallets are rotating up the share rankings.
Material:
Cost tier stratification separates specification-grade alloy formulations from economy-tier commodity inputs.
- Steel:Tool-grade carbon and alloy steels with controlled vanadium content deliver 45-60 HRC hardness ratings through oil or induction hardening. OSHA ANSI strike-tool specifications mandate traceable heat-treatment certificates for commercial acceptance.
- Composite:Fiberglass-reinforced polymer handles with rubber overmolds dampen vibration transmission to 40% below wood equivalents. Professional contractors in Texas and Florida are specifying these for repetitive-strike injury prevention programs.
- Aluminum:Non-sparking bronze-aluminum alloys serve petrochemical and explosive environments. Texas refinery maintenance crews procure these through specialized industrial distributors.
- Wood:Hickory and ash handles retain preference among traditional craftsmen and budget-sensitive DIY buyers. Retail chains in the Southeast maintain wood-handle SKUs for price-conscious homeowners.
Steel maintains specification dominance. Composite configurations are climbing the fastest.
End User:
Application intensity determines replacement frequency and certification documentation requirements.
- Construction:Framing, finishing, and demolition crews consume hammers and mallets on accelerated replacement cycles. Sun Belt residential builders compress procurement timelines as housing starts rebound.
- Maintenance:Fleet and facility operations negotiate consolidated supplier relationships for traceable tool condition monitoring. Texas municipal infrastructure departments unbundle after-sales service from product procurement.
- Automotive:Body repair and mechanical technicians favor dead-blow mallets and ball-peen hammers through mobile van distribution networks serving shop floors.
- DIY Enthusiasts:Post-pandemic moderation in home improvement activity shifts volume toward entry-tier retail SKUs with wood handles and basic steel heads.
Construction anchors volume throughput. Maintenance is gaining procurement sophistication.
Distribution Channel:
Customer type dictates whether procurement flows through relationship-based wholesale negotiation or transactional retail capture.
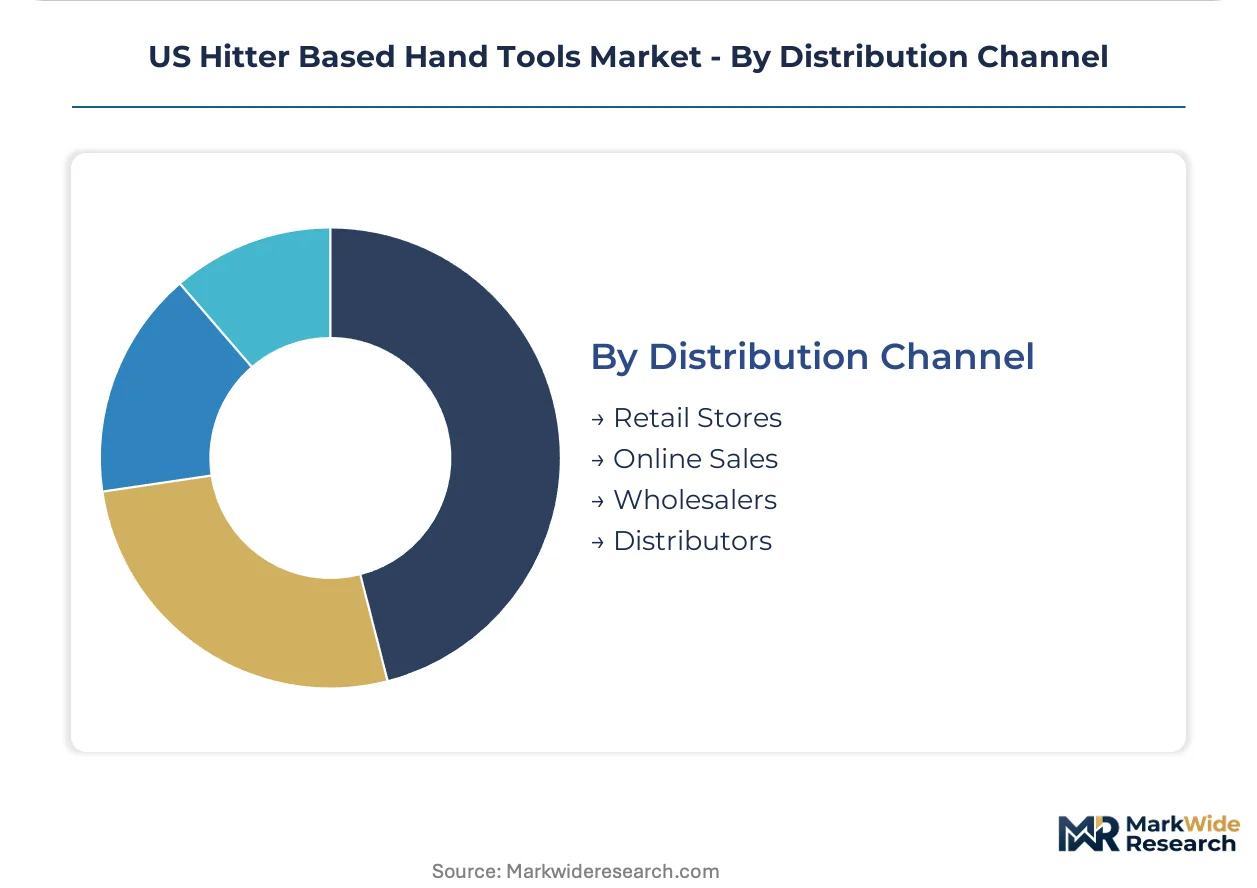
- Wholesalers:National construction firms and fleet maintenance operations procure bulk quantities through negotiated contracts with documented ANSI certification. Margin pools concentrate here through volume-tier pricing and consolidated logistics.
- Distributors:Industrial supply houses serving manufacturing and petrochemical clients maintain specialized non-sparking and ergonomic inventory. Texas and Florida distributors stock hurricane response and refinery turnaround configurations.
- Retail Stores:Home improvement chains capture DIY and small contractor walk-up demand through broad SKU availability and immediate fulfillment.
- Online Sales:Direct-to-consumer and small business procurement platforms serve replacement handle orders and specialized configurations bypassing geographic inventory constraints.
Wholesalers command the margin architecture. Online sales are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor and Atlantic seaboard ports position specific US sub-regions as procurement hubs for hitter-based hand tools, with infrastructure density dictating inventory staging and replacement cycle velocity.
Texas
Hurricane reconstruction crews and Permian Basin oilfield maintenance operations are compressing hammer and mallet replacement timelines. OSHA enforcement of updated ANSI strike-tool specifications mandates traceable heat-treatment documentation for commercial acceptance. Houston-area industrial distributors stock specialized non-sparking configurations for refinery turnaround seasons.
Florida
Utility restoration teams and marine repair yards are driving concentrated demand for fiberglass-handled striking tools. State-level procurement protocols for hurricane response staging yards require documented tool condition monitoring. Miami-Dade and Tampa Bay maintenance fleets unbundle after-sales service from product procurement.
California
Right-to-repair legislation is expanding refurbishment markets versus new unit sales in construction and fleet maintenance channels. Cal/OSHA alignment with federal hand-tool safety standards tightens material certification requirements for strike-tool imports. Los Angeles and San Francisco Bay Area contractors specify ergonomic composite handles for repetitive-strike injury prevention.
Illinois
Midwest manufacturing belt maintenance operations anchor wholesale procurement of cold chisels and ball-peen hammers. Illinois OSHA consultation programs emphasize documented hazard assessment for repetitive striking tasks. Chicago-area fleet managers consolidate supplier relationships for traceable certification documentation.
New York
State-level right-to-repair mandates are reshaping aftermarket handle replacement markets. New York Department of Labor enforcement of hand-tool safety protocols extends product development timelines for multi-standard compliance. New York Metro construction firms negotiate separate maintenance contracts for tool reconditioning.
US Hitter Based Hand Tools Market Competitive Landscape
Concentration sits with diversified tool conglomerates and specialized industrial fabricators operating across tiered pricing structures. The vendor base stratifies between mass-market retail suppliers, mobile distribution specialists, and industrial-grade manufacturers. Three archetypes dominate: broad-portfolio conglomerates leveraging retail shelf dominance, mobile-network operators serving fleet maintenance channels, and niche specialists targeting non-sparking and ergonomic configurations. Competitive moves center on consolidated supplier relationships for certification traceability and unbundled service contracts for fleet reconditioning.
Within the diversified conglomerate tier, Stanley Black & Decker, Inc. and Techtronic Industries Co. Ltd. exemplify scale-driven positioning across home improvement retail channels. Snap-On Incorporated anchors the mobile distribution archetype through direct-to-job-site van networks. Apex Tool Group LLC occupies a position within industrial maintenance specialization. These three represent distinct competitive vectors—retail footprint density, mobile service infrastructure, and channel-specific certification depth.
| Leading Market Players |
|---|
| Stanley Black & Decker, Inc. |
| Techtronic Industries Co. Ltd. |
| Snap-On Incorporated |
| Apex Tool Group LLC |
| Vaughan Manufacturing |
| The Ames Companies, Inc. |
| Q.E.P. Co., Inc. |
| ABC Hammers |
| Hardcore Hammers |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day heat-treatment lead times for tool-grade alloy heads concentrate pricing power with domestic foundries holding ANSI certification capacity, while wholesale buyers leverage volume consolidation to compress margin capture at the distribution tier. This temporal friction between certified production bottlenecks and procurement scale economics defines how value flows across the hitter-based hand tools supply chain.
Pricing Analysis
Volume-discount tiering separates specification-grade alloy formulations certified to 45-60 HRC hardness from economy-tier forged imports. Price differentiation rests on ANSI strike-tool documentation depth and after-sales service bundling. Cost compression in the economy tier intensifies because Southeast Asian import concentration limits domestic manufacturer pricing power. DIY enthusiasts exhibit highest price sensitivity; Texas municipal fleet managers show lowest sensitivity due to compliance mandates.
Supply Chain Analysis
Inbound logistics costs from Southeast Asian ports through Los Angeles-Long Beach and Savannah gateways determine landed cost economics for forged heads. Tool-grade alloy steel draws from domestic foundries in Ohio and Pennsylvania, composite handles from Mexican maquiladoras, and non-sparking aluminum alloys from Canadian suppliers. Single-source vulnerability concentrates in heat-treatment capacity for 50-60 HRC certification. Distribution runs through wholesale negotiation for national construction firms and mobile van networks for automotive technicians.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry metallurgist expertise for consistent 45-60 HRC hardness ratings represents the binding constraint on quality-controlled capacity expansion, with workforce aging compressing the talent pipeline faster than training programs replenish it.
For Market Incumbents: Fortify heat-treatment certification documentation as a competitive moat against import substitution, while consolidating supplier relationships with Texas and Florida construction fleets to secure traceable ANSI compliance contracts. Capacity addition in domestic foundry operations anchors margin defense against Southeast Asian price pressure. For New Entrants and Emerging Players: ANSI B107.54 fast-track certification for fiberglass composite handle configurations opens procurement access to Florida hurricane reconstruction and Texas oilfield maintenance channels. The penetrable segment sits in ergonomic vibration-dampening designs for repetitive-strike injury prevention programs. Go-to-market leverage runs through direct-to-job-site van sales bypassing wholesale markups. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fragmented regional foundry capacity and aging metallurgical expertise create acquisition targets with irreplaceable certification assets. The signal to watch is state-level right-to-repair legislation volume in California and New York, which would expand refurbishment service attach rates versus new unit sales economics.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Certification Investment | OSHA ANSI compliance documentation secures wholesale procurement from national construction firms. |
| Composite Handle Manufacturing Scale-Up | Fiberglass core production with rubber overmolds captures Florida and Texas contractor preference shifts. |
| Mobile Distribution Network Expansion | Direct-to-job-site van sales bypass traditional wholesale markups for fleet maintenance operations. |
| After-Sales Service Unbundling | Separate maintenance contracts for handle replacement penetrate Texas municipal infrastructure departments. |
| Right-to-Repair Service Development | Refurbishment capabilities in California and New York extend tool lifecycle revenue versus unit sales. |
Research Methodology
A standing panel of procurement directors at national construction firms, fleet maintenance supervisors, industrial distributor category managers, and foundry operations heads provided ongoing calibration across primary interview cycles. Secondary validation drew from OSHA enforcement records, ANSI standards documentation, customs import data for tool-grade steel, and SEC filings of diversified tool manufacturers. Bottom-up shipment estimates triangulated against top-down construction spending allocations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling captured product type, material specification, end-user application intensity, and distribution channel economics. CAGRs derived from regression analysis of replacement cycle compression in high-growth states and material substitution rates for composite configurations.
Underlying assumptions cover residential construction rebound velocity, OSHA enforcement intensity, and alloy input cost stability, with deviation risk concentrated in steel price volatility and import tariff adjustments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Fiber Laser Cutting Machines Market
Tools
Global Metal Forming Machine Tools Market
Tools
Thickness Planers Market
Tools
Woodworking Sanders Market
Tools
Structural Wood Screws Market
Tools
Brushcutter Market
Tools
Bandsaw Machines Market
Tools
Book Binding Machines Market
Tools
Drywall Tool Market
Tools
Mechanical Hand Tools Market
Tools
Overload Protection Tools Market
Tools
Workholding Tools Market
Tools
Mortiser Market
Tools
Tool Pliers Market
Tools
Handheld Engraving Machine Market
Tools
Stand Tile Saw Market