
 Power Tools Market | 2026-2036
Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Power Tools Market Intelligence
Lithium-ion cell chemistry is pivoting away from cobalt-heavy formulations toward lithium iron phosphate and high-nickel alternatives, reducing raw material cost volatility for cordless platforms. Robert Bosch GmbH leverages its in-house battery cell production to control supply chain exposure across European and Asian manufacturing footprints. Techtronic Industries Co., Ltd. competes through concentrated R&D spending on brushless motor architectures that extend runtime per charge cycle.
Power tools are electromechanical devices designed to deliver rotational or percussive force for cutting, drilling, fastening, or grinding operations, typically rated by torque output, no-load speed, and battery voltage in cordless configurations. Their primary purpose is to reduce manual labor intensity and improve repeatability in fabrication, assembly, and field construction tasks. Battery-powered cordless drills anchor the product type tier as the highest-volume category, driven by professional trade replacement cycles and homeowner penetration. Contractors represent the most margin-accretive end user segment, while DIY enthusiasts constitute the fastest-expanding demand pool as retail channels push compact, price-accessible lithium-ion platforms.
FCC certification governs electromagnetic emissions for electric and battery-powered tools sold in the United States, while CE marking and the EU Machinery Directive establish safety and interoperability standards for European market access. OSHA workplace safety rules in the United States and REACH chemical restrictions in Europe both elevate compliance costs but simultaneously filter out low-specification imports, tightening competitive intensity among compliant manufacturers. Stakeholders must track how evolving battery transport regulations and emerging carbon-border adjustment mechanisms reshape sourcing decisions for motor laminations, plastic housings, and cell pack assemblies.
Market Dynamics
The transition from corded to cordless platforms is restructuring competitive advantage around battery cell chemistry control and thermal management systems rather than mechanical engineering heritage.
Growth Catalysts
- EU Ecodesign Regulation:Mandatory energy efficiency standards for electric motors are accelerating brushless motor adoption across professional-grade equipment sold in Germany, France, and Italy.
- Residential construction:Single-family housing starts in the United States and Australia are pulling compact 18V-20V drill/driver kits through home improvement retail channels.
- Lithium iron phosphate cells:Cobalt-free cathode formulations are reducing raw material cost volatility for cordless platform manufacturers sourcing from Chinese cell producers.
Market Restraints
- Semiconductor supply concentration:Brushless motor controllers depend on silicon carbide MOSFETs concentrated in Taiwanese and South Korean foundry capacity.
- Battery transport restrictions:IATA lithium-ion shipping rules limit air freight options for finished cordless tools and replacement battery packs.
- Pneumatic tool substitution:Compressed-air nailers and impact wrenches retain cost advantages in high-volume automotive assembly plants.
Strategic Opportunities
- India manufacturing:Production-linked incentive schemes for electronic components are attracting power tool assembly operations to Gujarat and Tamil Nadu.
- Connected tool platforms:Bluetooth-enabled battery management systems are expanding into fleet management services for commercial contractor accounts.
- Refurbishment channels:Battery pack rebuild services using certified cell replacement are opening margin recovery streams outside original manufacturer control.
Industry Challenges
- Power electronics engineering:Shortage of motor control firmware developers is delaying next-generation brushless platform launches.
- Multi-certification timelines:Simultaneous FCC, CE marking, and GB standard compliance is extending product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Tools Market |
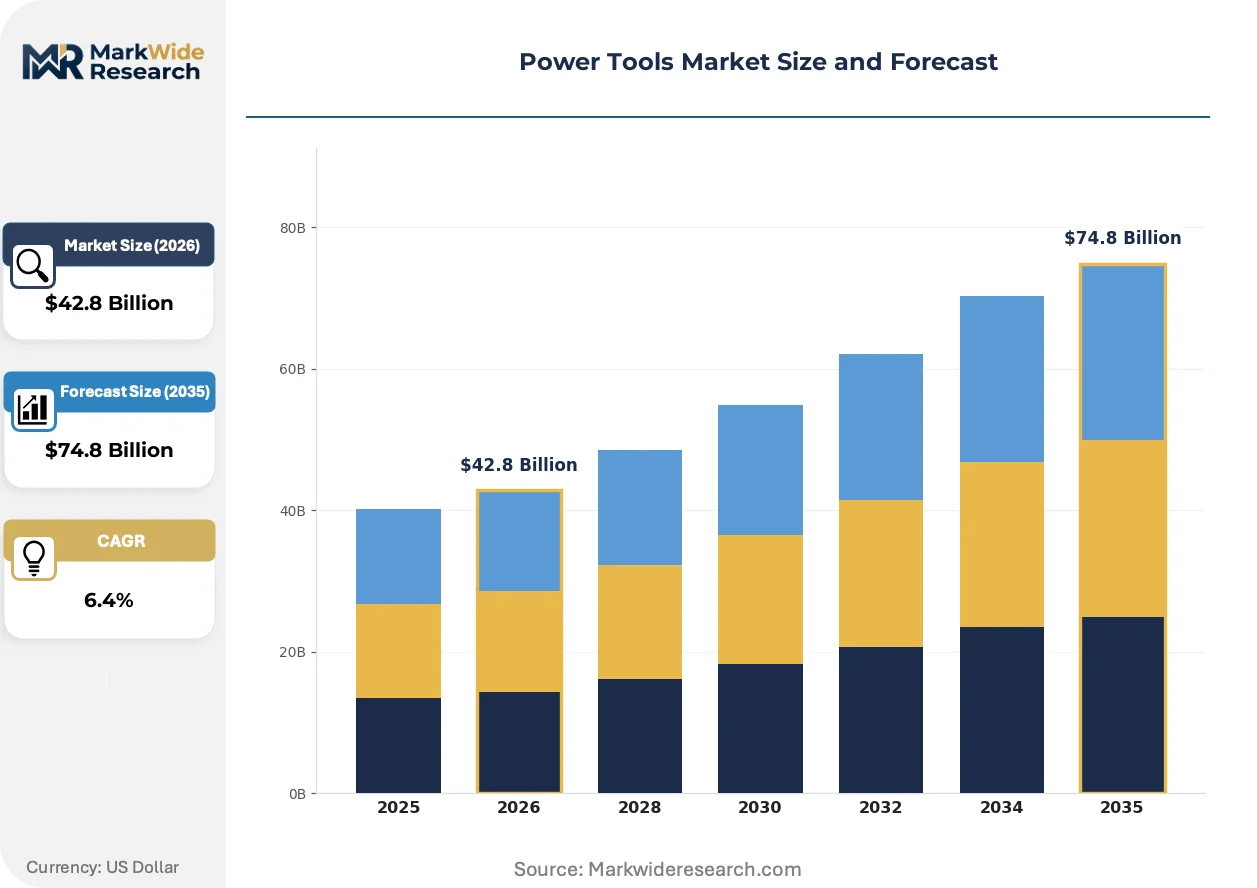
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless Drills, Angle Grinders, Jigsaws, Circular Saws End User: Contractors, Industrial Users, DIY Enthusiasts, Homeowners Power Source: Electric, Battery, Pneumatic, Hydraulic Application: Construction, Renovation, Woodworking, Metalworking |
| Companies Covered | Robert Bosch GmbH, Stanley Black & Decker, Techtronic Industries Co., Ltd., Makita Corporation, Koki Holdings Co., Ltd., Hilti Corporation, Atlas Copco AB, Emerson Electric Co., Chervon Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Tools Market Strategic Shifts & Innovations
Tool intelligence and energy density are converging to redefine performance benchmarks and ownership economics across professional and consumer segments.
Brushless motor architectures are expanding into compact 12V platforms previously dominated by brushed designs. Professional electricians and HVAC technicians in North America are adopting these lighter systems for overhead installation work. The technology is expanding into price-accessible tiers, compressing the performance gap between mid-range and premium cordless lines.
REACH chemical restrictions on SVHC substances in plastic housings and cable insulation are forcing compound reformulation across European supply chains. Manufacturers serving Germany and the Netherlands are accelerating halogen-free thermoplastic adoption ahead of 2026 sunset dates. Battery pack enclosures represent the highest compliance cost concentration due to flame-retardant additive substitution requirements.
Contractor procurement through integrated supply houses is fragmenting toward direct e-commerce replenishment of consumables and accessories. Independent electrical distributors in the United States are losing attach-rate revenue on bits, blades, and batteries to manufacturer-direct subscription programs. This pattern is most visible in commercial construction verticals where project-based purchasing authority has shifted to field operations managers.
Power Tools Market Segmentation
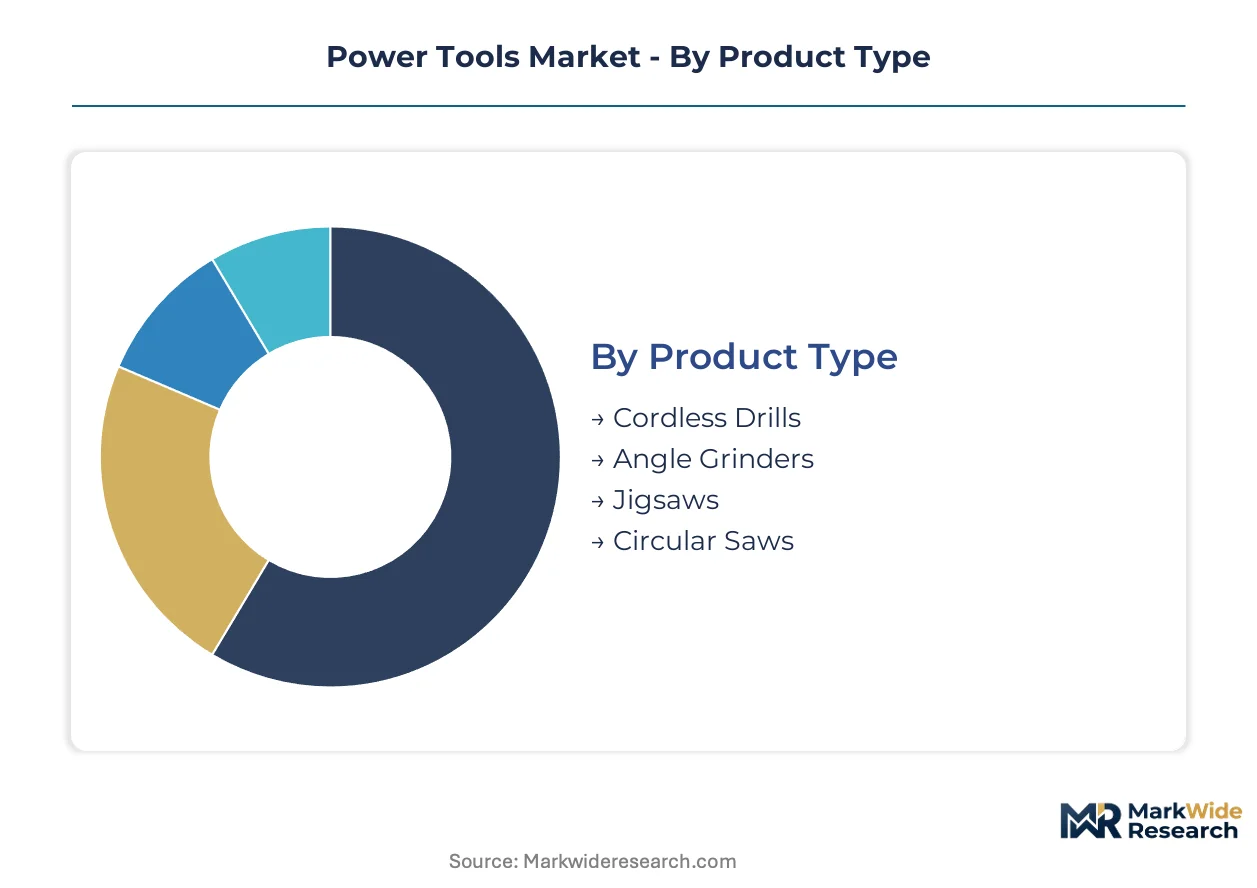
Power tools segment along four intersecting dimensions that determine margin structure and channel strategy. Product type and power source define manufacturing complexity and battery chemistry requirements, while end user and application dictate pricing tolerance and replacement cycle velocity.
Product Type:
Volume concentrates in compact drilling platforms, while premium margins accrue to specialized cutting equipment.
- Cordless Drills:These 18V-20V lithium-ion platforms dominate unit shipments through professional trade replacement cycles and homeowner penetration. Demand clusters in North American residential construction and German renovation markets, pulled by compact kit configurations through home improvement retail.
- Angle Grinders:Disc-based cutting and grinding tools serve metal fabrication and construction demolition with high torque brushless motor architectures. Industrial maintenance departments in automotive plants and shipyards drive specification requirements for dust sealing and vibration damping.
- Jigsaws:Reciprocating blade saws for curved cuts in wood and metal occupy a mid-volume tier with moderate technology differentiation.
- Circular Saws:These bench and portable cutting platforms anchor woodworking and framing applications with blade diameter determining power class segmentation.
Today's leader: Cordless Drills. Tomorrow's challenger: Angle Grinders.
End User:
Professional trade users command pricing power, while consumer segments expand addressable market breadth.
- Contractors:Commercial construction and specialty trade professionals generate the highest margin per unit through fleet purchasing and rapid replacement cycles. Their procurement shifts toward direct manufacturer subscription programs for battery and accessory replenishment.
- DIY Enthusiasts:These hobbyist purchasers represent the steepest expansion trajectory as compact lithium-ion platforms penetrate price-accessible tiers through retail channel promotion.
- Industrial Users:Manufacturing plant maintenance departments specify heavy-duty pneumatic and hydraulic alternatives for continuous-duty applications.
- Homeowners:Occasional-use purchasers drive seasonal demand spikes through promotional kit pricing at mass merchants.
Professional trades anchor profitability. Consumer segments drive volume scaling.
Power Source:
Battery platforms are displacing corded and pneumatic alternatives across mobility-critical applications.
- Battery:Lithium-ion cordless systems now dominate professional handheld categories, with cell chemistry pivoting toward cobalt-free formulations to reduce raw material cost volatility.
- Electric:Corded platforms retain cost advantages in stationary workshop environments and developing markets with intermittent grid reliability.
- Pneumatic:Compressed-air systems maintain position in high-volume automotive assembly where centralized compressor infrastructure exists.
- Hydraulic:These high-torque alternatives serve heavy construction and mining applications beyond battery power density limits.
Cordless solutions capture share fastest. Pneumatic systems defend industrial strongholds.
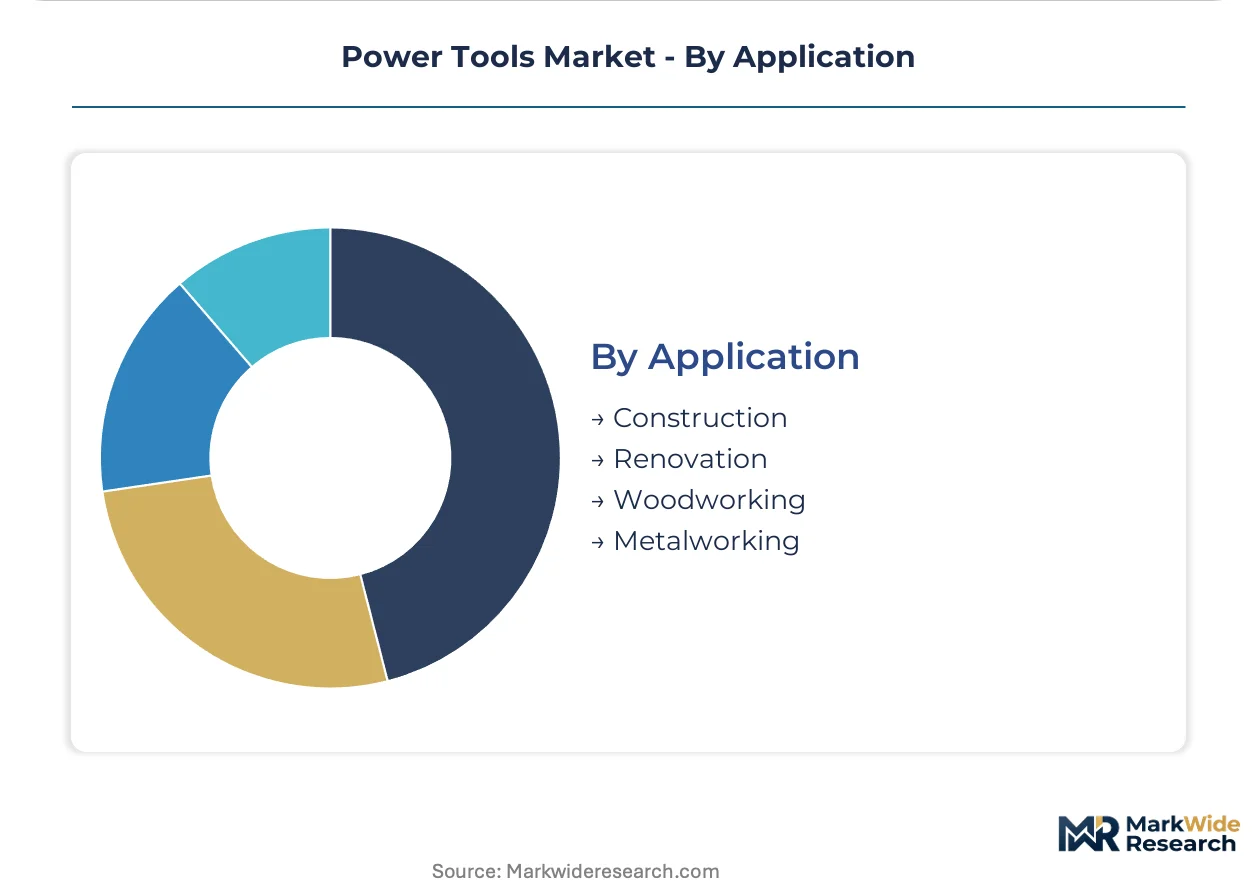
Application:
Construction activity levels determine regional demand timing, while material specialization drives tool specification diversity.
- Construction:New commercial and residential building generates concentrated demand for drilling, fastening, and cutting platforms with dust exposure ratings.
- Renovation:Remodeling activity in mature housing stocks pulls compact multi-tool kits through retail channels in Germany, France, and Australia.
- Woodworking:Precision cutting and shaping applications demand higher-speed spindle architectures with dust collection integration.
- Metalworking:Fabrication shops require thermal management and spark containment features for ferrous material processing.
New construction commands fleet scale. Renovation activity sustains replacement velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen-Dongguan production clusters anchor global cordless platform manufacturing, while demand concentrates across residential construction markets in North America, European renovation corridors, and Chinese infrastructure deployment. Regulatory divergence around battery chemistry and carbon intensity is fragmenting sourcing strategies across these demand centers.
United States
Single-family housing starts and commercial construction velocity pull compact 18V-20V drill/driver kits through home improvement retail. OSHA workplace safety rules elevate compliance costs for professional-grade equipment. Dallas-Fort Worth and Atlanta metro areas concentrate contractor fleet purchasing through integrated supply houses.
Germany
EU Ecodesign Regulation mandates accelerate brushless motor adoption across professional equipment sold through German distribution channels. REACH chemical restrictions on SVHC substances force halogen-free thermoplastic reformulation in battery pack enclosures. Stuttgart and Munich industrial corridors host precision motor manufacturing for premium cordless platforms.
China
Domestic infrastructure investment and export manufacturing demand sustain lithium iron phosphate cell production at scale. MIIT battery safety standards and dual carbon goals reshape cell chemistry roadmaps for cordless tool manufacturers. Shenzhen and Dongguan clusters integrate cell pack assembly with finished tool production for global export markets.
India
Production-linked incentive schemes for electronic components attract power tool assembly operations to Gujarat and Tamil Nadu. BIS certification requirements extend product launch timelines for multinational manufacturers entering the market. Pune and Chennai industrial zones concentrate contract manufacturing for both domestic distribution and re-export to Middle East markets.
Australia
Residential renovation activity in Sydney and Melbourne metro areas sustains replacement cycle velocity for compact lithium-ion platforms. TGA-equivalent electrical safety standards align with international norms while maintaining distinct certification pathways. Perth mining services sector drives demand for high-torque hydraulic alternatives beyond battery power density limits.
Power Tools Market Key Industry Players
Global majors compete with regional champions across battery chemistry control and brushless motor architectures. The vendor base organizes around three tiers: diversified industrial conglomerates with captive cell production, specialized power tool manufacturers with concentrated R&D spending, and contract assemblers serving price-accessible retail tiers. Consolidation pressure intensifies around semiconductor supply security and multi-certification compliance capabilities. Dominant competitive moves include backward integration into battery cell production and geographic expansion into India manufacturing corridors.
Among diversified industrial conglomerates, Robert Bosch GmbH exemplifies the integrated archetype through in-house battery cell production spanning European and Asian footprints. Techtronic Industries Co., Ltd. occupies a position within the specialized manufacturer tier, while Stanley Black & Decker represents scale-driven portfolio breadth across professional and consumer segments. These three anchors illustrate how competitive positioning diverges between supply chain control, concentrated technology investment, and brand portfolio diversification strategies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Stanley Black & Decker |
| Techtronic Industries Co., Ltd. |
| Makita Corporation |
| Koki Holdings Co., Ltd. |
| Hilti Corporation |
| Atlas Copco AB |
| Emerson Electric Co. |
| Chervon Holdings |
| Others |
Cost & Logistics Intelligence
Lithium iron phosphate cell costs cascade through cordless platform pricing tiers from Shenzhen pack integrators to German distribution channels, with cobalt-free chemistry compressing raw material volatility for mid-range professional equipment.
Pricing Analysis
Input-cost pass-through from battery cell chemistry shifts is compressing margins in economy-tier cordless drills while professional-grade brushless platforms maintain pricing power through runtime-per-charge differentiation. Three-tier pricing structure across premium, standard, and economy levels segments by motor architecture sophistication and battery management system capability. Pricing pressure stems from Chinese cell oversupply feeding contract assembler competition in retail-accessible tiers. DIY enthusiasts exhibit highest price sensitivity, while commercial contractors prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Workforce availability constraints in Dongguan and Shenzhen are tightening assembly capacity for brushless motor controllers, pushing multinational OEMs toward Gujarat and Tamil Nadu production-linked incentive corridors. Motor laminations draw from Japanese cold-rolled steel specialists, while silicon carbide MOSFETs rest on Taiwanese foundry output. Single-source vulnerability concentrates in South Korean power semiconductor fabrication. Distribution runs through integrated supply houses in Dallas-Fort Worth and Atlanta, with manufacturer-direct subscription programs fragmenting traditional electrical distributor attach-rate revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power tools market reads as a late-cycle quality story, with contractor procurement shifting toward premium brushless platforms that deliver measurable runtime advantages on commercial job sites.
For Market Incumbents: Lock in battery chemistry roadmaps through captive cell supply agreements or in-house lithium iron phosphate production, insulating margin structures from Chinese spot-market volatility. Defend fleet account relationships by embedding Bluetooth-enabled battery management systems into subscription replenishment programs before independent distributors lose attach-rate revenue entirely to direct channels. For New Entrants and Emerging Players: EU Ecodesign Regulation in Germany, France, and Italy opens a window for brushless motor specialists to capture specification share in professional equipment tiers ahead of 2026 compliance deadlines. Target price-accessible 12V compact platforms for North American residential construction, where overhead installation work demands lighter systems. Pursue e-commerce-first go-to-market positioning to bypass entrenched supply house relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-certification compliance capabilities and semiconductor supply security separate viable platforms from stranded inventory. Long-term viability favors manufacturers with backward integration into battery cells or captive motor lamination supply. Acquisition target archetype: mid-tier brushless motor specialists with firmware engineering depth but limited geographic certification footprint. Watch IATA lithium-ion shipping rule enforcement as inflection indicator for air freight-dependent aftermarket battery pack economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Captive lithium iron phosphate supply insulates Robert Bosch GmbH from Chinese spot volatility. |
| Brushless Motor Firmware Development | Talent scarcity in motor control engineering delays next-generation platform launches across specialized manufacturers. |
| Bluetooth-Enabled Fleet Management Systems | Techtronic Industries Co., Ltd. embeds subscription revenue into commercial contractor accounts. |
| India Manufacturing Footprint Expansion | PLI schemes in Gujarat attract assembly operations serving Middle East re-export markets. |
| Halogen-Free Thermoplastic Reformulation | REACH SVHC compliance in battery pack enclosures elevates European market entry costs. |
Research Approach
Coverage spans North America, Europe, Asia-Pacific, and India, with primary inputs from each region combined with secondary validation. Interviews with power tool OEM procurement directors, brushless motor firmware engineers, lithium-ion cell pack integrators, and commercial contractor fleet managers triangulate against customs records, MIIT battery safety filings, SEC 10-K disclosures, and EU Ecodesign implementation guidance. Bottom-up unit shipment modeling and top-down construction activity correlation establish volume anchors.
Rate-of-change decomposition separates volume growth from mix-shift toward higher-voltage platforms and brushless architectures across the analysis window. Segmentation dimensions include product type, power source chemistry, end-user procurement behavior, and application intensity. CAGRs derive from replacement cycle velocity in professional tiers and penetration rates in consumer segments. Forecast inputs incorporate housing start data, infrastructure deployment pipelines, and cell chemistry cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt semiconductor supply disruptions or accelerated EU carbon-border adjustment implementation. Assumptions reflect sustained lithium iron phosphate cost advantages and stable IATA shipping rule enforcement. Material deviation in battery transport regulations or REACH substance restriction timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Hydraulic Tools and Equipment Market
Tools
Global Construction Camera Market
Tools
Fatigue Testing Machine Market
Tools
Grabber Pole Market
Tools
Floor Saw Market
Tools
Multi Spindle Machines Market
Tools
Indexable Inserts Market
Tools
Level Floats Market
Tools
Shredder Blades Market
Tools
Garden Digging Tools Market
Tools
Screwdriver Market
Tools
Cutting Tools Market
Tools
Global Protractor Market
Tools
Turning Centers Market
Tools
Wood Floor Grinding Machine Market
Tools
Rotary Knife Cutters Market