
 Global Woodworking Machinery Market | 2026-2036
Global Woodworking Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Woodworking Machinery Market Foresight
Aftermarket service revenue is fragmenting across distributed dealer networks and direct-to-factory digital channels. Homag Group leverages its global service infrastructure to capture recurring maintenance contracts. SCM Group competes through specialized technical training programs for regional technicians. Biesse Group anchors its aftermarket position with predictive diagnostics integrated into CNC control systems.
Woodworking machinery encompasses powered equipment designed to cut, shape, finish, and assemble wood-based materials using mechanical force, thermal processes, or abrasive action, typically operating at spindle speeds between 3,000 and 24,000 RPM depending on material density and cutting depth. CNC machining technology leads equipment investment as furniture manufacturers pursue batch-size-one production flexibility, while laser cutting machines represent the fastest-growing product category driven by composite panel processing demand in architectural applications. Servo motor systems command premium positioning due to energy recovery capabilities and precision repeatability within 0.01 millimeters.
EU CE marking and Machinery Directive 2006/42/EC mandate emergency stop functionality and noise emission limits for equipment sold across member states, while China's GB standards and MIIT technical regulations enforce domestic safety certification for imported machinery. The US OSHA lockout/tagout requirements and EPA wood dust exposure limits shape facility upgrade cycles. Stakeholders must monitor evolving carbon border adjustments and embodied carbon disclosure rules that will reshape supplier qualification criteria and capital allocation priorities.
Market Dynamics
Furniture manufacturers are compressing batch sizes toward single-unit production, forcing capital equipment buyers to prioritize rapid changeover capability over raw throughput metrics. This demand compression is reshaping supplier R&D priorities and aftermarket service architectures.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon refrigerants in industrial cooling systems accelerates replacement cycles for thermal process equipment in German and Italian panel processing plants.
- Architectural millwork demand:Commercial interior fit-out projects in China specify laser-cut composite panels for acoustic and fire-rated wall systems, pulling specialized cutting machinery investment.
- Servo motor energy recovery:Regenerative braking systems in CNC routers cut facility electricity consumption, satisfying corporate carbon reduction mandates while lowering operating cost exposure.
Market Restraints
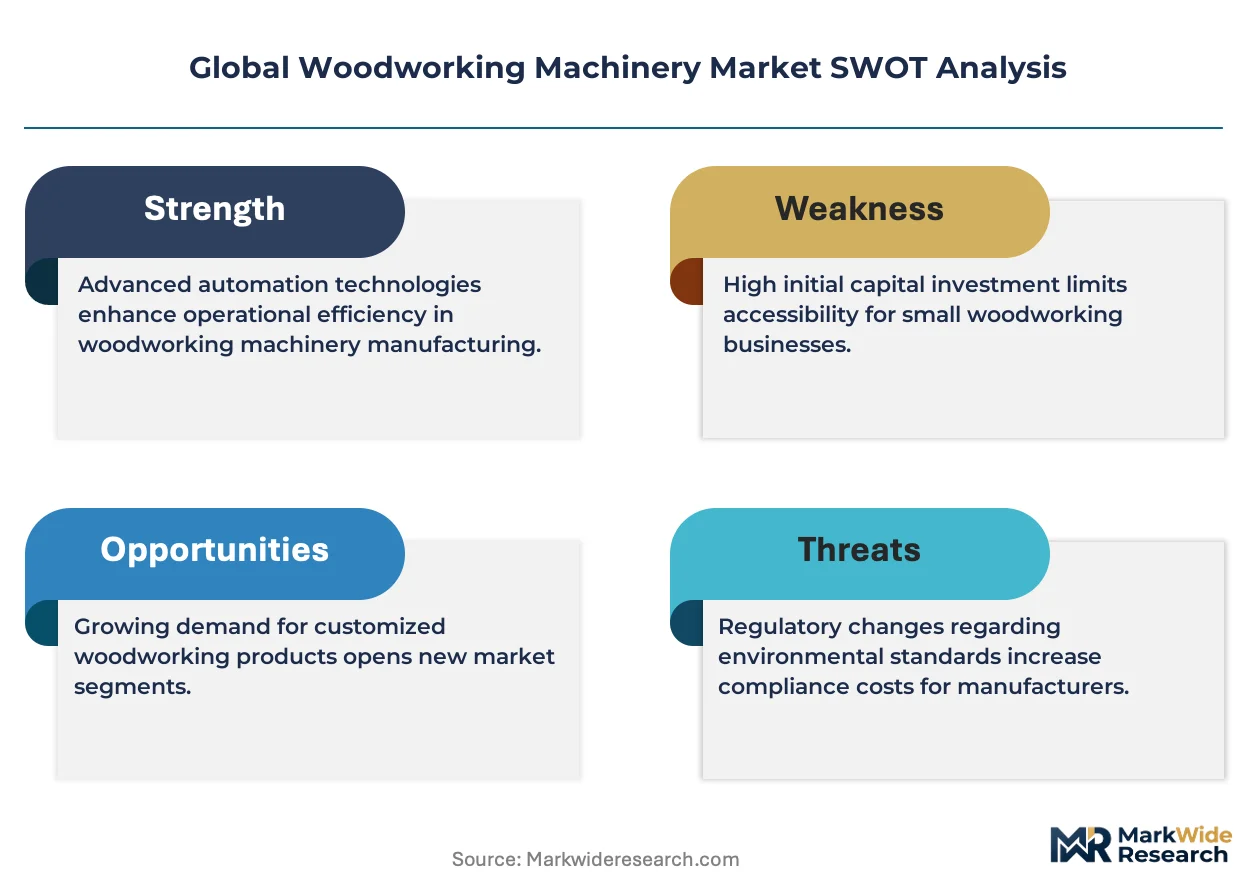
- Steel and aluminum input volatility:Machine frame and precision casting costs fluctuate with commodity index movements, compressing OEM margin predictability on fixed-price contracts.
- Controller chipset concentration:Industrial motion control semiconductors source from a narrow Taiwan and South Korea supplier base, creating single-point vulnerability for European and North American builders.
- Manual sanding substitution:Robotic surface finishing systems displace operator-heavy processes in high-volume furniture plants, slowing greenfield machinery orders for conventional wide-belt equipment.
Strategic Opportunities
- Vietnam and Indonesia manufacturing:Export-oriented wood product factories in Southeast Asia lack automated cutting density, creating first-mover advantage for predictive maintenance service providers.
- US Inflation Reduction Act:Domestic manufacturing tax credits for capital equipment purchases incentivize reshoring of furniture production from Asian contract manufacturers.
- 5G-enabled edge diagnostics:Real-time vibration analysis and tool-wear prediction converge with low-latency connectivity, enabling subscription-based uptime guarantees that displace transactional spare parts revenue.
Industry Challenges
- Mechatronics technician scarcity:Maintenance organizations struggle to recruit operators fluent in both mechanical alignment and PLC troubleshooting, extending mean time to repair.
- CE marking documentation burden:Machinery Directive 2006/42/EC conformity assessment timelines stretch 8-14 months for novel control architectures, delaying product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Woodworking Machinery Market |
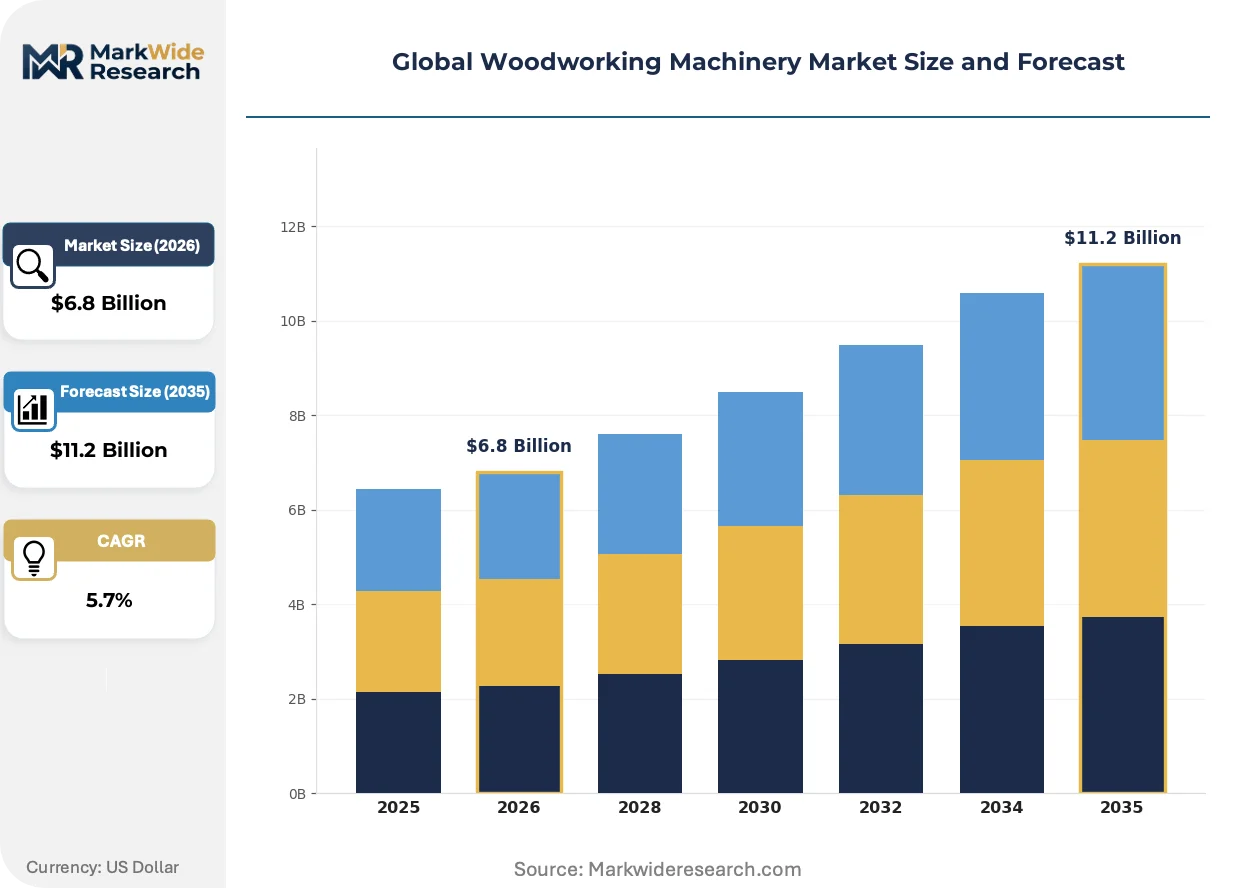
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saws, Sanders, Routers, Planers, Drilling Machines, Laser Cutting Machines Technology: CNC Machining, Pneumatic, Hydraulic, Servo Motor, Laser, Manual Application: Furniture Manufacturing, Shipbuilding, Construction Work, Musical Instruments, Cabinet Making, Model Building End User Industry: Woodworking Workshops, Architectural Firms, Craftsmanship Studios, Educational Institutions |
| Companies Covered | Homag Group, SCM Group, Biesse Group, Weinig Group, IMA Schelling Group, HOLYTEK Industrial Corp., Dürr Group, Felder Group, Holz-Her, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Woodworking Machinery Market Shifts & Advancements
Digital thread integration is collapsing the boundary between design software and shop-floor execution, compressing the traditional CAD-to-cut workflow from hours to minutes. This convergence demands new supplier competencies in software architecture and data interoperability.
Batch-size-one production software is collapsing the economic viability of dedicated single-purpose machines. Furniture manufacturers in Germany and the United States deploy parametric nesting algorithms that generate unique cutting patterns per order without manual programming intervention. The technology enables micro-factories to compete on customization speed previously reserved for mass producers.
EU CE marking and Machinery Directive 2006/42/EC now mandate integrated safety-rated monitored stops for collaborative robot installations. Woodworking OEMs redesign machine guarding architectures to accommodate human-robot coexistence in sanding and material handling stations. Italian and Spanish equipment builders face compressed certification timelines as notified bodies queue deep with industrial automation submissions.
Aftermarket service unbundling is fragmenting traditional dealer revenue pools. North American furniture manufacturers now procure spare parts through direct manufacturer portals while sourcing installation labor from independent technician networks. This disintermediation pressures regional distributors to develop proprietary technical training certifications as defensive differentiation.
Global Woodworking Machinery Market Segmentation
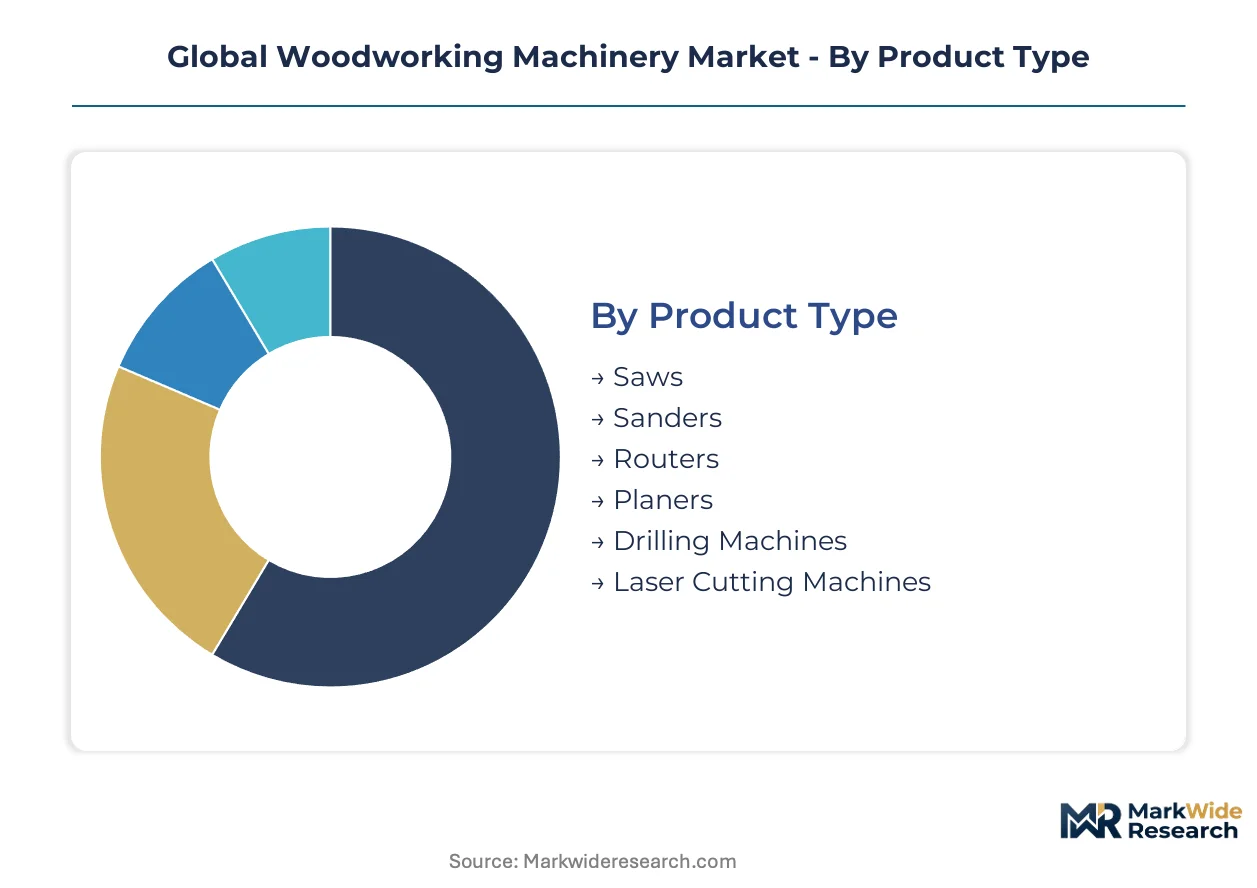
Segmentation reveals divergent service intensity across equipment categories. CNC systems demand predictive maintenance contracts while manual tools rely on transactional spare parts. Procurement patterns cluster by production scale rather than end-use vertical.
Product Type:
After-sales service intensity varies sharply by mechanical complexity and control system integration.
- Saws:Circular and band saw configurations dominate volume installations in panel processing plants. Demand concentrates in German and Italian manufacturers upgrading to servo-driven blade positioning for reduced setup waste.
- Sanders:Wide-belt and orbital sanding systems incorporate vacuum dust extraction and automatic abrasive belt changers. North American furniture plants deploy robotic sanding cells to displace manual finishing labor.
- Routers:Spindle-based cutting systems with tool magazine automation serve high-mix production environments.
- Planers:Thicknessing and surfacing equipment maintains steady replacement cycles in hardwood mills.
- Drilling Machines:Multi-spindle boring centers support cabinet manufacturing batch production.
- Laser Cutting Machines:CO2 and fiber laser systems process composite panels for acoustic wall systems. Chinese architectural millwork specifications are climbing the fastest for specialized cutting machinery investment.
Saws hold the largest share; momentum sits with laser cutting machines.
Technology:
Capital allocation splits between precision automation and cost-optimized mechanical systems.
- CNC Machining:Computer-numerical control routers and machining centers enable batch-size-one production flexibility. German furniture manufacturers deploy parametric nesting software to generate unique cutting patterns without manual programming.
- Servo Motor:Regenerative braking systems recover energy during deceleration cycles, cutting facility electricity consumption. Corporate carbon reduction mandates in the United States accelerate premium positioning for energy-recovery equipped machines.
- Pneumatic:Compressed air actuation remains cost-effective for clamping and material handling functions.
- Hydraulic:High-force pressing and veneering applications maintain installed base in plywood manufacturing.
- Laser:Thermal cutting processes achieve edge quality standards for fire-rated architectural panels.
- Manual:Operator-controlled equipment persists in craftsmanship studios and educational training facilities.
CNC machining commands the dominant investment flow; servo motor systems are expanding most quickly on energy efficiency mandates.
Application:
End-use requirements dictate automation depth and changeover speed specifications.
- Furniture Manufacturing:Residential and commercial producers compress batch sizes toward single-unit production. United States manufacturers prioritize rapid changeover capability over raw throughput metrics.
- Construction Work:Structural timber processing and prefabricated building components require heavy-duty material handling integration. Chinese infrastructure investment pulls specialized cutting machinery for engineered wood products.
- Shipbuilding:Marine-grade plywood and interior fit-out applications demand moisture-resistant material processing.
- Musical Instruments:Precision carving and acoustic optimization require specialized spindle control.
- Cabinet Making:Frame and panel construction systems support kitchen and storage product lines.
- Model Building:Prototype and architectural scale model production utilizes compact machining centers.
Furniture manufacturing absorbs the largest equipment volume; construction work is gaining share fastest on prefabrication trends.
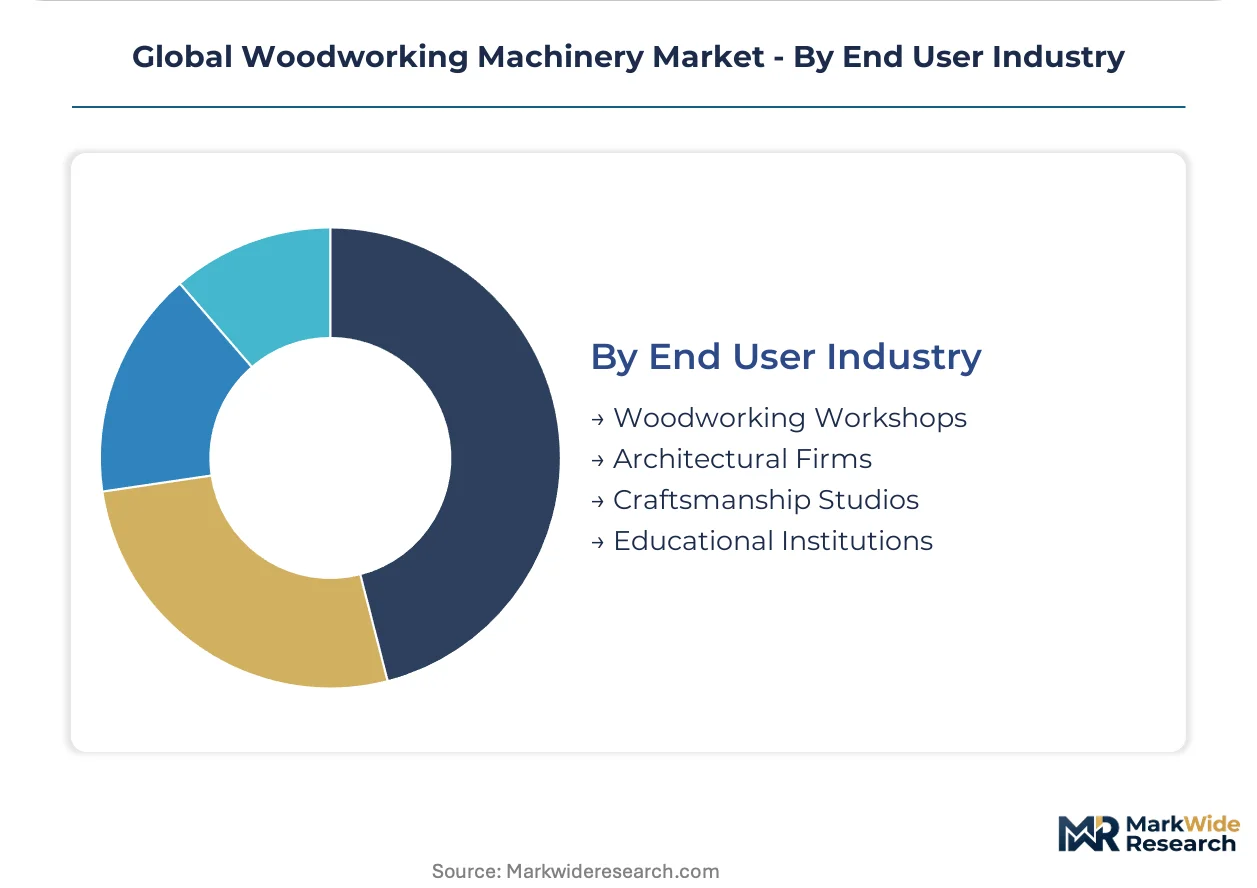
End User Industry:
Customer scale determines procurement channel preference and service contract penetration.
- Woodworking Workshops:Independent production facilities combine manual and automated equipment. German and Italian clusters concentrate demand for mid-range CNC systems with dealer service coverage.
- Architectural Firms:Design practices internalize prototyping capability through compact machining centers. United States commercial interior specialists specify laser-cut composite panels for acoustic installations.
- Craftsmanship Studios:Artisan producers maintain manual tool preferences with selective automation upgrades.
- Educational Institutions:Vocational training programs require safety-certified equipment with curriculum integration support.
Woodworking workshops represent the largest customer base; architectural firms are climbing fastest on in-house fabrication adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Italy demonstrate low price elasticity for servo-driven precision equipment, while Vietnamese and Indonesian manufacturers remain highly sensitive to capital expenditure thresholds. This divergence shapes regional supplier strategies and service model economics.
Germany
Furniture manufacturers in Baden-Württemberg and North Rhine-Westphalia deploy parametric nesting software for batch-size-one production flexibility. The EU F-Gas Regulation accelerates thermal process equipment replacement cycles in panel processing plants. Stuttgart's manufacturing cluster concentrates demand for energy-recovery equipped CNC systems with predictive maintenance contracts.
China
Architectural millwork specifications for acoustic and fire-rated wall systems pull specialized laser cutting machinery investment. MIIT technical regulations and GB standards enforce domestic safety certification for imported machinery. Yangtze River Delta fabricators in Shanghai and Suzhou expand automated cutting density for composite panel processing.
United States
Domestic manufacturers prioritize rapid changeover capability over raw throughput metrics for residential furniture production. OSHA lockout/tagout requirements and EPA wood dust exposure limits shape facility upgrade cycles. Southeast woodworking clusters in North Carolina and Virginia leverage Inflation Reduction Act tax credits for capital equipment reshoring.
Italy
Panel processing plants in Emilia-Romagna and Veneto upgrade to servo-driven blade positioning systems for reduced setup waste. Machinery Directive 2006/42/EC conformity assessment timelines compress product launch windows for novel control architectures. Bologna's equipment builders face deep queues at notified bodies for collaborative robot safety certifications.
Vietnam
Export-oriented wood product factories lack automated cutting density, creating first-mover advantage for predictive maintenance service providers. The country's national industrial standards authority enforces equipment safety protocols for imported machinery. Ho Chi Minh City and Binh Duong Province manufacturing zones attract CNC router investment from furniture contract manufacturers.
Global Woodworking Machinery Market Competitive Landscape
Capability concentration sits with European precision-engineering specialists; scale advantage sits with diversified industrial conglomerates. The vendor base separates into three functional tiers: full-lifecycle service integrators, component-specialist boutiques, and mass-market fabricators. Two dominant competitive moves define current positioning: predictive diagnostics integration into control architectures, and direct-to-factory digital channel development that disintermediates traditional dealer networks.
Within the European precision tier, Homag Group and SCM Group exemplify divergent service architecture strategies. Homag leverages global infrastructure for recurring maintenance contract capture, while SCM competes through specialized technical training programs for regional technician networks. Biesse Group anchors the predictive diagnostics segment with CNC-integrated vibration analysis capabilities.
| Leading Market Players |
|---|
| Homag Group |
| SCM Group |
| Biesse Group |
| Weinig Group |
| IMA Schelling Group |
| HOLYTEK Industrial Corp. |
| Dürr Group |
| Felder Group |
| Holz-Her |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's container rate volatility compresses margin buffers for European OEMs sourcing castings from Chinese foundries while amplifying price differentiation between servo-equipped precision systems and pneumatic alternatives. This freight-cost dynamic concentrates supply power with diversified manufacturers maintaining regional fabrication footprints and forces price-tier stratification based on energy-recovery certification rather than throughput specifications alone.
Pricing Analysis
Aftermarket service contracts generate lifetime value multiples exceeding original equipment sales for CNC machining centers. Three-tier pricing structure across premium, standard, and economy levels reflects servo motor energy-recovery certification, predictive diagnostics integration, and regional service network density. Cost compression in the economy tier intensifies because dealer networks disintermediate for spare parts procurement. Large-scale furniture manufacturers in Germany demonstrate lowest price sensitivity; Vietnamese export factories exhibit highest elasticity to capital expenditure thresholds.
Supply Chain Analysis
Supplier-financing facilities with 180-day extended terms have become standard for Taiwanese motion-control semiconductor vendors serving European machine builders. Precision casting supply concentrates in Germany, Italy, and China; controller chipsets draw from Taiwan and South Korea. Steel and aluminum frame materials hinge on commodity index movements. Single-source vulnerability sits with industrial motion-control semiconductors. Distribution runs through authorized dealer networks undergoing digital disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The woodworking machinery sector enters a high-growth disruption phase as EU F-Gas Regulation mandates accelerate thermal equipment replacement cycles and batch-size-one software collapses dedicated machine economics.
For Market Incumbents: Build predictive maintenance moats through CNC-integrated vibration analysis and edge diagnostics subscriptions. Deepen backward integration into servo motor production to capture energy-recovery premium positioning. Counter emerging 5G-enabled service entrants by consolidating regional technician certification programs under proprietary training architectures.
For New Entrants and Emerging Players: Vietnam's automated cutting density gap offers first-mover positioning for subscription-based uptime guarantee providers. Indonesia's export-oriented wood product factories lack predictive maintenance penetration. Target architectural millwork applications in China specifying laser-cut composite panels. Lead with direct-to-factory digital spare parts portals that bypass established dealer networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-engineering specialists with software-defined service architectures over mass-market fabricators. The five-to-ten year viability window rewards vendors controlling both parametric nesting algorithms and predictive diagnostics hardware. Target acquisition archetypes include CNC control system developers with integrated safety-rated monitored stop capabilities. Monitor CE marking conformity assessment queue depths at Italian notified bodies as inflection indicator for product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Diagnostics Integration | Biesse Group's CNC-embedded vibration analysis enables subscription-based uptime guarantees displacing transactional parts revenue. |
| Direct-to-Factory Digital Channel | Homag Group's manufacturer portal procurement captures spare parts volume escaping traditional dealer networks. |
| Energy-Recovery Servo Motor Deployment | Corporate carbon reduction mandates in the United States accelerate premium positioning for regenerative braking equipped machines. |
| Parametric Nesting Software Development | German furniture manufacturers deploy unique cutting pattern generation without manual programming intervention. |
| Southeast Asia Service Infrastructure Buildout | Vietnamese and Indonesian manufacturing zones lack automated cutting density creating predictive maintenance white space. |
Research Methodology
Cross-validation between OEM procurement disclosures and customs trade data anchors the qualitative findings across the analysis window. Primary interviews with maintenance directors, plant engineers, aftermarket service heads, and CNC control system architects combine with secondary validation through EU Machinery Directive filings, SEC 10-K equipment capital expenditure disclosures, MIIT technical regulation submissions, and Yangtze River Delta industrial cluster production statistics. Bottom-up equipment shipment aggregation and top-down manufacturing value-added estimates triangulate market sizing.
Calibration against historical replacement cycle patterns and regulatory phase-in schedules shapes the projection framework across product type, technology tier, application vertical, and end-user scale dimensions. CAGRs derive from segmented growth rate reconciliation with macroeconomic manufacturing investment indices. Forecast inputs incorporate EU F-Gas Regulation compliance timelines, US Inflation Reduction Act capital equipment credit utilization rates, and 5G infrastructure deployment curves enabling edge diagnostics.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified industrial conglomerates would shift outcomes. Macroeconomic deviation in steel and aluminum commodity indices, regulatory acceleration in carbon border adjustments, or technological breakthrough in collaborative robot safety architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Crane Motors Market
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market
Construction Equipment and Machinery
Benelux Metal Fabrication Equipment Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market