
 India Lathe Machines Market | 2026-2036
India Lathe Machines Market Size, Share, and Industry Trends Forecast 2026-2036
India Lathe Machines Market Insights
Dealer-direct hybrid channels is tilting toward direct manufacturer engagement with large automotive OEMs and aerospace contractors. HMT Machine Tools Limited leverages its government-backed heritage to sustain institutional procurement relationships across defense and public sector undertakings. Ace Designers Ltd. anchors the southern market with CNC specialization for precision component machining. Jyoti CNC Automation Ltd. competes aggressively on electric and hybrid technology configurations for energy-efficient operations.
Lathe machines are rotating workpiece machining tools that employ single-point cutting tools to remove material along horizontal or vertical axes, with spindle speeds typically ranging from several hundred to several thousand RPM depending on workpiece diameter and material. These machines serve primary industrial purposes in turning, facing, threading, and grooving operations for cylindrical components across metalworking industries. CNC Lathes command the premium tier of the product spectrum due to programmable automation and repeatability demands from aerospace and medical device end users. Manual Lathes retain relevance in maintenance workshops and small-batch general engineering applications where capital constraints limit automation adoption. Multitasking Lathes represent the fastest-growing configuration as manufacturers pursue single-setup completion of complex geometries to reduce cycle times.
BIS machinery safety standards and CEA electrical equipment regulations shape product certification requirements for domestic sale and import substitution eligibility under PLI scheme incentives. CDSCO quality benchmarks for medical device manufacturing indirectly drive precision lathe specifications for orthopedic implant and surgical instrument producers. State-level industrial policies in Maharashtra and Gujarat supplement national frameworks with capital subsidy-linked machinery upgrade mandates. Stakeholders must monitor evolving PLI scheme disbursement timelines and BIS harmonization with ISO standards to calibrate capacity expansion and technology refresh cycles.
Market Dynamics
Electric drivetrain manufacturing in Maharashtra and Gujarat is compressing setup times and forcing multitasking lathe adoption across tier-one automotive supply chains. Tier suppliers must now complete complex shaft and rotor geometries in single clamping cycles to match OEM takt times.
Growth Catalysts
- PLI Scheme Incentives:The Production Linked Incentive scheme for specialty steel and auto components subsidizes domestic machinery procurement, accelerating capital expenditure timelines for precision machining capacity.
- BIS Harmonization:Alignment of Indian machine tool safety standards with ISO frameworks reduces export friction for domestic manufacturers targeting Middle Eastern and African markets.
- Rajkot Cluster Modernization:The Gujarat machine tool hub is consolidating from fragmented manual lathe production toward CNC-equipped job shops serving aerospace subcontracting.
Market Restraints
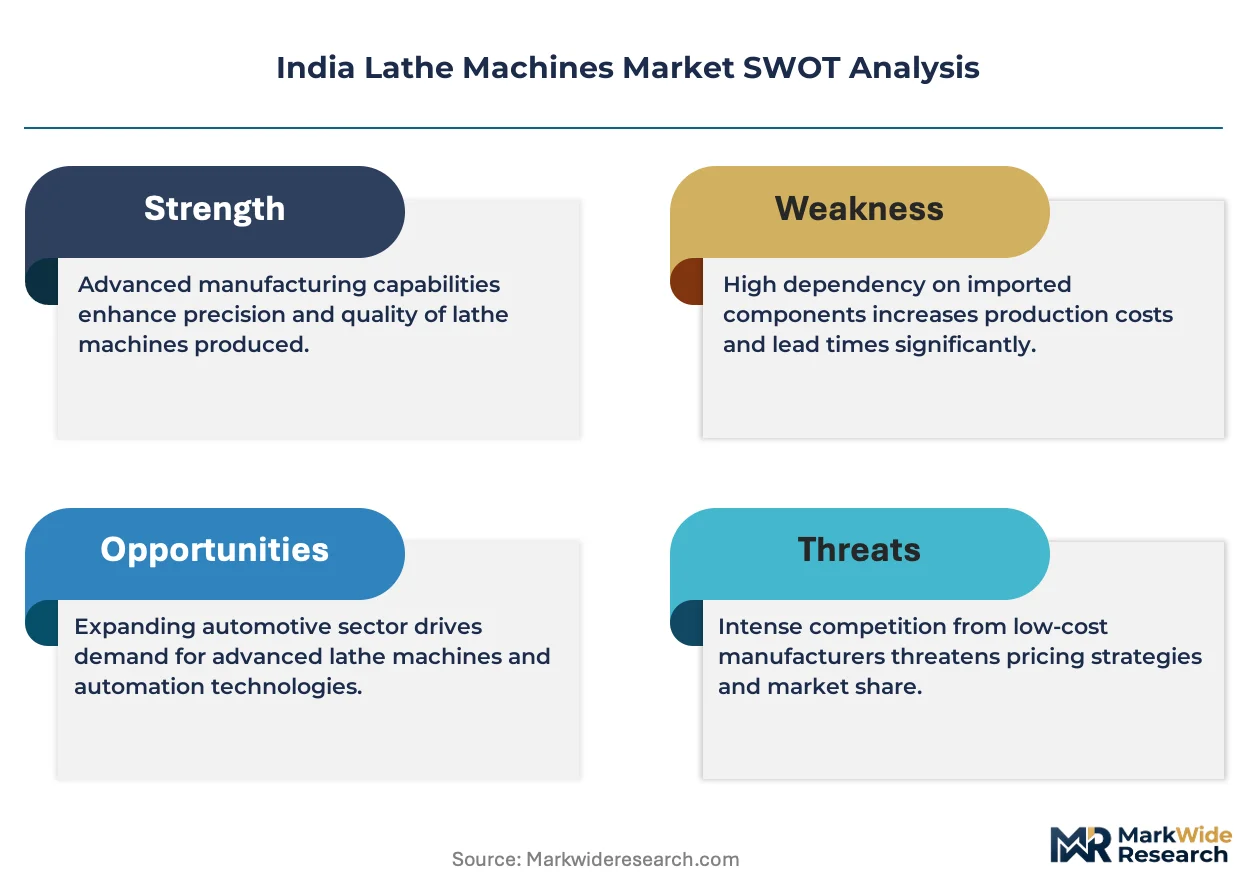
- Imported Control System Dependency:Fanuc and Siemens CNC controllers constitute the majority of installed bases, exposing margins to yen and euro volatility and licensing restrictions.
- Scrap Steel Price Volatility:Cast iron bed and spindle material costs fluctuate with global ferrous scrap indices, compressing margin predictability for mid-tier domestic builders.
- CEA Electrical Certification Delays:Central Electricity Authority compliance timelines for servo motor and drive systems extend product launch cycles by four to eight months.
Strategic Opportunities
- Medical Device Orthopedics:CDSCO-mandated quality benchmarks for implant manufacturing are creating specification pull for sub-micron repeatability lathes in titanium and cobalt-chrome.
- Defense Indigenization:Ordnance Factory Board restructuring and private sector participation in artillery and armored vehicle component supply is opening institutional procurement channels.
- Hybrid Machine Convergence:Integration of additive deposition heads with subtractive turning platforms enables repair and remanufacturing applications for worn industrial shafts.
Industry Challenges
- CNC Programming Talent Scarcity:G-code and CAM software proficiency gaps at the operator level limit utilization rates of installed multitasking centers in Pune and Bengaluru clusters.
- BIS Certification Backlogs:Machinery safety testing queue lengths at accredited laboratories delay product launches and contract finalizations for export-bound builders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Lathe Machines Market |
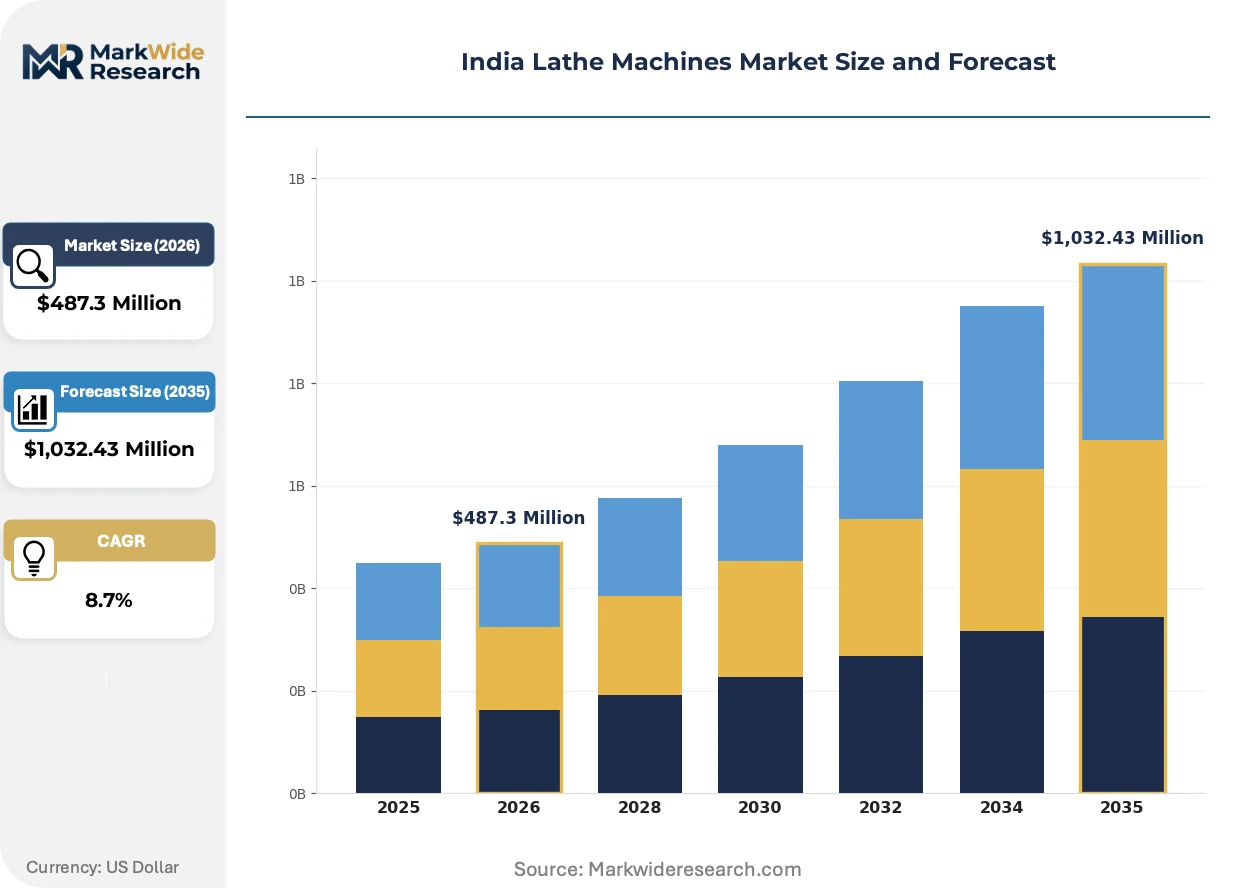
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Lathes, Manual Lathes, Multitasking Lathes, Vertical Lathes End User: Aerospace, Automotive OEMs, General Engineering, Medical Devices Technology: Manual, CNC, Hybrid, Electric Application: Prototype Manufacturing, Batch Production, Component Machining, Maintenance |
| Companies Covered | Bhavya Machine Tools, Esskay Lathe & Machine Tools, HMT Machine Tools Limited, Ace Designers Ltd., Bharat Fritz Werner Ltd., Batliboi Ltd., Lakshmi Machine Works Limited, Rajkot Machine Tools, Jyoti CNC Automation Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Lathe Machines Market Trends and Innovations
Automation architecture is collapsing the boundary between roughing and finishing operations, with live tooling and Y-axis milling eliminating secondary machining stations. This convergence is redrawing floor space economics and labor deployment models.
Multitasking lathes with integrated bar feeders and robotic part handling are collapsing the traditional segregation of turning centers from machining centers. Tier-one automotive suppliers in Pune are adopting these configurations to halve work-in-process inventory. The structural result is compressed capital intensity per finished component across high-volume electric motor shaft production.
BIS machinery safety standards are tightening guarding and interlock requirements for automatic tool changers and spindle enclosures. Domestic builders must redesign legacy platforms to achieve compliance, adding engineering cost but creating differentiation against uncertified imports. Medical device manufacturers in Gujarat are prioritizing BIS-certified suppliers to preempt CDSCO audit findings.
Direct manufacturer engagement is displacing dealer networks for large automotive and aerospace contracts in Maharashtra and Karnataka. OEMs are consolidating supplier panels and demanding embedded application engineering support. This pattern is most pronounced in Bengaluru, where defense contractors and space research institutions specify turnkey automation cells rather than standalone machines.
India Lathe Machines Market Segmentation
Lathe machine procurement patterns in India diverge sharply across precision requirements, automation levels, and end-use certification demands. Understanding these fault lines enables suppliers to align R&D roadmaps with subsidy eligibility and buyer capital cycles.
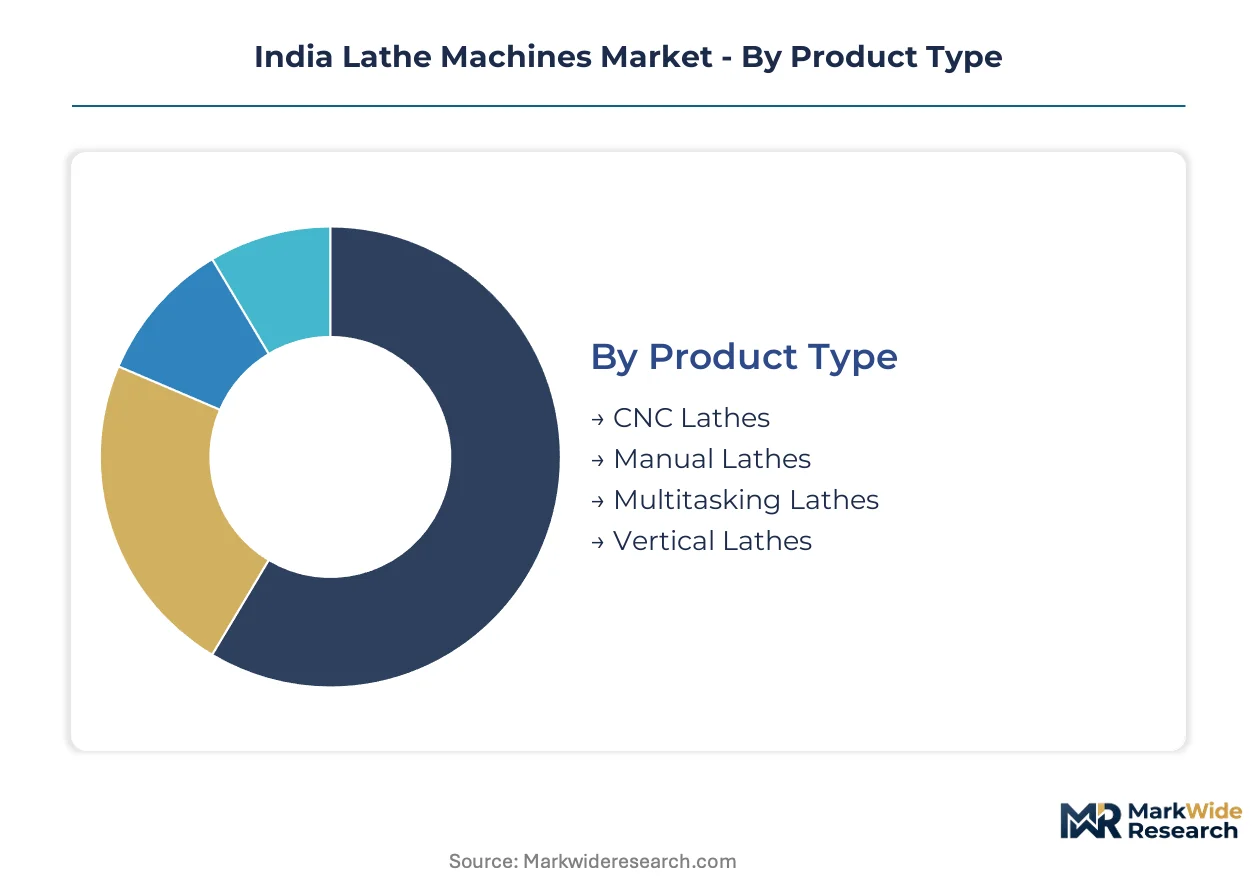
Product Type:
Cost tier stratification separates premium programmable systems from entry-level mechanical platforms, with distinct margin profiles and replacement cadences.
- CNC Lathes:Programmable automation platforms with servo-driven axes and closed-loop positioning deliver sub-micron repeatability for aerospace and medical device specifications. Demand concentrates in Bengaluru and Pune defense corridors where BIS-certified suppliers qualify for PLI-linked procurement tenders.
- Multitasking Lathes:Integrated milling and turning capabilities collapse multiple setups into single clamping cycles. Maharashtra electric drivetrain suppliers are adopting these configurations to match OEM takt time compression mandates for rotor shaft geometries.
- Manual Lathes:Mechanical feed and hand-operated carriage systems serve maintenance workshops and vocational training institutes. Rajkot job shops retain these for low-volume repair work.
- Vertical Lathes:Face plate orientation accommodates large-diameter workpieces such as turbine casings and bearing races. Heavy engineering clusters in Gujarat deploy these for power generation component machining.
CNC Lathes commands the established base. The steepest expansion runs through Multitasking Lathes.
End User:
Application maturity varies across certification intensity, volume predictability, and technical specification rigor.
- Automotive OEMs:Tier-one suppliers in Maharashtra and Gujarat drive precision machining capacity expansion for electric drivetrain components. BIS machinery safety compliance is mandatory for PLI scheme eligibility.
- Medical Devices:CDSCO-mandated quality benchmarks for orthopedic implants and surgical instruments demand sub-micron repeatability in titanium and cobalt-chrome. Gujarat manufacturers prioritize BIS-certified lathe suppliers to preempt audit findings.
- Aerospace:Defense contractors and space research institutions in Bengaluru specify turnkey automation cells with embedded application engineering support.
- General Engineering:Fragmented job shops across Rajkot and Coimbatore serve maintenance and small-batch fabrication with mixed manual and CNC capacity.
Automotive OEMs anchors volume demand. Medical Devices is climbing the fastest on specification premiumization.
Technology:
Automation architecture determines energy efficiency, operator skill requirements, and controller licensing exposure.
- CNC:Computer-numerical control with G-code programmability dominates precision production. Fanuc and Siemens controllers constitute the majority of installed bases, exposing margins to yen and euro volatility.
- Electric:Servo motor and drive systems replace hydraulic actuation for energy efficiency and positioning accuracy. CEA electrical certification timelines extend product launch cycles by four to eight months.
- Hybrid:Additive deposition heads integrated with subtractive turning platforms enable repair and remanufacturing of worn industrial shafts.
- Manual:Hand-operated feed mechanisms retain relevance where capital constraints limit automation adoption and batch sizes remain irregular.
CNC technology holds the dominant share. Electric configurations are gaining share fastest on energy efficiency mandates.
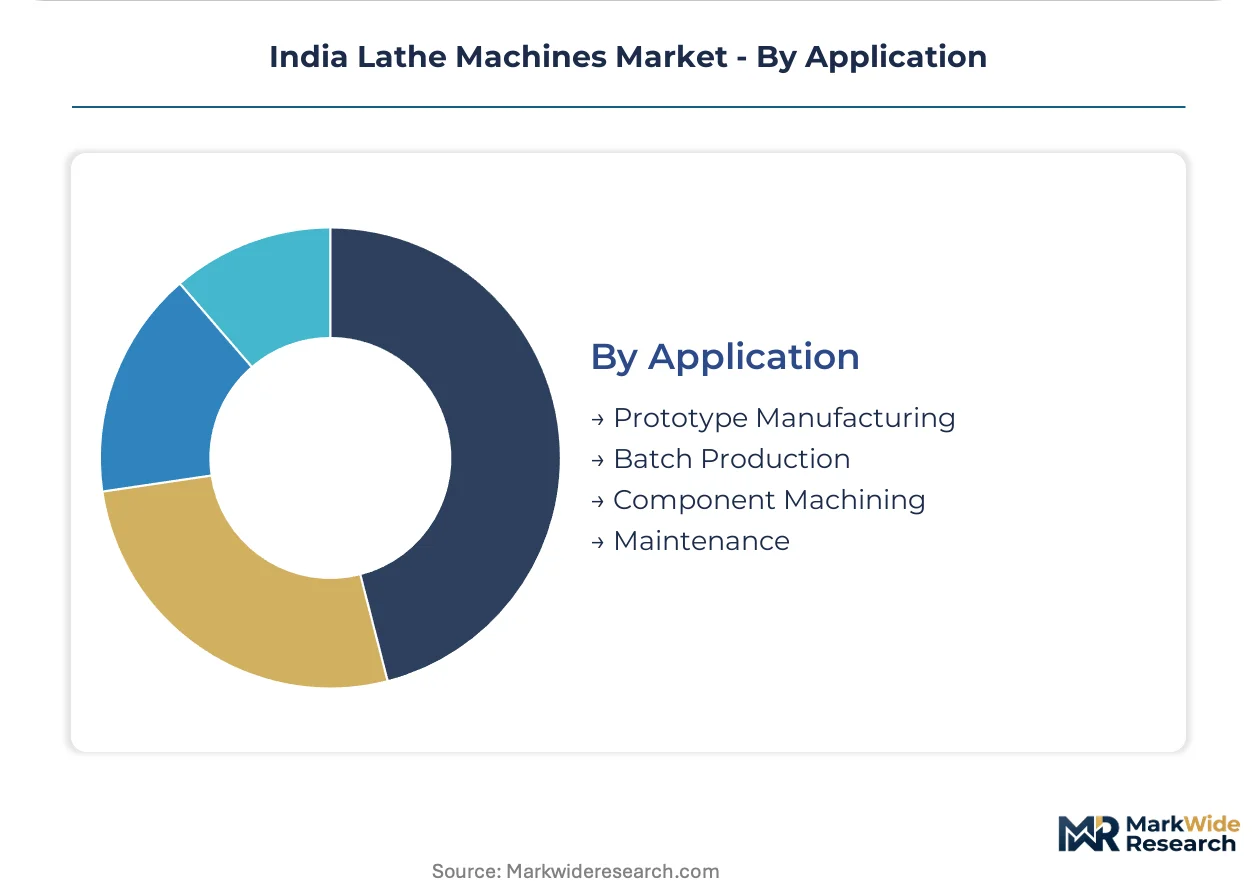
Application:
Volume predictability and setup frequency separate continuous production from intermittent, specification-driven work.
- Component Machining:Dedicated production of cylindrical parts for assembly into larger systems. Pune and Bengaluru automotive suppliers deploy multitasking lathes to halve work-in-process inventory.
- Batch Production:Medium-volume runs with periodic changeovers require quick tooling and program retrieval. General engineering job shops prioritize this flexibility.
- Prototype Manufacturing:Low-volume, high-variety work demands rapid setup and programming iteration. Aerospace development centers in Bengaluru drive specification pull.
- Maintenance:Repair and remanufacturing of worn shafts and housings. Manual lathes retain relevance here for one-off geometries.
Component Machining commands the revenue base. Prototype Manufacturing shows the steepest expansion trajectory on defense and space program acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands premium pricing for precision-grade CNC systems, while Gujarat manual-lathe producers compete on entry-level cost structures. This asymmetry reflects divergent industrial maturity and subsidy capture rates across western Indian manufacturing belts.
Maharashtra
Automotive OEMs in Pune and Nashik drive multitasking lathe procurement for electric drivetrain shaft geometries. PLI scheme disbursements for auto component manufacturing accelerate capital expenditure timelines for tier-one suppliers. Aurangabad's defense aerospace corridor demands turnkey automation cells with embedded application engineering support.
Gujarat
Rajkot's machine tool hub consolidates from fragmented manual production toward CNC-equipped job shops serving aerospace subcontracting. State-level industrial policies supplement national frameworks with capital subsidy-linked machinery upgrade mandates. Ahmedabad and Vadodara process machinery builders source certified platforms to preempt BIS compliance delays.
Karnataka
Bengaluru's defense contractors and space research institutions specify sub-micron repeatability systems for titanium and cobalt-chrome component machining. CDSCO quality benchmarks for medical device manufacturing create specification pull for orthopedic implant producers. Mysuru and Tumkur satellite clusters absorb overflow demand from the capital's capacity constraints.
Tamil Nadu
Coimbatore's general engineering job shops deploy mixed manual and CNC capacity for maintenance and small-batch fabrication work. CEA electrical certification timelines for servo motor systems extend product launch cycles for regional builders. Hosur's automotive component suppliers modernize shop floors to match OEM takt time compression mandates.
Telangana
Hyderabad's defense public sector undertakings sustain institutional procurement relationships with government-backed machinery suppliers. BIS harmonization with ISO standards reduces export friction for domestic manufacturers targeting Middle Eastern markets. Warangal's emerging industrial corridor attracts precision machining investments from tier-two automotive suppliers.
India Lathe Machines Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in controller licensing and spindle supply. The vendor base stratifies across government-backed heritage institutions, southern CNC specialists, and western job-shop consolidators. Three archetypes dominate: legacy public sector suppliers with institutional procurement access, precision automation specialists serving medical and aerospace certification demands, and volume builders competing on electric and hybrid technology configurations. Competitive moves concentrate on direct manufacturer engagement displacement of dealer networks and embedded application engineering support for large automotive contracts.
Among government heritage suppliers, HMT Machine Tools Limited occupies a position exemplifying institutional procurement channel access across defense and public sector undertakings. Ace Designers Ltd. and Jyoti CNC Automation Ltd. represent the precision automation tier, with the former anchoring southern market CNC specialization and the latter competing on energy-efficient technology configurations. These three entities collectively illustrate the competitive structure's segmentation between subsidy-capturing legacy platforms and specification-driven private automation specialists.
| Leading Market Players |
|---|
| Bhavya Machine Tools |
| Esskay Lathe & Machine Tools |
| HMT Machine Tools Limited |
| Ace Designers Ltd. |
| Bharat Fritz Werner Ltd. |
| Batliboi Ltd. |
| Lakshmi Machine Works Limited |
| Rajkot Machine Tools |
| Jyoti CNC Automation Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Rajkot's manual lathe segment compresses margins for entry-tier builders while simultaneously elevating pricing power for BIS-certified CNC specialists in Pune and Bengaluru. This utilization asymmetry forces tier-two suppliers to absorb controller licensing costs or exit, reshaping procurement negotiations across Maharashtra's automotive corridors.
Pricing Analysis
Configured-to-order multitasking lathes command spreads exceeding standard CNC platforms by factors tied to axis complexity and automation bundling. Three-tier pricing structure across premium, standard, and economy levels segments on BIS certification grade and embedded application engineering support. Pricing pressure stems from yen-denominated Fanuc controller licensing exposing margins to currency volatility. Tier-one automotive OEMs in Gujarat exhibit lowest price sensitivity due to PLI-linked capital subsidy absorption, while Rajkot job shops resist premium tier migration.
Supply Chain Analysis
Extended payment terms from 90 to 180 days characterize supplier-financing arrangements for controller imports, straining working capital for domestic builders. Cast iron bed material draws from Indian foundry clusters in Kolhapur and Coimbatore, while servo motors and linear scales source from Germany, Japan, and Taiwan. Single-source vulnerability concentrates in Siemens and Fanuc CNC architectures, with CEA electrical certification timelines extending procurement cycles. Distribution runs through manufacturer-direct engagement for large automotive contracts, supplemented by regional dealer networks for general engineering accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against additive manufacturing substitution for shaft repair and remanufacturing applications, as hybrid deposition-turning platforms erode traditional lathe incumbency in maintenance verticals.
For Market Incumbents: Harden controller supply resilience through dual-source licensing negotiations with Siemens and domestic alternatives, reducing yen exposure. Deepen backward integration into cast iron spindle casting at Kolhapur facilities to buffer scrap steel volatility. Anchor PLI scheme eligibility through accelerated BIS certification investment, preempting compliance delays that disqualify competitors from Maharashtra automotive tenders.
For New Entrants and Emerging Players: Medical device orthopedics in Gujarat represents the most penetrable entry point, with CDSCO-mandated quality benchmarks creating specification pull for sub-micron repeatability platforms untapped by incumbent medical specialists. Defense indigenization channels through Ordnance Factory Board restructuring offer institutional procurement access with lower competitive density than automotive. Pursue embedded application engineering partnerships with Ahmedabad implant manufacturers as primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-premium play because BIS harmonization with ISO standards creates export-enabled domestic builders with defendable positioning in Middle Eastern and African markets. Target acquisition profile centers on southern CNC specialists with existing medical device supplier relationships and latent capacity for aerospace certification expansion. Monitor PLI scheme disbursement velocity as inflection signal for capital expenditure acceleration across tier-one automotive supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Controller Localization Partnership | Reduces yen exposure and CEA certification timelines for servo motor integration. |
| BIS Certification Fast-Track Investment | Unlocks PLI-linked procurement tenders from Maharashtra automotive OEMs. |
| Medical Device Supplier Qualification | Captures CDSCO-driven specification pull from Gujarat orthopedic implant manufacturers. |
| Additive-Subtractive Hybrid Platform Launch | Defends against remanufacturing substitution threat in industrial shaft repair verticals. |
| Defense PSU Institutional Channel Access | Secures long-dated procurement relationships through Ordnance Factory Board restructuring. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BIS machinery safety directives, CEA electrical equipment regulations, and PLI scheme disbursement records. Primary interviews engaged plant engineers at Pune and Bengaluru tier-one automotive suppliers, procurement leads at Gujarat medical device manufacturers, aftermarket service heads at Rajkot job shop consolidators, and OEM platform engineers specifying multitasking lathe configurations. Secondary validation drew from customs trade data on controller imports, CDSCO quality benchmark notifications, and state-level industrial policy filings from Maharashtra and Gujarat. Bottom-up capacity estimates from domestic builder production records triangulate against top-down demand aggregation from end-user capital expenditure disclosures.
Forecast inputs incorporate machine tool replacement cadences, PLI scheme subsidy capture rates, and electric drivetrain manufacturing capacity expansion timelines across the analysis window. Segmentation dimensions modeled include product type automation level, end-use certification intensity, technology controller architecture, and regional industrial cluster maturity. CAGRs derive from installed base growth projections adjusted for technology substitution effects and regulatory compliance-driven replacement cycles. Controller import dependency and scrap steel price volatility feed as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in rupee-yen-euro exchange rates or ferrous scrap indices would shift the trajectory. Forecasts reflect documented assumptions on BIS harmonization pace and PLI disbursement continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Global Woodworking Machinery Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Global Rebar Processing Equipment Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Concrete Block Making Machines Market