
 Wooden Pallets Market | 2026-2036
Wooden Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden Pallets Market Analytics
Southeast Asia is rewriting regional supply chain configurations as Vietnam and Indonesia expand softwood processing capacity for export-oriented pallet manufacturing. CHEP (Brambles Limited) leverages its pooled pallet network to dominate closed-loop logistics across European retail corridors. PalletOne Inc. anchors North American production through integrated sawmill-to-pallet operations in the southeastern United States. Cabka Group GmbH differentiates via hybrid plastic-wood composite designs that compete in pharmaceutical cold-chain applications.
Wooden pallets are load-bearing platforms constructed from hardwood or softwood lumber, typically assembled with nails or staples to ISO 6780 dimensional standards, designed for forklift handling and unitized cargo transport across intermodal networks. Stringer pallets retain cost leadership in high-volume food and beverage distribution where single-use economics prevail, while block pallets capture premium positioning in automated warehouse systems requiring four-way entry access. The logistics end-user segment sustains the deepest demand pool, though retail direct procurement is gaining traction as big-box operators internalize pallet management to reduce per-trip rental fees.
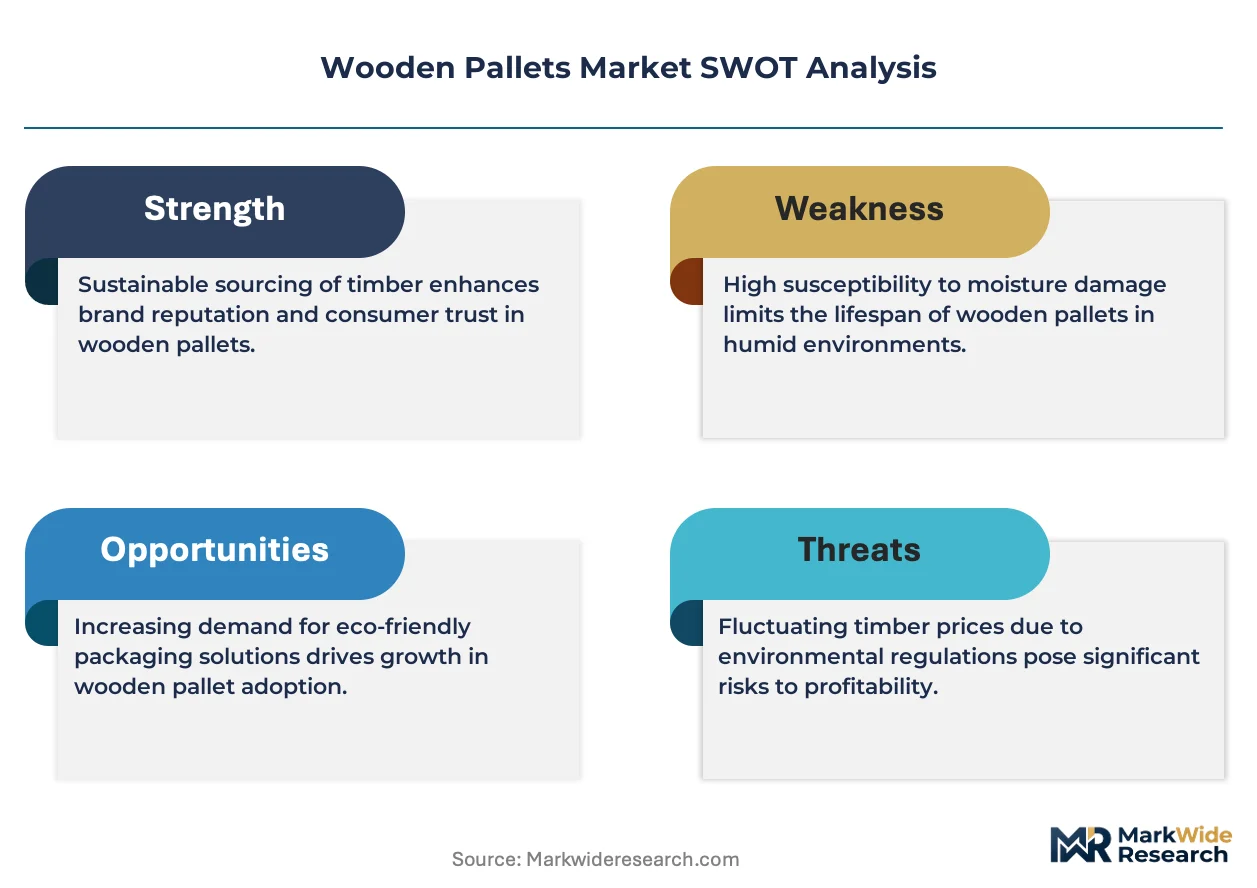
The European Union's Ecodesign for Sustainable Products Regulation and the U.S. EPA timber treatment standards are reshaping material certification requirements, compelling manufacturers to document heat-treatment compliance under ISPM 15 for cross-border shipments. China's GB/T 2934 pallet dimension standards and SAMR quality enforcement are synchronizing domestic production with export-market specifications. Stakeholders must monitor how carbon-border adjustment mechanisms alter the cost calculus between virgin timber, recycled lumber, and engineered wood substitutes before committing to long-term capacity investments.
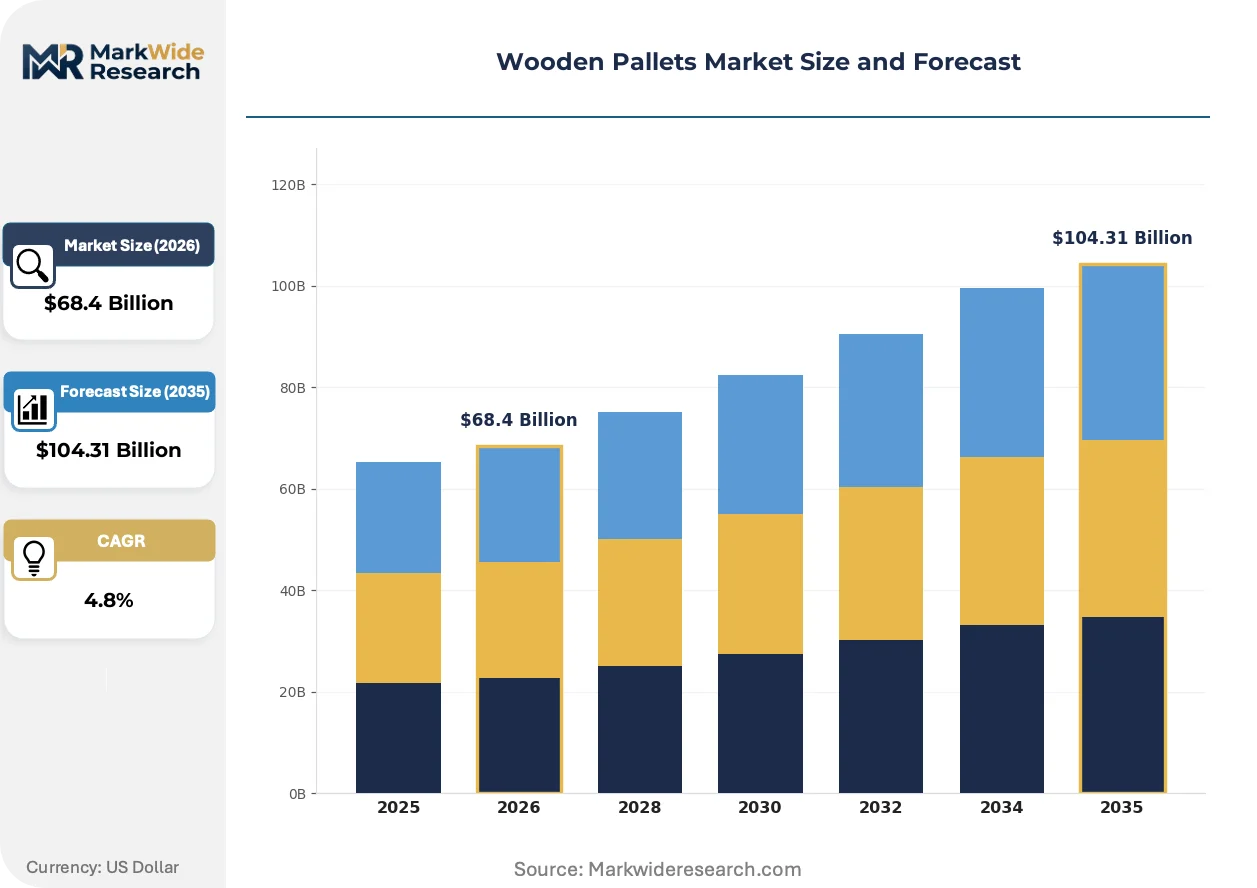
Market Dynamics
EU Green Deal timber traceability mandates and the U.S. EPA heat-treatment standards are compressing supply chains toward certified, documented sourcing while e-commerce logistics volumes pull capacity expansion across North American distribution networks.
Growth Catalysts
- E-commerce logistics volume:Third-party fulfillment networks in the United States are scaling pallet procurement to match same-day delivery density requirements.
- ISPM 15 compliance harmonization:Cross-border phytosanitary certification is standardizing export-ready pallet specifications, reducing customs friction for hardwood stringer producers.
- Automotive export corridors:Germany's manufacturing belt sustains high-volume block pallet consumption for chemical and vehicle component unitization.
Market Restraints
- Softwood lumber input volatility:Baltic and Nordic sawmill capacity constraints transmit price instability directly to pallet manufacturing cost structures.
- Plastic pallet substitution:Hygienic closed-loop systems in pharmaceutical cold chains are displacing wooden alternatives where moisture resistance commands premium positioning.
- EU Ecodesign documentation burden:Digital product passport requirements under the Sustainable Products Regulation extend compliance timelines and raise administrative overhead for SME producers.
Strategic Opportunities
- Vietnam-Indonesia processing expansion:Southeast Asian softwood capacity growth enables export-oriented pallet manufacturing for Asia-Pacific logistics networks.
- Carbon-border adjustment positioning:Documented heat-treatment and recycled-content certification creates differentiation advantage for EU-facing exporters ahead of full CBAM implementation.
- Retail direct procurement:Big-box operators internalizing pallet fleet management bypass rental intermediaries, opening volume contracts with integrated sawmill-to-pallet producers.
Industry Challenges
- ISPM 15 certification backlog:Treatment facility capacity constraints delay export readiness for small-batch manufacturers serving seasonal agricultural shippers.
- Legacy ERP integration:Timber traceability documentation systems require middleware development to synchronize with existing inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden Pallets Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $104.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Block Pallets, Stringer Pallets, Non-Wood Pallets, Heavy-Duty Pallets Application: Food & Beverage, Pharmaceuticals, Construction, Furniture End User: Retail, Logistics, Manufacturing, Warehousing Size: Standard, Custom, Euro Pallets, Lightweight |
| Companies Covered | Cabka Group GmbH, PECO Pallet, Inc., CHEP (Brambles Limited), PGS Group, Inka-Paletten, PalletOne Inc., Craemer GmbH, Kamps Pallets, Falkenhahn AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden Pallets Market Evolving Landscape
Digital tracking systems and composite material engineering are compressing traditional pallet lifecycle economics while regulatory documentation requirements reshape competitive capabilities.
RFID-embedded pallet tracking is virtualizing fleet visibility across closed-loop rental networks. Retail grocery distributors in Western Europe are deploying tagged block pallets at scale to eliminate manual inventory reconciliation. This virtualization is compressing asset utilization metrics and enabling dynamic repositioning algorithms that reduce empty-mile ratios.
REACH chemical restrictions and the EU F-Gas Regulation are tightening treatment substance approvals for timber preservation. Industrial consequences include accelerated phase-out of certain biocide applications and migration toward heat-treatment-only certification. German and Dutch pallet producers are responding with capital redeployment into kiln capacity expansion.
Consolidated buying by third-party logistics providers is displacing fragmented rental arrangements in North American food and beverage distribution. Regional 3PLs are negotiating direct mill contracts for stringer pallets, bypassing pooled equipment intermediaries. This pattern concentrates most visibly in the southeastern United States where sawmill proximity supports just-in-time delivery commitments.
Wooden Pallets Market Segmentation
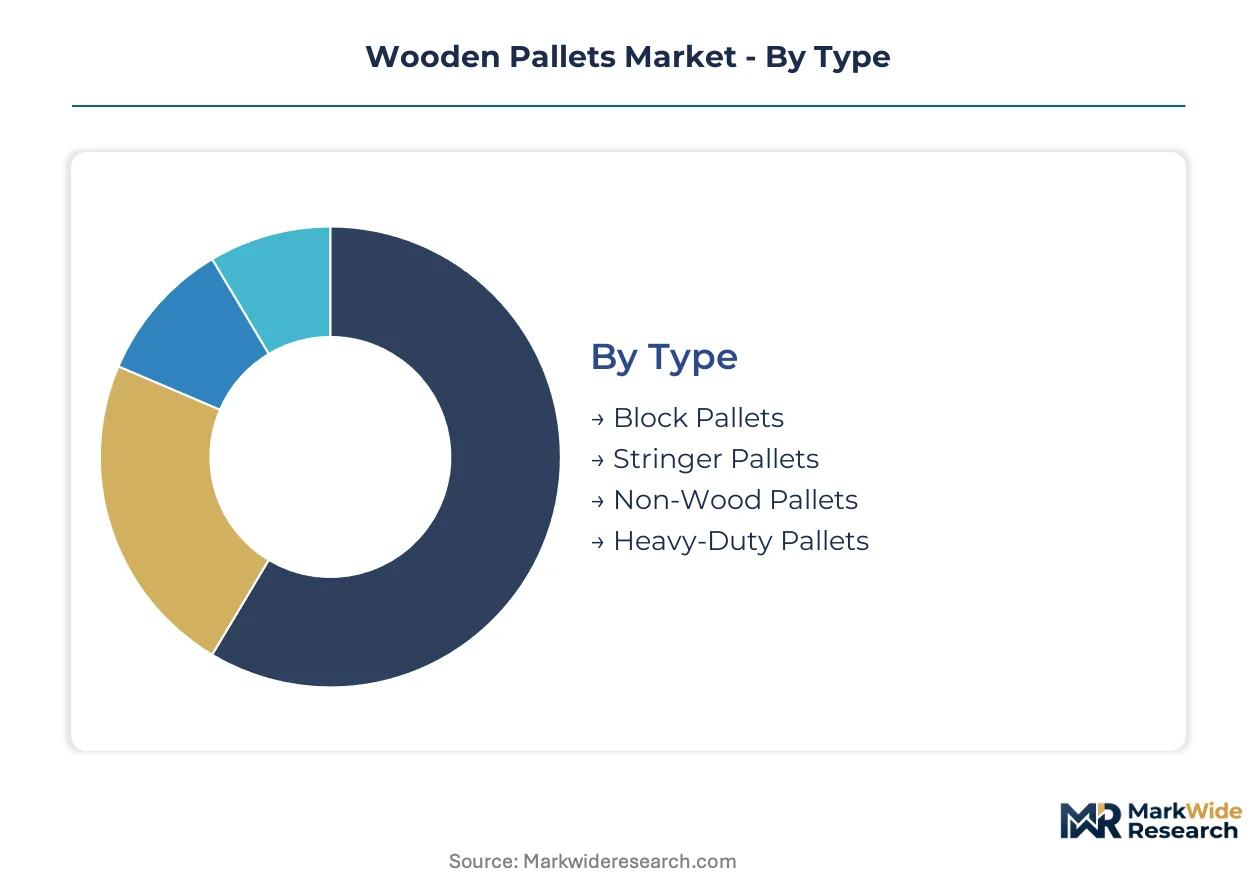
Pallet procurement patterns diverge sharply across use cycles. High-turnover food distribution demands disposable stringer economics, while closed-loop pharmaceutical systems prioritize durable block designs with tracking integration.
Type:
Cycle times range from single-trip food logistics to decade-long rental pool rotation, with material construction dictating replacement frequency and capital recovery profiles.
- Block Pallets:Four-way entry construction using perpendicular stringer blocks enables forklift access from all sides. Automated warehouse systems in Germany's automotive corridors specify these for robotic handling compatibility, though higher unit costs limit penetration in price-sensitive agricultural shipping.
- Stringer Pallets:Two-way entry design with parallel top and bottom deck boards supported by longitudinal stringers. U.S. food and beverage distributors favor these for single-use export economics where ISPM 15 heat-treatment compliance costs must stay minimal.
- Non-Wood Pallets:Injection-molded plastic or composite alternatives serving pharmaceutical cold chains requiring moisture resistance and sanitization protocols.
- Heavy-Duty Pallets:Reinforced lumber or steel-enhanced constructions for machinery and construction material transport exceeding standard load ratings.
Stringer pallets anchor the volume base while block pallets gain share at the steepest rate.
Application:
Margin structures compress toward commodity levels in high-volume segments while specialized compliance requirements sustain premium positioning in regulated end-uses.
- Food & Beverage:Perishable supply chains drive the highest pallet consumption velocity. U.S. third-party fulfillment networks source stringer pallets by the million-unit lot for grocery distribution, with seasonal harvest peaks creating demand surges that strain southeastern sawmill capacity.
- Pharmaceuticals:Temperature-controlled logistics mandate hygienic, trackable pallet solutions. EU REACH chemical restrictions and F-Gas Regulation compliance push manufacturers toward heat-treated block designs with embedded RFID for chain-of-custody documentation.
- Construction:Bulk material transport of cement, brick, and structural components employs heavy-duty specifications with higher load tolerances.
- Furniture:Finished goods distribution favors lightweight standard dimensions to minimize dimensional weight charges in less-than-truckload networks.
Food and beverage anchors the volume base while pharmaceuticals climbs the fastest on compliance-driven specification upgrades.
End User:
Procurement authority is shifting from pooled equipment intermediaries toward direct fleet ownership as operators seek rental fee elimination.
- Logistics:Third-party providers and dedicated contract carriers represent the deepest demand pool. Consolidated buying by regional 3PLs in the southeastern United States is displacing fragmented rental arrangements through direct sawmill contracts.
- Retail:Big-box operators internalizing pallet management bypass CHEP and other pooled networks. Direct procurement volume contracts favor integrated producers with captive lumber supply.
- Manufacturing:Automotive and chemical exporters in Germany's industrial corridor maintain high-volume block pallet consumption for component unitization.
- Warehousing:Dedicated storage operations favor durable specifications for extended in-facility cycling before retirement.
Logistics anchors the volume base while retail gains share fastest through fleet internalization.
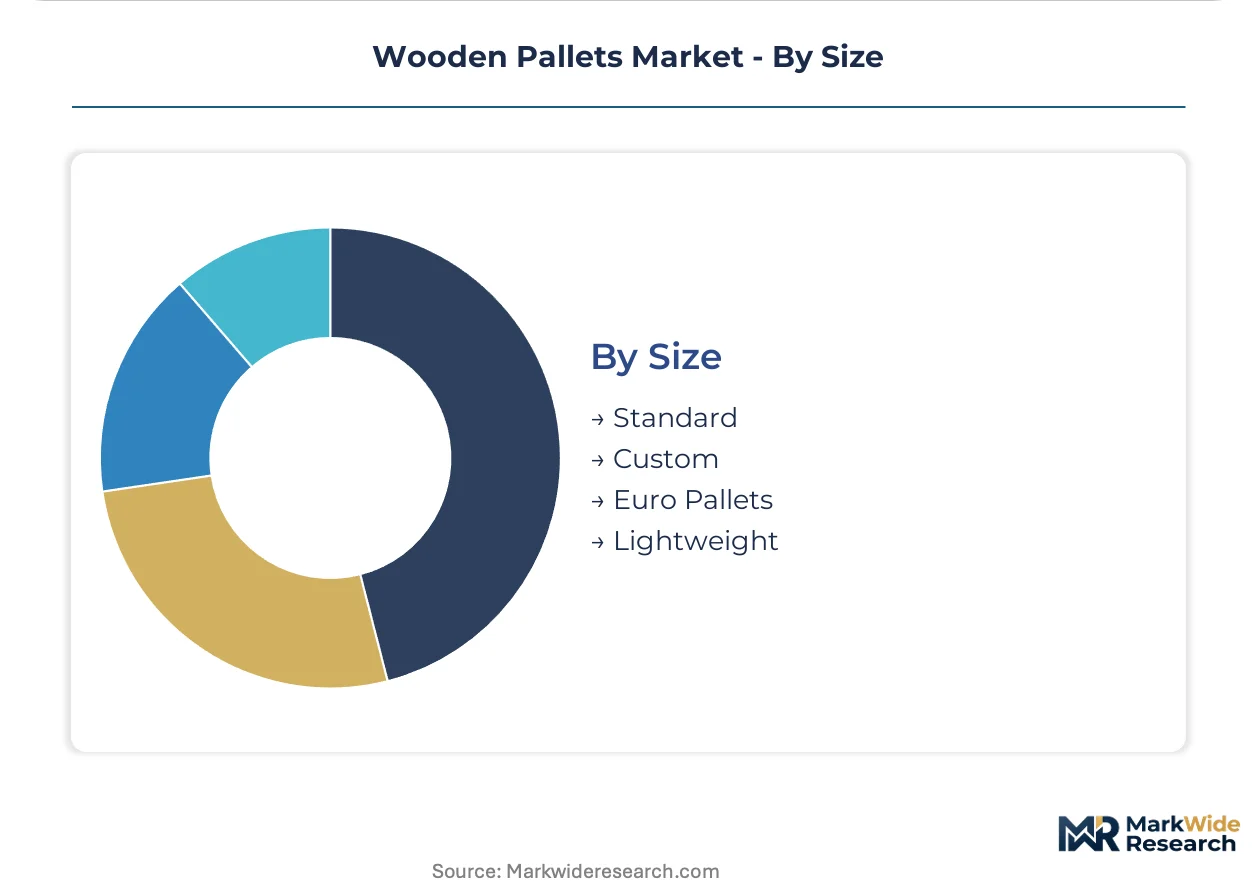
Size:
Standardization pressures from intermodal compatibility clash with customization demands from specialized cargo dimensions.
- Standard:ISO 6780 dimensions dominate North American domestic freight. Intermodal compatibility with rail container specifications constrains deviation.
- Euro Pallets:EUR/EPAL 1200x800mm specification mandatory for EU retail distribution. Germany's grocery networks enforce compliance through rejection of non-certified alternatives at receiving docks.
- Custom:Non-standard dimensions serve specialized machinery, aerospace components, and irregular cargo profiles where unitization efficiency outweighs interchangeability.
- Lightweight:Reduced lumber content for air freight dimensional weight optimization and single-use export where return logistics are uneconomical.
Standard dimensions anchor the volume base while Euro pallets expand most quickly on EU regulatory harmonization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's intermodal throughput underwrites the Netherlands' central role in European pallet circulation, while the Mississippi River barge network anchors North American softwood logistics.
United States
Third-party fulfillment networks in Georgia and Texas are scaling pallet procurement to match same-day delivery density requirements. EPA heat-treatment standards compress supply chains toward certified sourcing. The southeastern sawmill belt from Alabama through North Carolina sustains integrated pallet manufacturing operations.
Germany
Automotive and chemical exporters in Baden-Württemberg maintain high-volume block pallet consumption for component unitization. EU Green Deal timber traceability mandates extend compliance timelines for SME producers. The Rhine-Main industrial corridor concentrates pallet fleet management operations serving retail grocery distribution.
China
Domestic e-commerce logistics providers are synchronizing pallet specifications with export-market requirements under GB/T 2934 standards. SAMR quality enforcement tightens manufacturing compliance documentation. Yangtze River Delta processing clusters are expanding heat-treatment capacity for cross-border shipments.
Vietnam
Export-oriented manufacturers are leveraging expanded softwood processing capacity to supply Asia-Pacific logistics networks. National timber legality verification systems align with EU Deforestation Regulation due diligence requirements. Ho Chi Minh City industrial zones are attracting pallet fabrication investment from regional distributors.
Indonesia
Integrated forestry-to-fabrication operations are targeting ASEAN market expansion with tropical hardwood alternatives. Ministry of Environment and Forestry sustainable forest management certification supports export market access. Java-based manufacturing clusters are scaling production for Australian and Japanese import specifications.
Wooden Pallets Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented supply. The vendor base organizes around three structural tiers: pooled equipment networks with captive fleet ownership, integrated sawmill-to-pallet producers with captive lumber supply, and regional fabrication shops serving spot-market demand. Dominant competitive moves include backward integration into sawmill capacity and geographic expansion through distribution partnerships.
Among Germany-based fabricators, Cabka Group GmbH exemplifies the composite-material specialist archetype, while CHEP anchors the pooled-network tier with its closed-loop rental infrastructure. PalletOne Inc. represents the integrated producer model with southeastern U.S. sawmill proximity. These three occupy positions spanning material innovation, asset-light logistics, and vertical supply control.
| Leading Market Players |
|---|
| Cabka Group GmbH |
| PECO Pallet, Inc. |
| CHEP (Brambles Limited) |
| PGS Group |
| Inka-Paletten |
| PalletOne Inc. |
| Craemer GmbH |
| Kamps Pallets |
| Falkenhahn AG |
| Others |
Value Network & Pricing Analysis
Undercapacity in Baltic and Nordic sawmill operations is compressing softwood lumber availability, forcing pallet manufacturers toward spot-market procurement and eroding contract pricing stability across European supply chains.
Pricing Analysis
EU Ecodesign for Sustainable Products Regulation dictates the pricing tier structure across the wooden pallets market, separating heat-treated ISPM 15-certified block pallets from untreated stringer alternatives. Price differentiation hinges on certification grade and volume scale, with automotive exporters in Germany absorbing premium positioning for four-way entry designs while U.S. food distributors drive commoditization through million-unit spot purchases. Cost compression in standard stringer grades is intensifying because sawmill capacity constraints transmit directly to input costs. Third-party logistics providers exhibit highest price sensitivity through consolidated tender processes, whereas pharmaceutical cold-chain operators demonstrate lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Softwood lumber feedstock draws from concentrated harvesting operations across Sweden, Finland, and the Baltic states, with secondary hardwood sourcing anchored in the southeastern United States. Raw material dependencies rest on kiln-drying capacity, ISPM 15 treatment facility availability, and nail fastener supply from steel rolling mills. Single-source vulnerability concentrates in Nordic sawmill networks where weather-related production interruptions cascade through pallet manufacturing schedules. Distribution runs through pooled equipment intermediaries in European retail corridors and direct mill contracts in North American food and beverage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pallet fleet management services are expanding faster than hardware manufacturing, with RFID-enabled tracking and dynamic repositioning algorithms generating recurring revenue streams that outpace unit sales growth.
For Market Incumbents: Insulate core positioning through backward integration into captive sawmill capacity in the southeastern United States and certification investment ahead of full EU carbon-border adjustment mechanism implementation. Plastic pallet substitution in pharmaceutical applications threatens wooden alternatives in hygienic closed-loop systems, requiring material innovation responses in composite hybrid designs. For New Entrants and Emerging Players: Build out heat-treatment facility capacity in Vietnam and Indonesia to capture Asia-Pacific export demand under synchronized GB/T 2934 and ISPM 15 specifications. Retail direct procurement represents the most penetrable channel, with big-box operators bypassing CHEP and PECO rental networks through volume contracts with integrated producers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across RFID-embedded tracking infrastructure and automated kiln systems, favoring asset-light platform operators over heavy manufacturing footprints. Acquisition target archetype: regional fabrication shops with established ISPM 15 certification and sawmill proximity in underserved logistics corridors. Signal to watch: treatment facility utilization rates as leading indicator of export-ready capacity tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sawmill Capacity | Captive lumber supply secures margin control against Baltic price volatility. |
| ISPM 15 Certification Expansion | Heat-treatment capacity unlocks cross-border phytosanitary compliance for EU and Asia-Pacific exports. |
| RFID Fleet Tracking Deployment | Embedded sensors enable dynamic repositioning algorithms that reduce empty-mile ratios for rental networks. |
| Composite Material R&D Investment | Hybrid plastic-wood designs compete in pharmaceutical cold-chain applications where moisture resistance commands premium positioning. |
| Retail Direct Procurement Contracts | Volume agreements with big-box operators bypass CHEP intermediaries and capture rental fee elimination value. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with sawmill operations managers, pallet manufacturing plant directors, third-party logistics procurement leads, and retail supply chain executives; and secondary validation through customs trade data, EPA timber treatment standard filings, EU Ecodesign regulatory documentation, and FAO forest product statistics. Bottom-up triangulation across regional production clusters and top-down demand modeling across end-use segments ensured cross-verification of volume estimates.
Forecast inputs considered pallet type segmentation by construction design, application segmentation by compliance requirements, end-user segmentation by procurement authority, and geographic segmentation by sawmill proximity and treatment facility density. CAGRs were derived through regression analysis of historical lumber input costs against finished pallet price indices, incorporating e-commerce logistics volume trajectories and regulatory implementation timelines as industry-specific demand drivers across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Southeast Asian softwood processors or accelerated plastic pallet substitution in pharmaceutical applications would shift outcomes beyond modeled ranges. Cross-checking against FAO forest product trade statistics and EU Timber Regulation enforcement data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
Pallet Slip Sheets Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
Europe Pallet Market