
 Europe Pallet Market | 2026-2036
Europe Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pallet Market Intelligence
Pallet pooling as a service layer is consolidating what European buyers actually purchase, shifting capital expenditure into operational subscriptions. CHEP leverages its pooled network density to control pan-European return cycles. CABKA Group GmbH anchors its position through captive plastic recycling and closed-loop resin recovery. DS Smith Plc competes via corrugated pallet specialization for lightweight, single-use export corridors.
A pallet is a portable, horizontal platform—typically 1200 mm × 800 mm or 1200 mm × 1000 mm in Europe—built from wood slats, extruded plastic, or pressed fiber, designed for forklift entry on two or four sides to enable unitized goods handling across warehousing, transport, and retail display. Wood material still dominates European volume due to low first cost and repairability, though plastic is displacing share in pharmaceutical and food-grade closed-loop applications where hygiene washing and ISPM-15 exemption add operational value. Block pallets lead in automated high-bay warehouses across Germany and the Netherlands because their four-way entry aligns with conveyor and robotic handling systems.
The EU Green Deal, REACH chemical compliance, and national packaging extended producer responsibility schemes are collectively restricting single-use wooden pallet flows and elevating documentation burdens for treated timber cross-border movement. ECHA scrutiny of chemical preservatives in wood treatment is pushing converters toward heat-treated or plastic alternatives that bypass residual substance registration. Stakeholders must monitor how the EU Packaging and Packaging Waste Regulation revision redefines reuse targets and whether pooled model operators can demonstrate measurable trip rates against those thresholds.
Market Dynamics
EU circular economy mandates are compressing pallet lifecycles and forcing material substitutions, converting a capital goods market into a compliance-driven service layer where trip documentation and reuse verification determine supplier viability.
Growth Catalysts
- EU Green Deal packaging rules:Mandatory reuse targets for transport packaging accelerate pooling model penetration across German and Dutch distribution networks.
- Pharmaceutical cold-chain expansion:Temperature-validated plastic pallets capture share in vaccine and biologics logistics where thermal stability and hygiene washing protocols add operational value.
- Automated warehouse density:Four-way entry block pallets align with robotic handling systems in high-bay facilities across the Netherlands and northern Germany.
Market Restraints
- Timber input cost volatility:Softwood lumber prices fluctuate with Nordic forestry harvest cycles and energy-intensive kiln drying costs.
- REACH chemical compliance friction:ECHA scrutiny of wood preservatives restricts cross-border movement of chemically treated pallets and elevates documentation burdens.
- Plastic resin supply concentration:Virgin and recycled polymer feedstock clusters in Benelux and northwest Germany create geographic dependency risk for converters.
Strategic Opportunities
- Eastern European manufacturing corridors:Poland and Czech Republic automotive supplier parks present underpenetrated demand for closed-loop pooling services.
- Corrugated fiber pallet substitution:Lightweight pressed fiber formats bypass ISPM-15 treatment requirements in single-use export lanes to Asia-Pacific markets.
- Digital pallet passports:RFID and blockchain-enabled tracking systems align with upcoming EU Digital Product Passport requirements for packaging traceability.
Industry Challenges
- ISPM-15 heat-treatment capacity:Certified kiln infrastructure shortages in southern Europe bottleneck export-compliant wooden pallet supply during peak agricultural seasons.
- Reuse verification systems:Pooled operators struggle to document measurable trip rates against evolving EU Packaging and Packaging Waste Regulation reuse thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pallet Market |
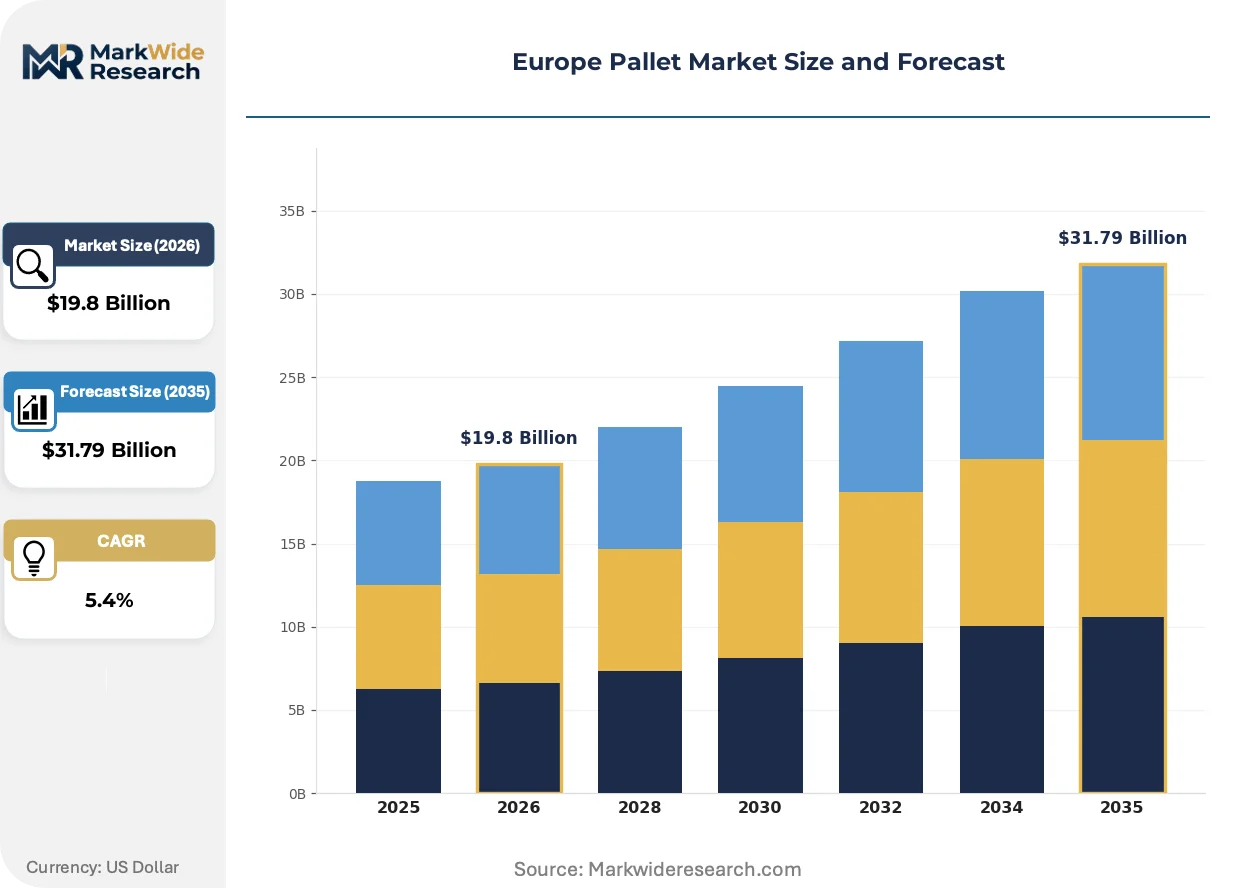
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $31.79 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Plastic, Metal, Composite Type: Block, Double-Face, GMA, Stringer Application: Food & Beverage, Pharmaceuticals, Automotive, Retail Capacity: Standard, Heavy-Duty, Lightweight, Custom |
| Companies Covered | CHEP, CABKA Group GmbH, Craemer GmbH, AUER GmbH, Falkenhahn AG, DS Smith Plc, PGS Group, Smurfit Kappa Group, La Palette Rouge, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pallet Market Strategic Shifts & Innovations
Material science advances and regulatory digitization are converging to transform pallet economics from unit-cost competition toward lifecycle accountability and data-verified circularity performance.
RFID-embedded plastic pallets are expanding into pharmaceutical and food-grade closed-loop systems, enabling real-time location tracking and wash-cycle counting that wooden alternatives cannot support. Major European retailers and third-party logistics providers in France and Germany now specify chip-enabled assets for high-value inventory lanes. This visibility infrastructure is expanding into predictive maintenance and automated pool reconciliation, compressing working capital requirements for fleet operators.
REACH chemical compliance is forcing converters toward heat-treated timber and virgin plastic alternatives that bypass residual substance registration. ECHA's tightened scrutiny of creosote and copper-based wood preservatives has eliminated certain treatment options for cross-border pallet flows. Food-grade and pharmaceutical shippers in Benelux and Scandinavia now specify heat-treated or plastic pallets exclusively, creating a two-tier market split by regulatory risk tolerance.
Subscription-based pallet pooling is displacing outright purchase across European manufacturing and retail supply chains. Buyers in automotive and consumer packaged goods sectors prioritize operational expenditure models that transfer fleet management, repair, and compliance documentation to specialized operators. This preference shift concentrates most visibly in Germany, where dense manufacturing clusters and short transport radii enable economically viable return-cycle economics for pooled assets.
Europe Pallet Market Segmentation
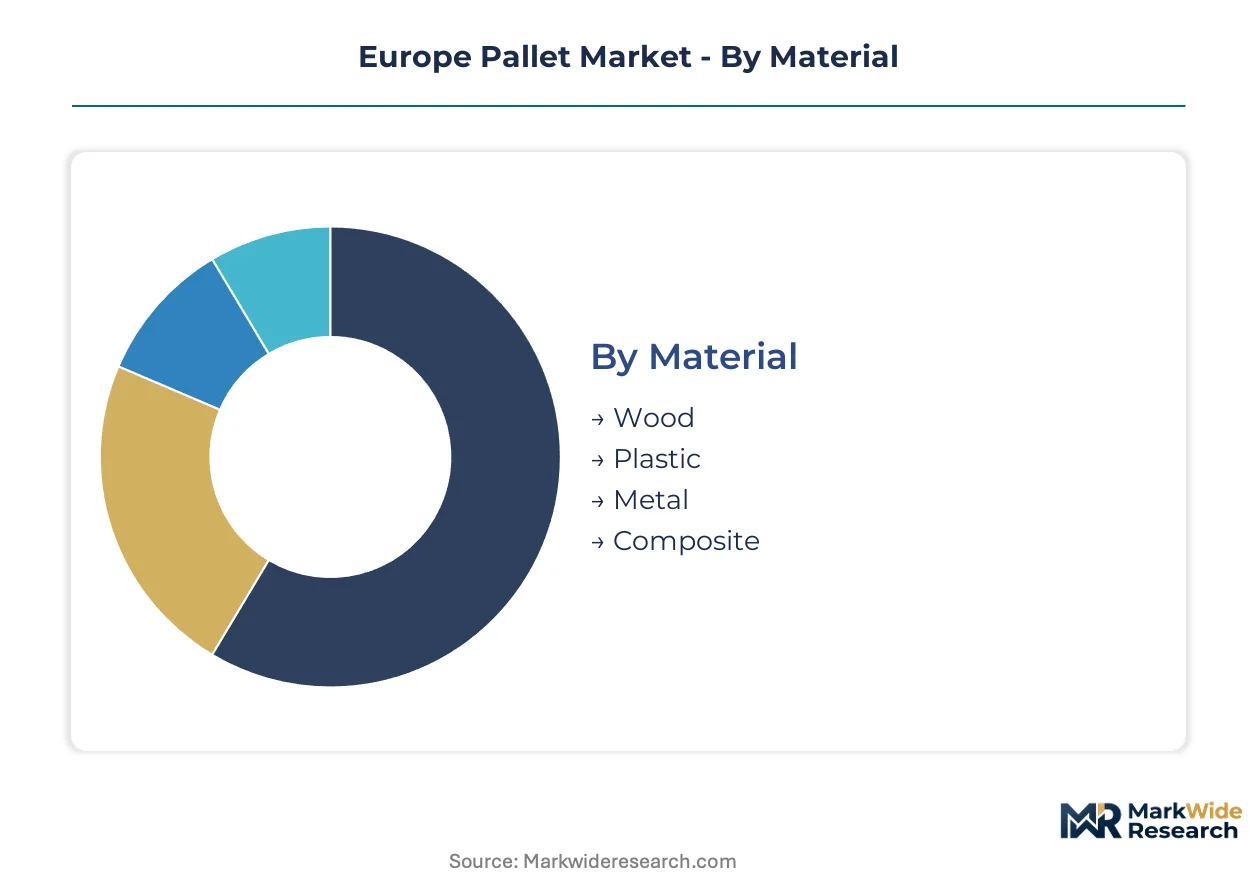
Pallet specification varies sharply across European supply chains, with material choice and entry configuration determining compatibility with automated handling, regulatory compliance, and pooling economics. Buyers segment procurement by load requirements, hygiene protocols, and return-cycle infrastructure availability.
Material:
Cost sensitivity and regulatory risk tolerance split buyers into distinct procurement tiers across the continent.
- Wood:Softwood and hardwood slat construction dominates first-cost procurement for general logistics. German and French retailers specify heat-treated timber for cross-border compliance, though ECHA preservative restrictions are compressing chemically treated supply.
- Plastic:HDPE and PP injection-molded platforms capture pharmaceutical and food-grade closed-loop systems where wash-cycle durability and ISPM-15 exemption justify premium positioning. Benelux cold-chain operators specify these exclusively for temperature-validated lanes.
- Metal:Steel and aluminum platforms serve heavy industrial applications with extreme load cycling. Automotive stamping plants in Czech Republic and Slovakia deploy these for die handling and captive internal loops.
- Composite:Pressed fiber and hybrid resin-wood formulations bypass timber treatment requirements in single-use export corridors. Lightweight formats gain traction in France-to-Asia-Pacific air freight lanes.
Volume sits with wood; growth tilts toward plastic.
Type:
Warehouse automation density determines entry configuration demand across northern European distribution networks.
- Block:Four-way entry via cubic wood or plastic blocks enables omnidirectional forklift and robotic handling. Netherlands high-bay facilities and German automotive supplier parks specify these for conveyor integration.
- Double-Face:Identical top and bottom decks support reversible loading and racking stability. Retail distribution centers in France prioritize these for seasonal volume surges and mixed-load flexibility.
- GMA:Grocery Manufacturers Association specifications align with North American import-export lanes. Port logistics operators in Rotterdam and Hamburg stock these for transatlantic container stuffing.
- Stringer:Two-way entry via parallel longitudinal boards suits low-automation warehousing and single-direction forklift operations. Southern European agricultural exporters favor these for harvest-season peak demand.
Block pallets command automated corridors; stringer formats retain cost-driven agricultural flows.
Application:
Sector-specific hygiene and traceability requirements reshape material and tracking specifications.
- Food & Beverage:Washable plastic platforms with RFID traceability dominate dairy, meat, and beverage pooling networks. German discount retailers mandate chip-enabled assets for supply chain visibility.
- Pharmaceuticals:Temperature-validated plastic pallets with thermal stability certification capture vaccine and biologics logistics. EMA cold-chain guidelines drive specification toward closed-loop pooling in Benelux.
- Automotive:Heavy-duty block and metal formats support just-in-time sequencing and component kitting. Czech and Polish supplier parks near OEM assembly plants drive concentrated demand.
- Retail:Mixed material procurement balances pooled plastic for high-rotation SKUs against purchased wood for promotional and seasonal surges. French hypermarket operators segment by product value density.
Food and beverage anchors volume; pharmaceutical lanes are expanding most quickly.
Capacity:
Load specification and handling frequency determine durability tier selection.
- Standard:1000-1500 kg dynamic load rating serves general warehousing and retail distribution. German mid-market manufacturers specify these for pooled fleet compatibility.
- Heavy-Duty:Reinforced construction exceeds 2000 kg for automotive components, machinery, and dense consumer goods. Industrial captives in northern Italy favor these for internal production loops.
- Lightweight:Reduced material content for single-use export and air freight where tare weight drives freight economics. Corrugated fiber formats in this tier bypass ISPM-15 for Asia-Pacific destinations.
- Custom:Engineered dimensions and load ratings for specialized manufacturing equipment and non-standard container optimization. Aerospace suppliers in Toulouse and Hamburg specify these for sensitive component transport.
Standard capacity dominates pooled networks; custom specifications capture margin in specialized manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Nordic timber zones and Benelux resin clusters, while consumption pulls toward German manufacturing belts and Dutch port logistics corridors. This spatial mismatch sustains cross-border pallet flows and pooling network economics.
Germany
Automotive supplier parks in Bavaria and Baden-Württemberg drive block pallet demand for just-in-time sequencing. The KBA enforces strict transport packaging documentation for cross-border component flows. Stuttgart's dense OEM ecosystem sustains closed-loop pooling services with sub-48-hour return cycles.
Netherlands
Rotterdam port throughput and high-bay warehouse automation in Venlo generate four-way entry pallet specifications. The EU Green Deal packaging rules mandate reuse targets that accelerate subscription pooling adoption. Eindhoven's pharmaceutical logistics corridor specifies RFID-enabled plastic platforms for cold-chain validation.
France
Parisian retail distribution and Lyon-based food processing anchor mixed-material procurement strategies. ANSM pharmaceutical guidelines push vaccine logistics toward washable, traceable pallet formats. The Île-de-France hypermarket network segments fleet by product value density and rotation velocity.
Poland
Automotive component manufacturing in Silesia and Greater Poland creates underpenetrated demand for closed-loop pooling infrastructure. EU cohesion funding supports logistics modernization in eastern manufacturing corridors. Wrocław's supplier parks near German OEM plants drive cross-border pallet flow requirements.
Italy
Industrial machinery exporters in Lombardy and Emilia-Romagna favor heavy-duty formats for dense capital goods shipment. REACH chemical compliance restricts creosote-treated timber for Mediterranean agricultural export lanes. Bologna's packaging machinery cluster innovates in automated palletizing systems for European distribution.
Europe Pallet Market Key Industry Players
Top-tier vendors anchor pan-European pooling networks, while mid-scale fabricators compete on material specialization and regional repair density. The vendor base stratifies between asset-light service operators and capital-intensive recycling-integrated manufacturers. Three archetypes dominate: pooled network orchestrators, captive resin recyclers, and corrugated lightweight specialists. Consolidation is accelerating through repair depot acquisitions and cross-border pooling alliance formation.
Within the pooled network tier, CHEP exemplifies the asset-heavy service model with density-driven return cycle control. CABKA Group GmbH anchors the recycling-integrated archetype through captive plastic recovery and closed-loop resin operations. DS Smith Plc occupies a position within the lightweight substitution vector, representing corrugated fiber specialization for single-use export corridors.
| Leading Market Players |
|---|
| CHEP |
| CABKA Group GmbH |
| Craemer GmbH |
| AUER GmbH |
| Falkenhahn AG |
| DS Smith Plc |
| PGS Group |
| Smurfit Kappa Group |
| La Palette Rouge |
| Others |
Cost & Logistics Intelligence
Mandatory pooling subscriptions among German automotive suppliers and Dutch retailers are compressing capital expenditure into operational expenditure models, forcing converters to absorb fleet management costs and recalibrate per-trip pricing against reuse verification thresholds.
Pricing Analysis
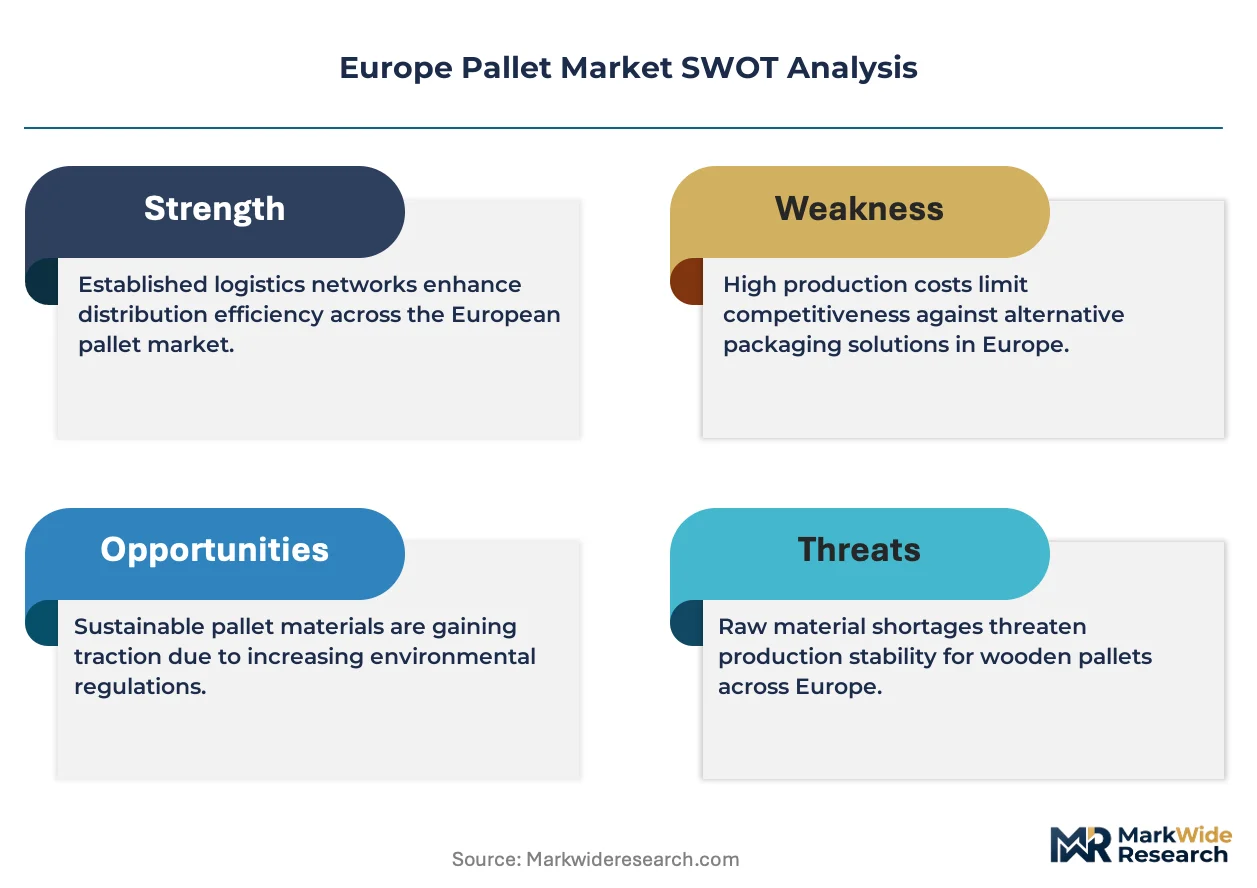
Price erosion across pooled plastic tiers traces to CHEP's network density advantages and CABKA's captive resin recovery operations, which compress competitor margins in pharmaceutical and food-grade closed-loop segments. Three-tier pricing structure across premium RFID-enabled plastic, standard heat-treated wood, and economy stringer formats differentiates buyers by hygiene protocol and automation compatibility. Cost-down pressure on wooden alternatives accelerates because ECHA preservative restrictions eliminate chemically treated supply options. Small agricultural exporters in southern Europe exhibit highest price sensitivity, while Benelux cold-chain operators accept premium positioning for temperature-validated assets.
Supply Chain Analysis
Single-source vulnerability sits with Nordic softwood harvest zones and Benelux polymer feedstock clusters, where geographic concentration amplifies disruption risk from forestry cycle volatility and resin supply bottlenecks. Raw material procurement draws from Swedish and Finnish timber concessions, northwest German petrochemical complexes, and Dutch mechanical recycling facilities. Tariff exposure on cross-border treated timber movements under evolving EU Packaging and Packaging Waste Regulation reuse documentation requirements threatens compliance-cost escalation. Distribution runs through Rotterdam and Hamburg port logistics corridors, with repair depot networks concentrating in German manufacturing belts and Dutch high-bay warehouse zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID-embedded plastic pallets are displacing wooden alternatives in pharmaceutical and food-grade lanes, converting a commodity hardware market into a data-verified service layer where traceability infrastructure determines supplier viability.
For Market Incumbents: Lock in pooling network density through repair depot acquisitions in Polish and Czech automotive corridors, defending against corrugated fiber substitution in lightweight export lanes by demonstrating superior trip-rate documentation against EU Green Deal reuse thresholds. Backward integration into captive mechanical recycling secures resin supply continuity as virgin polymer feedstock concentrates in Benelux. For New Entrants and Emerging Players: Eastern European automotive supplier parks present underpenetrated demand for closed-loop pooling services, with Silesian and Greater Poland manufacturing zones lacking comparable return-cycle infrastructure to German equivalents. Target pharmaceutical logistics operators in Eindhoven's cold-chain corridor with temperature-validated plastic platforms and blockchain-enabled pallet passports that preempt EU Digital Product Passport requirements. For Investors and Strategic Acquirers: Re-rating potential sits with recycling-integrated plastic converters given ECHA chemical compliance friction eliminating wood preservative alternatives and accelerating material substitution timelines. Acquisition candidates combining captive resin recovery with RFID fleet management capabilities offer defensive positioning through regulatory-driven demand shifts. Monitor EU Packaging and Packaging Waste Regulation reuse threshold finalization as inflection indicator for pooling model economics.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Mechanical Recycling Buildout | CABKA's closed-loop resin operations insulate margin from virgin polymer volatility in Benelux feedstock zones. |
| RFID Fleet Management Platform | Real-time location tracking aligns with EMA cold-chain guidelines for vaccine logistics traceability requirements. |
| Repair Depot Network Expansion | Polish corridor acquisitions compress return-cycle economics for automotive supplier parks near German OEM plants. |
| Corrugated Fiber Format Development | DS Smith's lightweight substitution bypasses ISPM-15 treatment requirements for Asia-Pacific air freight lanes. |
| Blockchain Pallet Passport Pilot | Digital traceability infrastructure preempts EU Digital Product Passport mandates for packaging circularity verification. |
Research Approach
Trade statistics from Eurostat, industry association publications from European Pallet Association (EPAL), and customs flow data from Nordic timber export registries formed the secondary backbone, supplemented by primary interviews with pooling fleet managers, automotive procurement leads at Tier 1 suppliers, pharmaceutical logistics operators, wood treatment facility operators, and plastic recycling facility technical directors. Bottom-up shipment data triangulated against top-down manufacturing capacity assessments across German, Dutch, and Polish production zones.
Bottom-up modeling tracked pallet flows by material type, entry configuration, and application sector across the projection horizon, while top-down validation anchored aggregate market sizing to macroeconomic indicators for warehousing investment and port throughput. Segmentation dimensions included material substrate, pallet type, end-use industry, load capacity tier, and regional regulatory cluster. CAGRs derived from historical shipment velocity patterns and forward-looking capacity expansion announcements, with specific inputs from EU Green Deal implementation timelines and ECHA chemical compliance enforcement trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Packaging and Packaging Waste Regulation reuse threshold finalization, Nordic forestry harvest cycle disruptions, and polymer feedstock price volatility from energy market fluctuations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
China Pallets Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Pallets Market
Pallets Packaging
Pallet Boxes Market
Pallets Packaging
GCC Pallet Market
Pallets Packaging
Middle East Pallets Market