
 Spill Pallets Market | 2026-2036
Spill Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Spill Pallets Market Outlook
Skilled polymer fabrication labor is bifurcating the competitive landscape between mass producers and precision molders. UltraTech International leverages its captive rotomolding capacity to dominate the high-capacity segment for petrochemical clients. New Pig Corporation differentiates through specialized channel control in laboratory and pharmaceutical end-uses. DENIOS anchors European demand with steel fabrication expertise calibrated to German chemical park specifications.
Spill pallets are engineered containment platforms, typically rotationally molded from polyethylene or fabricated from coated steel, designed to capture leaks and drips from drums, intermediate bulk containers, and machinery during storage or transfer operations. Polyethylene variants lead volume due to chemical resistance and lower unit economics, while steel spill pallets command premium positioning in flammable liquid environments where fire code compliance is mandatory. Drum pallets represent the most mature type category with established replacement cycles, whereas modular pallet systems are displacing fixed configurations as facilities prioritize reconfigurable floor layouts.
EPA SPCC regulations in the United States mandate secondary containment for oil storage above threshold volumes, directly shaping product capacity minimums and inspection protocols. OSHA workplace safety standards and REACH chemical handling frameworks in Europe enforce material compatibility documentation and load rating verification, raising compliance costs for non-certified suppliers. Buyers must monitor evolving state-level amendments to federal rules and assess whether their supplier base maintains dual certification for cross-border chemical logistics.
Market Dynamics
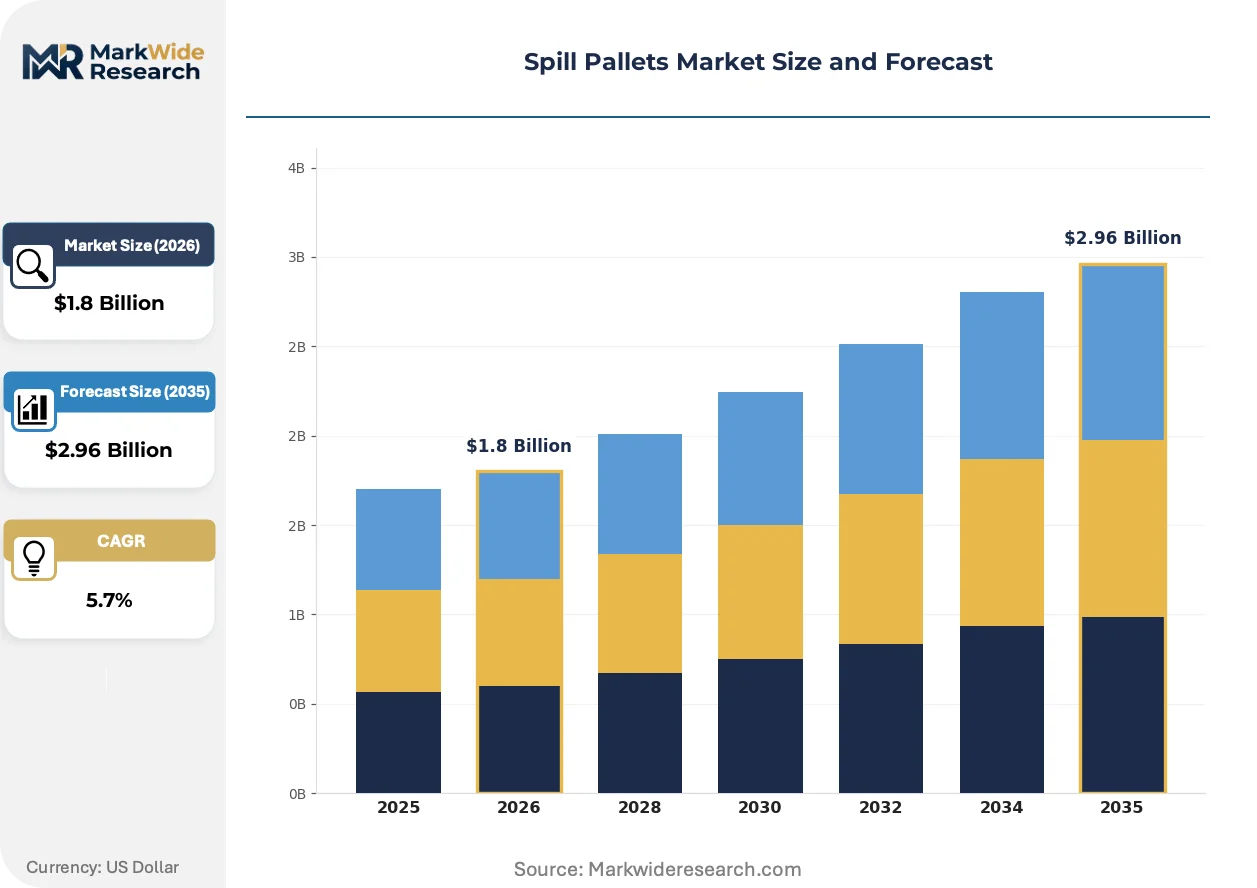
Secondary containment mandates from EPA SPCC regulations are compressing replacement cycles and forcing drum-intensive facilities toward modular pallet architectures that accommodate reconfigurable layouts without civil works.
Growth Catalysts
- EPA SPCC Enforcement:Oil storage facilities above threshold volumes must install compliant containment, driving systematic retrofit demand across petrochemical terminals and bulk lubricant distributors.
- Rotational Molding Scale:Polyethylene spill pallet production benefits from captive rotomolding capacity expansion, lowering unit economics for high-volume drum containment applications.
- Indian Chemical Parks:Clustered industrial zones near Gujarat and Maharashtra are mandating standardized secondary containment, creating concentrated procurement pull from integrated manufacturing complexes.
Market Restraints
- Steel Input Volatility:Coated steel fabrication depends on galvanized sheet pricing, exposing fire-code-compliant pallet producers to commodity swings that polyethylene competitors avoid.
- German Fabrication Concentration:Precision steel containment engineering clusters around chemical park specifications, creating geographic supplier lock-in for EU buyers seeking TÜV certification.
- Modular System Complexity:Reconfigurable pallet platforms require load-rating verification across connection geometries, slowing specification approval compared to fixed-capacity alternatives.
Strategic Opportunities
- Pharmaceutical Cleanroom Integration:Aseptic manufacturing facilities need contamination-resistant containment with smooth polyethylene surfaces that support validated cleaning protocols.
- Battery Electrolyte Handling:Lithium-ion gigafactories require acid-resistant secondary containment for electrolyte drums, opening material specification shifts beyond traditional oil-focused chemistries.
- CE Marking Harmonization:Unified EU machinery safety standards reduce certification fragmentation, enabling cross-border pallet sales without country-specific testing duplication.
Industry Challenges
- Rotomolding Technician Scarcity:Skilled polymer fabrication labor pools concentrate in legacy tank manufacturing regions, constraining precision molding capacity expansion for complex sump geometries.
- Dual-Certification Burden:Suppliers serving cross-border chemical logistics must maintain separate EPA SPCC documentation and REACH material compatibility files, inflating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spill Pallets Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyethylene, Steel, Plastic, Composite Type: Standard Pallets, Stackable Pallets, Modular Pallets, Drum Pallets Application: Industrial Use, Chemical Storage, Waste Management, Laboratory Use Capacity: 1000 Liters, 2000 Liters, 3000 Liters, 4000 Liters |
| Companies Covered | Brady Corporation, New Pig Corporation, UltraTech International, ENPAC, Eagle Manufacturing Company, Justrite Manufacturing Company, DENIOS, Fisher Scientific, Seton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spill Pallets Market Strategic Shifts
Material science advances and regulatory precision are compressing product lifecycles while opening specification gaps between commodity drum pallets and engineered containment systems.
Collapsible polyethylene containment systems are miniaturizing storage footprints for intermittent drum handling operations. Pharmaceutical contract manufacturers and specialty chemical distributors are adopting fold-flat pallet designs that deploy only during transfer operations. This architecture is miniaturizing the addressable market for fixed-capacity steel alternatives in facilities with severe space constraints.
REACH chemical compatibility documentation requirements are hardening material specification discipline across EU chemical handling. ECHA substance database cross-referencing now mandates polymer grade verification against specific drum contents, disqualifying generic polyethylene formulations. German chemical park operators are responding by consolidating procurement around suppliers with captive testing laboratories capable of generating batch-specific compatibility certificates.
Leasing arrangements for containment infrastructure are displacing capital purchase models among mid-size chemical distributors. Third-party logistics providers in the US Gulf Coast region are bundling spill pallet provisioning with drum management services, unbundling ownership from compliance responsibility. This pattern concentrates most visibly among hazardous waste handlers serving EPA Region 6 enforcement jurisdictions where inspection frequency has intensified.
Spill Pallets Market Segmentation
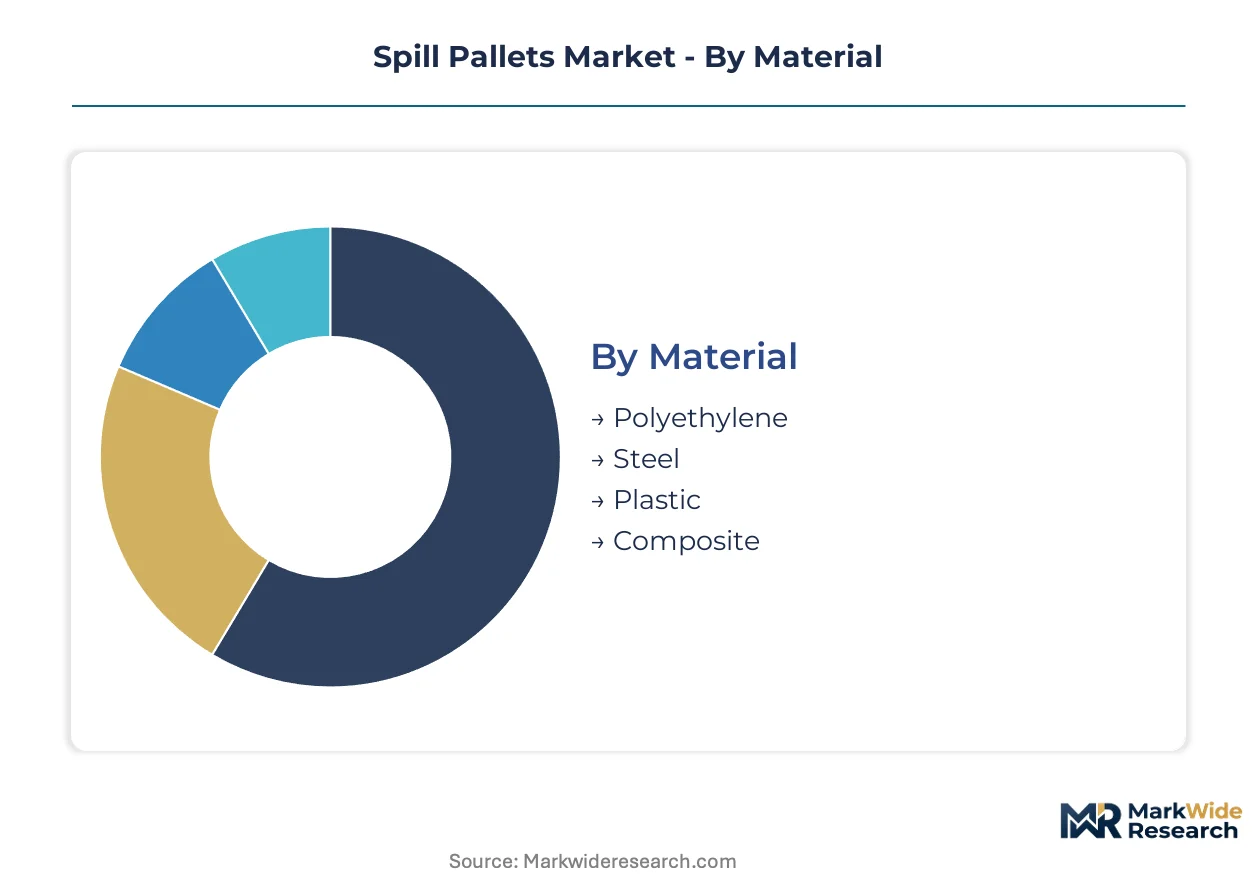
Spill pallet specification varies sharply across containment scenarios, with material chemistry and regulatory fire codes dicting procurement splits. Buyers segment procurement by hazard class, footprint constraints, and inspection protocols rather than unit cost alone.
Material:
EPA SPCC oil storage rules and OSHA flammable liquid codes split procurement between corrosion-resistant polymers and fire-rated steel fabrication.
- Polyethylene:Rotationally molded high-density polyethylene dominates drum containment for acids, bases, and petroleum derivatives. Chemical manufacturers in Texas and Louisiana specify polyethylene for its chemical resistance and lower inspection maintenance burden under EPA Region 6 enforcement.
- Steel:Galvanized and coated steel fabrication commands premium positioning where NFPA 30 fire codes mandate non-combustible containment. German chemical park operators require TÜV-certified steel pallets for solvent storage, locking procurement around localized fabrication clusters.
- Plastic:Injection-molded polypropylene variants serve light-duty laboratory and maintenance applications with lower load ratings. Pharmaceutical cleanrooms specify smooth-surface plastic pallets for validated cleaning protocols.
- Composite:Fiberglass-reinforced and hybrid material pallets bridge chemical resistance with structural rigidity for specialized electrolyte handling in battery manufacturing.
Established volume favors polyethylene; emerging adoption favors composite formulations for next-generation chemistries.
Type:
Facility reconfiguration demands and replacement cycle economics drive specification toward architectures that minimize civil works.
- Drum Pallets:Fixed-capacity four-drum platforms represent the most mature installed base with predictable replacement cycles. Bulk lubricant distributors in the US Gulf Coast maintain systematic retrofit programs as EPA inspection frequency intensifies.
- Modular Pallets:Interlocking sump systems allow reconfigurable layouts without concrete curbs or permanent barriers. Indian chemical parks near Gujarat mandate modular architectures for tenant flexibility in shared storage yards.
- Stackable Pallets:Nestable designs minimize return freight and storage footprint for drum logistics providers operating multi-site distribution networks.
- Standard Pallets:Single-drum and two-drum fixed platforms serve intermittent handling operations with lowest capital entry points.
Procurement gravity centers on modular systems; drum pallets retain highest replacement volume.
Application:
End-use hazard classification determines material specification, inspection frequency, and documentation burden.
- Chemical Storage:Bulk tank farms and drum warehouses require capacity-rated containment with EPA SPCC inspection logs. REACH documentation requirements in Europe harden material compatibility verification for cross-border chemical logistics.
- Industrial Use:Manufacturing floor drip containment for machinery and transfer points specifies lower-capacity platforms with frequent repositioning. OSHA workplace safety audits drive systematic specification upgrades.
- Waste Management:Hazardous waste handlers require secondary containment for accumulation areas prior to manifesting and shipment. EPA RCRA inspection protocols mandate load-rated sump capacity.
- Laboratory Use:Research and pharmaceutical facilities specify compact containment for solvent carboys and reagent bottles with contamination-resistant surfaces.
Chemical storage commands specification investment; laboratory use climbs fastest on pharmaceutical capacity expansion.
Capacity:
Sump volume minimums derive directly from stored container capacity and regulatory containment percentage rules.
- 1000 Liters:Single-drum and small IBC containment for distributed manufacturing and maintenance operations. Mid-size chemical distributors specify 1000-liter platforms for branch-level compliance.
- 2000 Liters:Standard four-drum configurations dominate petroleum terminal and lubricant warehouse procurement. German chemical parks specify 2000-liter steel platforms as baseline for solvent drum storage.
- 3000 Liters:Large IBC and multiple drum arrays serve bulk chemical distribution and toll manufacturing. REACH large-volume substance handlers specify elevated capacity for concentrated storage zones.
- 4000 Liters:Maximum-capacity platforms for tanker offload areas and high-volume transfer operations. Petrochemical terminals on the US Gulf Coast deploy 4000-liter systems for railcar and tank truck containment.
2000-liter platforms anchor replacement demand; 4000-liter systems expand on terminal infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA SPCC enforcement intensity in the United States is compressing replacement cycles for drum-intensive facilities. German chemical park specifications are locking procurement around TÜV-certified steel fabrication. Indian chemical clusters near Gujarat and Maharashtra are mandating standardized secondary containment for tenant flexibility.
United States
Petrochemical terminals and bulk lubricant distributors in Texas and Louisiana face intensified EPA Region 6 inspection protocols. OSHA workplace safety audits drive systematic specification upgrades for manufacturing floor containment. Houston-Galveston corridor facilities deploy 4000-liter systems for railcar and tank truck secondary containment.
Germany
Chemical manufacturers require TÜV-certified steel pallets for solvent storage under REACH chemical handling frameworks. ECHA substance database cross-referencing mandates polymer grade verification against specific drum contents. BASF-Ludwigshafen and Bayer-Leverkusen chemical parks consolidate procurement around suppliers with captive testing laboratories.
India
Clustered industrial zones near Gujarat and Maharashtra mandate standardized secondary containment for shared storage yards. CDSCO pharmaceutical manufacturing standards drive contamination-resistant containment specification for aseptic facilities. Ankleshwar and Vapi chemical estates represent concentrated procurement pull from integrated manufacturing complexes.
China
Lithium-ion gigafactories in Jiangsu and Fujian provinces require acid-resistant secondary containment for electrolyte drums. MEE environmental compliance inspections harden material specification discipline for hazardous waste handlers. Yangtze River Delta battery manufacturing clusters open material specification shifts beyond traditional oil-focused chemistries.
United Kingdom
Hazardous waste handlers serving industrial corridors face heightened Environment Agency inspection frequency. HSE workplace safety regulations enforce load-rating verification for reconfigurable pallet platforms. Teesside and Merseyside chemical clusters maintain systematic retrofit programs as enforcement tightens.
Spill Pallets Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in spill pallet supply. Mass producers with captive rotational molding capacity compete on unit economics for high-volume drum containment applications. Precision molders and steel fabricators anchor premium positioning where fire code compliance or validated cleaning protocols command specification. Strategic moves center on geographic expansion into chemical park clusters and portfolio diversification toward modular system architectures.
Within the integrated molding tier, UltraTech International and New Pig Corporation exemplify divergent specialization vectors. UltraTech leverages rotomolding scale for petrochemical terminal procurement. New Pig occupies a position in laboratory and pharmaceutical end-uses through specialized channel control. DENIOS anchors European demand with steel fabrication expertise calibrated to German chemical park specifications. Among diversified safety suppliers, Brady Corporation and Fisher Scientific sit within broader industrial and scientific distribution portfolios where spill containment represents a category extension rather than core vertical.
| Leading Market Players |
|---|
| Brady Corporation |
| New Pig Corporation |
| UltraTech International |
| ENPAC |
| Eagle Manufacturing Company |
| Justrite Manufacturing Company |
| DENIOS |
| Fisher Scientific |
| Seton |
| Others |
Value Chain & Pricing Dynamics
EPA SPCC certification gates supplier qualification while simultaneously stratifying price tiers, as only rotomolders with documented compliance histories capture premium positioning in petrochemical procurement. Buyers face dual screening: technical audit for sump geometry precision and price negotiation for volume scale, with uncertified competitors relegated to spot-market laboratory sales.
Pricing Analysis
Geographic price spreads of 15-25% separate US Gulf Coast petrochemical terminals from Indian chemical park procurement, reflecting freight absorption and certification documentation burdens. Three-tier pricing structure across premium, standard, and economy levels aligns with fire-code compliance grades, with TÜV-certified steel pallets commanding substantial premiums over polyethylene alternatives. Cost compression in economy-grade drum pallets is intensifying because captive rotomolding capacity expansion in Texas and Louisiana floods commodity segments. Mid-size chemical distributors exhibit highest price sensitivity, while pharmaceutical cleanroom operators prioritize validated cleaning protocols over unit cost.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Hamburg ports constrain European steel pallet distribution, with container availability fluctuations amplifying lead time uncertainty for German chemical park deliveries. Manufacturing concentrates in the United States, Germany, and China, with polyethylene resin sourcing tethered to Gulf Coast petrochemical complexes and galvanized sheet steel drawing from Ruhr Valley mills. Single-source vulnerability concentrates in rotational molding technician labor pools clustered around legacy tank manufacturing regions. Distribution runs through industrial safety distributors and direct chemical park procurement offices, with third-party logistics providers increasingly bundling containment with drum management services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, REACH, and CDSCO jurisdictions fragments procurement standards, creating specialized niches for certification-capable suppliers. Modular system architectures displace fixed-capacity alternatives, opening white-space for reconfigurable platform specialists.
For Market Incumbents: Compound defensive positioning through captive rotomolding capacity additions in Texas and Louisiana to capture EPA Region 6 retrofit demand. Secure TÜV certification maintenance for German chemical park specifications, as European competitors without dual EPA-REACH documentation face exclusion from cross-border chemical logistics. Vertical integration into polymer grade testing laboratories hardens REACH compliance capabilities against emerging composite material entrants. For New Entrants and Emerging Players: Differentiate on battery electrolyte handling specifications for lithium-ion gigafactories in Jiangsu and Fujian provinces, where acid-resistant containment demand outpaces established oil-focused supplier capabilities. Target Indian pharmaceutical cleanroom procurement near Ankleshwar and Vapi, where CDSCO aseptic manufacturing standards create specification gaps. Pursue direct sales to specialty chemical distributors with leasing-arrangement bundling, unbundling ownership from compliance responsibility. For Investors and Strategic Acquirers: EPA SPCC enforcement intensification reshapes the acquisition landscape toward suppliers with documented inspection compliance histories and captive rotomolding assets. Five-to-ten year viability favors precision molders with pharmaceutical channel control over commodity drum pallet producers facing polyethylene price volatility. Target acquisition archetype: mid-cap specialists with dual EPA-REACH certification and modular system engineering capabilities. Signal to monitor: state-level amendments to federal SPCC rules that would accelerate replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Supply | Gulf Coast petrochemical complexes provide captive polyethylene feedstock for rotomolding scale. |
| Modular System Architecture Development | Interlocking sump platforms capture Indian chemical park mandates for tenant flexibility. |
| Dual Certification Investment | Simultaneous EPA SPCC and REACH documentation enables cross-border chemical logistics penetration. |
| Pharmaceutical Cleanroom Specialization | Smooth-surface polyethylene validation protocols open aseptic manufacturing procurement channels. |
| Battery Electrolyte Containment Engineering | Acid-resistant composite formulations address lithium-ion gigafactory specification shifts. |
Study Parameters
A standing panel of plant engineers, chemical procurement managers, EHS compliance officers, and rotational molding operations directors provided ongoing calibration across the analysis window. Primary interviews with industrial safety distributors and pharmaceutical facility managers combined with secondary validation from EPA enforcement databases, ECHA substance registrations, customs trade records, and ACC industry reports. Bottom-up capacity utilization estimates and top-down regulatory mandate sizing were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period. Segmentation dimensions modeled include material chemistry, containment capacity tier, application hazard class, and regional regulatory cluster. CAGRs were derived from facility retrofit cycle analysis and chemical park infrastructure investment pipelines. Forecast inputs incorporated EPA inspection frequency trends and Indian chemical park development timelines.
The analysis sits within stated boundaries; outcomes outside sustained enforcement intensity or raw material price stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation schedules and polymer fabrication labor availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
UK Pallets Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Pallet Slip Sheets Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Pallet Boxes Market
Pallets Packaging
Pallets Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
China Pallets Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Disposable Plastic Pallet Market