
 Pallet Slip Sheets Market | 2026-2036
Pallet Slip Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Slip Sheets Market Outlook
Food and beverage distribution is realigning toward slip-sheet-based unit loads as cold-chain warehouses automate layer picking and push-pull handling. WestRock Company leverages its containerboard integration to supply coated kraft slip sheets with moisture resistance for refrigerated logistics. Smurfit Kappa Group anchors European demand through regional corrugated and solid board mills that feed on-site slip sheet converting. International Paper competes with broad North American manufacturing scale and recycled fiber sourcing networks that lower input cost volatility.
Pallet slip sheets are thin, flat platforms—typically manufactured from kraft paperboard, oriented polypropylene, or laminated fiber-resin composites—that sit beneath unitized loads to enable forklift-free handling via push-pull attachments or roller conveyors, generally ranging from 0.5 mm to 2.0 mm in caliper depending on load weight and friction requirements. Paper grade slip sheets dominate warehouse applications where single-trip use and downstream recyclability align with retailer sustainability mandates, while polyethylene variants sustain longer rotation cycles in closed-loop transportation pools between manufacturing plants and distribution centers. Composite constructions that bond recycled paper cores with polymer barrier layers occupy premium niches in pharmaceutical and electronics end uses where moisture protection and dimensional stability justify higher unit costs.
The EPA promotes source reduction and recycled content through its Sustainable Materials Management program, while OSHA standards for manual materials handling indirectly accelerate mechanical load containment adoption in US facilities. The EU Green Deal and PPWR framework tighten packaging recyclability thresholds that favor fiber-based slip sheets over non-recyclable plastic alternatives in European supply chains. Stakeholders must monitor how divergent transatlantic regulatory timelines for extended producer responsibility reshape material selection criteria and regional manufacturing footprints.
Market Dynamics
Warehouse automation and the EU Packaging and Packaging Waste Regulation are converging to eliminate traditional pallet pooling in favor of lightweight, single-trip fiber-based containment systems that reduce transport weight and simplify reverse logistics.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Green Deal and PPWR framework mandate recyclability thresholds that favor kraft paperboard slip sheets over non-recyclable plastic alternatives in European supply chains.
- Layer-picking robotics:Cold-chain warehouses deploying automated layer-picking systems require standardized, low-profile unit loads that push-pull attachments handle more efficiently than conventional pallets.
- German just-in-time density:Automotive and chemical exporters in Germany operate dense distribution networks where high-frequency pallet exchange elimination cuts handling cycles and transport weight.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container prices fluctuate with packaging demand cycles, compressing converter margins when input costs spike without corresponding pass-through mechanisms.
- Polypropylene substitution in closed loops:Polyethylene variants sustain longer rotation cycles in manufacturing plant-to-distribution center pools, limiting fiber-based penetration in captive transport systems.
- Moisture performance ceiling:Uncoated kraft slip sheets fail in refrigerated logistics without barrier treatments, restricting addressable share in food and beverage cold chain applications.
Strategic Opportunities
- Pharmaceutical barrier composites:Bonded fiber-resin constructions with moisture protection and dimensional stability command premium positioning in pharmaceutical and electronics end uses.
- US warehouse OSHA compliance:OSHA standards for manual materials handling accelerate mechanical load containment adoption in US facilities, opening retrofit demand for push-pull systems.
- India cold-chain buildout:Food and beverage logistics infrastructure expansion creates first-mover positioning for coated kraft slip sheets in temperature-controlled distribution.
Industry Challenges
- Push-pull equipment retrofit costs:Warehouse operators face capital requirements for forklift attachment upgrades and roller conveyor modifications to enable slip-sheet handling.
- Load stability certification timelines:Third-party testing for unit load containment performance adds lead time before slip sheets qualify for high-value automotive and electronics shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Slip Sheets Market |
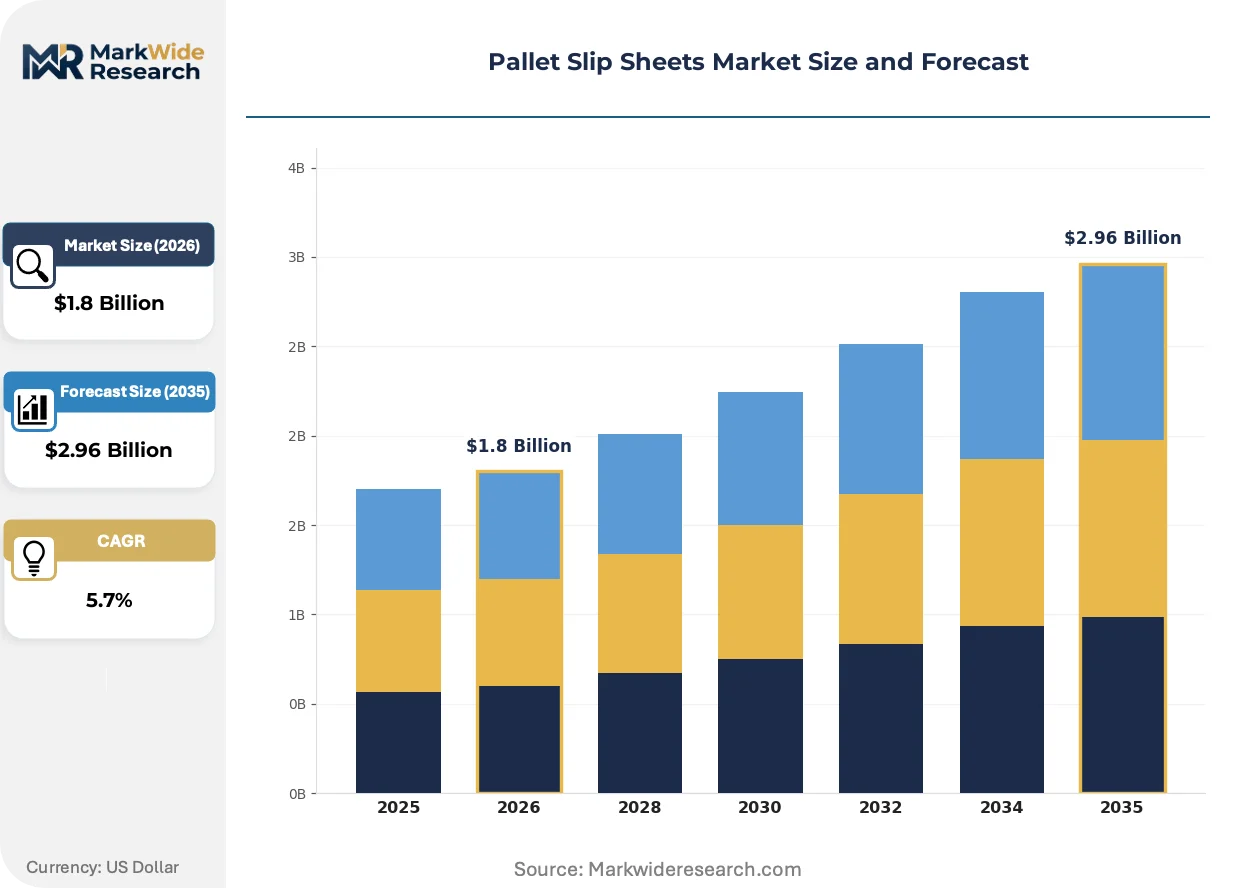
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Paper, Composite, Others End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Material: Polyethylene, Recycled Paper, Wood Fiber, Resin Application: Warehouse, Transportation, Retail, Industrial Packaging |
| Companies Covered | WestRock Company, International Paper, Smurfit Kappa Group, Fresh-Pak Corp, Georgia-Pacific, DS Smith, Sonoco Products Company, Dura-Fibre, LLC, Badger Paperboard, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Slip Sheets Market Strategic Shifts
Material science advances and regulatory compliance requirements are reshaping product specifications across the value chain. Manufacturers now compete on barrier performance and recyclability credentials rather than unit cost alone.
Coated kraft constructions with moisture-resistant polymer layers are integrating into refrigerated logistics workflows. Food and beverage distributors operating automated cold-chain warehouses adopt these hybrid materials at accelerating rates. The technology is integrating previously separate functions—structural support and humidity protection—into single-trip formats that eliminate plastic pallet wrap requirements.
The EU Packaging and Packaging Waste Regulation tightens extended producer responsibility thresholds for material recovery. Industrial converters must demonstrate fiber-based slip sheets meet recyclability standards that polyethylene alternatives cannot satisfy. German automotive exporters and French retail distributors face the most immediate compliance deadlines, driving specification changes in supplier contracts.
Buyer procurement teams now mandate lifecycle carbon accounting in packaging selection criteria. Retail grocery chains and third-party logistics operators weight transport efficiency and end-of-life recyclability above upfront unit cost. This behavioral shift concentrates in Northern European markets where retailer sustainability scorecards determine supplier qualification status.
Pallet Slip Sheets Market Segmentation
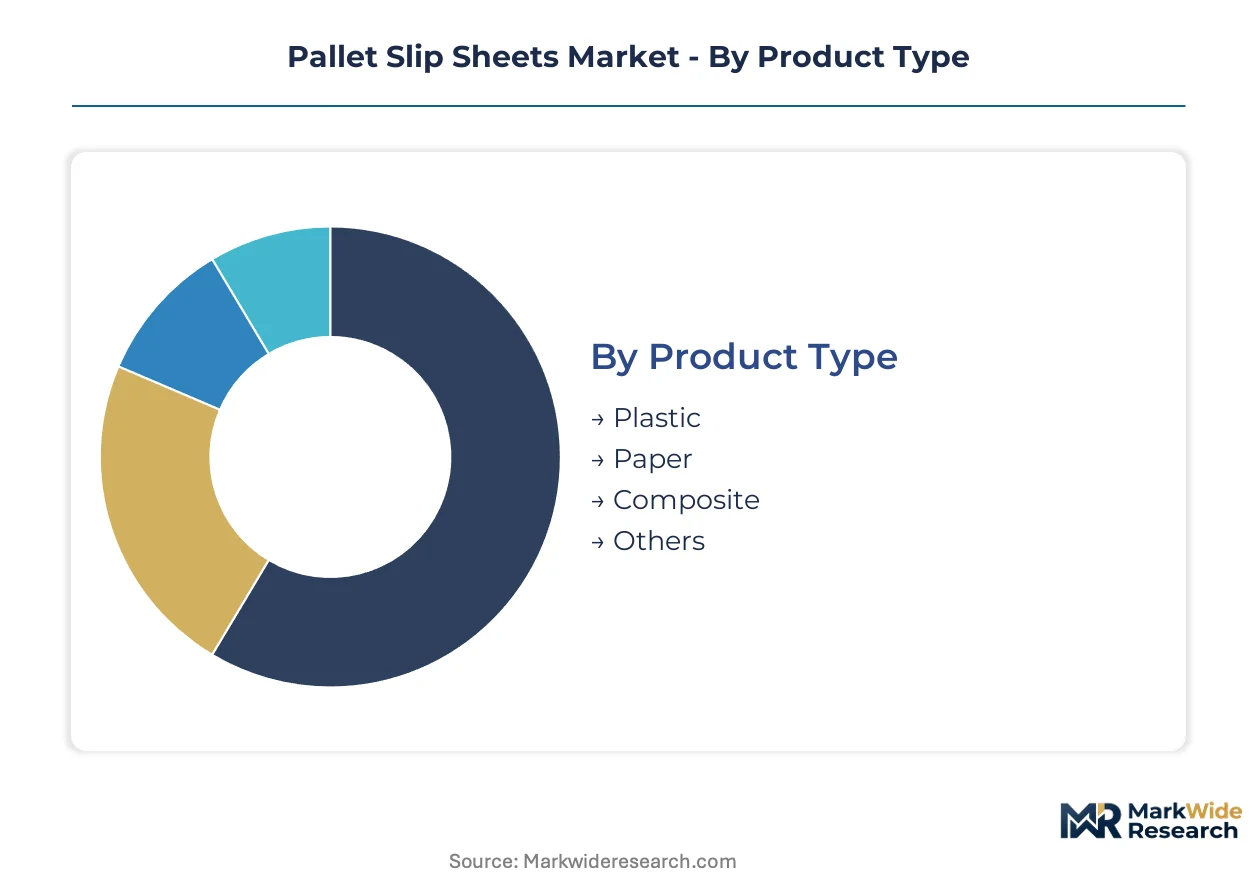
Pallet slip sheet specifications diverge sharply across handling environments and regulatory jurisdictions. Material selection and product architecture determine compatibility with automation infrastructure, moisture exposure, and end-of-life recovery requirements.
Product Type:
Paper-based manufacturing lines demand lower capital intensity than extrusion or composite lamination systems, though coating and barrier treatment equipment raises fixed costs for premium grades.
- Paper:Kraft paperboard constructions range from 0.5 mm to 1.2 mm caliper, with uncoated grades serving dry warehouse applications and polymer-coated variants addressing refrigerated logistics in Germany and France. EU Packaging and Packaging Waste Regulation recyclability thresholds favor this segment in European supply chains.
- Plastic:Oriented polypropylene or polyethylene sheets sustain 50-200 rotation cycles in closed-loop manufacturing plant pools. Capital requirements concentrate in extrusion and orientation equipment, with longer asset lives amortized across captive transport systems.
- Composite:Bonded fiber-resin constructions with moisture barriers and dimensional stability.
- Others:Experimental bio-based and hybrid material formulations.
Most installed capacity flows through Paper. Expansion is steepest in Composite.
End User:
Food and beverage distributors generate the highest shipment volumes, while pharmaceutical and electronics buyers command premium pricing for certified containment performance.
- Food & Beverage:Cold-chain warehouses in Germany and the Netherlands deploy automated layer-picking systems requiring standardized, low-profile unit loads. Coated kraft slip sheets with moisture resistance integrate into refrigerated workflows, eliminating plastic pallet wrap requirements.
- Pharmaceutical:Barrier composites with bonded fiber-resin construction meet dimensional stability requirements for high-value drug shipments. FDA and EMA serialization mandates drive specification rigor.
- Consumer Goods:Mass retail distribution with sustainability scorecard procurement criteria.
- Electronics:Static-dissipative and moisture-protected unit load containment for semiconductors and components.
Procurement volume concentrates in Food & Beverage. Margin expansion is most pronounced in Pharmaceutical.
Material:
Feedstock sourcing strategies separate regional manufacturing footprints, with recycled fiber networks dominating European production and virgin resin supply chains anchoring North American plastic sheet output.
- Recycled Paper:Old corrugated container pricing volatility compresses converter margins during demand spikes. WestRock and International Paper leverage integrated containerboard networks to stabilize input costs.
- Polyethylene:Virgin and recycled resin grades sustain multi-trip rotation cycles in captive manufacturing-to-distribution pools.
- Wood Fiber:Unbleached kraft pulp from sustainable forestry certification programs.
- Resin:Thermoset and thermoplastic binders for composite barrier constructions.
Production volume runs through Recycled Paper. Technology investment is concentrating in Resin.
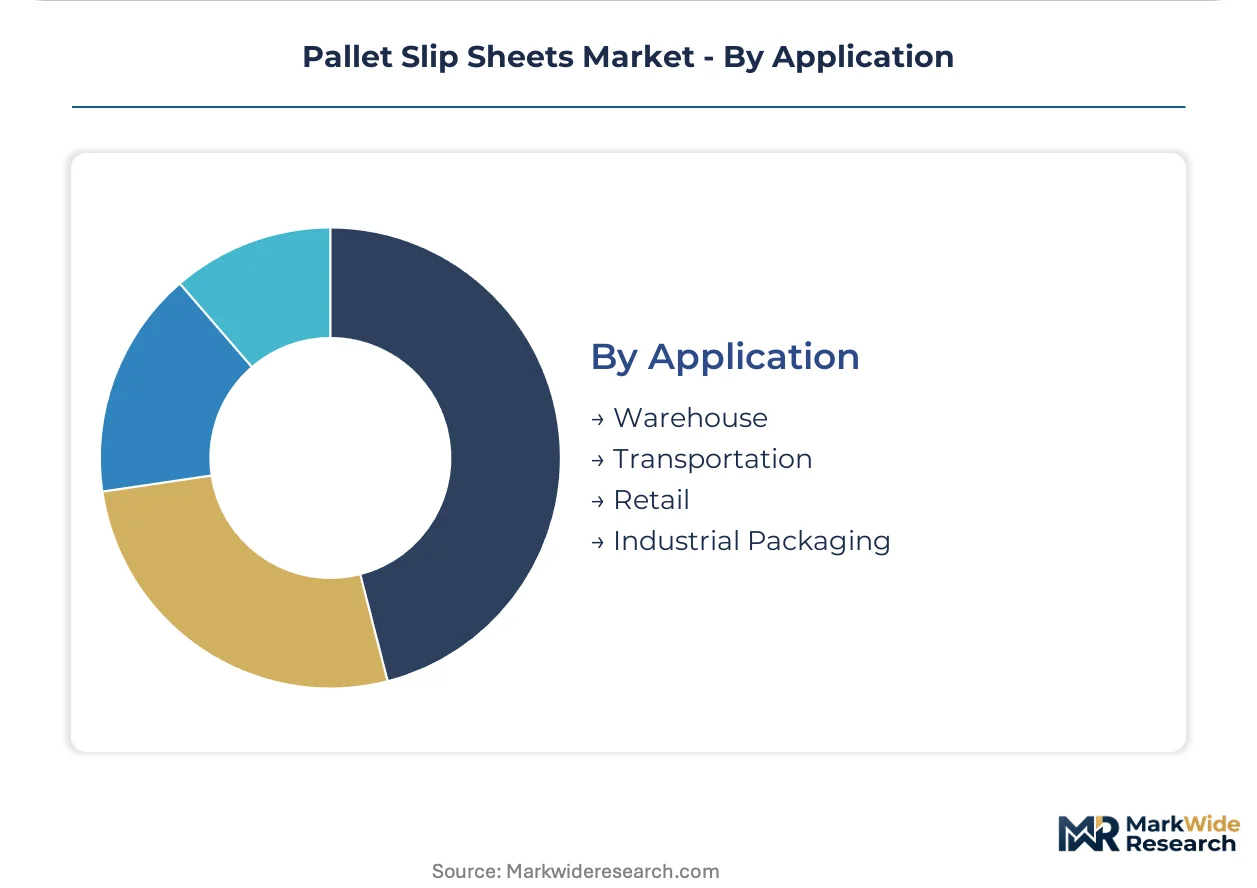
Application:
Automation penetration rates vary dramatically by handling environment, with warehouse and transportation settings requiring distinct equipment retrofit profiles.
- Warehouse:Push-pull attachments and roller conveyor modifications enable forklift-free handling. OSHA manual materials handling standards in US facilities accelerate mechanical load containment adoption, opening retrofit demand for automation-compatible slip sheet systems.
- Transportation:Long-haul freight optimization favors lightweight containment that reduces tare weight and fuel consumption.
- Retail:Single-trip fiber-based formats align with retailer sustainability mandates and downstream recyclability requirements.
- Industrial Packaging:Heavy-load containment for automotive and chemical just-in-time distribution networks.
Equipment deployment concentrates in Warehouse. Infrastructure buildout is advancing most quickly in Transportation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as converters relocate toward jurisdictions with lower compliance costs for fiber-based packaging. Production migration concentrates where recycled fiber networks intersect with automation-ready logistics infrastructure.
Germany
Automotive and chemical exporters in Baden-Württemberg and North Rhine-Westphalia operate dense just-in-time networks that eliminate pallet exchange cycles. The EU Packaging and Packaging Waste Regulation imposes immediate recyclability thresholds that favor kraft paperboard over polyethylene alternatives. Stuttgart's automotive cluster drives specification rigor for high-frequency handling systems.
United States
Cold-chain warehouse automation in Chicago and Dallas-Fort Worth accelerates push-pull system deployment for layer-picking operations. OSHA manual materials handling standards indirectly mandate mechanical load containment in distribution facilities. The EPA's Sustainable Materials Management program promotes source reduction through lightweight unit-load formats.
France
Retail grocery distributors in the Île-de-France region weight sustainability scorecards above upfront unit cost in procurement decisions. The EU Green Deal tightens extended producer responsibility timelines for packaging recovery. Paris-area logistics hubs specify coated kraft slip sheets for refrigerated workflows.
China
E-commerce fulfillment center buildout in the Yangtze River Delta and Pearl River Delta creates demand for standardized low-profile unit loads. The country's national environmental regulator advances dual carbon goals that favor lightweight transport packaging. Shanghai's automated warehouse cluster tests hybrid fiber-resin composites for moisture-sensitive electronics shipments.
India
Food and beverage cold-chain infrastructure expansion in Maharashtra and Gujarat opens first-mover positioning for coated kraft formats. The Bureau of Indian Standards develops packaging material specifications aligned with international recyclability benchmarks. Mumbai's temperature-controlled distribution networks pilot slip-sheet handling for pharmaceutical exports.
Pallet Slip Sheets Market Competitive Environment
Capacity expansion dominates the current landscape as integrated containerboard producers scale coating and barrier treatment lines to capture refrigerated logistics demand. The vendor base stratifies between multinational paperboard conglomerates with captive fiber supply and regional converters serving captive manufacturing-to-distribution pools. Three archetypes define competitive positioning: integrated pulp-to-sheet operators, specialized barrier composite fabricators, and regional kraft converters. Geographic expansion and portfolio diversification toward moisture-resistant grades represent the dominant competitive vectors.
Among North American integrated producers, WestRock Company and International Paper exemplify scale-driven archetypes with containerboard network control, while Smurfit Kappa Group anchors European positioning through regional mill integration. These three entities represent divergent feedstock strategies—recycled fiber network density versus virgin kraft pulp integration—that shape regional cost structures and sustainability credentialing.
| Leading Market Players |
|---|
| WestRock Company |
| International Paper |
| Smurfit Kappa Group |
| Fresh-Pak Corp |
| Georgia-Pacific |
| DS Smith |
| Sonoco Products Company |
| Dura-Fibre, LLC |
| Badger Paperboard, Inc. |
| Others |
Value Chain & Pricing Dynamics
Coating line automation in kraft paperboard mills simultaneously compresses per-unit conversion costs and consolidates supplier power among integrated containerboard producers. The EU Packaging and Packaging Waste Regulation accelerates capital deployment toward barrier-treatment capabilities, reshaping cost economics for moisture-resistant grades while squeezing regional converters without captive fiber networks.
Pricing Analysis
Distributor margins on coated kraft slip sheets run 12-18 points above direct-to-automotive-OEM contracts that bypass intermediaries. Three-tier pricing structure across premium barrier composites, standard coated kraft, and economy uncoated grades separates pharmaceutical certification tiers from mass retail procurement. Price differentiation hinges on moisture resistance certification and volume scale, with cold-chain distributors least sensitive and commodity dry-goods buyers most responsive to unit cost. Cost compression in standard grades is intensifying because recycled old corrugated container prices spike during packaging demand cycles without full pass-through mechanisms.
Supply Chain Analysis
Freight cost differentials between German mill clusters and peripheral European markets favor on-site converting at major logistics hubs. Supply concentrates in Germany, the United States, and China, with recycled fiber networks anchoring European production and virgin resin supply chains anchoring North American plastic sheet output. Raw material dependencies draw from old corrugated containers, polyethylene resin, and thermoplastic barrier coatings. Single-source vulnerability concentrates in specialized polymer coating additives sourced from limited chemical suppliers. Distribution runs through integrated paperboard conglomerates with direct OEM contracts and regional converters serving captive manufacturing-to-distribution pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pallet Slip Sheets Market functions as a regulatory compounder where EU Green Deal packaging mandates create structural demand shifts favoring fiber-based containment systems.
For Market Incumbents: Deepen backward integration into recycled fiber networks to stabilize input cost volatility that compresses margins during demand spikes. Invest in coating line capacity at German and US mill clusters to capture refrigerated logistics demand before regional converters achieve barrier-treatment capabilities. The threat of polypropylene substitution in closed-loop manufacturing pools limits fiber-based penetration, making moisture performance certification the critical defensive lever. For New Entrants and Emerging Players: Automated layer-picking compatibility offers a technology-first wedge into cold-chain warehouse retrofit demand where incumbent paperboard producers lack specialized push-pull system expertise. Target Indian pharmaceutical export corridors where temperature-controlled distribution infrastructure buildout creates first-mover positioning for coated kraft formats. Pursue direct partnerships with forklift attachment manufacturers to bundle slip-sheet supply with equipment retrofit packages. For Investors and Strategic Acquirers: Valuations sit cheapest among regional kraft converters without captive fiber supply but with established automotive OEM relationships. The five-to-ten year viability window favors acquisition of barrier composite fabricators with FDA and EMA certification pathways already established. Watch for inflection when German automotive exporters accelerate just-in-time network specifications toward high-frequency pallet elimination.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Capacity Expansion | Captures EU PPWR-compliant demand from refrigerated logistics operators in Germany and France. |
| Recycled Fiber Network Integration | Stabilizes input cost exposure to old corrugated container price volatility across European production. |
| Push-Pull Equipment Partnership | Accelerates warehouse automation retrofit adoption through bundled slip-sheet and handling system offerings. |
| Pharmaceutical Certification Investment | Unlocks premium positioning in FDA and EMA serialization-mandated drug distribution networks. |
| India Cold-Chain Joint Venture | Establishes localized coated kraft production ahead of Bureau of Indian Standards packaging specifications. |
Study Parameters
Coverage spans Germany, the United States, France, China, and India, with primary inputs from each market combining interviews with plant managers at containerboard mills, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors at barrier coating suppliers. Secondary validation draws from EU regulatory filings, EPA Sustainable Materials Management documentation, SEC 10-K disclosures from integrated paperboard producers, and customs trade data on kraft paperboard imports. Bottom-up shipment estimates triangulate against top-down demand modeling from end-use industry consumption patterns.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions include material type, end-use industry, application environment, and regional regulatory cluster. CAGRs derive from logistic adoption curves for warehouse automation infrastructure and regulatory compliance timelines. Industry-specific forecast inputs incorporate EU PPWR implementation schedules and OSHA manual materials handling enforcement patterns.
The model holds under sustained warehouse automation investment and stable recycled fiber supply; deviation in coating additive shortages or push-pull equipment adoption delays would shift volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Displays Market
Pallets Packaging
Germany Pallets Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Corrugated Pallet Wrap Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
Pallet Pooling Market