
 Block Pallets Market | 2026-2036
Block Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Block Pallets Market Outlook
Buyer concentration among large retail chains and third-party logistics providers is hardening procurement standards across the Block Pallets Market. Brambles (CHEP) leverages its pooled pallet network to sustain dominant coverage in fast-moving consumer goods supply chains. PalletOne anchors North American manufacturing through extensive hardwood sourcing and regional mill infrastructure. CABKA Group differentiates by specializing in plastic block pallets derived from post-consumer recycled polymers.
Block pallets are flat transport structures built with solid columnar supports at corners and center points, typically measuring 1200 mm by 1000 mm for Euro-compatible logistics, designed to withstand forklift entry from four sides and racking loads exceeding 1,500 kg. Their primary purpose is stabilizing unitized cargo during storage, handling, and intermodal transit. Wooden block pallets retain the largest volume share across export applications due to low material cost and straightforward ISPM-15 heat treatment compliance, though plastic block pallets are capturing share in pharmaceutical and food-grade closed-loop systems where hygiene validation and washdown compatibility command premium positioning. Heavy-duty grades concentrate margin pools in automotive and chemical manufacturing, while light-duty variants face commoditization in single-use retail display roles.
EPA regulations on methyl bromide and chromium-copper-arsenate wood treatments are restricting conventional hardwood pallet production in the United States, pushing buyers toward certified heat-treated or alternative material platforms. The European Union's REACH framework and F-Gas Regulation indirectly shape plastic pallet resin specifications and recycling accountability across member states. Stakeholders must monitor evolving packaging waste directives and carbon border adjustment mechanisms to align material sourcing decisions with compliance thresholds and total cost of ownership benchmarks.
Market Dynamics
ISPM-15 heat treatment mandates and EPA chemical restrictions are compressing traditional hardwood pallet supply while pulling capital toward plastic and composite alternatives across export logistics networks.
Growth Catalysts
- ISPM-15 export compliance:International phytosanitary standards require heat-treated wooden pallets for cross-border shipments, standardizing block pallet specifications across Germany, the United States, and Brazil.
- Food-grade hygiene mandates:FDA washdown requirements and EU food contact material regulations are accelerating plastic block pallet adoption in pharmaceutical cold chains and dairy distribution.
- Automotive supplier clustering:Dense manufacturing corridors in Stuttgart, Wolfsburg, and Detroit generate concentrated demand for heavy-duty block pallets rated above 1,500 kg racking loads.
Market Restraints
- Resin price volatility:Post-consumer recycled polymer feedstock costs fluctuate with crude oil benchmarks and collection infrastructure gaps, squeezing margins for plastic block pallet producers.
- Hardwood supply concentration:Appalachian oak and southern yellow pine harvesting face EPA logging restrictions and seasonal procurement bottlenecks, limiting untreated wood pallet expansion.
- Steel-reinforced composite limitations:Embedded metal components complicate end-of-life recycling under EU packaging waste directives, creating circularity friction versus pure polymer alternatives.
Strategic Opportunities
- Indian pharmaceutical export corridors:CDSCO cold chain validation requirements and rising biologics shipments from Hyderabad and Pune create demand for hygienic, trackable plastic block pallets.
- Pallet-as-a-service models:Third-party logistics providers are deploying IoT-enabled pooling networks that shift capital expenditure from buyer balance sheets to per-trip usage fees.
- Carbon border adjustment alignment:EU CBAM scope expansion into embodied packaging emissions rewards block pallets with verified lifecycle carbon data and recycled content certification.
Industry Challenges
- RFID integration complexity:Embedding durable tracking tags into block pallet cores without compromising structural integrity requires specialized welding and encapsulation expertise that remains scarce.
- Multi-standard certification timelines:Simultaneous compliance with ISO 8611 load testing, FDA food contact, and REACH substance restrictions extends product development cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Block Pallets Market |
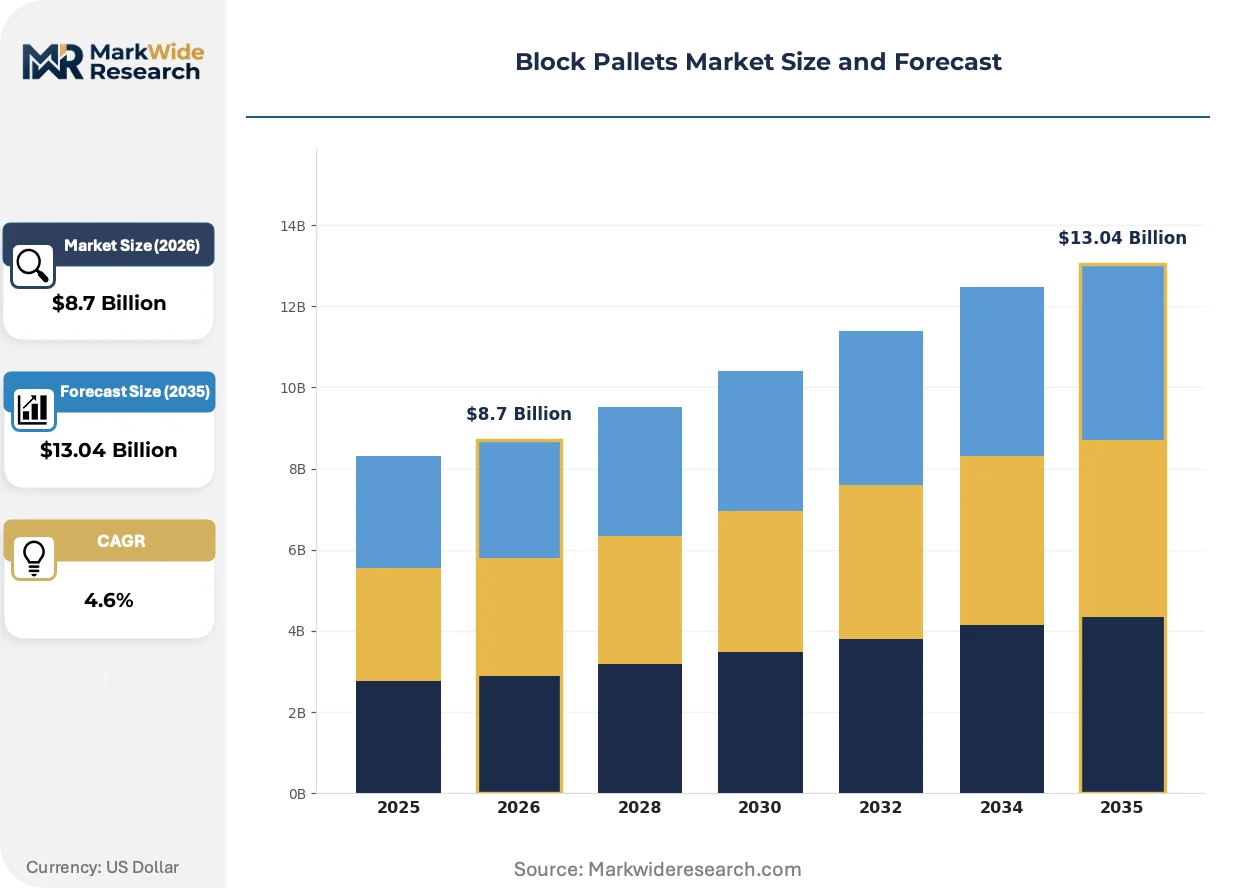
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Block Pallets, Plastic Block Pallets, Metal Block Pallets, Composite Block Pallets End User: Food & Beverage, Pharmaceuticals, Retail, Manufacturing Grade: Heavy Duty, Medium Duty, Light Duty, Industrial Grade Application: Storage, Transportation, Display, Export |
| Companies Covered | Brambles (CHEP), PalletOne, PGS Group, Loscam, CABKA Group, Litco International, Millwood, Schoeller Allibert, PECO Pallet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Block Pallets Market Strategic Shifts
Material science advances and regulatory pressure on chemical wood treatments are converging to redefine block pallet performance benchmarks and circularity expectations across supply chains.
High-density polyethylene block pallets manufactured from post-consumer milk jugs and detergent bottles are expanding into pharmaceutical distribution and fresh produce logistics. Cold chain operators in the Netherlands and California are adopting these units for their moisture resistance and steam-cleaning compatibility. This material transition is compressing the addressable market for chemically treated hardwood alternatives in hygiene-sensitive applications.
REACH substance restrictions and the EU F-Gas Regulation are tightening specifications for plastic pallet resins and foam blowing agents used in insulated variants. Manufacturers must reformulate polymer blends to eliminate restricted phthalates and heavy metal stabilizers while maintaining impact resistance. German automotive suppliers and French food processors face the steepest compliance deadlines under the 2025 REACH evaluation roadmap.
Buyers are consolidating vendor relationships around full-service pallet pooling contracts that bundle supply, retrieval, washing, and repair into per-use fees. Retail chains and beverage distributors in the United States are displacing outright purchase models with CHEP and PECO managed programs. This contractual shift concentrates procurement authority among large third-party logistics providers and compresses margins for standalone manufacturers.
Block Pallets Market Segmentation
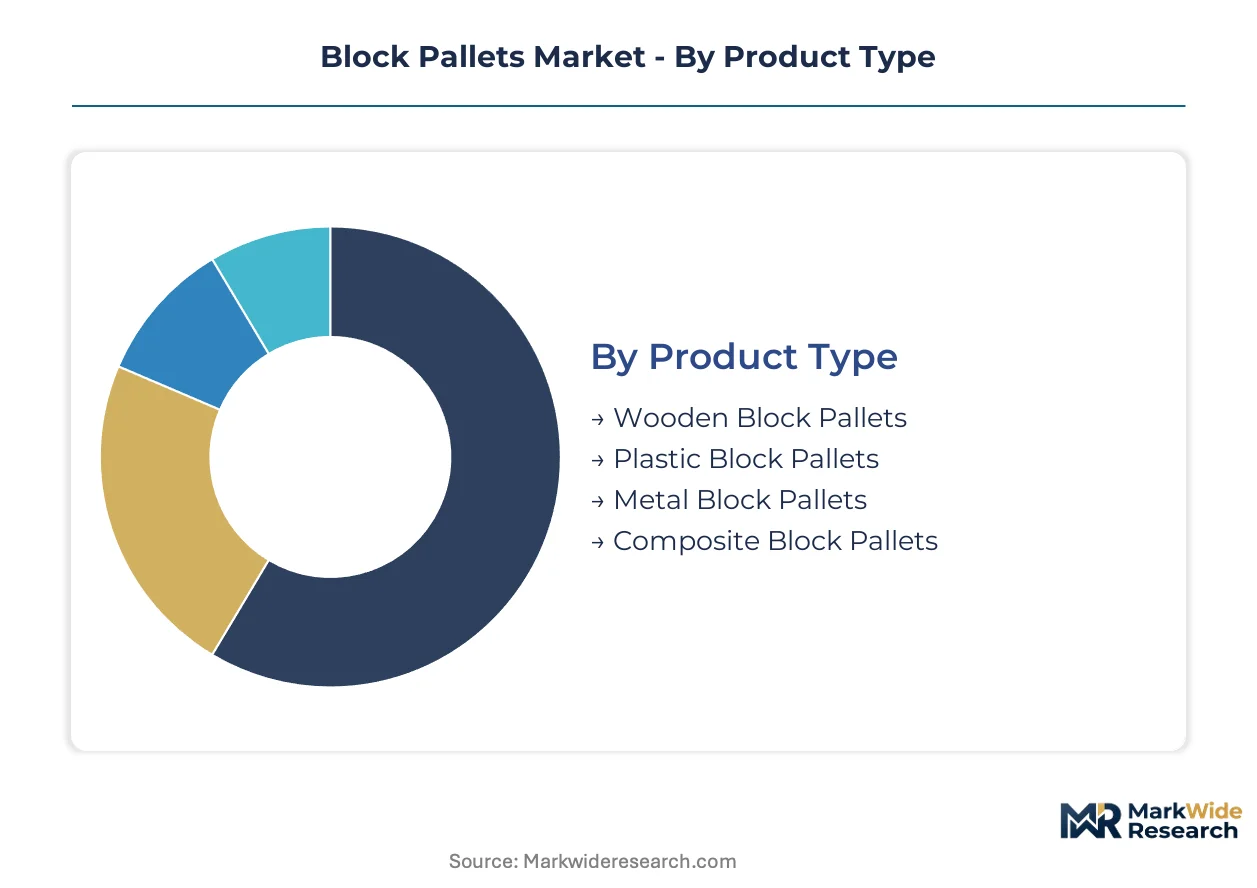
Block pallet procurement decisions pivot on load-bearing requirements, hygiene mandates, and lifecycle cost calculations across closed-loop versus single-use deployment scenarios. Segmentation reveals how material science advances and regulatory pressures are redrawing competitive boundaries between incumbent hardwood platforms and emerging polymer alternatives.
Product Type:
Customization intensity varies sharply across this category, from commodity hardwood specifications to engineered polymer formulations requiring resin certification and mold precision.
- Wooden Block Pallets:Constructed from Appalachian oak or southern yellow pine with heat-treated cores meeting ISPM-15 phytosanitary standards for cross-border shipments. Demand concentrates in export corridors from Germany and Brazil where compliance documentation carries legal liability, though EPA restrictions on chemical wood treatments are compressing untreated hardwood supply.
- Plastic Block Pallets:Injection-molded from high-density polyethylene or polypropylene resins, often incorporating post-consumer recycled content for carbon accounting. Adoption is accelerating in pharmaceutical cold chains and dairy distribution networks across the Netherlands and California where FDA washdown requirements and moisture resistance command premium positioning.
- Metal Block Pallets:Fabricated from galvanized steel or aluminum for extreme load environments exceeding 2,000 kg static capacity. Concentrated in automotive stamping plants and heavy machinery distribution where durability outweighs unit cost.
- Composite Block Pallets:Hybrid constructions combining wood fibers with polymer binders or embedded steel reinforcement. Deployment is limited by end-of-life recycling friction under EU packaging waste directives.
Most installed capacity flows through Wooden Block Pallets. Expansion is steepest in Plastic Block Pallets.
End User:
Cost tier stratification separates capital-intensive hygiene-validated applications from price-sensitive retail display logistics.
- Food & Beverage:Pooled pallet networks dominate beverage distribution and fresh produce logistics, with CHEP and PECO managing retrieval and washdown cycles. FDA food contact material regulations and EU food-grade mandates are displacing chemically treated wood in dairy and protein cold chains.
- Pharmaceuticals:CDSCO cold chain validation requirements in India and EU GDP guidelines are driving demand for trackable, hygienic plastic pallets with embedded RFID and temperature logging capabilities. Hyderabad and Pune export corridors represent concentrated growth nodes.
- Retail:Single-use light-duty pallets for in-store display and promotional staging, facing margin compression from corrugated alternatives and sustainability scorecard pressures.
- Manufacturing:Heavy-duty block pallets rated for 1,500 kg+ racking loads in automotive supplier clusters around Stuttgart, Wolfsburg, and Detroit, with just-in-time delivery requirements dictating pooling contract terms.
Volume leadership sits with Food & Beverage. The steepest expansion trajectory belongs to Pharmaceuticals.
Grade:
Application maturity determines margin structure, with industrial specifications capturing value through certification burden and performance guarantees.
- Heavy Duty:Engineered for 1,500-2,500 kg dynamic loads and four-way forklift entry with steel reinforcement or dense hardwood cores. Demand clusters in chemical manufacturing and automotive component logistics where racking failure carries operational shutdown risk.
- Medium Duty:Standard 1,000-1,200 kg capacity for general warehousing and distribution, representing the commoditized volume core of pallet pooling fleets.
- Light Duty:Single-trip or limited-reuse specifications for retail display and lightweight consumer goods, facing displacement from collapsible plastic crates and slip-sheet systems.
- Industrial Grade:Custom-engineered platforms with anti-static coatings, fire-retardant additives, or conductive properties for electronics and hazardous material handling, commanding specification premiums through ISO 8611 load testing documentation.
Pooling fleet investment concentrates in Medium Duty. Industrial Grade is gaining share fastest through specification creep in regulated sectors.
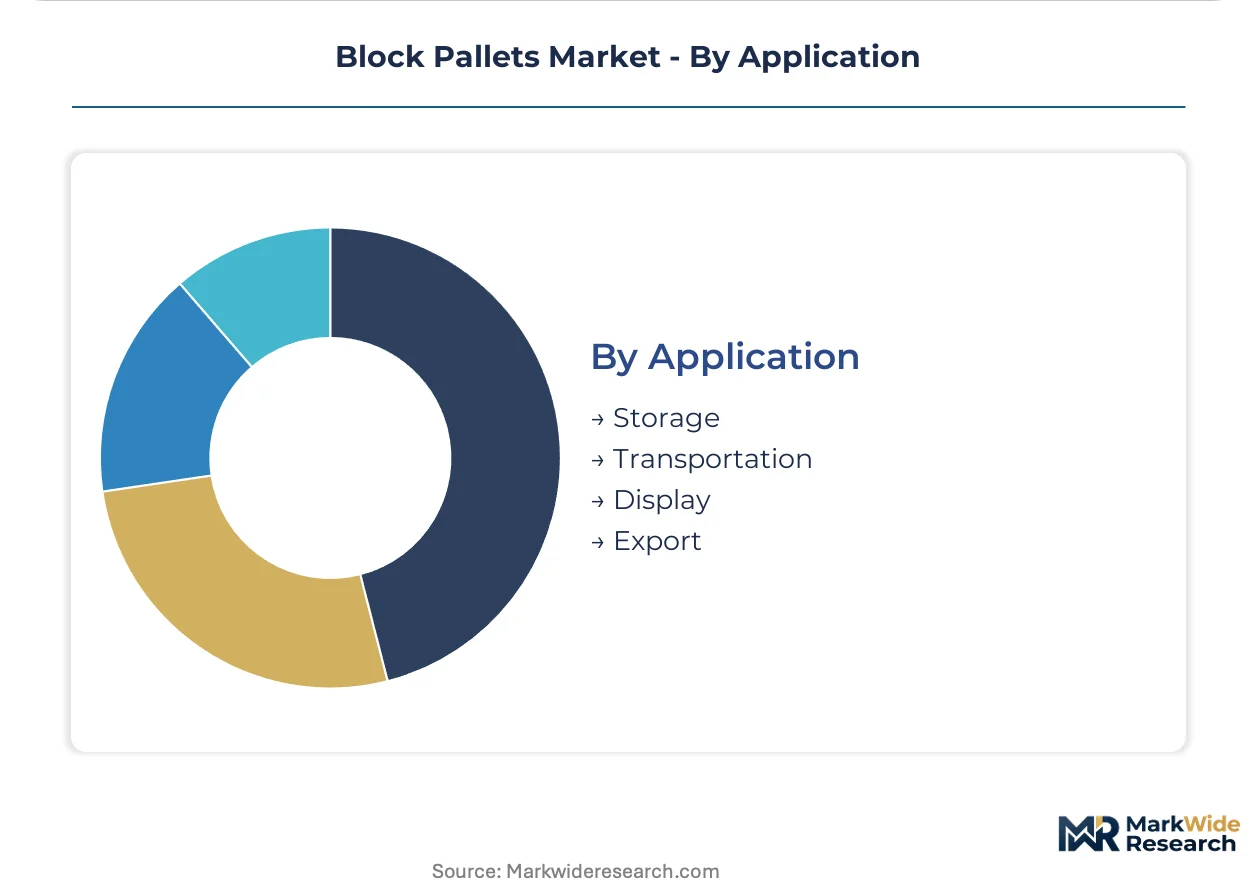
Application:
Customer type separation distinguishes asset-owning operators from third-party logistics providers managing pallet-as-a-service contracts.
- Storage:Block pallets optimized for static racking loads and warehouse automation compatibility, with dimensional precision requirements for automated storage and retrieval systems in German and US distribution centers.
- Transportation:Dynamic load specifications for over-road and intermodal transit, with CHEP and PECO pooling networks dominating North American fast-moving consumer goods supply chains through per-trip pricing models.
- Display:Aesthetic-grade finishes and retail-ready dimensions for in-store merchandising, typically light-duty construction with higher unit margins offset by limited reuse cycles.
- Export:ISPM-15 heat treatment certification and IPPC marking requirements for wooden pallets, with plastic alternatives exempt from phytosanitary documentation but facing higher upfront capital costs.
Transportation commands the largest installed base. Display applications are climbing the fastest as retail media networks expand in-store promotional infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier density generates heavier block pallet specifications than Brazil's export agriculture corridors, yet both markets face tightening phytosanitary documentation requirements that reshape procurement patterns.
United States
Food and beverage distribution networks in California and the Midwest are expanding pallet pooling programs at scale. EPA restrictions on methyl bromide and chromium-copper-arsenate wood treatments are compressing untreated hardwood supply, pushing buyers toward certified heat-treated or alternative material platforms. The Detroit automotive corridor generates concentrated demand for heavy-duty block pallets rated above 1,500 kg for just-in-time component delivery.
Germany
Dense automotive supplier clustering around Stuttgart and Wolfsburg drives specification-heavy procurement for racking-stable platforms. REACH substance restrictions and the EU F-Gas Regulation are tightening resin specifications for plastic pallet alternatives, forcing reformulation of polymer blends to eliminate restricted phthalates. ISPM-15 export compliance requirements from Hamburg and Bremerhaven ports standardize documentation burdens across wooden pallet supply chains.
Brazil
Agricultural export corridors from São Paulo and Paraná rely on ISPM-15 heat-treated wooden block pallets for soy and protein shipments. ANVISA hygiene mandates are accelerating plastic pallet trials in pharmaceutical distribution from the São Paulo metro area. Seasonal harvesting cycles create demand spikes that strain regional hardwood treatment capacity.
India
CDSCO cold chain validation requirements and rising biologics shipments from Hyderabad and Pune are creating demand for hygienic, trackable plastic block pallets. The country's national pharmaceutical regulator is tightening distribution standards for temperature-sensitive exports. Western Maharashtra's manufacturing belt is emerging as a concentrated node for pooled pallet deployment in generics logistics.
Netherlands
Rotterdam's port logistics and dense fresh produce distribution networks are adopting high-density polyethylene block pallets for moisture resistance and steam-cleaning compatibility. EU packaging waste directives are creating circularity friction for steel-reinforced composite alternatives. The Randstad distribution cluster is consolidating vendor relationships around full-service pooling contracts that bundle washing and repair cycles.
Block Pallets Market Competitive Environment
North American producers anchor the pooled network tier; European specialists hold the engineered polymer segment. The vendor base separates into asset-heavy pooling operators, regional hardwood fabricators, and resin-focused molders. Three archetypes dominate: pallet-as-a-service platforms, post-consumer recycled polymer specialists, and automotive-grade heavy-duty manufacturers. Competitive moves concentrate on IoT-enabled tracking integration and backward integration into resin collection infrastructure.
Within the pooling operator tier, Brambles (CHEP) and PECO Pallet exemplify asset-heavy platforms that shift capital expenditure from buyer balance sheets to per-trip usage fees. Among European-based molders, CABKA Group occupies a position representing the post-consumer recycled polymer archetype. PalletOne anchors the North American hardwood fabrication tier through extensive regional mill infrastructure. These three names illustrate how geographic origin and company structure align with divergent strategic postures across material platforms.
| Leading Market Players |
|---|
| Brambles (CHEP) |
| PalletOne |
| PGS Group |
| Loscam |
| CABKA Group |
| Litco International |
| Millwood |
| Schoeller Allibert |
| PECO Pallet |
| Others |
Value Chain & Pricing Dynamics
Post-consumer recycled polymer injection molding is compressing unit economics for plastic block pallets while simultaneously concentrating production capacity among resin-integrated molders in Germany and the Netherlands. This technological shift simultaneously lowers per-unit material costs and raises barriers for hardwood-dependent fabricators facing EPA chemical restrictions and ISPM-15 compliance documentation burdens.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for plastic block pallets as post-consumer recycled resin supply expands. Pricing stratifies across premium, standard, and economy tiers based on FDA food contact certification level and volume scale under pooling contracts. Cost compression in light-duty wooden pallets is intensifying because untreated hardwood supply faces EPA logging restrictions. Retail chains exhibit highest price sensitivity, while pharmaceutical cold chain operators accept premium positioning for washdown-compatible platforms.
Supply Chain Analysis
Direct-to-OEM channels handle automotive sector demand for heavy-duty specifications above 1,500 kg racking loads, while third-party pooling networks serve fast-moving consumer goods distribution. Supply concentrates in the United States, Germany, and Brazil, with raw material dependencies spanning Appalachian oak, southern yellow pine, and post-consumer HDPE feedstock. Single-source vulnerability in heat-treatment certification capacity creates bottlenecks during seasonal export surges. Distribution runs through CHEP and PECO managed fleets in North America, with regional hardwood fabricators serving spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Block Pallets Market functions as a geographic-arbitrage play where EU REACH compliance costs in Germany create cost disadvantages against US producers supplying heat-treated hardwood to shared export corridors.
For Market Incumbents: Deepen backward integration into post-consumer resin collection infrastructure to secure feedstock cost advantages against oil-price volatility. Expand heat-treatment certification capacity in the United States ahead of EPA restrictions on chemical wood treatments. Prioritize IoT-enabled tracking integration to defend pooling contract renewals against emerging pallet-as-a-service platforms. For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical-grade plastic pallets opens white-space targeting of Indian CDSCO-compliant cold chain corridors from Hyderabad and Pune. Brazil's ANVISA hygiene mandates create penetrable entry points for moisture-resistant alternatives to chemically treated wood. Lead with per-trip usage fee models to displace capital-intensive purchase decisions among mid-size logistics providers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional hardwood fabricators lacking pooling network integration or resin molding capabilities. Long-term viability across the analysis window favors asset-light technology platforms over capital-intensive mill operations. Monitor EU carbon border adjustment mechanism scope expansion into embodied packaging emissions as the critical inflection signal for material platform switching.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Collection | Captures post-consumer HDPE feedstock cost advantage against crude oil price volatility. |
| ISPM-15 Certification Capacity Expansion | Secures export corridor access for wooden pallet supply to Germany and Brazil. |
| IoT-Enabled Pooling Network Deployment | Shifts buyer economics from capital expenditure to per-trip usage fees. |
| Pharmaceutical Cold Chain Specialization | Captures premium positioning under FDA washdown and CDSCO validation requirements. |
| EU Carbon Border Adjustment Alignment | Positions recycled content platforms for competitive advantage under embodied emissions accounting. |
Study Parameters
Multiple input streams — procurement director interviews at retail chains and third-party logistics providers, plant manager surveys at hardwood treatment facilities, and regulatory filing analysis — were reconciled to construct demand and supply estimates. Primary fieldwork engaged pallet pooling operators, automotive supplier procurement teams, and pharmaceutical distribution executives across the United States, Germany, India, and Brazil. Secondary validation drew from EPA regulatory dockets, EU REACH substance restriction updates, CDSCO cold chain guidelines, and customs trade data for ISPM-15 marked wooden pallet movements. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level estimates.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated material platform, end-use industry, grade specification, and geographic regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Forecast inputs included resin price volatility indices, automotive production forecasts for Stuttgart and Detroit corridors, and biologics export growth from Indian pharmaceutical clusters.
The model assumes a particular technology adoption path; alternative pathways for RFID-embedded tracking integration would alter the outlook for pooling network economics and manufacturer margin structures. Forecasts reflect assumptions regarding EPA enforcement intensity on chemical wood treatments and EU packaging waste directive implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
Middle East Pallets Market
Pallets Packaging
North America Pallet Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Foldable Pallet Container Market