
 Mexico Pallets Market | 2026-2036
Mexico Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Pallets Market Insights
Buyer concentration among automotive and electronics manufacturers is decoupling from traditional pallet ownership models toward pooled leasing arrangements. Brambles Limited (CHEP) leverages its circular pooling infrastructure to anchor fleet density across northern Mexico's manufacturing belt. Schoeller Allibert competes through reusable plastic crate-to-pallet systems designed for pharmaceutical cold chains. CABKA Group specializes in recycled polymer pallets, positioning its closed-loop resin recovery as a compliance advantage under tightening environmental rules.
A pallet is a portable platform, typically constructed from wood slats, plastic resin, or metal, designed to support goods during lifting by forklift or pallet jack and to enable unitized load transport. Standard dimensions of 48 by 40 inches dominate North American cross-border trade, with heat-treated hardwood construction required for phytosanitary compliance. Wood material type retains the largest volume share due to low first cost and repairability, though plastic pallet demand accelerates fastest in pharmaceutical and electronics end user industries where hygiene and dimensional consistency command premium positioning. Rackable product types capture higher margins in automated warehouse environments, while nestable designs reduce empty-backhaul costs for third-party logistics providers operating across Mexico's central plateau distribution corridors.
SEMARNAT enforces NOM-144 treatment standards for wood packaging in international commerce, directly shaping material selection and supplier certification requirements for export-oriented manufacturers. Mexico's Federal Commission for the Protection against Sanitary Risk (COFEPRIS) imposes traceability mandates on pharmaceutical logistics that elevate plastic pallet specifications over untreated wood alternatives. Stakeholders must monitor whether proposed amendments to the General Law for Prevention and Integral Management of Waste extend producer responsibility obligations to pallet recovery systems, a shift that would reshape leasing economics and material substitution timelines across the sector.
Market Dynamics
Nearshoring-driven manufacturing concentration across Mexico's central corridor is compressing pallet fleet turnover cycles and forcing pooled asset models to displace traditional ownership structures. Automotive and aerospace suppliers now demand just-in-time availability with full traceability compliance.
Growth Catalysts
- Automotive supplier clustering:BMW's San Luis Potosí assembly hub and its tier-one supplier parks generate concentrated pallet demand with standardized 48-by-40-inch specifications. Tier-one component manufacturers are converting to CHEP-managed pooling contracts to eliminate capital tie-up.
- NOM-144-SEMARNAT-2004 enforcement:Mandatory heat-treatment certification for cross-border wood packaging is accelerating supplier consolidation toward certified treaters. Export-oriented manufacturers face shipment holds without compliant documentation.
- Querétaro logistics corridor density:Foreign manufacturers clustering around the state's aerospace and electronics parks create route density that justifies automated pallet depots and rapid exchange pools.
Market Restraints
- Resin price volatility:Recycled polymer feedstock costs fluctuate with petrochemical benchmarks, compressing margins for plastic pallet producers serving pharmaceutical cold chains.
- Hardwood supply concentration:Heat-treated pine and oak sourcing concentrates in Michoacán and Chihuahua sawmills, exposing pallet manufacturers to regional weather disruptions and transport bottlenecks.
- COFEPRIS traceability mandates:Pharmaceutical logistics rules require lot-level pallet tracking that untreated wood cannot satisfy, structurally excluding domestic wood pallet suppliers from high-margin segments.
Strategic Opportunities
- Baja California medical device corridor:Tijuana and Mexicali maquiladoras serving US FDA-regulated customers lack adequate plastic pooling infrastructure, creating first-mover advantage for certified cold-chain pallet providers.
- Closed-loop resin recovery systems:Proposed amendments to Mexico's General Law for Prevention and Integral Management of Waste may extend producer responsibility to packaging, positioning recycled polymer pallet operators for regulatory preference.
- RFID-embedded pallet convergence:Integration of passive RFID tags with rackable plastic pallets enables real-time inventory visibility that automotive OEMs now specify in supplier contracts.
Industry Challenges
- Heat-treatment certification backlog:SEMARNAT-accredited facilities face inspection queue delays of 6-8 weeks, forcing exporters to maintain buffer inventory or risk shipment detention at US and Canadian ports.
- Legacy ERP integration friction:Third-party logistics providers operating mixed wood-plastic fleets struggle to reconcile CHEP, IFCO, and proprietary pooling systems within single warehouse management platforms.
- Skilled technician scarcity:Automated pallet repair and quality-sorting equipment requires mechatronics expertise that technical institutes in Guanajuato and Nuevo León have not scaled to meet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Pallets Market |
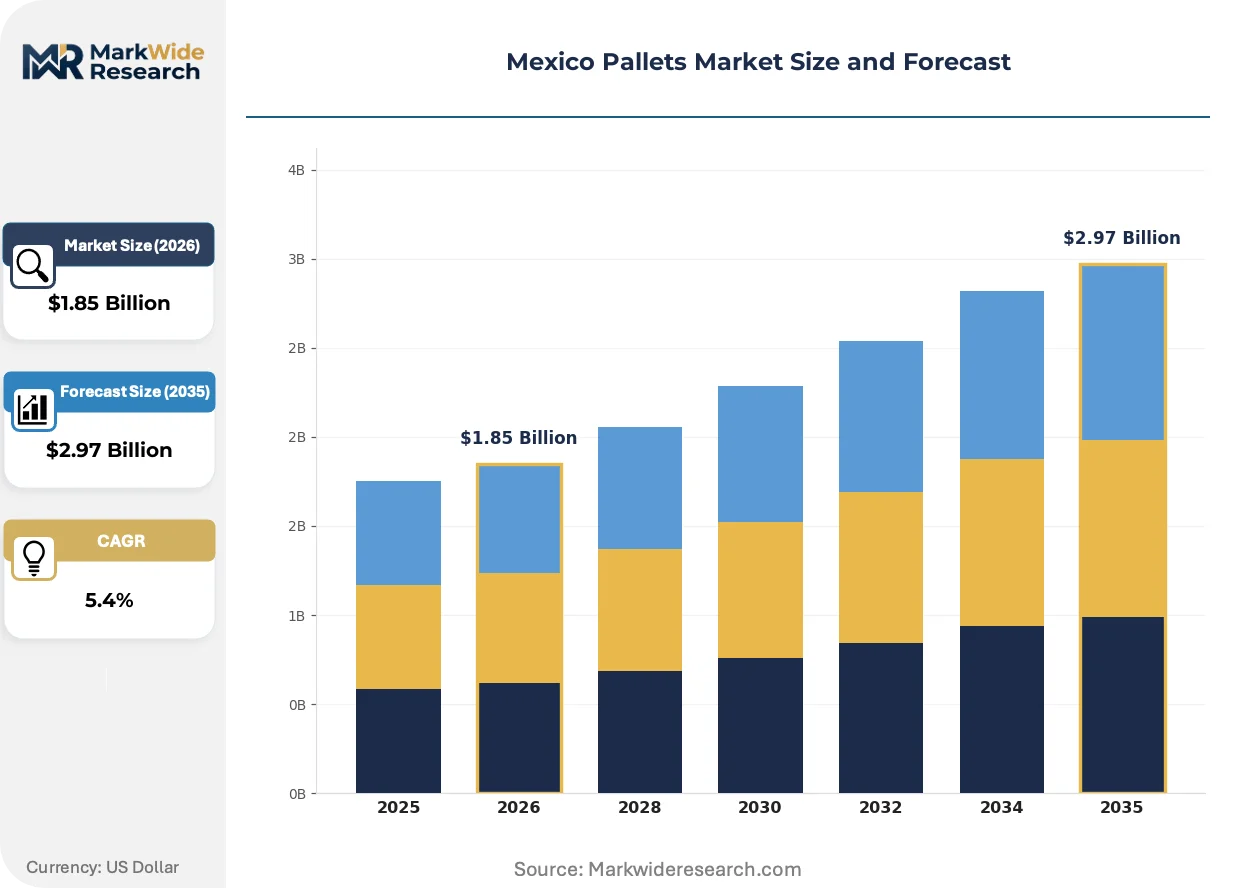
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Plastic, Metal, Corrugated Fiberboard, Composite, Paper Product Type: Stackable, Nestable, Rackable, Reversible, Double-Face, Single-Face End User Industry: Food & Beverage, Pharmaceuticals, Electronics, Chemicals, Automotive Components, Consumer Goods Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Third-Party Logistics Providers, Retailers, Leasing Services |
| Companies Covered | DS Smith, Schoeller Allibert, Brambles Limited (CHEP), CABKA Group, LOSCAM, Conitex Sonoco, Rehrig Pacific Company, PECO Pallet, Smurfit Kappa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Pallets Market Trends and Innovations
Asset digitization and regulatory tightening are converging to reshape material specifications and ownership models across Mexican supply chains. Pallet functionality now extends beyond load-bearing to data-carrying compliance infrastructure.
RFID-embedded plastic pallets are expanding into automotive and pharmaceutical logistics as traceability mandates harden. Tier-one suppliers to BMW and Audi Mexico are specifying tag-readable assets for inbound sequencing. This technology is expanding into supplier quality scorecards, with unreadable pallets triggering automatic rejection at receiving docks.
NOM-144-SEMARNAT-2004 amendments under review would tighten methyl bromide phase-out timelines and strengthen documentation requirements. Sawmills and treatment facilities face capital upgrades to thermo-mechanical kilns. Export-oriented manufacturers in Nuevo León and Tamaulipas are pre-emptively switching to plastic alternatives to eliminate phytosanitary risk entirely.
Leasing contracts now displace purchase orders among multinational manufacturers seeking to convert fixed pallet assets to operating expenses. Procurement teams at electronics and medical device maquiladoras favor per-trip pricing with full maintenance inclusion. This transition concentrates fastest in Querétaro and Guanajuato, where foreign-owned manufacturers dominate supplier parks and standardized pooling agreements reduce working capital requirements.
Mexico Pallets Market Segmentation
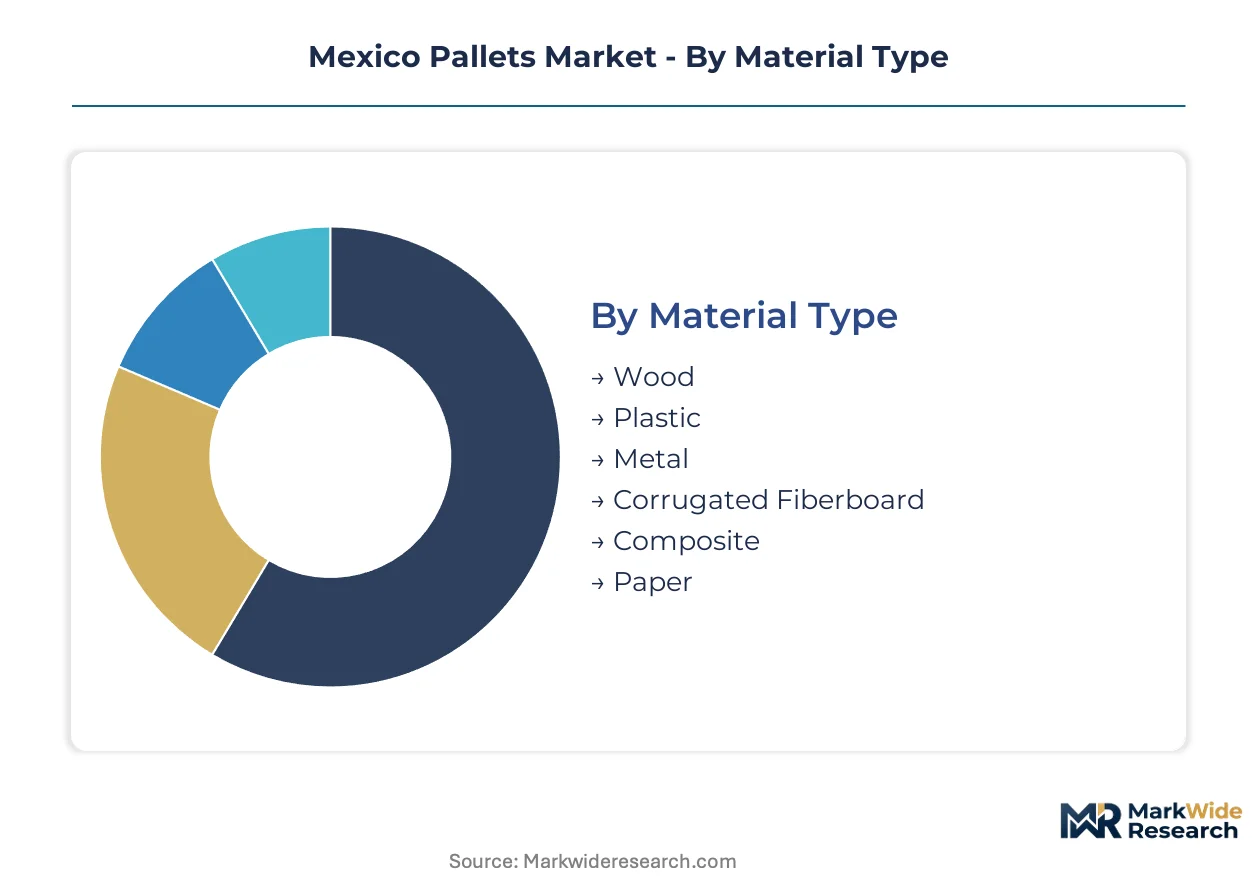
Pallet specification varies sharply across Mexican manufacturing corridors. Material selection and product geometry determine compliance eligibility, while channel structure reflects the shift from asset ownership to pooled logistics contracts.
Material Type:
Replacement cycles accelerate where NOM-144 certification burdens or hygiene mandates render incumbent materials obsolete.
- Wood:Heat-treated pine and oak construction dominates cross-border freight due to low first cost and established repair infrastructure. Michoacán sawmills supply the bulk of certified hardwood, though SEMARNAT inspection queues now push automotive exporters toward alternatives.
- Plastic:High-density polyethylene and polypropylene formulations deliver dimensional consistency for automated handling systems. Demand concentrates in Tijuana medical device maquiladoras where COFEPRIS traceability rules exclude untreated wood from pharmaceutical cold chains.
- Metal:Steel and aluminum pallets serve heavy industrial applications with extreme load requirements.
- Corrugated Fiberboard:Lightweight disposable platforms support one-way export shipments with minimal return logistics.
- Composite:Engineered wood-plastic blends balance sustainability messaging with performance specifications.
- Paper:Honeycomb cardboard construction addresses lightweight, non-reusable applications in consumer goods distribution.
Wood sits at the top of the volume ranking, with plastic climbing the fastest.
Product Type:
Cost tier differentiation separates capital-intensive automated warehouse specifications from manual-handling economy segments.
- Stackable:Standardized 48-by-40-inch platforms enable vertical cube utilization in high-turn distribution centers. Querétaro aerospace supplier parks specify stackable plastic pallets for inbound sequencing to BMW and Audi assembly lines.
- Rackable:Reinforced bottom deck construction supports unit loads in selective pallet racking without additional containment. Pharmaceutical distributors in Mexico City pay premiums for rackable assets that integrate with automated storage and retrieval systems.
- Nestable:Hollow leg designs reduce empty backhaul cube by up to 60 percent. Third-party logistics providers operating Guadalajara-Monterrey corridors favor nestable plastic pools for retail replenishment circuits.
- Reversible:Symmetrical deck surfaces permit loading from either orientation.
- Double-Face:Solid top and bottom decks distribute loads evenly for heavy industrial applications.
- Single-Face:Economical construction for light-duty, one-way shipping applications.
Stackable assets command the widest deployment base, with rackable specifications gaining share in automated facilities.
End User Industry:
Application-specific requirements drive material substitution and service model selection across manufacturing verticals.
- Automotive Components:Just-in-time sequencing demands RFID-traceable plastic pallets with zero-defect dimensional tolerances. Tier-one suppliers around San Luis Potosí have converted to CHEP-managed pooling to eliminate capital tie-up.
- Pharmaceuticals:COFEPRIS lot-level tracking mandates exclude wood from regulated cold chains. Baja California medical device exporters require plastic pallets with embedded temperature loggers.
- Electronics:Static-dissipative plastic formulations protect sensitive components in Guanajuato supplier parks.
- Food & Beverage:Washable plastic and compliant wood alternatives serve retail distribution with varying hygiene protocols.
- Chemicals:Corrosion-resistant plastic and metal constructions handle aggressive material containment.
- Consumer Goods:Cost-sensitive applications favor wood and corrugated fiberboard for high-volume retail replenishment.
Automotive components anchor current demand volume, with pharmaceuticals expanding most quickly.
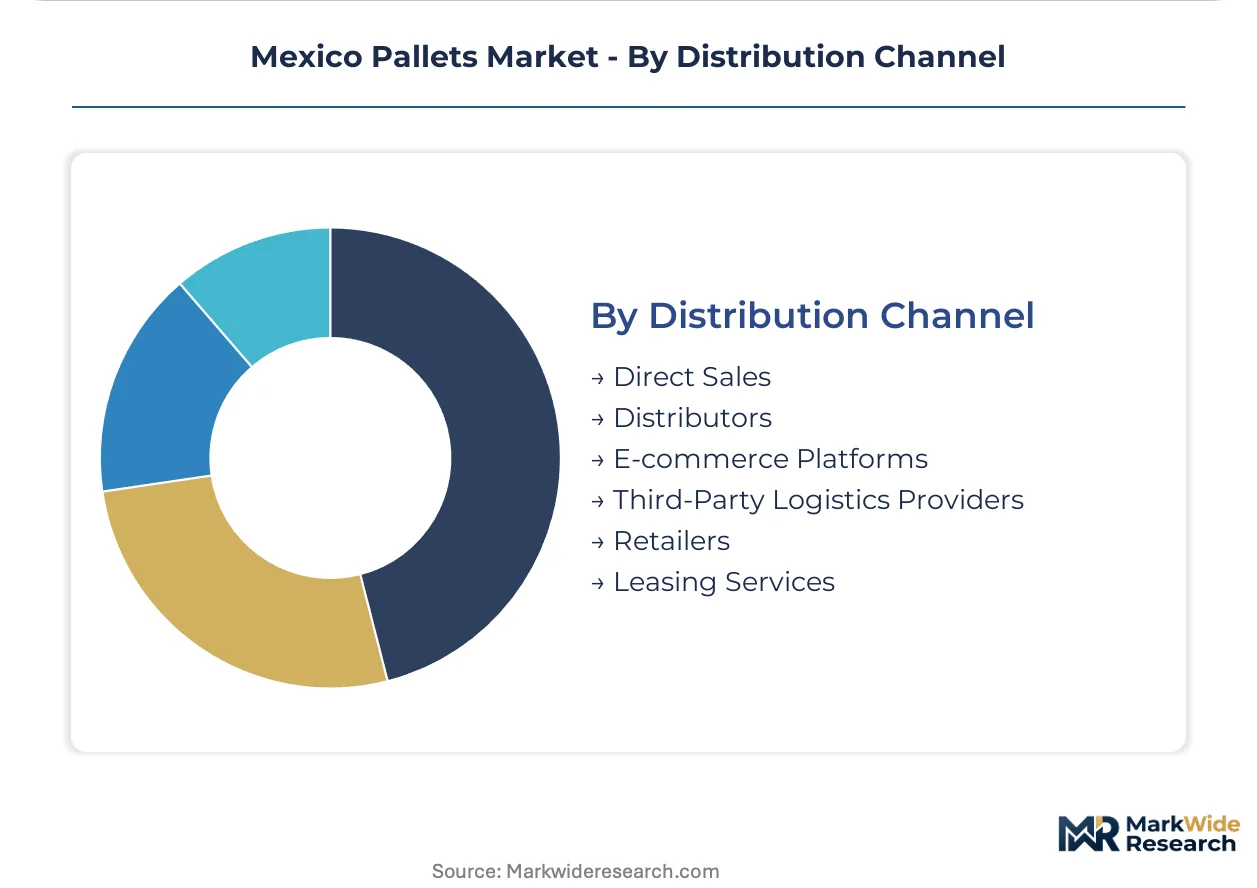
Distribution Channel:
Customer type and fleet scale determine whether procurement flows through direct manufacturer relationships or intermediary pooling operators.
- Leasing Services:Per-trip pricing with full maintenance inclusion converts fixed pallet assets to operating expenses. Multinational manufacturers in Querétaro and Guanajuato favor this model for working capital efficiency.
- Third-Party Logistics Providers:Integrated fleet management combines pooled assets with transportation and warehousing services. Large 3PLs struggle to reconcile multiple pooling systems within single warehouse management platforms.
- Direct Sales:Asset purchase agreements persist among small and mid-sized domestic manufacturers.
- Distributors:Regional inventory buffers support rapid replacement of damaged units.
- E-commerce Platforms:Digital procurement channels serve spot buyers with standardized specifications.
- Retailers:Large-format chains maintain captive pallet fleets for store replenishment.
Leasing services have captured the largest share of multinational procurement, with third-party logistics integration advancing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled logistics technicians and mechatronics specialists concentrate across Mexico's central manufacturing belt, anchoring pallet fleet maintenance and automated depot operations. Their geographic clustering mirrors foreign direct investment flows into automotive and aerospace supplier parks. Regional demand patterns reflect this workforce distribution and the infrastructure built to serve it.
Bajío Region
Automotive component manufacturers cluster around Querétaro and Guanajuato, generating dense pallet pooling circuits. SEMARNAT enforces NOM-144 certification at treatment facilities across the corridor. BMW and Audi assembly hubs in San Luis Potosí drive standardized 48-by-40-inch specifications through tier-one supplier contracts.
Nuevo León
Monterrey's industrial base demands rackable plastic pallets for automated warehouse environments. The state's environmental regulator monitors waste management compliance for closed-loop resin recovery systems. Apodaca and Santa Catarina host third-party logistics providers operating mixed wood-plastic fleets across northern distribution corridors.
Northern Border States
Tijuana and Mexicali maquiladoras serving US FDA-regulated medical device manufacturers require plastic pallets with embedded traceability features. COFEPRIS mandates lot-level tracking that structurally excludes untreated wood from pharmaceutical cold chains. Baja California's medical device corridor lacks adequate certified pooling infrastructure, creating supply gaps.
Jalisco
Guadalajara's electronics manufacturing parks specify static-dissipative plastic formulations for sensitive component handling. The state's technical institutes struggle to scale mechatronics programs for automated pallet repair equipment. El Salto and Tlajomulco logistics zones favor nestable designs for retail replenishment circuits with high empty-backhaul ratios.
Mexico City Metro
Pharmaceutical distributors in the capital pay premiums for rackable assets integrating with automated storage and retrieval systems. COFEPRIS traceability mandates elevate plastic pallet specifications over wood alternatives. Toluca and Cuautitlán Izcalli warehouse clusters concentrate demand for CHEP-managed pooling contracts.
Mexico Pallets Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Mexico's pallet procurement channels. The market structure tilts toward consolidation in pooled asset management, with leasing operators capturing multinational manufacturer contracts. Three archetypes dominate: circular pooling infrastructure providers, reusable plastic system designers, and recycled polymer specialists. Competitive moves center on fleet density expansion in high-corridor manufacturing zones and technology integration for traceability compliance.
Within the circular pooling tier, Brambles Limited (CHEP) anchors fleet density across northern Mexico's manufacturing belt. Schoeller Allibert occupies a position in reusable plastic crate-to-pallet systems for temperature-controlled logistics. CABKA Group exemplifies the recycled polymer archetype, positioning closed-loop resin recovery as a regulatory compliance advantage. These three represent distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| DS Smith |
| Schoeller Allibert |
| Brambles Limited (CHEP) |
| CABKA Group |
| LOSCAM |
| Conitex Sonoco |
| Rehrig Pacific Company |
| PECO Pallet |
| Smurfit Kappa |
| Others |
Pricing and Supply Chain Analysis
RFID-embedded pallet adoption across Mexico's automotive corridors is simultaneously compressing per-unit hardware margins and concentrating procurement power among pooled fleet operators. This technology shift forces standalone manufacturers to absorb tag costs or cede share to CHEP-managed circular systems that amortize electronics across high-turn networks.
Pricing Analysis
Per-trip bundled service contracts now dominate multinational procurement, separating premium RFID-traceable plastic pools from standard heat-treated wood leases and economy-grade corrugated fiberboard spot purchases. Price differentiation rests on NOM-144 certification grade and COFEPRIS traceability compliance, with pharmaceutical cold-chain specifications commanding substantial premiums over untreated alternatives. Cost compression in standard wood tiers is intensifying because SEMARNAT inspection queues force exporters to maintain buffer inventory or risk detention. Domestic manufacturers and small maquiladoras exhibit highest price sensitivity, while BMW and Audi tier-one suppliers prioritize compliance reliability over per-unit cost.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate that tier-one suppliers qualify both CHEP-managed pooling networks and independent plastic pallet treaters to mitigate single-source vulnerability. Raw material flows draw from Michoacán and Chihuahua sawmills for heat-treated hardwood, while recycled polymer feedstock hinges on petrochemical benchmarks and Baja California resin recovery infrastructure. Supply chain risk centers on tariff exposure for cross-border plastic resin shipments under USMCA rules. Distribution runs through third-party logistics depots in Querétaro and Guanajuato that reconcile mixed wood-plastic fleets within single warehouse management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's pallet market represents a late-cycle quality story as nearshoring manufacturers abandon ownership models for premium pooled specifications with full traceability compliance. This demand shift toward RFID-embedded assets and certified cold-chain infrastructure rewards operators with circular fleet density and regulatory certification depth.
For Market Incumbents: Extend pooling depot automation across the Bajío corridor to capture BMW and Audi supplier park conversions before competitors consolidate route density. Defensive consolidation moves should prioritize backward integration into Michoacán sawmill partnerships to secure heat-treatment capacity amid SEMARNAT inspection backlogs, while simultaneous investment in thermo-mechanical kiln upgrades anticipates methyl bromide phase-out amendments. The emerging threat of recycled polymer specialists with closed-loop resin recovery systems demands preemptive certification investment to maintain pharmaceutical and electronics segment access.
For New Entrants and Emerging Players: NOM-144-SEMARNAT-2004 enforcement in Mexico opens a window for certified plastic pallet providers to capture share in Tijuana and Mexicali medical device corridors where COFEPRIS traceability mandates structurally exclude untreated wood. The most penetrable segment lies in Baja California's FDA-regulated maquiladoras lacking adequate certified pooling infrastructure. A focused go-to-market angle targets temperature-controlled logistics with embedded RFID and temperature logger specifications, positioning against incumbent wood-plastic hybrid fleets that fail pharmaceutical cold-chain compliance.
For Investors and Strategic Acquirers: Valuations sit cheapest among recycled polymer specialists with captive resin recovery systems that anticipate producer responsibility amendments to Mexico's General Law for Prevention and Integral Management of Waste. Long-term viability across the 5-10 year window favors operators with circular infrastructure in high-corridor manufacturing zones rather than asset-light distributors. The specific signal to watch is SEMARNAT's methyl bromide phase-out timeline acceleration, which would structurally advantage plastic alternatives and trigger rapid manufacturer switching away from certified wood treaters.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID Fleet Digitization | Automotive OEMs now specify tag-readable assets for inbound sequencing compliance. |
| Closed-Loop Resin Recovery | CABKA Group positions polymer recycling as regulatory advantage under tightening environmental rules. |
| Thermo-Mechanical Kiln Upgrade | Sawmills face capital requirements as SEMARNAT tightens methyl bromide phase-out timelines. |
| Depot Automation Investment | Querétaro logistics density justifies automated pallet repair and quality-sorting equipment deployment. |
| Pharmaceutical Cold-Chain Certification | COFEPRIS lot-level tracking mandates exclude untreated wood from high-margin regulated segments. |
Research Methodology
Bottom-up automotive and pharmaceutical demand modeling reconciled against top-down sawmill and polymer resin supply tracking forms the analytical core of this study. Primary interviews with tier-one supplier procurement managers, third-party logistics depot operators, SEMARNAT-accredited treatment facility supervisors, and pharmaceutical cold-chain compliance officers combined with secondary validation from Mexican customs trade data, NOM-144 certification registries, and COFEPRIS pharmaceutical distribution licensing records. This bottom-up and top-down triangulation ensures volume estimates reflect actual fleet deployment rather than theoretical capacity.
The input-output matrix framing connects resin feedstock availability and hardwood treatment capacity to end-use demand across material type, product geometry, and distribution channel segments. Segmentation dimensions modeled include material substitution timelines, rackable versus nestable product specifications, and leasing versus direct purchase channel evolution across the projection horizon. CAGRs derive from manufacturing investment flow tracking and automotive production cluster expansion rates, with specific forecast inputs incorporating nearshoring facility announcement pipelines and NOM-144 enforcement intensity scenarios.
Revisions become necessary when SEMARNAT regulatory amendments, USMCA tariff renegotiations, or petrochemical price volatility materialize beyond baseline assumptions. Deviation in methyl bromide phase-out timelines or producer responsibility law passage would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Spill Pallets Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Europe Pallet Wrapping Machine Market
Pallets Packaging
Pallet Labelling System Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Middle East Pallets Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
Europe Pallet Market