
 Urea Formaldehyde Concrete Market | 2026-2036
Urea Formaldehyde Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Urea Formaldehyde Concrete Market Intelligence
The gap between premium low-emission formulations and commodity-grade urea formaldehyde concrete is restructuring procurement patterns across residential and commercial construction. Georgia-Pacific leverages captive resin production to control input costs across its concrete operations. BASF SE anchors its position through polymer-modified formulation chemistry that reduces curing time. Mitsui Chemicals competes on thermal performance specifications for insulation-grade precast panels.
Urea formaldehyde concrete is a composite binder system combining urea-formaldehyde resin with mineral aggregates, typically cured through acid-catalyzed condensation at temperatures between 25°C and 80°C to achieve compressive strengths ranging from 20 to 40 MPa; its primary purpose is to produce lightweight, thermally insulating structural elements with lower density than conventional Portland cement concrete. The poured product category dominates volume but carries thinner margins due to site-mix logistics and labor intensity, while the precast segment captures higher value through factory-controlled emission profiles and dimensional precision. Polymer-modified formulations are gaining fastest specification growth as architects prioritize crack resistance and freeze-thaw durability in flooring applications.
EPA formaldehyde emission standards for composite wood products extend testing protocols that influence urea formaldehyde concrete acceptance in US residential construction. ECHA REACH restrictions on formaldehyde reclassification are tightening supply qualifications for European precast manufacturers. BIS certification requirements in India mandate compressive strength verification for imported binder systems. Stakeholders must monitor how regulatory divergence between emission-based and performance-based standards reshapes cross-border product qualification pathways.
Market Dynamics
Passive-house building codes across Central Europe are compressing specification timelines for low-emission binder systems, forcing precast manufacturers to accelerate reformulation cycles while managing formaldehyde emission testing costs.
Growth Catalysts
- German EnEV thermal regulations:Mandatory U-value thresholds for residential foundations are specifying urea formaldehyde concrete for its insulating properties in passive-house construction.
- Acid-catalyzed condensation curing:Process refinements enabling ambient-temperature curing are expanding site-pour feasibility into temperate climate zones previously restricted to precast.
- Lightweight structural retrofits:Aging building stock in Northern Italy is driving demand for thermally insulating floor slabs that reduce dead loads on existing frames.
Market Restraints
- Formaldehyde price volatility:Methanol feedstock fluctuations and energy-intensive synthesis create margin compression for commodity-grade resin producers.
- Portland cement substitution:Geopolymer and alkali-activated binder systems are capturing specification share in non-thermal structural applications where insulating value is secondary.
- ECHA REACH reclassification:Tightened carcinogen hazard categories for formaldehyde are extending compliance timelines and testing costs for European precast exporters.
Strategic Opportunities
- Polish residential construction:EU cohesion fund infrastructure programs are channeling investment into prefabricated housing clusters with thermal performance mandates.
- Hybrid polymer-UF systems:Convergence of acrylic latex modification with base urea-formaldehyde chemistry is opening crack-resistant flooring specifications in Nordic markets.
- Digital precast platforms:Factory-to-site logistics coordination through BIM-integrated ordering systems is reducing lead-time friction for multi-unit residential developers.
Industry Challenges
- Emissions testing capacity:Chamber testing protocols for formaldehyde release require 28-day conditioning cycles that bottleneck factory throughput during specification surges.
- Cross-regional qualification divergence:EPA composite wood protocols and ECHA REACH classifications employ incompatible emission measurement methods, complicating export documentation for multi-jurisdiction projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urea Formaldehyde Concrete Market |
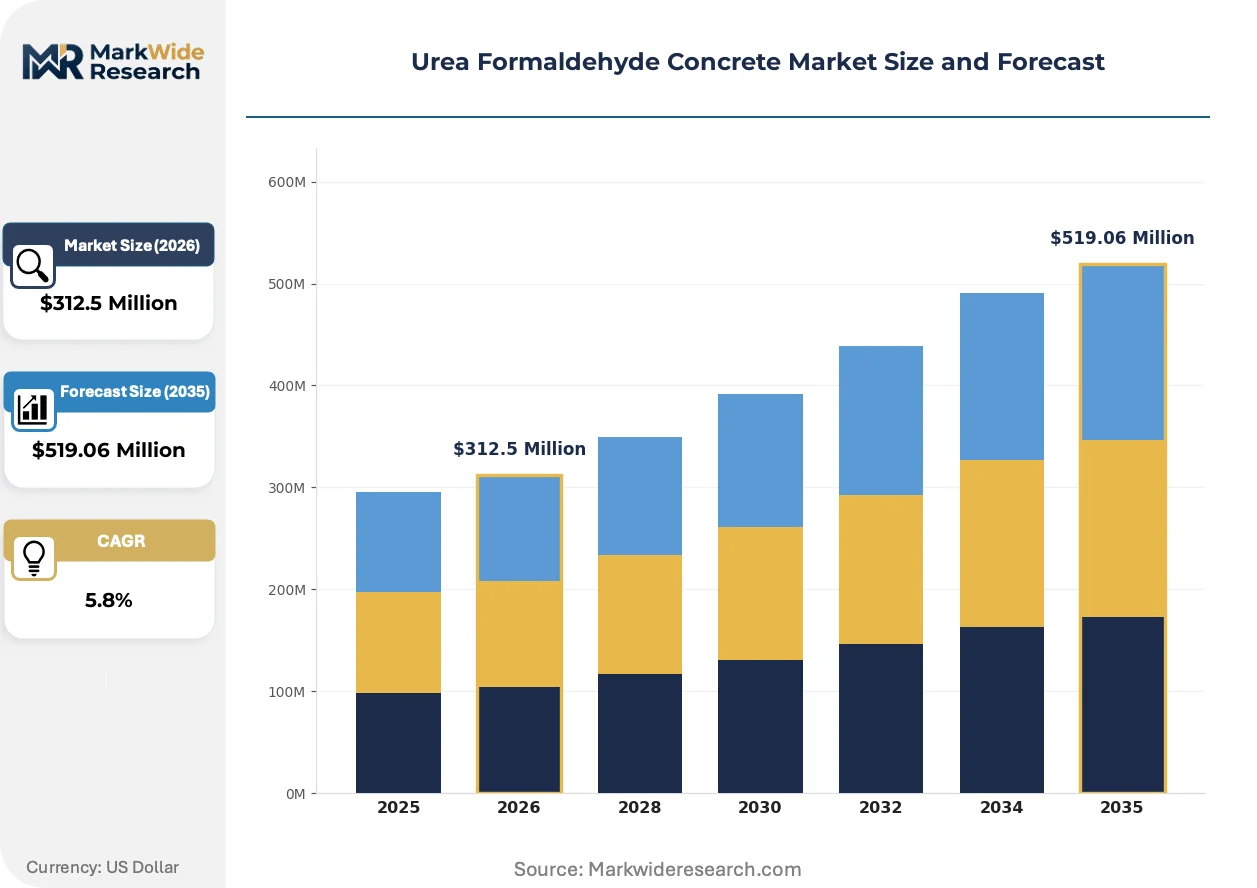
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poured, Precast, Reinforced, Lightweight End Use Industry: Construction, Automotive, Furniture, Electronics Formulation: Conventional, Polymer-Modified, High-Performance, Sustainable Application: Flooring, Insulation, Coatings, Adhesives |
| Companies Covered | Acron Group, Chemtan Company, Georgia-Pacific, Norplex-Micarta, Holders Technology, BASF SE, Hexion Inc., Akzo Nobel, Mitsui Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urea Formaldehyde Concrete Market Strategic Shifts & Innovations
Reformulation chemistry and factory automation are compressing the performance gap between poured and precast categories while regulatory measurement protocols fragment across Atlantic standards.
Polymer-modified urea formaldehyde systems incorporating acrylic latex dispersions are modularizing specification pathways for high-traffic flooring applications. Commercial developers in the Netherlands are specifying these hybrids for warehouse slabs requiring freeze-thaw resistance. The technology is modularizing procurement decisions by collapsing the traditional trade-off between thermal insulation and surface durability into single-system solutions.
ECHA REACH restrictions on formaldehyde reclassification entered force in 2023, triggering mandatory safety data sheet revisions across European precast supply chains. Manufacturers serving German passive-house projects must now document sub-0.1 ppm emission profiles under EN 717-1 chamber protocols. Spanish precast exporters are responding by consolidating testing partnerships with Madrid-based certification laboratories to maintain qualification continuity.
Architect specification authority is consolidating around performance-based rather than prescriptive binder selection, with thermal bridging calculations now driving material choice earlier in design phases. Engineering consultancies in Copenhagen and Vienna are displacing traditional specification lists with whole-building energy modeling outputs. This shift is most visible in Austrian multi-family residential projects where envelope U-value targets override legacy brand preferences.
Urea Formaldehyde Concrete Market Segmentation
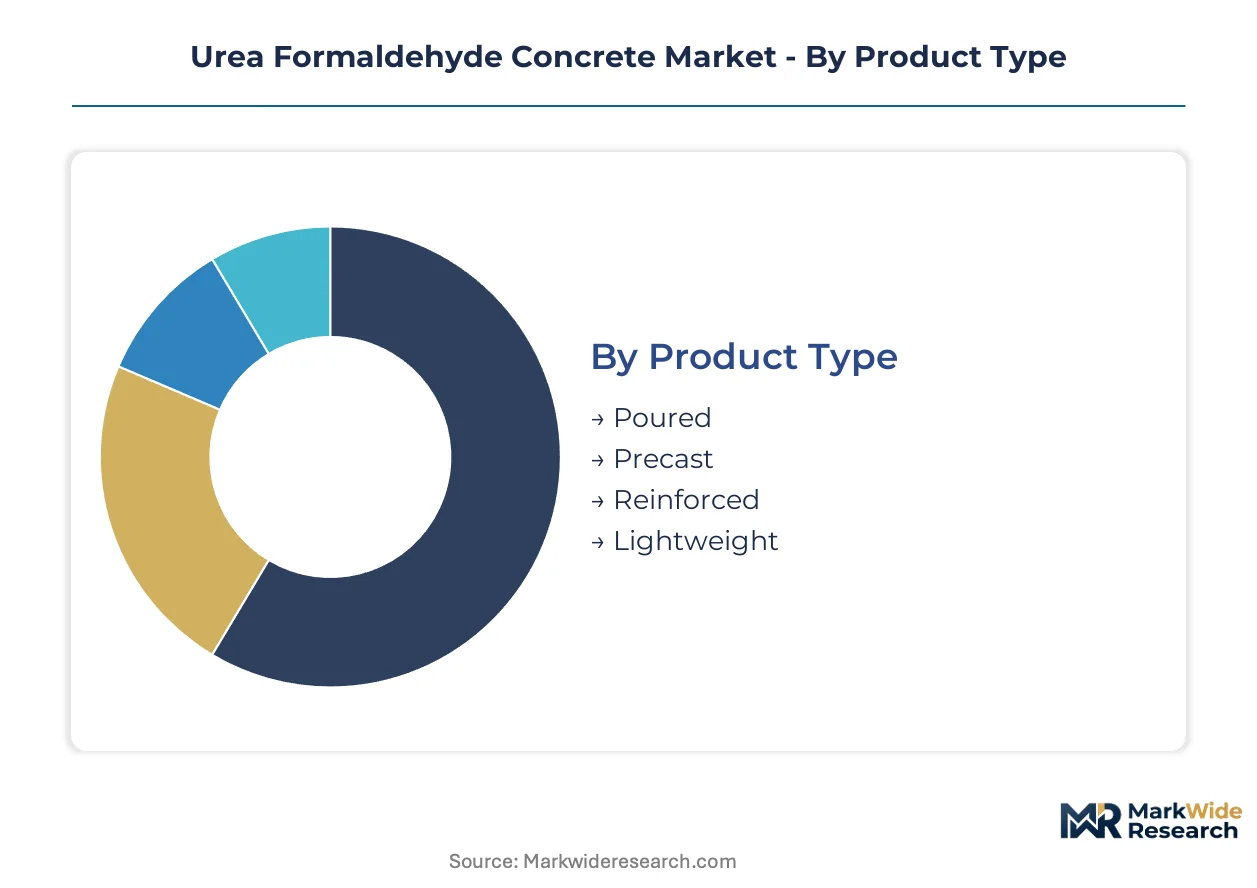
Segmentation in urea formaldehyde concrete reveals how thermal performance requirements and emission regulations partition demand across manufacturing methods and end-use specifications. Each category captures distinct trade-offs between factory-controlled quality and site-pour flexibility.
Product Type:
The customization-vs-standardization spectrum runs from site-pour variability to factory-precision output across this category.
- Poured:Mixed and cured on construction sites through acid-catalyzed condensation at ambient temperatures. Demand concentrates in Northern Italian lightweight structural retrofits where reducing dead loads on aging frames overrides factory precision advantages. Site logistics and labor intensity compress margins despite volume dominance.
- Precast:Manufactured under controlled factory conditions with documented sub-0.1 ppm emission profiles for German passive-house certification. Thermal performance mandates and dimensional precision command premium pricing in multi-unit residential developments across Poland and Austria.
- Reinforced:Steel or fiber-reinforced variants for structural load-bearing applications requiring enhanced compressive strength.
- Lightweight:Expanded aggregate formulations targeting dead-load reduction in vertical extensions and rooftop additions.
Most installed capacity flows through poured applications. Expansion is steepest in precast as factory emission documentation becomes mandatory for EU residential tenders.
End Use Industry:
Cost tier differentiation separates thermal-mandated construction from price-sensitive manufacturing applications in this category.
- Construction:Foundation slabs, wall panels, and flooring systems specified for U-value compliance in German EnEV-regulated buildings. Passive-house building codes across Central Europe are compressing specification timelines and accelerating reformulation cycles for low-emission binder systems.
- Automotive:Lightweight interior panels and acoustic insulation for commercial vehicle cabins where fire-retardant properties intersect with mass reduction targets.
- Furniture:Core material for laminated surfaces and molded components where formaldehyde emission thresholds vary by regional regulation.
- Electronics:Encapsulation and potting compounds leveraging electrical insulation properties of cured resin matrices.
Construction absorbs the majority of production volume. Automotive applications are expanding most quickly as commercial vehicle electrification intensifies weight reduction priorities.
Formulation:
Application maturity separates legacy chemistry from emerging polymer-hybrid systems in this category.
- Conventional:Standard urea-formaldehyde resin with mineral aggregates cured through traditional acid catalysis. Commodity-grade production faces margin compression from methanol feedstock volatility and Portland cement substitution in non-thermal applications.
- Polymer-Modified:Acrylic latex dispersions integrated with base UF chemistry for crack-resistant flooring specifications. Dutch warehouse developers are specifying these hybrids for freeze-thaw durability in high-traffic slabs.
- High-Performance:Engineered formulations with accelerated curing or enhanced compressive strength for structural retrofit projects.
- Sustainable:Bio-based formaldehyde scavengers and reduced-emission hardener systems targeting Nordic green building certifications.
Conventional formulations retain the largest installed base. Polymer-modified systems are gaining share fastest as architects collapse the thermal insulation versus surface durability trade-off into single-system specifications.
Application:
Customer type segmentation distinguishes project-scale procurement from component manufacturing in this category.
- Flooring:Thermally insulating slab systems for residential and commercial buildings where U-value calculations drive material selection. Copenhagen and Vienna engineering consultancies are displacing legacy brand preferences with whole-building energy modeling outputs.
- Insulation:Precast wall and roof panels for passive-house envelopes requiring documented thermal bridging performance. Spanish precast exporters are consolidating testing partnerships with Madrid-based certification laboratories to maintain ECHA REACH qualification continuity.
- Coatings:Protective surface treatments and decorative finishes leveraging resin adhesion properties.
- Adhesives:Binder applications in composite wood products where EPA testing protocols influence cross-border acceptance criteria.
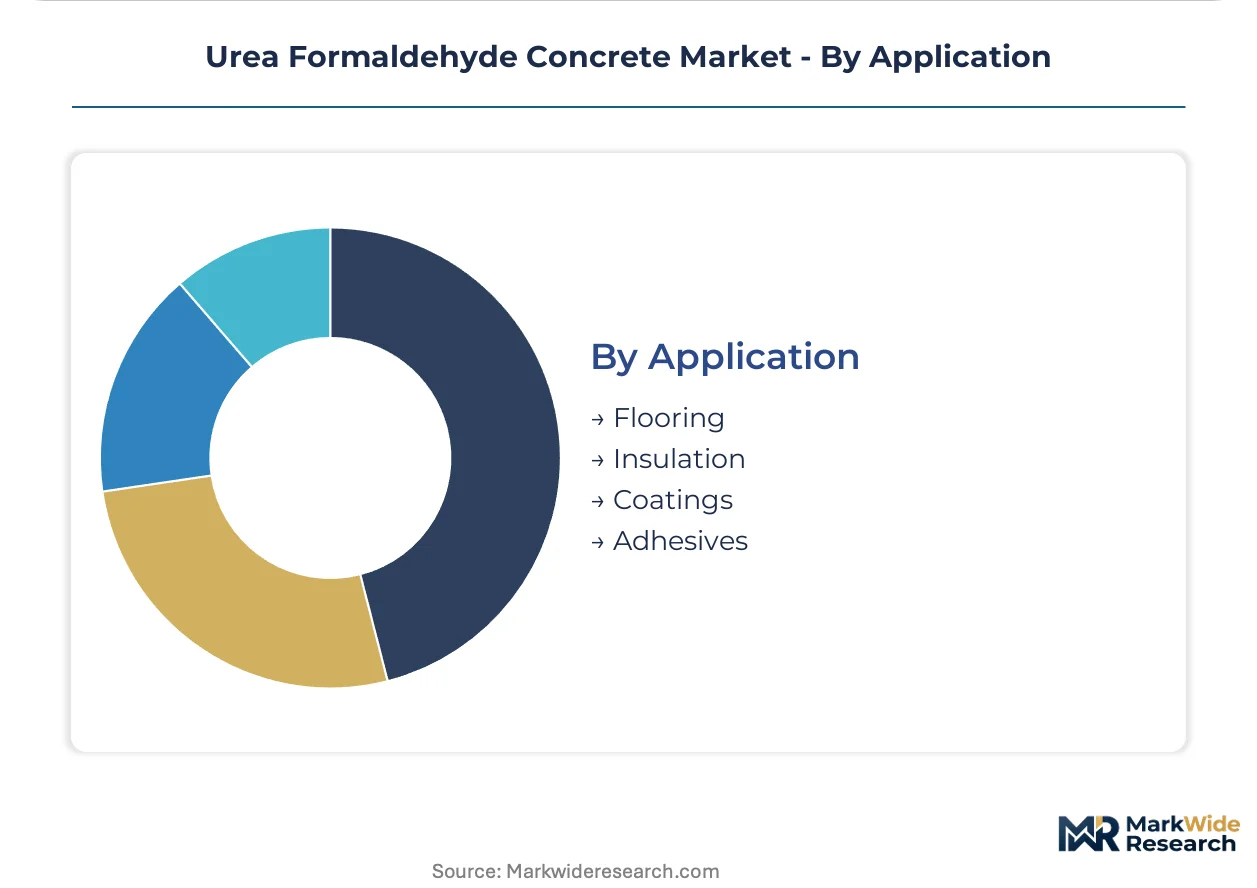
Flooring applications command the largest share of specification volume. Insulation-grade panels are climbing the fastest as EU cohesion fund programs channel investment into prefabricated housing clusters with thermal performance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled precast technicians and resin chemists cluster around German industrial zones, anchoring European supply capacity for low-emission binder systems. Their concentration reflects decades of formaldehyde processing heritage and proximity to passive-house construction demand.
Germany
Passive-house building codes in Bavaria and Baden-Württemberg specify sub-0.1 ppm emission thresholds for foundation slabs, compressing procurement timelines for certified precast manufacturers. EnEV thermal regulations mandate U-value compliance that favors urea formaldehyde concrete's insulating properties. The Stuttgart-Munich corridor hosts concentrated precast fabrication capacity serving multi-unit residential developers.
Poland
EU cohesion fund infrastructure programs channel investment into prefabricated housing clusters with thermal performance mandates, accelerating specification of insulating concrete systems. National building efficiency directives align with European Green Deal targets for residential envelope performance. The Łódź-Katowice industrial belt is consolidating testing partnerships with German certification laboratories to maintain cross-border qualification continuity.
Italy
Aging building stock in Lombardy and Veneto drives demand for lightweight floor slabs that reduce dead loads on existing structural frames without thermal bridging. Regional retrofit incentives prioritize materials with documented insulating value for heritage building upgrades. The Milan-Turin axis hosts specialized contractors executing structural lightweighting projects for commercial and residential vertical extensions.
Netherlands
Commercial warehouse developers in Rotterdam and Eindhoven specify polymer-modified formulations for freeze-thaw resistance in high-traffic flooring applications. National building codes emphasize whole-building energy modeling that collapses thermal insulation and surface durability into single-system procurement decisions. The Randstad logistics corridor concentrates demand for crack-resistant slab systems serving distribution center construction.
Spain
Precast exporters serving German and Austrian markets face extended compliance timelines from ECHA REACH reclassification of formaldehyde hazard categories. Madrid-based certification laboratories are consolidating testing partnerships with manufacturers to maintain chamber protocol documentation for EU residential tenders. The Madrid-Catalonia industrial corridor is adapting factory emission documentation systems to EN 717-1 conditioning cycle requirements.
Urea Formaldehyde Concrete Market Key Industry Players
Capital-heavy producers compete with asset-light formulation specialists across distinct capability tiers. Integrated resin manufacturers control upstream chemical synthesis, while downstream precast fabricators concentrate on factory-controlled curing and emission documentation. Three archetypes dominate: captive resin producers with backward integration into formaldehyde synthesis, polymer-modification specialists blending acrylic dispersions with base UF chemistry, and regional precast operators optimizing logistics for site-pour substitution. Consolidation pressures favor M&A between resin producers and precast fabricators, while technology licensing agreements spread polymer-hybrid formulations across European markets.
Among North American integrated producers, Georgia-Pacific exemplifies the captive-resin archetype through in-house control of formaldehyde synthesis inputs. BASF SE anchors the polymer-modification tier with formulation chemistry capabilities spanning acrylic latex integration. Mitsui Chemicals occupies a position representing Asian thermal-performance specialization for insulation-grade specifications. These three entities illustrate how geographic origin and corporate structure map to distinct competitive positioning without prescribing specific strategic actions or market shares.
| Leading Market Players |
|---|
| Acron Group |
| Chemtan Company |
| Georgia-Pacific |
| Norplex-Micarta |
| Holders Technology |
| BASF SE |
| Hexion Inc. |
| Akzo Nobel |
| Mitsui Chemicals |
| Others |
Cost & Logistics Intelligence
German passive-house procurement mandates for sub-0.1 ppm emission documentation are compressing supplier qualification timelines and forcing precast manufacturers to absorb chamber testing costs into factory gate pricing. This demand-side specification pressure is restructuring how resin producers and precast fabricators negotiate contract terms across Central European markets.
Pricing Analysis
Bundled emission certification and logistics services separate premium precast suppliers from commodity-grade poured concrete operators. Three-tier pricing structure across certified low-emission, standard precast, and site-mix economy levels reflects the cost of EN 717-1 chamber documentation and factory-controlled curing infrastructure. Pricing pressure stems from methanol feedstock volatility in formaldehyde synthesis, which compresses margins for captive resin producers lacking polymer-modification capabilities. Commercial developers in the Netherlands demonstrate lowest price sensitivity due to whole-building energy modeling procurement, while Northern Italian retrofit contractors exhibit highest sensitivity as dead-load reduction specifications compete on installed cost.
Supply Chain Analysis
Single-source vulnerability sits with German industrial zones for skilled resin chemist and precast technician labor pools. Manufacturing capacity concentrates in Germany, Poland, and Spain, with raw material dependencies spanning methanol feedstock from Dutch and Belgian petrochemical complexes, urea from German fertilizer producers, and acrylic latex modifiers from BASF Ludwigshafen operations. Supply chain risk centers on regulatory restriction divergence between EPA composite wood protocols and ECHA REACH classifications, which fragments export documentation requirements. Distribution runs through factory-direct contracts to multi-unit residential developers, with BIM-integrated ordering systems reducing lead-time friction for Polish and Austrian projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urea formaldehyde concrete functions as a regulatory compounder where ECHA REACH formaldehyde reclassification is accelerating demand for documented low-emission precast systems across EU residential construction.
For Market Incumbents: Extend factory emission documentation capabilities to capture Polish and Austrian passive-house specification surges before testing capacity bottlenecks harden competitive moats. Consolidate testing partnerships with Madrid-based certification laboratories to maintain ECHA REACH qualification continuity against Spanish exporter consolidation pressure. Backward integration into formaldehyde synthesis secures margin control against methanol feedstock volatility. For New Entrants and Emerging Players: Polymer-modified formulation chemistry offers the most penetrable wedge for Nordic flooring specifications where freeze-thaw resistance commands premium positioning. Target Dutch warehouse developers through direct specification to engineering consultancies displacing legacy brand preferences with whole-building energy modeling outputs. White-space opportunity sits in Italian lightweight structural retrofits where aging building stock and regional incentives create procurement entry points without incumbent emission certification advantages. For Investors and Strategic Acquirers: Asymmetric upside sits with regional precast operators possessing factory-controlled curing infrastructure and existing ECHA REACH documentation systems. Long-term viability hinges on regulatory trajectory sustaining emission-based specification premiums over performance-only procurement. Acquisition target archetype: mid-cap Polish or Austrian precast fabricators with thermal performance testing partnerships and multi-unit residential developer relationships. Signal to watch: chamber testing capacity expansion announcements from Madrid and Stuttgart certification laboratories indicating demand validation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Formaldehyde Synthesis | Captive methanol-to-resin production insulates margin compression from feedstock volatility. |
| Polymer-Modified Formulation Licensing | Acrylic latex integration opens Nordic flooring specifications with freeze-thaw resistance premiums. |
| Chamber Testing Partnership Consolidation | Madrid laboratory alliances maintain ECHA REACH qualification continuity for Spanish exporters. |
| BIM-Integrated Ordering Platform Deployment | Factory-to-site logistics coordination reduces lead-time friction for Polish residential developers. |
| Regional Precast Capacity Expansion | Łódź-Katowice industrial belt positioning captures EU cohesion fund prefabricated housing investment. |
Research Approach
Direct dialogue with precast plant managers, resin procurement leads at downstream fabricators, ECHA regulatory affairs specialists, and German passive-house engineering consultants anchored qualitative insight development. Secondary validation drew from customs and trade data for urea-formaldehyde resin flows, SEC 10-K disclosures from integrated chemical producers, Cefic sector reports, and EN 717-1 chamber testing protocol documentation. Bottom-up and top-down triangulation cross-checked regional production capacity estimates against end-use demand modeling.
Bottom-up volume modeling aggregated individual precast facility throughput and poured concrete site-mix estimates across Germany, Poland, Italy, Netherlands, and Spain, while top-down analysis calibrated against European construction material consumption patterns and passive-house certification databases. Segmentation dimensions included product type (poured versus precast versus polymer-modified), end-use industry (construction versus automotive), and formulation chemistry across the analysis window. CAGRs derived from regression against EnEV thermal regulation adoption curves and EU Green Deal residential efficiency targets.
The model holds under sustained ECHA REACH emission threshold enforcement and German passive-house code expansion; deviation in Portland cement substitution acceleration or geopolymer binder cost parity would shift volume projections. Forecasts reflect assumptions about regulatory compliance cost pass-through and chamber testing capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
Europe Adhesives Market
Adhesives & Sealants
North America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Cycloaliphatic Epoxy Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Global Methyl Acrylate Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Europe Waterborne Adhesives Market