
 Europe Cyanoacrylate Adhesives Market | 2026-2036
Europe Cyanoacrylate Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cyanoacrylate Adhesives Market Foresight
CE marking under the EU Medical Device Regulation is reorganizing competitive access for cyanoacrylate suppliers serving healthcare applications. Henkel AG & Co. KGaA leverages its adhesive portfolio breadth to dominate industrial bonding contracts across German automotive plants. Illinois Tool Works Inc. anchors its position through specialized dispensing systems that integrate with high-speed assembly lines. Arkema Group differentiates via advanced monomer chemistry that extends bond durability under thermal stress.
Europe cyanoacrylate adhesives are single-component, fast-curing thermoplastic resins formulated primarily from ethyl or butyl cyanoacrylate monomers, polymerizing on contact with surface moisture to form high-tensile bonds within seconds. Their primary purpose is permanent or temporary joining of metals, plastics, rubber, and biological tissues where clamping or heat curing is impractical. Ethyl cyanoacrylate leads volume consumption due to its versatility across automotive and electronics assembly, while octyl cyanoacrylate captures premium margin pools in medical wound closure where biocompatibility requirements elevate pricing. Medical end-use represents the fastest-growing segment as surgical adhesives displace sutures in European hospitals.
EMA biocompatibility standards, REACH chemical registration requirements, and the EU F-Gas Regulation collectively shape formulation choices, testing protocols, and market entry timelines for adhesive manufacturers. ECHA substance evaluations are forcing reformulation of certain cyanoacrylate catalyst systems, redirecting R&D spending toward compliant alternatives. Stakeholders must monitor evolving EU chemical hazard classifications that could reclassify monomer grades and trigger downstream labeling obligations.
Market Dynamics
REACH chemical registration requirements and ECHA substance evaluations are forcing systematic reformulation of cyanoacrylate catalyst systems across European manufacturing bases. This regulatory pressure is compressing product development cycles while elevating compliance costs for adhesive suppliers serving automotive, medical, and electronics assembly sectors.
Growth Catalysts
- EU Green Deal decarbonization mandates:Automotive OEMs in Germany and France are accelerating adhesive bonding adoption to enable lightweight vehicle architectures and reduce assembly energy intensity compared with welding.
- EMA biocompatibility standards evolution:Medical device manufacturers are expanding cyanoacrylate use in wound closure applications as surgical adhesives displace traditional suturing methods in European hospital procurement.
- Ethyl cyanoacrylate monomer versatility:Electronics assemblers across Europe's industrial corridor are standardizing on this chemistry for high-speed component bonding where thermal curing is impractical.
Market Restraints
- Specialized monomer supply concentration:Production of medical-grade octyl cyanoacrylate concentrates among a limited supplier base, creating vulnerability for wound closure adhesive manufacturers.
- ECHA catalyst system restrictions:Substance evaluations are disqualifying established accelerator chemistries, forcing costly reformulation without guaranteed performance equivalence.
- UV-curable epoxy substitution:Electronics manufacturers in precision assembly applications are migrating to alternative chemistries offering superior thermal stability and reworkability.
Strategic Opportunities
- Poland and Czech Republic industrial expansion:Automotive component manufacturing is migrating eastward within Europe, creating demand for localized adhesive supply and technical service infrastructure.
- CSRD sustainability reporting requirements:Large EU manufacturers must now document supply chain environmental impact, favoring adhesive suppliers with verified lifecycle data and bio-based formulation pathways.
- Smart dispensing system integration:Convergence of adhesive chemistry with IoT-enabled application equipment is opening premium service contracts linking material supply to real-time quality monitoring.
Industry Challenges
- Polymer chemistry specialist scarcity:Formulation expertise combining cyanoacrylate monomer science with REACH compliance is concentrated among aging technical workforces in Germany and Switzerland.
- CE marking timeline compression:EU Medical Device Regulation transition is accelerating certification requirements for surgical adhesive suppliers, compressing product validation windows.
- Legacy equipment compatibility:High-speed automotive assembly lines require adhesive dispensing retrofitting to accommodate reformulated chemistries with altered viscosity and cure profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cyanoacrylate Adhesives Market |
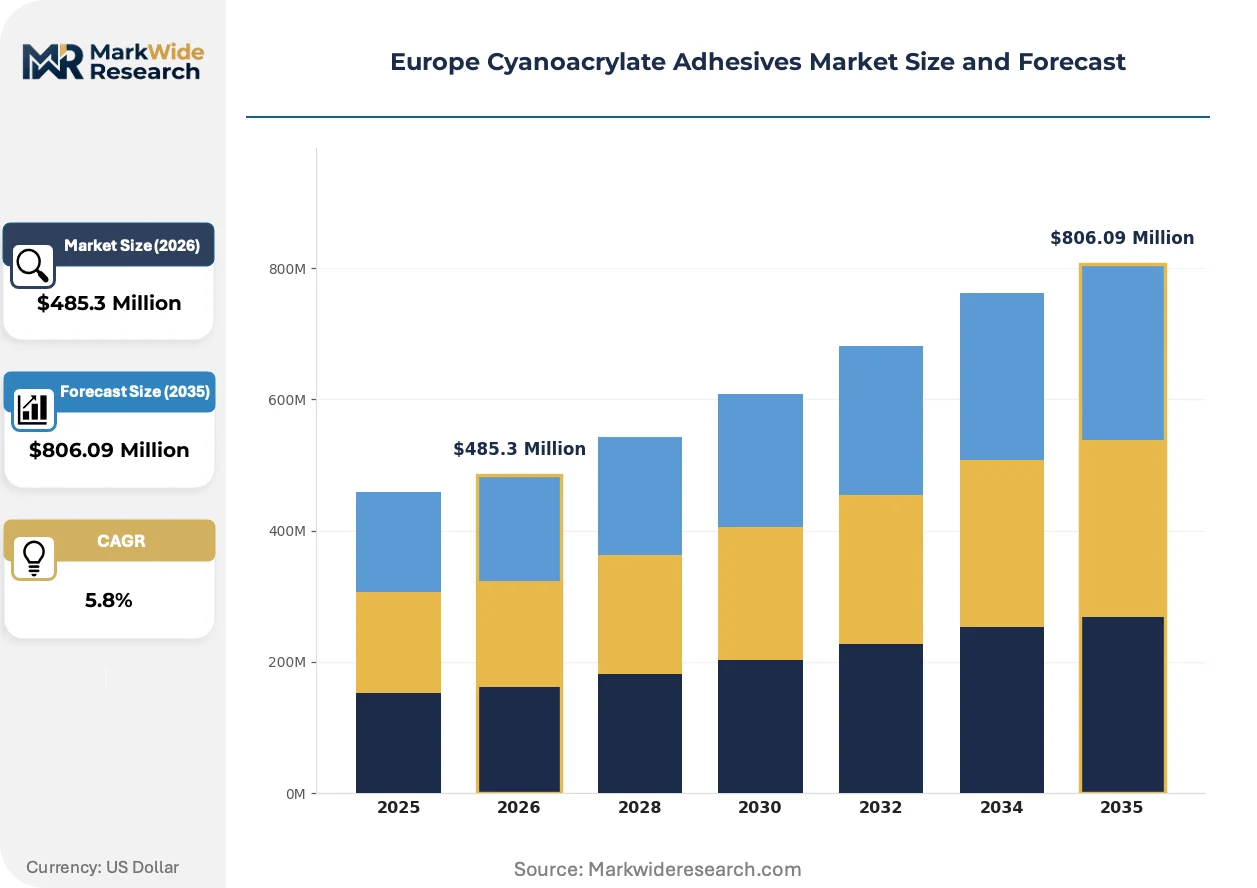
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $806.09 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethyl Cyanoacrylate, Butyl Cyanoacrylate, Methyl Cyanoacrylate, Octyl Cyanoacrylate End User: Automotive, Electronics, Medical, Consumer Goods Application: Bonding, Coating, Sealing, Repairing Packaging Type: Syringe, Bottle, Tube, Pouch |
| Companies Covered | Henkel AG & Co. KGaA, Illinois Tool Works Inc., 3M, Pidilite Industries Ltd., Aica Kogyo Co. Ltd., Arkema Group, Soudal Holding N.V., NANPAO RESINS CHEMICAL GROUP, H.B. Fuller Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cyanoacrylate Adhesives Market Shifts & Advancements
Formulation science and application technology are diverging along performance-specialized versus cost-optimized trajectories. This bifurcation is fragmenting supplier strategies and creating distinct competitive arenas within the European market.
Octyl cyanoacrylate biocompatibility engineering is bifurcating the medical-grade segment from industrial applications. German surgical device manufacturers are adopting advanced monomer purification protocols to meet EMA Class III device requirements. This technology is compressing margins for standard-grade suppliers while enabling premium pricing for biocompatible formulations in wound closure and internal tissue bonding.
REACH authorization procedures are extending substance evaluation timelines for cyanoacrylate catalyst systems. ECHA's systematic screening of accelerator chemistries is forcing reformulation investments before commercial obsolescence. Medical adhesive manufacturers face the steepest compliance burden, as device master files require extensive revalidation when raw material specifications change.
Hospital procurement consolidation is concentrating purchasing power among centralized European supply networks. Group purchasing organizations in France and Italy are standardizing cyanoacrylate wound closure specifications across regional health systems. This concentration is most visible in Germany, where university hospital networks are displacing individual facility purchasing autonomy with framework contracts favoring multi-product adhesive suppliers.
Europe Cyanoacrylate Adhesives Market Segmentation
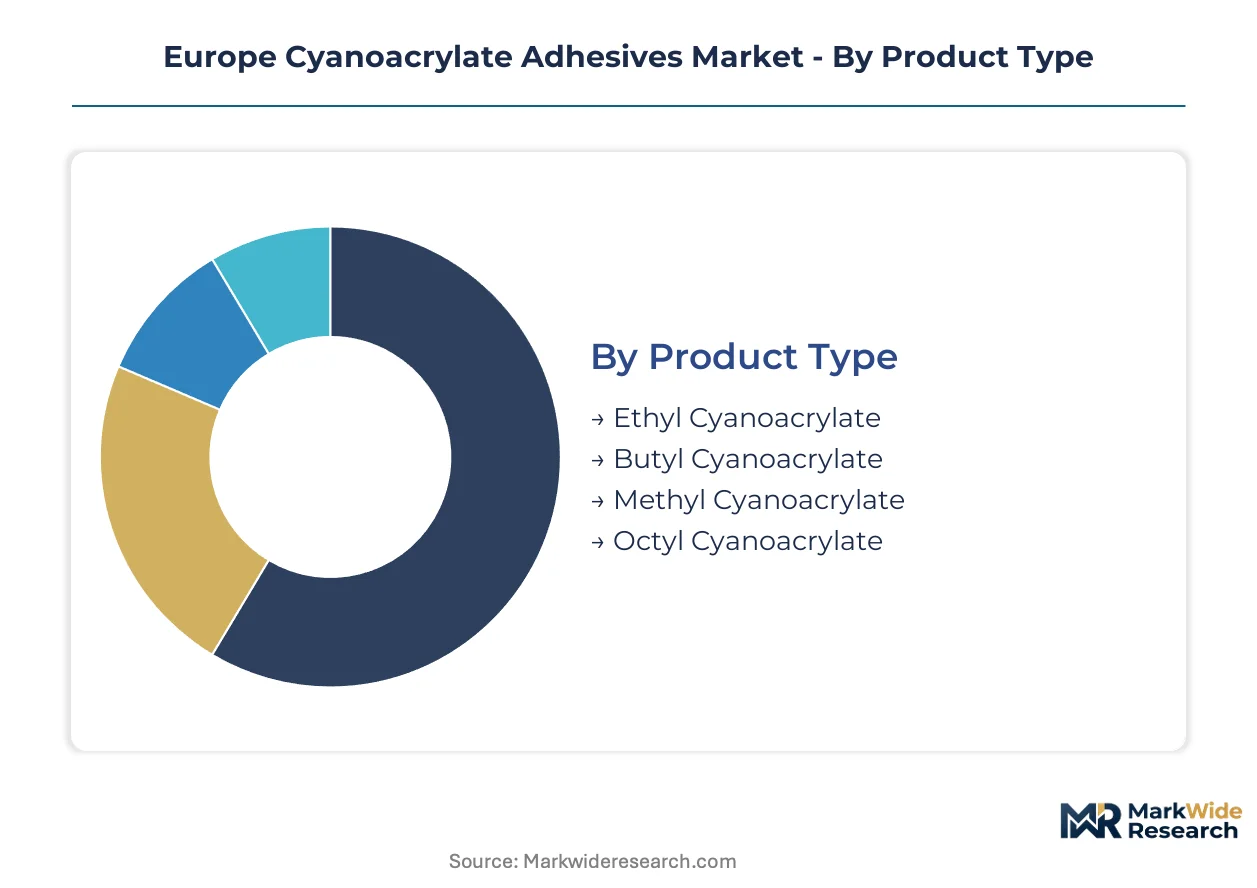
Segmentation in the Europe cyanoacrylate adhesives market reveals distinct performance requirements across industrial, medical, and consumer channels. Each category carries unique formulation specifications, regulatory burdens, and supply chain configurations that shape supplier positioning.
Product Type:
German and French manufacturers dominate domestic consumption of industrial-grade chemistries, while medical-grade monomers flow through specialized Swiss and Dutch distribution channels serving export-led wound closure markets.
- Ethyl Cyanoacrylate:This monomer forms the backbone of high-speed automotive and electronics assembly applications due to its rapid polymerization kinetics and broad substrate compatibility. Demand concentrates in Germany's industrial corridor, where automotive OEMs specify this chemistry for lightweight structural bonding under EU Green Deal decarbonization mandates.
- Octyl Cyanoacrylate:Advanced purification protocols yield biocompatible formulations meeting EMA Class III device requirements for internal tissue bonding. Swiss and German surgical device manufacturers drive premium pricing in this segment as hospital procurement consolidation across France and Italy standardizes wound closure specifications.
- Butyl Cyanoacrylate:Slower cure profiles suit flexible substrate applications in consumer goods assembly across Poland and Czech Republic manufacturing zones.
- Methyl Cyanoacrylate:High-tensile formulations serve specialized metal bonding in French aerospace component suppliers.
Ethyl cyanoacrylate holds the largest share; momentum sits with octyl cyanoacrylate.
End User:
Cost tier differentiation separates specification-grade industrial buyers from price-sensitive consumer channels, with medical applications commanding formulation premiums that reflect biocompatibility testing burdens.
- Automotive:OEM assembly plants in Germany and France specify adhesive bonding to replace mechanical fasteners, enabling lightweight vehicle architectures. REACH compliance costs and ECHA catalyst restrictions compress margins for standard-grade suppliers while favoring integrated material-dispensing system providers.
- Medical:Surgical adhesives displace traditional suturing in European hospital procurement, with EMA biocompatibility standards evolution accelerating device master file revalidation cycles. German university hospital networks consolidate purchasing through framework contracts favoring multi-product adhesive suppliers.
- Electronics:High-speed component assemblers across Europe's industrial corridor standardize on ethyl cyanoacrylate where thermal curing is impractical.
- Consumer Goods:Polish and Czech Republic manufacturing expansion drives volume demand for cost-optimized formulations in household product assembly.
Automotive commands the largest value share; medical end-use is expanding most quickly.
Application:
Volume concentration varies by process intensity, with bonding dominating industrial throughput while coating and sealing applications carry higher per-unit margins in specialized manufacturing.
- Bonding:Permanent joining of metals, plastics, and rubber substrates constitutes the core application across automotive and electronics assembly lines. German automotive plants integrate this process with IoT-enabled dispensing equipment for real-time quality monitoring.
- Sealing:Hermetic closure applications in medical device manufacturing require validated cure profiles under EU Medical Device Regulation CE marking timelines.
- Coating:Protective surface treatments in electronics assembly face substitution pressure from UV-curable epoxies offering superior thermal stability.
- Repairing:Field maintenance applications in industrial equipment service generate aftermarket demand through specialized distribution networks.
Bonding holds the largest share; sealing gains share fastest.
Packaging Type:
Supply concentration in precision dispensing systems creates margin differentiation, with syringe and specialized delivery formats commanding premiums over commodity bottle and tube configurations.
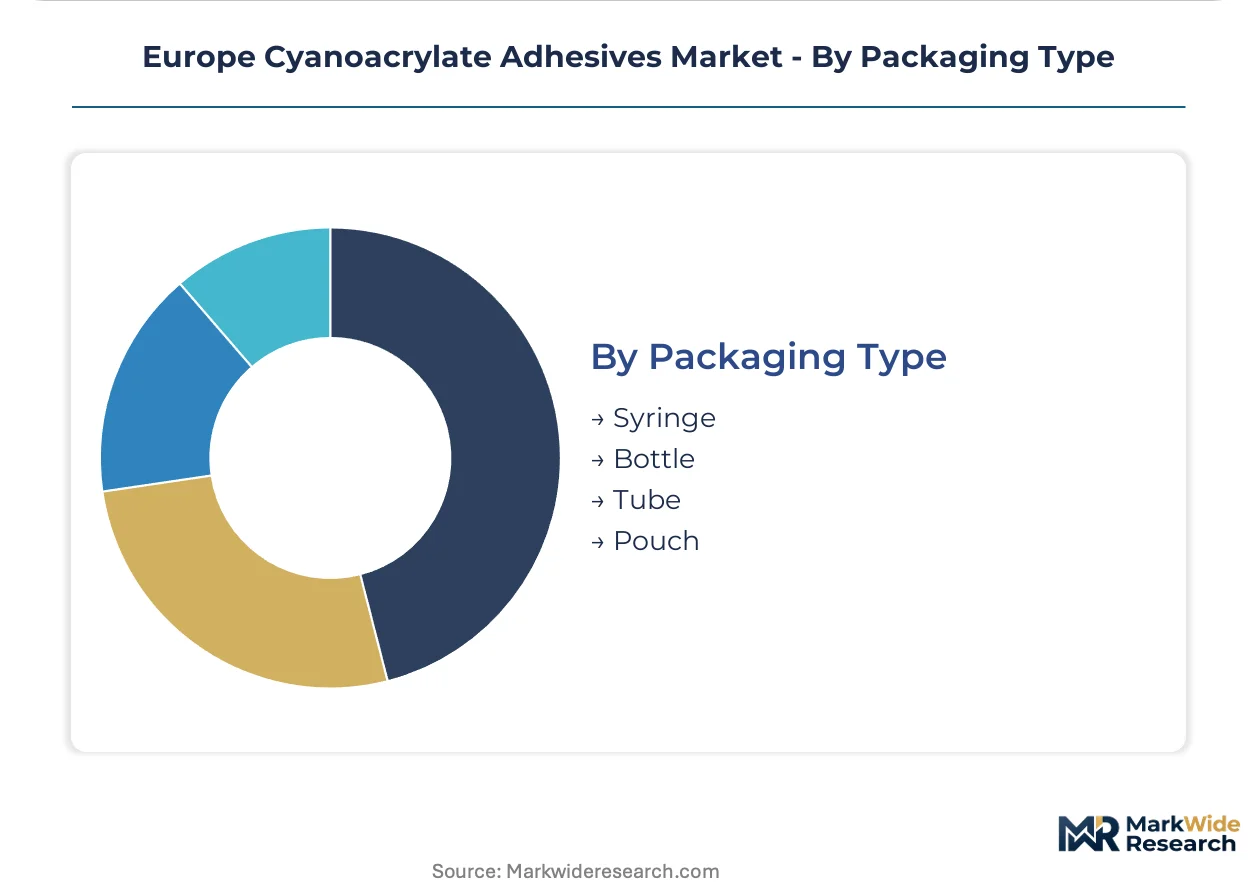
- Syringe:Pre-filled, single-use delivery systems dominate medical and precision electronics applications where contamination control is critical. Illinois Tool Works anchors market position through specialized dispensing systems integrated with high-speed assembly lines.
- Bottle:Bulk containers serve high-volume industrial users in German automotive plants with automated application equipment.
- Tube:Squeeze formats target maintenance and repair channels across European industrial distributors.
- Pouch:Flexible packaging reduces shipping costs for export-led medical adhesive shipments from Swiss and Dutch logistics hubs.
Syringe packaging holds the largest share; pouch formats show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal decarbonization mandates are redirecting automotive assembly investment toward adhesive-intensive lightweight architectures across German and French manufacturing corridors. REACH compliance costs and ECHA substance evaluations are compressing formulation development timelines while elevating technical barriers for suppliers serving medical and electronics sectors.
Germany
Automotive OEMs in Stuttgart and Munich specify cyanoacrylate bonding to replace mechanical fasteners in electric vehicle platforms under EU Green Deal mandates. ECHA catalyst system restrictions are forcing BASF and Henkel to reformulate accelerator chemistries for assembly line compatibility. Baden-Württemberg's industrial corridor concentrates medical device manufacturing where surgical adhesive demand is displacing traditional suturing.
France
Aerospace component suppliers in Toulouse adopt methyl cyanoacrylate formulations for high-tensile metal bonding in composite airframe assembly. ANSM biocompatibility standards align with EMA Class III device requirements for wound closure applications. Île-de-France hospital networks consolidate procurement through group purchasing organizations favoring multi-product adhesive suppliers with CE marking expertise.
Switzerland
Swissmedic regulations govern surgical adhesive exports to EU markets from Basel and Zurich manufacturing bases. Precision dispensing equipment integration with IoT-enabled quality monitoring is elevating technical service requirements for wound closure suppliers. The country's pharmaceutical cluster demands advanced monomer purification protocols that extend bond durability under thermal stress.
Poland
Automotive component manufacturing migration from Western Europe is creating demand for localized ethyl cyanoacrylate supply in Silesian industrial zones. Butyl cyanoacrylate formulations serve flexible substrate applications in consumer goods assembly where cost optimization outweighs performance premiums. Polish manufacturing expansion lacks domestic formulation expertise, creating import dependency for specification-grade chemistries.
Netherlands
Rotterdam logistics hubs facilitate medical-grade adhesive distribution to European hospital networks under EMA temperature-controlled shipping protocols. CSRD sustainability reporting requirements favor suppliers with verified lifecycle data for bio-based formulation pathways. Dutch electronics assemblers standardize on high-speed component bonding where thermal curing remains impractical.
Europe Cyanoacrylate Adhesives Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with adhesive portfolio breadth alongside specialized dispensing system integrators. Market structure concentrates around three strategic tiers: integrated material-equipment providers commanding automotive contracts, medical-grade specialists capturing wound closure premiums, and regional distributors serving price-sensitive assembly operations. Dominant competitive moves include backward integration into monomer production and strategic partnerships with IoT-enabled application equipment manufacturers.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and Arkema Group exemplify portfolio-breadth strategies that span industrial and medical-grade formulations. Illinois Tool Works Inc. occupies a distinct position linking material supply to precision dispensing infrastructure. H.B. Fuller Company represents the mid-tier specialist archetype with concentrated exposure to automotive and electronics assembly verticals. These three anchors illustrate how competitive positioning diverges between chemistry-led and equipment-led value capture models.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Illinois Tool Works Inc. |
| 3M |
| Pidilite Industries Ltd. |
| Aica Kogyo Co. Ltd. |
| Arkema Group |
| Soudal Holding N.V. |
| NANPAO RESINS CHEMICAL GROUP |
| H.B. Fuller Company |
| Others |
Supply & Pricing Matrix
Capacity utilization at German monomer production facilities shapes price floors across industrial-grade ethyl cyanoacrylate tiers, while Swiss medical-grade purification capacity anchors premium octyl cyanoacrylate pricing. REACH compliance costs and ECHA catalyst system restrictions compress margins for standard-grade suppliers unable to pass reformulation expenses downstream.
Pricing Analysis
Certification level creates the primary spread across medical-grade octyl cyanoacrylate commanding premium multiples over industrial ethyl formulations. Pricing stratifies across EMA Class III biocompatible tiers, REACH-compliant industrial grades, and cost-optimized butyl variants for consumer assembly. Cost compression in standard industrial tiers intensifies as UV-curable epoxies displace cyanoacrylates in electronics coating applications. Automotive OEM procurement teams exhibit lowest price sensitivity due to dispensing system integration lock-in, while Polish consumer goods assemblers drive volume negotiations for flexible substrate formulations.
Supply Chain Analysis
Germany and Switzerland anchor monomer production and medical-grade purification respectively, with Dutch distribution hubs facilitating temperature-controlled logistics to hospital networks. Raw material flows draw from ethyl cyanoacrylate monomer feedstock, specialized accelerator chemistries, and pharmaceutical-grade packaging components. Single-source vulnerability concentrates in medical-grade octyl cyanoacrylate purification capacity. Distribution runs through Swiss and Dutch logistics clusters serving pan-European hospital procurement networks, with direct mill supply relationships dominating German automotive plant consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from EMA biocompatibility standards evolution creating specialized niches for surgical adhesive suppliers with device master file expertise. Hospital procurement consolidation across France and Italy fragments volume concentration among multi-product adhesive portfolios.
For Market Incumbents: Secure backward integration into monomer production to defend margin position against REACH-driven catalyst reformulation costs. Expand captive supply of ethyl cyanoacrylate feedstock in Baden-Württemberg to insulate automotive contracts from import dependency. Deepen dispensing system integration partnerships to reinforce technical service lock-in against UV-curable epoxy substitution in electronics assembly. For New Entrants and Emerging Players: CE marking fast-track under EU Medical Device Regulation creates entry pathway for wound closure adhesive specialists. Target Polish and Czech Republic automotive component manufacturing zones where localized supply gaps meet cost-optimized formulation demand. Pursue technical service partnerships with IoT-enabled dispensing equipment manufacturers to bypass direct chemistry R&D barriers. For Investors and Strategic Acquirers: Mid-cap formulation specialists with REACH compliance infrastructure and EMA device master file portfolios represent prime acquisition targets. Long-term viability hinges on regulatory capacity rather than scale economies in this compliance-intensive specialty chemicals segment. Monitor ECHA substance evaluation timelines as inflection indicator for catalyst system obsolescence risk and reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive ethyl cyanoacrylate supply insulates Henkel and Arkema from import volatility and REACH-driven cost spikes. |
| CE Marking Pathway Investment | EMA Class III device master file capability unlocks premium surgical adhesive contracts with German university hospital networks. |
| IoT-Enabled Dispensing System Partnership | Illinois Tool Works leverages precision equipment integration to capture automotive assembly line service contracts. |
| Green Manufacturing Transition | CSRD-compliant lifecycle data attracts EU manufacturer procurement under sustainability reporting mandates. |
| Geographic Manufacturing Footprint Expansion | Polish Silesian industrial zones offer cost-competitive assembly proximity for automotive component supply. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA substance evaluation databases, EU customs trade flows, and SEC filings from adhesive portfolio conglomerates. Interviews with German automotive procurement directors, Swiss surgical device R&D leads, Dutch hospital GPO contracts managers, and Polish consumer goods plant engineers inform demand-side validation. Top-down market sizing triangulates against bottom-up segment aggregation across ethyl, octyl, butyl, and methyl cyanoacrylate chemistries.
Segmentation dimensions modeled span product type, end-use industry, application method, and packaging format across the projection horizon. CAGRs derive from elasticity-adjusted volume projections incorporating EU Green Deal automotive lightweighting mandates and EMA biocompatibility standards evolution. Forecast inputs include REACH authorization timeline scenarios and hospital procurement consolidation patterns in France and Italy.
Underlying assumptions cover ECHA catalyst system evaluation outcomes and EU Medical Device Regulation transition stability, with deviation risk concentrated in medical-grade monomer supply disruptions and UV-curable epoxy substitution acceleration in electronics coating. Recalibration cycles align with material shifts in EMA biocompatibility standards and CSRD sustainability reporting implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
PVA Glue Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Urethane Adhesives Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Melamine Based Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Middle East and Africa Sealants Market