
 Tissue Adhesives Market | 2026-2036
Tissue Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Adhesives Market Analytics
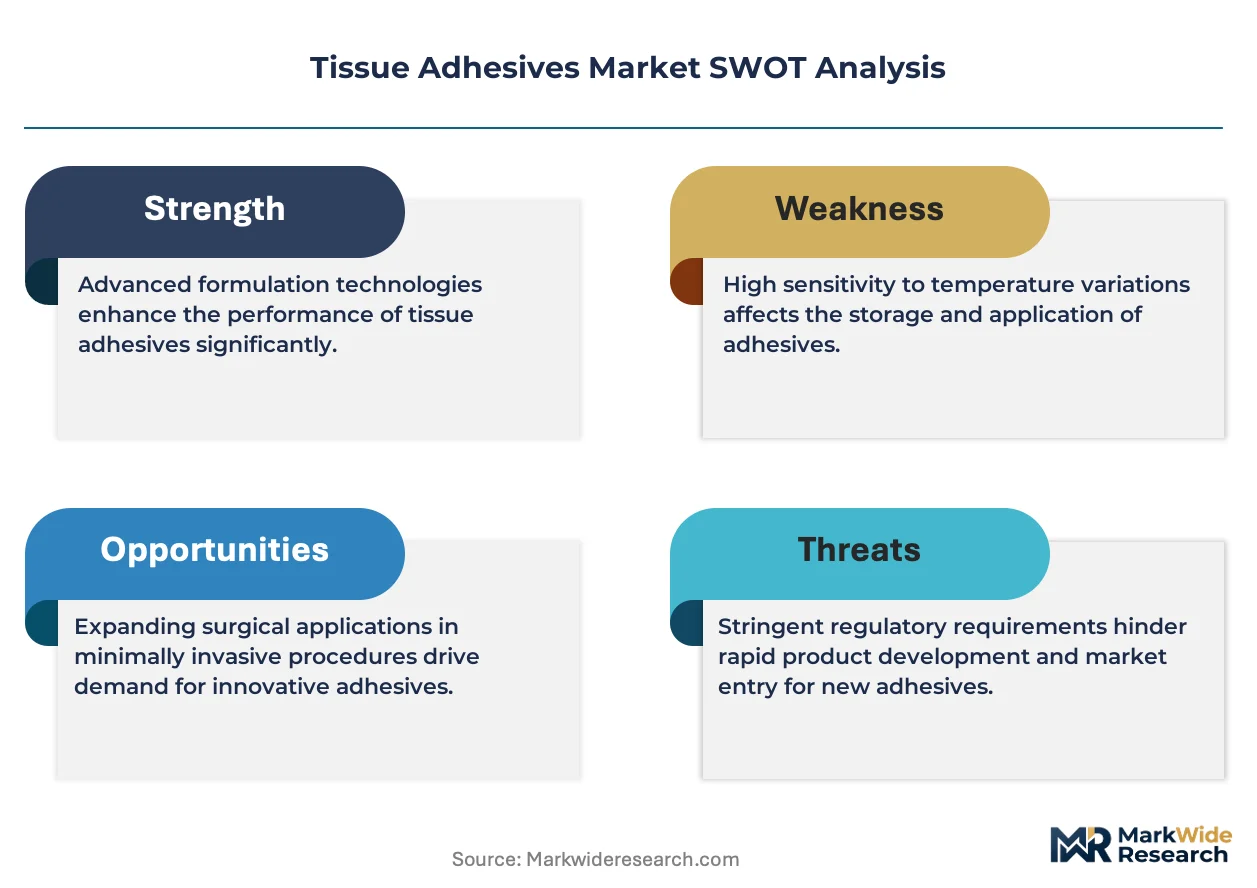
A capital-intensity divergence between integrated multinationals and specialized adhesive developers is bifurcating competitive dynamics in tissue adhesives. Johnson & Johnson leverages its Ethicon surgical portfolio to sustain dominance in operating-room distribution channels. Baxter International anchors its position through plasma-derived fibrin sealant manufacturing that competitors struggle to replicate at equivalent scale. CryoLife specializes in cardiac and vascular adhesive applications, occupying a defensible niche where regulatory barriers limit new entrants.
Tissue adhesives comprise synthetic or biological formulations that polymerize upon tissue contact to form flexible bonds, with cyanoacrylate variants setting within 30-60 seconds under physiological moisture conditions. These materials serve primarily to replace or supplement sutures and staples in wound closure, reducing operative time and needle-stick injuries. Fibrin-based adhesives command premium positioning in hemostatic applications where biocompatibility overrides cost sensitivity, while cyanoacrylate segments compete on speed and ease of use in superficial wound closure. The surgical procedures application category draws disproportionate investment as laparoscopic and robotic platforms expand adhesive-compatible access routes.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments shape product development timelines and clinical evidence requirements for tissue adhesive manufacturers. ISO 10993 biocompatibility testing standards further constrain material selection and supplier qualification processes. Stakeholders must monitor evolving CMS and national health technology assessment body decisions on adhesive reimbursement parity relative to conventional closure methods, as these determinations will influence hospital procurement prioritization and manufacturer commercial strategy.
Market Dynamics
Minimally invasive surgical platforms are compressing operative timeframes and elevating adhesive-compatible access routes, forcing manufacturers to reformulate viscosity and setting-speed parameters for laparoscopic delivery systems.
Growth Catalysts
- Laparoscopic expansion:Robotic surgery installations in tertiary hospitals are creating dedicated adhesive procurement budgets for port-site closure and mesenteric sealing.
- FDA 510(k) pathway streamlining:Predicate device referencing for cyanoacrylate variants is compressing regulatory timelines for incremental formulation improvements.
- Needle-stick injury reduction mandates:OSHA bloodborne pathogen compliance pressures are accelerating suture substitution in emergency departments across the United States.
Market Restraints
- Bovine-derived thrombin supply concentration:Plasma fractionation capacity concentrates in North American and European facilities, exposing fibrin sealant manufacturers to raw material bottlenecks.
- Technical limitation:Cyanoacrylate brittleness under cyclical loading restricts load-bearing applications in orthopedic and fascial closure.
- EMA MDR clinical evidence escalation:Post-market surveillance requirements for Class III devices are extending recertification cycles and inflating quality management system costs.
Strategic Opportunities
- Pediatric cardiac surgery:Tissue fragility in neonatal populations creates premium positioning for low-exotherm adhesive formulations with enhanced flexibility profiles.
- Japan's PMDA Sakigake designation:Expedited review pathways for regenerative medicine products are attracting fibrin-based adhesive developers seeking priority market access.
- Point-of-care wound closure kits:Pre-filled adhesive applicators with integrated hemostatic matrices are penetrating ambulatory surgical centers and combat medic supply chains.
Industry Challenges
- Polymer chemistry specialization gap:Formulation scientists with simultaneous expertise in biocompatible cyanoacrylate synthesis and surgical workflow integration command scarcity premiums that constrain R&D team scaling.
- ISO 10993-5 cytotoxicity retesting:Supplier changes in stabilizer or dye components trigger full biocompatibility panel repetition, compressing product update cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Adhesives Market |
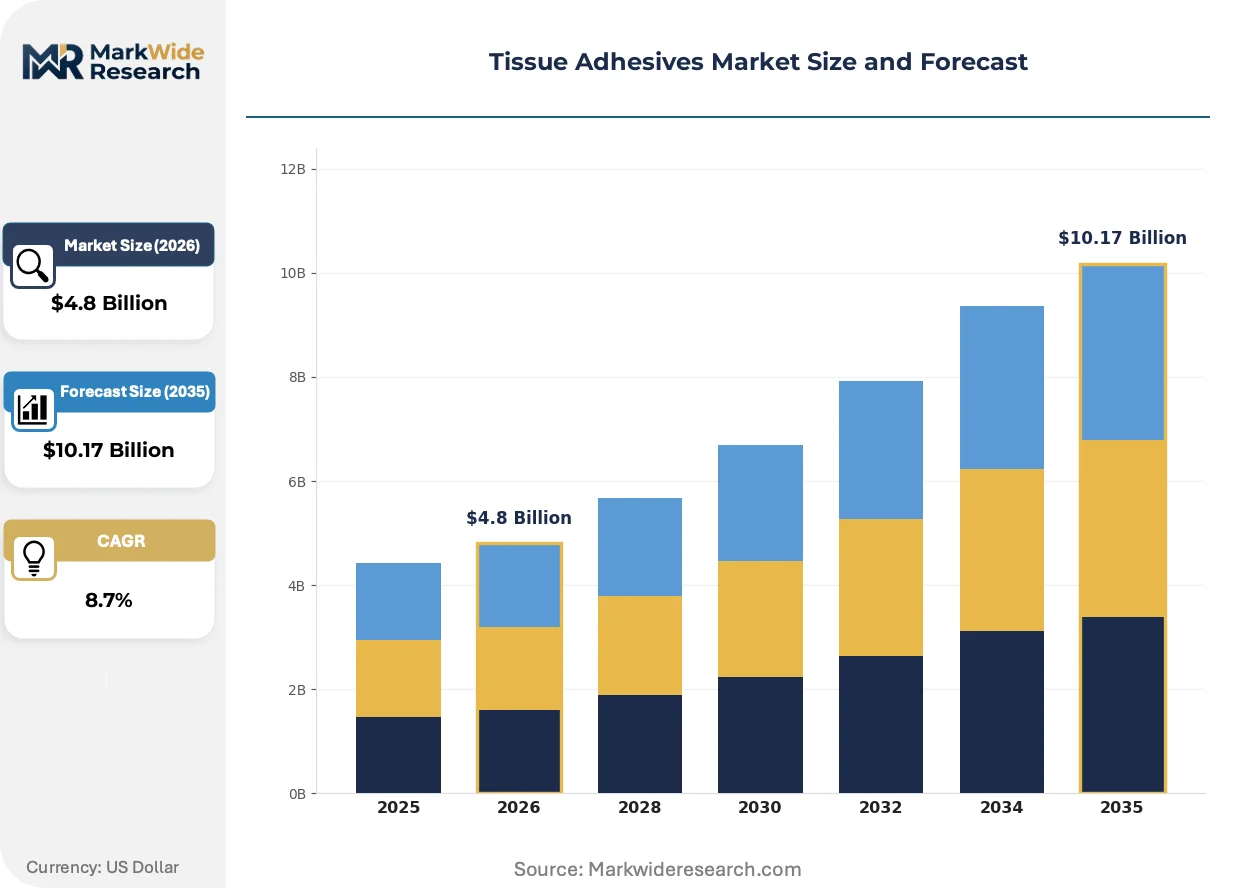
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyanoacrylate, Fibrin, Albumin, Polyethylene Glycol Application: Wound Closure, Surgical Procedures, Trauma Treatment, Tissue Repair End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Care Technology: Topical, Internal, Biodegradable, Non-Biodegradable |
| Companies Covered | Johnson & Johnson, Baxter International Inc., Becton, Dickinson and Company, Medtronic, Integra LifeSciences, B. Braun Melsungen AG, CryoLife, Inc., Cohera Medical, Inc., Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Adhesives Market Evolving Landscape
Formulation chemistry and delivery mechanism engineering are converging to address the tension between rapid polymerization and tissue-compatible exotherm profiles.
Photocurable hybrid adhesives incorporating methacrylated gelatin backbones are supplanting conventional cyanoacrylates in dermal closure applications where controlled cure rates prevent thermal necrosis. Plastic surgery units in South Korean and Brazilian tertiary hospitals are piloting these systems for facial wound approximation. The technology is compressing revision surgery rates while commanding per-procedure premiums that offset slower application times.
EMA Medical Device Regulation Annex XIV clinical evaluation requirements are mandating prospective registry data for fibrin sealant safety surveillance. Manufacturers must now submit post-market clinical follow-up protocols as condition of CE marking renewal. Cardiac surgery applications face the steepest evidence burden, with some suppliers withdrawing from thoracic indications rather than absorbing longitudinal study costs.
Hospital value analysis committees are consolidating closure modality purchasing decisions under perioperative supply managers rather than surgeon preference cards. This centralization is elevating total cost-of-closure analytics over unit price comparisons in the United States and Germany. Adhesive vendors are responding with bundled pricing models that incorporate applicator training and waste reduction guarantees.
Tissue Adhesives Market Segmentation
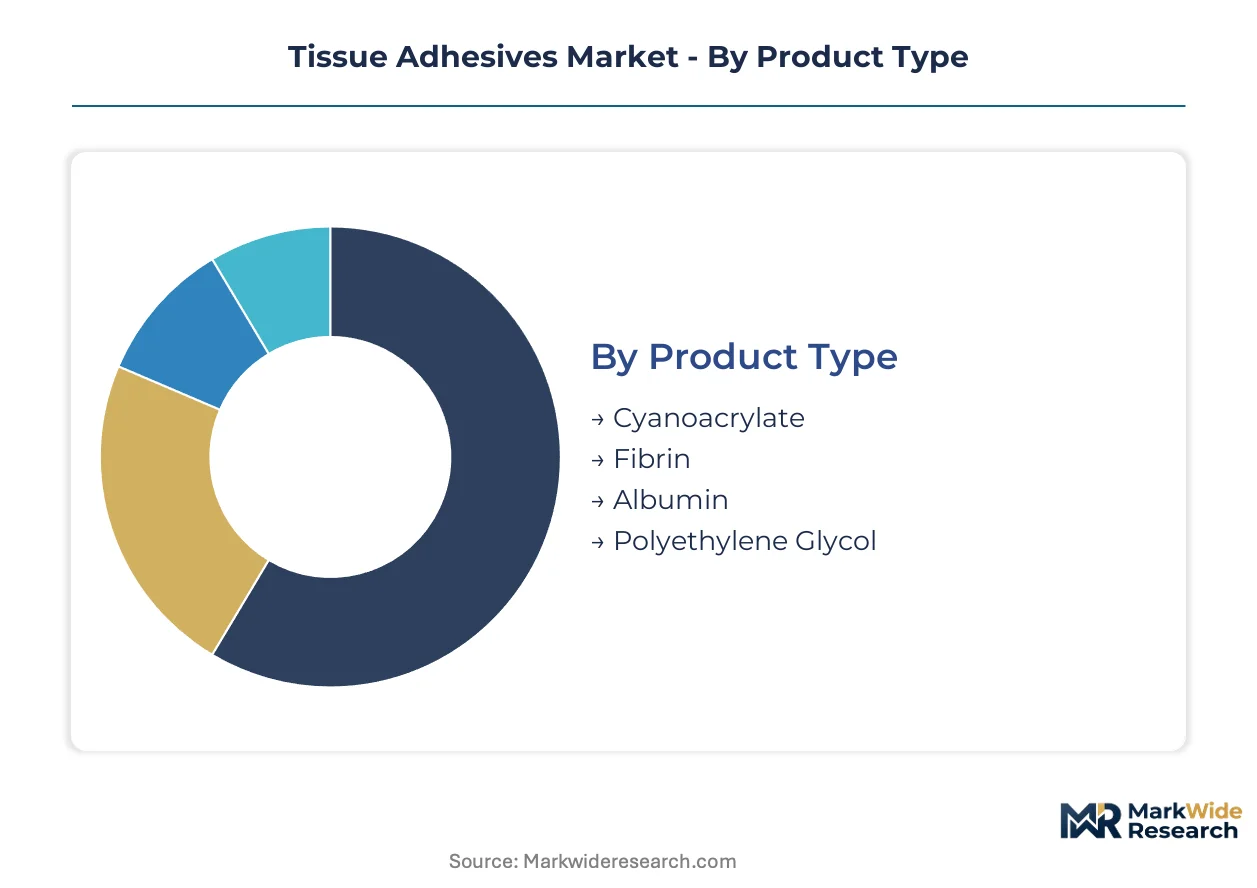
Tissue adhesive manufacturers configure product portfolios across four intersecting dimensions. Each segmentation axis carries distinct regulatory pathways, margin structures, and customer procurement behaviors that shape commercial strategy.
Product Type:
Cyanoacrylate formulations dominate domestic hospital procurement in the United States and Germany, while fibrin-based adhesives anchor export-led supply chains serving Japanese and South Korean cardiac surgery centers.
- Cyanoacrylate:Synthetic ester formulations polymerize through anionic chain reaction upon tissue contact, delivering sub-60-second set times. Demand concentrates in United States emergency departments where OSHA needle-stick mandates accelerate suture substitution.
- Fibrin:Plasma-derived thrombin and fibrinogen combinations replicate final coagulation cascade stages. Japanese tertiary hospitals absorb premium volumes for pediatric cardiac applications where biocompatibility overrides cost sensitivity.
- Albumin:Cross-linked protein matrices derived from human or bovine serum. European hemostatic product developers integrate albumin sealants into hybrid formulations.
- Polyethylene Glycol:Synthetic hydrogel systems forming covalent tissue bonds without exothermic reaction. Niche positioning in dural and neural tissue applications.
Cyanoacrylate commands the established base. The steepest expansion runs through polyethylene glycol formulations penetrating neural surgery protocols.
Application:
Cost tier stratification separates high-acuity surgical applications from commoditized superficial wound closure, with reimbursement parity determining hospital procurement prioritization.
- Wound Closure:Superficial skin approximation in emergency and ambulatory settings. United States trauma centers drive volume through adhesive-based laceration repair protocols.
- Surgical Procedures:Laparoscopic port-site sealing and mesenteric bonding during minimally invasive operations. Robotic surgery installations in German tertiary hospitals create dedicated procurement budgets.
- Trauma Treatment:Battlefield and pre-hospital hemostasis where rapid application supersedes precision. Combat medic supply chains in NATO member states standardize pre-filled applicator formats.
- Tissue Repair:Vascular anastomosis reinforcement and parenchymal organ sealing. EMA MDR Class III device classification elevates clinical evidence requirements.
Surgical procedures absorb the highest per-procedure pricing. Trauma treatment is climbing fastest through defense procurement standardization.
End User:
Customer type determines packaging configuration, training intensity, and regulatory jurisdiction, with hospital systems consolidating purchasing decisions under perioperative supply managers.
- Hospitals:Integrated delivery networks in the United States and Germany negotiate bundled pricing incorporating applicator training and waste reduction guarantees. Value analysis committees elevate total cost-of-closure analytics over unit price.
- Ambulatory Surgical Centers:Freestanding facilities in United States metropolitan markets favor pre-filled, single-use applicators minimizing pharmacy preparation overhead.
- Clinics:Dermatology and plastic surgery practices in South Korea and Brazil pilot photocurable hybrid systems for facial wound approximation.
- Home Care:Post-discharge wound management for chronic ulcer patients. Reimbursement fragmentation limits penetration outside German and Japanese long-term care insurance frameworks.
Hospitals anchor volume concentration. Ambulatory surgical centers are expanding most quickly through United States site-of-service migration.
Technology:
Biodegradability specifications and application depth define regulatory classification, with internal-use technologies commanding stricter biocompatibility panels than topical alternatives.
- Topical:Epidermal and superficial dermal bonding without systemic absorption. FDA 510(k) predicate pathways compress clearance timelines for incremental formulation improvements.
- Internal:Intra-cavitary and parenchymal applications requiring absorbable or permanent implant profiles. EMA MDR Annex XIV clinical evaluation mandates prospective registry data submission.
- Biodegradable:Hydrolytic or enzymatic degradation synchronized with tissue healing timelines. ISO 10993-6 implantation testing standards constrain degradation byproduct toxicity profiles.
- Non-Biodegradable:Permanent polymer networks for structural reinforcement in vascular and dural applications. Limited to cyanoacrylate and polyethylene glycol chemistries.
Topical technologies hold the volume base. Internal biodegradable systems are gaining share fastest through laparoscopic platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German tertiary hospitals where reimbursement parity for adhesive-based closure has matured, while United States procurement remains fragmented across integrated delivery networks negotiating disparate bundled contracts.
United States
OSHA needle-stick injury mandates accelerate suture substitution in emergency departments, while FDA 510(k) predicate pathways compress clearance timelines for cyanoacrylate improvements. The Mayo Clinic and Cleveland Clinic anchor demand concentration for robotic surgery adhesive procurement.
Germany
EMA MDR Annex XIV clinical evaluation requirements mandate prospective registry data for fibrin sealant surveillance, elevating evidence burdens for thoracic indications. The Berlin-Brandenburg medical technology cluster hosts value analysis committees consolidating perioperative purchasing decisions.
Japan
PMDA Sakigake designation for regenerative medicine products attracts fibrin-based developers seeking priority market access, with pediatric cardiac applications commanding premium positioning. Tokyo and Osaka tertiary hospitals absorb disproportionate volumes for neonatal tissue fragility solutions.
South Korea
Photocurable hybrid adhesive pilot programs in plastic surgery units drive facial wound approximation demand, while MFDS streamlined review pathways accelerate novel formulation approvals. Seoul National University Hospital anchors dermal closure technology adoption.
Brazil
ANVISA biocompatibility testing alignment with ISO 10993 standards constrains imported product entry, creating procurement preference for established suppliers. São Paulo's Albert Einstein Hospital network standardizes adhesive protocols for ambulatory surgical expansion.
Tissue Adhesives Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated multinationals commanding surgical portfolio distribution channels while specialized developers occupy defensible niches. The market structure bifurcates between scale-driven fibrin sealant manufacturers and agile cyanoacrylate formulators. Three strategic archetypes dominate: diversified surgical conglomerates leveraging cross-product bundling, plasma-fractionation specialists with captive biological supply, and cardiac-focused developers fortified by regulatory barriers. Competitive moves concentrate on perioperative supply manager consolidation and point-of-care applicator pre-fill formats.
Among diversified surgical conglomerates, Johnson & Johnson and Baxter International occupy positions defined by distribution infrastructure depth and biological manufacturing scale respectively. CryoLife exemplifies the cardiac-specialist archetype where indication-specific regulatory barriers limit competitive entry. These three anchors represent the spectrum from broad surgical portfolio leverage to concentrated biological expertise.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Baxter International Inc. |
| Becton, Dickinson and Company |
| Medtronic |
| Integra LifeSciences |
| B. Braun Melsungen AG |
| CryoLife, Inc. |
| Cohera Medical, Inc. |
| Smith & Nephew |
| Others |
Value Network & Pricing Analysis
ISO 10993 biocompatibility testing standards gate both raw material supplier qualification and price differentiation between medical-grade and industrial-grade cyanoacrylate feedstocks. Manufacturers absorbing full biocompatibility panel costs command premium positioning in cardiac and neural applications where regulatory compliance overrides procurement cost sensitivity.
Pricing Analysis
Configured-to-order pricing for pediatric cardiac formulations spreads 40-60 percent above standard emergency-department cyanoacrylate SKUs. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 10993-6 implantation testing depth and FDA 510(k) predicate complexity. Cost compression in standard topical segments is intensifying because hospital value analysis committees consolidate purchasing under perioperative supply managers. Ambulatory surgical centers exhibit highest price sensitivity; Japanese tertiary hospitals absorbing fibrin sealant volumes show lowest.
Supply Chain Analysis
Container availability constraints on North Atlantic trade lanes elevate inbound logistics costs for European plasma fractionation facilities sourcing bovine thrombin from United States abattoirs. Manufacturing concentrates in United States, Germany, and Japan where FDA, EMA MDR, and PMDA certification infrastructure supports high-margin production. Raw material dependencies center on plasma-derived fibrinogen, pharmaceutical-grade cyanoacrylate monomers, and methacrylated gelatin precursors. Single-source vulnerability concentrates in North American plasma fractionation capacity. Distribution runs through surgical device distributors and hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital value analysis committees in United States integrated delivery networks and German tertiary hospital systems, fragmenting surgeon preference-card autonomy.
For Market Incumbents: Secure backward integration into plasma fractionation capacity to insulate fibrin sealant margins from raw material bottlenecks. Deepen channel control through exclusive GPO contracts with United States hospital systems before reimbursement parity determinations finalize. Emerging photocurable hybrid entrants threaten cyanoacrylate volume in dermal closure segments. For New Entrants and Emerging Players: Anchor in polyethylene glycol neural surgery applications where EMA MDR Class III barriers have forced incumbent withdrawals. Pediatric cardiac surgery in Japanese and South Korean tertiary hospitals offers the most penetrable premium segment. Pursue PMDA Sakigake designation pathways to compress regulatory timelines against established fibrin sealant suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable internal-use adhesive manufacturing as ISO 10993-6 implantation testing and longitudinal registry requirements escalate quality management system costs. Five-to-ten year viability favors acquisition targets with captive biological supply chains or demonstrated regulatory navigation in cardiac Class III indications. Monitor EMA MDR Annex XIV clinical evaluation cost absorption as inflection signal for fibrin sealant manufacturer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatibility Certification Investment | ISO 10993-5 and ISO 10993-6 testing depth determines market access tier in cardiac applications. |
| Plasma Fractionation Capacity Expansion | Captive thrombin supply insulates fibrin sealant margins from North American raw material concentration. |
| Pre-filled Applicator Format Development | Point-of-care wound closure kits penetrate ambulatory surgical centers and combat medic supply chains. |
| PMDA Sakigake Pathway Pursuit | Expedited Japanese review accelerates priority market access for regenerative medicine adhesive formulations. |
| Hospital GPO Contract Consolidation | Exclusive agreements with United States integrated delivery networks lock out emerging photocurable hybrid competitors. |
Research Methodology
Cross-validation between FDA 510(k) clearance databases and EMA MDR notified body conformity assessments anchors the qualitative findings on regulatory pathway timelines. Primary interviews with surgical adhesive formulation scientists, hospital perioperative supply managers, plasma fractionation procurement leads, and biomedical engineers combined with secondary validation from FDA filings, EMA submissions, ISO 10993 test laboratory reports, and hospital GPO contract databases. Bottom-up volume triangulation against top-down expenditure flows verified segment-level estimates.
Sensitivity analysis on laparoscopic surgery adoption rates and reimbursement parity determinations shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry class, application acuity tier, end-user facility type, and technology biodegradability profile. CAGRs derived from procedure volume elasticity to adhesive penetration rates and pricing trajectory assumptions. Forecast inputs incorporate robotic surgery installation counts and EMA MDR recertification cycle extensions.
Decision-makers should treat outputs as directional under base assumptions of stable plasma fractionation capacity and maintained reimbursement parity for adhesive-based closure; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
China Sealants Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
United States Sealants Market
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market