
 Acrylates Copolymer Market | 2026-2036
Acrylates Copolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylates Copolymer Market Analysis
Asian petrochemical producers is recalibrating acrylates copolymer capacity to serve specialty-grade personal care and coatings demand. BASF SE leverages integrated acrylic acid backbones to sustain margin capture across emulsion and solution grades. Arkema anchors its position through advanced dispersion polymerization technology for high-clarity cosmetic films. The Dow Chemical Company competes on manufacturing scale in construction-grade emulsions for sealant applications.
Acrylates copolymer denotes a family of thermoplastic resins synthesized from acrylic acid esters and comonomers such as methacrylates or styrene, typically produced via emulsion or solution polymerization to achieve controlled molecular weights between 10,000 and 1,000,000 Daltons for tunable film flexibility and adhesion. These polymers function primarily as binders, rheology modifiers, and protective film formers across cosmetics, architectural coatings, and pressure-sensitive adhesives. Emulsion polymerization dominates production economics for waterborne coatings and personal care formulations, while bulk polymerization serves high-purity grades for medical and optical applications where residual solvent thresholds are stringent. Powder and granule formats command premium positioning in automated dry-mix construction systems and textile sizing operations where liquid handling logistics constrain adoption.
EPA oversight of volatile organic compound emissions in architectural coatings restricts solvent-borne solution polymer sales in the United States, redirecting formulation R&D toward low-VOC emulsion alternatives. REACH registration requirements in Europe mandate full monomer supply chain disclosure, elevating compliance costs for imports and favoring regional producers with established substance dossiers. FDA cosmetic ingredient reviews in the United States scrutinize acrylates copolymer safety profiles in leave-on products, influencing formulation substitution patterns among personal care brands. Stakeholders must track polymerization technology licensing costs and regional regulatory divergence to optimize capacity placement and product qualification investments.
Market Dynamics
Waterborne emulsion polymerization routes are displacing solvent-borne solution processes as REACH residual monomer limits tighten and EPA VOC thresholds harden, compressing legacy capacity economics while rewarding producers with integrated acrylic acid backbones and advanced dispersion control.
Growth Catalysts
- Personal care film formers:Hair styling and sunscreen formulators specify acrylates copolymers for humidity resistance and UV filter compatibility, pulling specialty-grade volume from emulsion polymerization lines.
- REACH registration dossiers:Full monomer supply chain disclosure requirements in Europe favor regional producers with established substance portfolios, creating qualified-supplier premiums for compliant imports.
- China coatings production:Domestic architectural and industrial coatings expansion concentrates manufacturing pull for both imported and local acrylates copolymer supply in East Asian petrochemical corridors.
Market Restraints
- Acrylic acid feedstock volatility:Crude-linked propylene oxidation economics transmit petrochemical cycle swings directly into copolymer margin structures, squeezing non-integrated compounders.
- Specialty-grade supply concentration:High-clarity cosmetic film production clusters with advanced dispersion technology holders in Western Europe and select Northeast Asian facilities, creating single-source risk for qualified personal care supply.
- Silicone-polyurethane substitution:Pressure-sensitive adhesive and sealant formulators trial hybrid silicone-urethane systems where acrylates copolymer tack and temperature resistance underperform specification.
Strategic Opportunities
- India personal care manufacturing:CDSCO cosmetic ingredient registration pathways and PLI scheme incentives for specialty chemicals attract acrylates copolymer qualification investments from multinational formulators establishing local production.
- Biobased acrylic acid integration:Fermentation-derived 3-hydroxypropionic acid routes to acrylic acid are converging with existing emulsion polymerization infrastructure, enabling carbon accounting advantages for sustainability-positioned brands.
- Automated dry-mix construction:Powder and granule format acrylates copolymers penetrate mortar and textile sizing systems where liquid logistics constraints previously blocked adoption, opening industrial volume channels.
Industry Challenges
- Emulsion polymerization scale-up expertise:Controlled molecular weight distribution engineering for 10,000 to 1,000,000 Dalton specifications requires scarce process chemistry talent, constraining capacity additions outside established technology licensees.
- FDA cosmetic ingredient review timelines:Leave-on product safety dossier preparation and response cycles extend 18-24 months, delaying formulation lock for personal care launches and compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylates Copolymer Market |
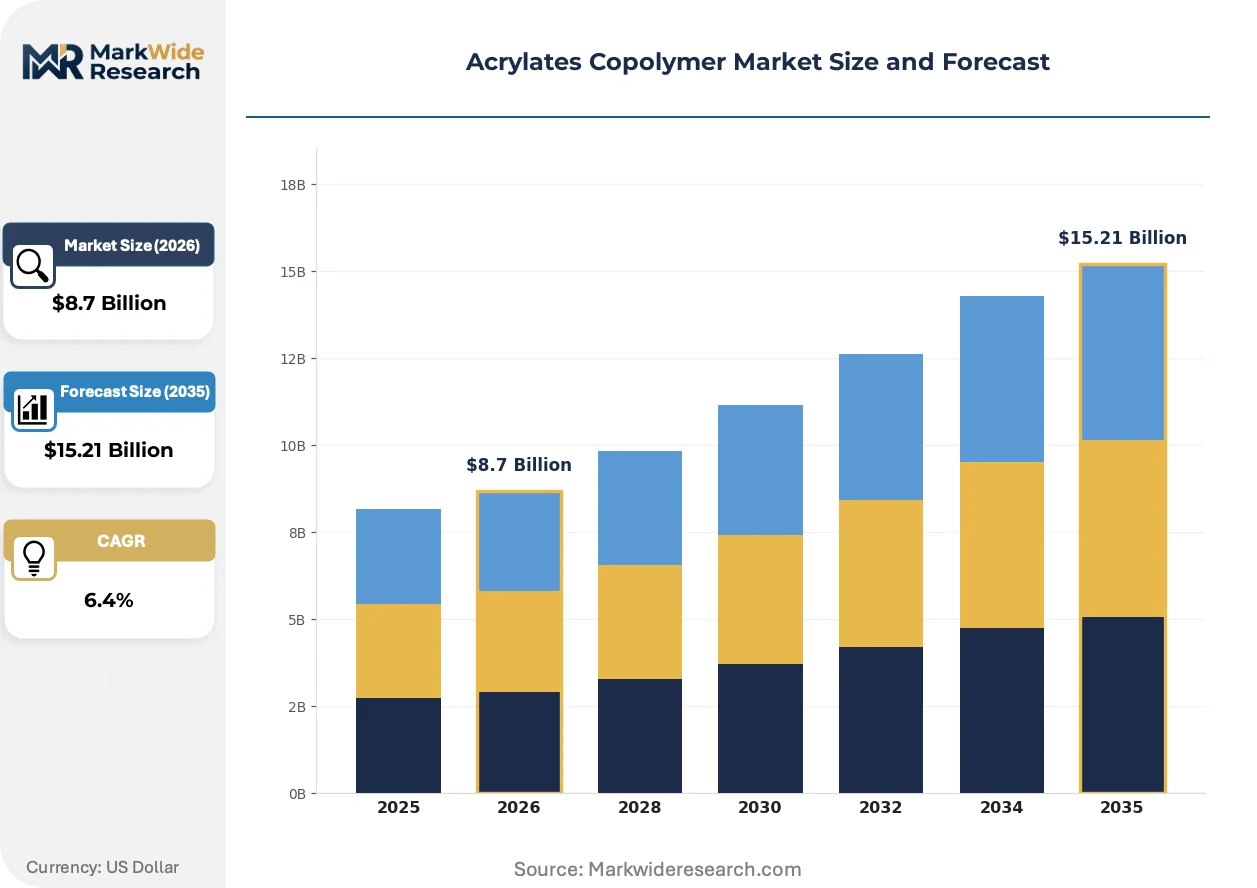
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Solution, Powder, Granule End User: Personal Care, Paints, Adhesives, Coatings Application: Cosmetics, Sealants, Textiles, Construction Technology: Dispersion Polymerization, Bulk Polymerization, Solution Polymerization, Emulsion Polymerization |
| Companies Covered | Celanese Corporation, ACURO ORGANICS LIMITED, Arkema, OMNOVA Solutions Inc., Archroma, BASF SE, The Lubrizol Corporation, H.B. Fuller Company, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylates Copolymer Market Emerging Trajectories
Reactive surfactant-free emulsion polymerization is compressing residual monomer thresholds while enabling direct cosmetic-grade qualification, shifting R&D allocation from post-polymer purification toward in-process molecular architecture control.
Hybrid acrylates-silicone copolymer architectures are unifying film flexibility and water resistance in single-binder systems. Premium hair care and sun care formulators in South Korea and Japan specify these hybrids for wash-off durability without silicone-heavy aesthetic drawbacks. The technology is unifying previously separate formulation steps, reducing SKU complexity for contract manufacturers.
ECHA REACH authorization list expansion for acrylic acid ester monomers is redirecting formulation qualification toward pre-registered polymer grades with demonstrated residual control. Importers without substance dossiers face elevated compliance costs and extended customs clearance timelines. Personal care contract manufacturers in Germany and France accelerate supplier audits to lock qualified polymer sources before 2027 review cycles.
Direct-to-brand technical service models are displacing traditional distributor-led specification support in North American architectural coatings. Large formulators in Ohio and Texas retain polymer scientists for on-site dispersion optimization, bypassing regional chemical distributors who previously controlled formulation guidance. This pattern concentrates volume with producers maintaining dedicated technical service laboratories in proximity to major coatings clusters.
Acrylates Copolymer Market Segmentation
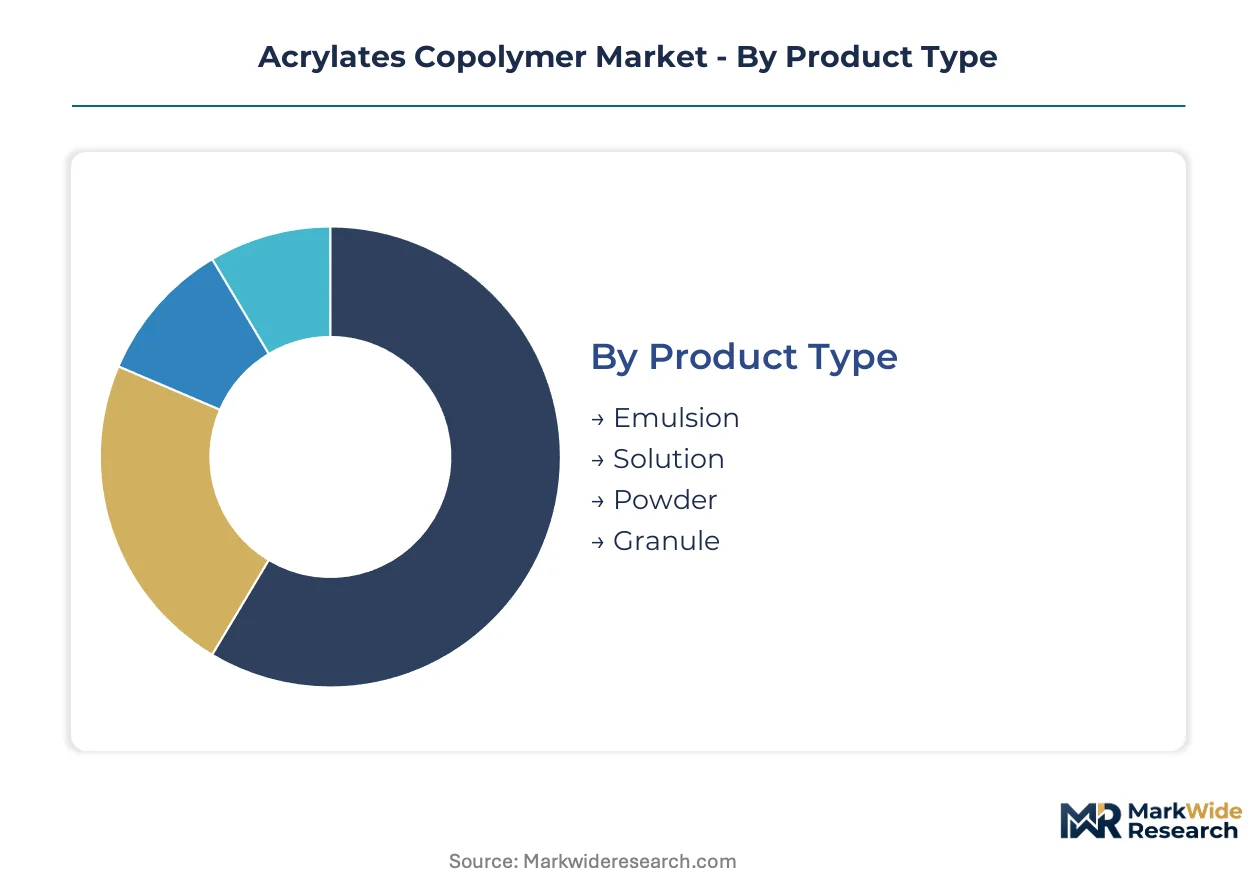
Acrylates copolymer specifications diverge sharply across waterborne emulsions, solvent solutions, and solid formats. Each product category carries distinct logistics economics and regulatory qualification pathways that determine competitive positioning.
Product Type:
Volume concentration sits with commodity waterborne grades, while premium capture concentrates in specialty solids for automated handling systems.
- Emulsion:Waterborne polymerization yields 40-60% solids dispersions optimized for architectural coatings and personal care film formers. Formulators in China and Germany specify these grades for low-VOC compliance under EPA and REACH thresholds.
- Solution:Solvent-borne systems carry 10-30% polymer content with precise molecular weight control for pressure-sensitive adhesives. EPA VOC restrictions in the United States compress demand growth, redirecting investment toward hybrid waterborne alternatives.
- Powder:Spray-dried particles enable automated dry-mix mortar systems where liquid logistics constrain adoption. Construction chemical producers in India specify powder grades for PLI scheme-eligible specialty chemical manufacturing.
- Granule:Agglomerated solid formats serve textile sizing operations requiring dust-free handling. Premium positioning reflects energy-intensive production and narrow specification tolerances for filament yarn processing.
Mature deployment sits with Emulsion grades across coatings and personal care. Newer deployment is concentrated in Powder formats for construction automation.
End User:
Application-driven specification complexity separates commodity coatings demand from high-margin personal care qualification requirements.
- Personal Care:Film-forming polymers for hair styling and sun care demand sub-100 ppm residual monomer thresholds. FDA cosmetic ingredient reviews in the United States and CDSCO registration pathways in India extend qualification timelines to 18-24 months.
- Paints:Architectural and industrial coatings consume volume emulsion grades with tunable glass transition temperatures for climate-specific flexibility. Chinese domestic production expansion concentrates manufacturing pull for both imported and local supply.
- Adhesives:Pressure-sensitive and structural bonding applications specify tackified copolymers with controlled peel adhesion. Silicone-urethane hybrid substitution threatens acrylates share where temperature resistance specifications tighten.
- Coatings:Protective and automotive topcoat formulations leverage acrylates for UV resistance and gloss retention. REACH authorization list expansion for acrylic acid ester monomers redirects qualification toward pre-registered polymer grades.
Volume leadership rests with Paints. Steepest expansion trajectory belongs to Personal Care as formulators specify humidity-resistant film formers.
Application:
Regulatory exposure varies dramatically between leave-on cosmetic products and industrial construction systems.
- Cosmetics:Skin and hair care formulations demand high-clarity films with sensory neutrality. South Korean and Japanese formulators specify hybrid acrylates-silicone architectures for wash-off durability without silicone-heavy aesthetics.
- Sealants:Construction and automotive joint sealing requires elastomeric recovery after compression set. Bulk polymerization serves these applications where residual solvent thresholds are less stringent than cosmetic grades.
- Textiles:Warp sizing and fabric finishing operations utilize granule and powder formats for dust-controlled handling. Energy-intensive drying steps favor solid polymer logistics over liquid emulsion transport.
- Construction:Cement modification and waterproofing membranes specify redispersible powders for dry-mix mortar systems. Automated batching compatibility opens industrial volume channels previously blocked by liquid handling constraints.
Established penetration characterizes Construction applications. Emerging qualification activity concentrates in Cosmetics as hybrid polymer architectures unify formulation steps.
Technology:
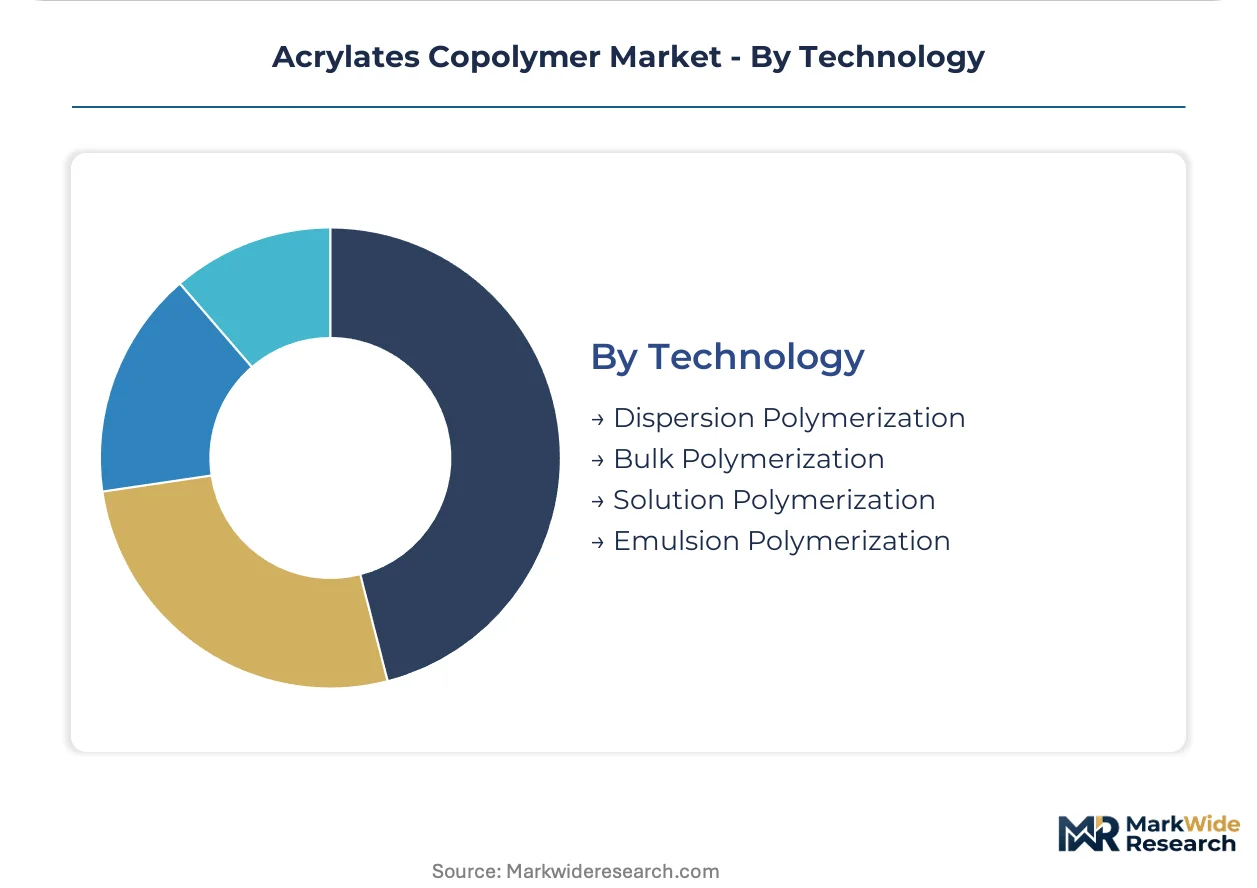
Process chemistry expertise scarcity constrains capacity expansion outside established technology licensees.
- Dispersion Polymerization:Advanced control over particle size distribution yields high-clarity cosmetic films with sub-50 nanometer primary particle dimensions. Arkema anchors proprietary positioning through this route for premium personal care supply.
- Bulk Polymerization:Solvent-free bulk processes serve medical and optical applications demanding sub-10 ppm residual monomer thresholds. High-purity grades command significant premiums over emulsion alternatives.
- Solution Polymerization:Homogeneous reaction media enable precise molecular weight targeting for adhesive tack optimization. EPA VOC emission restrictions in the United States compress legacy capacity economics for solvent-borne routes.
- Emulsion Polymerization:Waterborne heterogeneous systems dominate production economics for coatings and personal care. Reactive surfactant-free innovations compress residual monomer thresholds while enabling direct cosmetic-grade qualification.
Production scale concentrates with Emulsion Polymerization. Technology licensing premiums attach to Dispersion Polymerization for specialty-grade supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene oxidation capacity along the US Gulf Coast and acrylic acid clusters in Germany's Rhineland anchor upstream supply for acrylates copolymer production. Downstream demand concentrates in personal care formulators across South Korea and construction chemical producers in India.
United States
Hair styling and sunscreen formulators in New Jersey and California drive specialty-grade acrylates copolymer consumption for humidity-resistant films. EPA VOC emission thresholds in architectural coatings redirect procurement toward low-emulsion alternatives. Houston-Galveston petrochemical corridors sustain integrated acrylic acid backbones for domestic copolymer production.
Germany
High-clarity cosmetic film demand from Frankfurt and Düsseldorf personal care clusters pulls advanced dispersion polymerization supply. ECHA REACH authorization list expansion for acrylic acid ester monomers elevates compliance costs for non-registered imports. Ludwigshafen chemical parks anchor emulsion polymerization capacity with established substance dossiers.
China
Domestic architectural coatings expansion in Shanghai and Guangzhou concentrates manufacturing pull for both imported and local acrylates copolymer supply. MEE enforcement of dual carbon goals tightens emissions standards at acrylic acid oxidation units. Yangtze River Delta petrochemical corridors recalibrate capacity toward specialty-grade personal care and coatings demand.
India
CDSCO cosmetic ingredient registration pathways attract multinational formulator investments in Maharashtra and Gujarat. PLI scheme incentives for specialty chemicals accelerate local acrylates copolymer qualification for hair care and sun care applications. Mumbai-Pune industrial belts host contract manufacturers establishing automated dry-mix mortar systems for powder-grade adoption.
South Korea
Hybrid acrylates-silicone copolymer architectures from Seoul and Incheon formulators unify film flexibility and water resistance in premium hair care. MFDS cosmetic safety reviews scrutinize residual monomer thresholds in leave-on products. Gyeonggi-do chemical parks specialize in sub-50 nanometer particle dispersion for high-clarity cosmetic films.
Acrylates Copolymer Market Vendor Landscape
Global majors compete with regional champions across polymerization technology licensing and feedstock integration depth. The vendor base stratifies between integrated petrochemical conglomerates with captive acrylic acid supply and specialty compounders focused on cosmetic-grade qualification. Three archetypes dominate: backward-integrated resin producers, advanced dispersion technology licensors, and regional emulsion specialists serving construction markets. Capacity expansion and strategic technology licensing represent the dominant competitive moves as producers defend margin structures against propylene volatility.
Within the integrated petrochemical tier, BASF SE and The Dow Chemical Company exemplify scale-driven positioning through Rhineland and US Gulf Coast acrylic acid backbones. Arkema occupies a specialist position representing advanced dispersion polymerization capabilities for premium personal care supply. These three anchors demonstrate how technology control and feedstock integration separate tier-one positioning from regional compounders competing on formulation service proximity.
| Leading Market Players |
|---|
| Celanese Corporation |
| ACURO ORGANICS LIMITED |
| Arkema |
| OMNOVA Solutions Inc. |
| Archroma |
| BASF SE |
| The Lubrizol Corporation |
| H.B. Fuller Company |
| The Dow Chemical Company |
| Others |
Supply Flow & Price Mechanics
REACH residual monomer limits and EPA VOC thresholds gate qualified supply access and premium-tier pricing power, concentrating margin capture with producers possessing established substance dossiers and integrated acrylic acid backbones. Buyers without qualified supplier relationships face extended qualification timelines and elevated procurement costs for cosmetic-grade and low-emission formulations.
Pricing Analysis
Technical service bundling separates premium-tier producers from commodity competitors, with on-site dispersion optimization and formulation support included for high-volume coatings accounts while personal care buyers pay separately for cosmetic-grade certification documentation. Pricing stratifies across premium, standard, and economy tiers based on residual monomer thresholds and dispersion clarity grades. Cost compression in commodity emulsion grades is intensifying because Chinese domestic capacity expansion is flooding regional markets with unqualified supply. Construction chemical producers in India exhibit highest price sensitivity due to PLI scheme margin requirements, while South Korean cosmetic formulators tolerate premium positioning for hybrid acrylates-silicone architectures.
Supply Chain Analysis
Single-source vulnerability sits with advanced dispersion polymerization technology holders in Western Europe and select Northeast Asian facilities, where sub-50 nanometer particle production for high-clarity cosmetic films concentrates qualified supply. Acrylic acid feedstock draws from propylene oxidation capacity along the US Gulf Coast and Germany's Rhineland, with comonomer methacrylates and styrene sourcing from integrated petrochemical complexes in China and South Korea. Tariff exposure on specialty-grade imports into India threatens margin structures for multinational formulators establishing local qualification. Distribution runs through direct technical service models in North American architectural coatings, bypassing traditional distributor channels for large Ohio and Texas formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reactive surfactant-free emulsion polymerization is displacing legacy solvent-borne solution processes, compressing residual monomer thresholds while enabling direct cosmetic-grade qualification without post-polymer purification overhead.
For Market Incumbents: Acquire fermentation-derived 3-hydroxypropionic acid routes to biobased acrylic acid, securing carbon accounting advantages as sustainability-positioned brands tighten procurement criteria. Defend margin position by expanding captive dispersion polymerization capacity in Gyeonggi-do chemical corridors, countering silicone-urethane hybrid substitution threats in pressure-sensitive adhesive specifications. Lock long-term supply agreements with CDSCO-registered contract manufacturers in Maharashtra before multinational formulators complete local qualification investments. For New Entrants and Emerging Players: Capture automated dry-mix construction volume in Mumbai-Pune industrial belts, where powder-grade logistics advantages remain underexploited by liquid-emulsion incumbents. Target CDSCO cosmetic ingredient registration pathways for hair care and sun care applications, exploiting 18-24 month FDA review timelines that delay incumbent formulation locks. Lead with technical service proximity to Ohio and Texas coatings clusters, mirroring direct-to-brand models that are displacing distributor-led specification support. For Investors and Strategic Acquirers: ECHA REACH authorization list expansion for acrylic acid ester monomers is the leading indicator that qualified-supplier premiums will widen for pre-registered polymer grades with demonstrated residual control. The 5-10 year viability window favors acquisition of advanced dispersion technology licensors with established MFDS cosmetic safety review dossiers, rather than commodity emulsion capacity exposed to propylene cycle volatility. Watch for accelerated supplier audits by German and French personal care contract manufacturers ahead of 2027 review cycles as the inflection signal for qualification-driven supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biobased Acrylic Acid | Fermentation-derived 3-hydroxypropionic acid routes enable carbon accounting advantages for sustainability-positioned brand procurement. |
| Advanced Dispersion Polymerization Licensing | Sub-50 nanometer particle control secures premium positioning in South Korean and Japanese high-clarity cosmetic film demand. |
| CDSCO Cosmetic Ingredient Registration | Early qualification investments in Maharashtra and Gujarat capture multinational formulator localization before competitor dossier completion. |
| Direct Technical Service Laboratory Expansion | On-site dispersion optimization in Ohio and Texas coatings clusters bypasses distributor channels for volume concentration. |
| Powder Format Capacity Addition | Spray-dried particle production serves PLI scheme-eligible specialty chemical manufacturing in Indian automated dry-mix construction systems. |
Methodological Framework
Independent corroboration across plant managers at emulsion polymerization facilities, procurement leads at downstream coatings OEMs, and technical R&D directors at personal care formulators underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of disclosed acrylates producers, and ECHA REACH substance dossier databases. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across the analysis window.
Historical reference periods spanning pre- and post-REACH authorization list expansion anchor the forecast window, with projection horizons extending through regulatory review cycles and technology transition phases. Segmentation dimensions include product format (emulsion, solution, powder, granule), end-use industry (personal care, paints, adhesives, coatings), application (cosmetics, sealants, textiles, construction), and polymerization technology (dispersion, bulk, solution, emulsion). CAGRs derive from fitted growth curves calibrated to acrylic acid feedstock cost trajectories and regional coatings production indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to propylene oxidation economics, ECHA authorization list expansion timing, and MFDS cosmetic safety review precedent. Forecasts reflect assumptions about regulatory enforcement continuity, technology licensing availability, and substitution elasticity in pressure-sensitive adhesive specifications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
India Adhesives Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Brazil Adhesives Market