
 Brazil Sealants Market | 2026-2036
Brazil Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Sealants Market Outlook
Aftermarket technical service revenue is narrowing as Brazilian contractors shift toward specification-grade product procurement with embedded application support. Dow leverages its silicone manufacturing presence to anchor premium architectural project supply. Sika AG competes through specialized polyurethane systems for Brazil's commercial building envelope sector. Henkel AG & Co. KGaA sustains distributor loyalty via contractor training programs and localized technical centers.
Sealants are elastomeric compounds formulated with polymers such as silicone, polyurethane, acrylic, or butyl, designed to fill gaps and prevent fluid or air passage while accommodating joint movement of 25% to 50% of original width. These materials cure through moisture reaction, solvent evaporation, or UV initiation to form flexible, durable bonds in structural and non-structural assemblies. Silicone formulations dominate Brazil's façade and glazing segments due to superior weathering resistance and temperature cycling performance. Polyurethane captures growth in automotive and industrial bonding where adhesion to porous substrates and paint compatibility matter. Acrylic serves cost-sensitive construction repair and DIY channels with faster skin-over times and water cleanup.
ANVISA regulates chemical substance registration and labeling requirements for sealant formulations sold in Brazil, while the Brazilian Association of Technical Standards (ABNT) governs performance classification through NBR standards for construction adhesives and sealants. The National Environment Council (CONAMA) resolutions on volatile organic compound emissions increasingly restrict solvent-based products in populated zones. Stakeholders must monitor regulatory convergence between Brazilian state environmental agencies and federal chemical policy to anticipate reformulation timelines and certification costs.
Market Dynamics
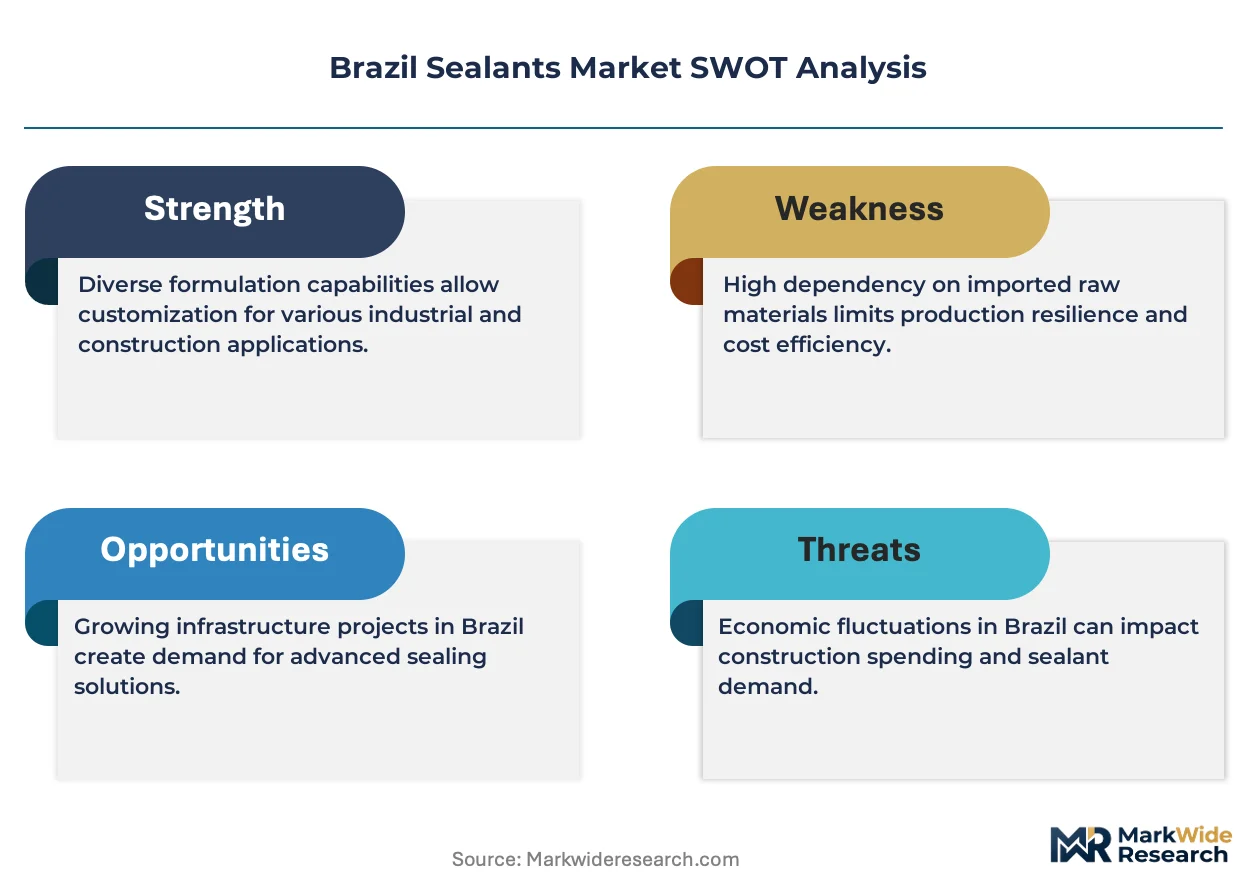
ANVISA's escalating enforcement of low-VOC formulation mandates is compressing solvent-based product margins and forcing manufacturers to reallocate R&D spending toward water-borne and hybrid polymer systems. This regulatory pivot is the dominant structural force reshaping competitive positioning across Brazil's construction and industrial sealant segments.
Growth Catalysts
- São Paulo State Infrastructure Rehabilitation:Federal PAC investment programs are accelerating bridge, tunnel, and commercial façade restoration projects. Specification-grade silicone and polyurethane systems are capturing procurement volume in these public tenders.
- CONAMA Resolution 491:This federal emission standard restricts solvent-based sealants in metropolitan zones. Manufacturers reformulating toward silyl-modified polymers are securing preferential placement in green building certification pathways.
- Silyl-Modified Polymer (SMP) Technology:Hybrid systems combining silicone weathering with polyurethane adhesion are penetrating Brazil's industrial maintenance segment. These formulations reduce primer requirements and accelerate cure cycles in high-humidity conditions.
Market Restraints
- Silicone Monomer Import Dependency:Brazil lacks domestic silicone feedstock production. D4 and D5 cyclic siloxane supply concentrates in Chinese and German chemical clusters, exposing formulators to freight cost volatility and currency fluctuation risk.
- ABNT NBR 13786 Certification Timeline:Construction sealant performance validation requires 180-day weathering tests at INMETRO-accredited laboratories. This procedural friction delays new product commercialization and locks working capital in inventory.
- Acrylic Water-Based Substitution Ceiling:Interior-grade acrylic sealants face displacement from hybrid polymer systems in premium residential applications. Price-sensitive DIY channels retain acrylic volume, but margin compression limits manufacturer investment in these SKUs.
Strategic Opportunities
- Northeast Brazil Industrial Corridor:Pernambuco and Ceará states are attracting automotive assembly and wind energy manufacturing. Polyurethane structural bonding applications in blade fabrication and vehicle panel assembly remain underpenetrated by established Southeast suppliers.
- Embedded Application Support Contracts:Brazilian contractors are consolidating vendor relationships around suppliers offering on-site technical training and joint specification development. Distributor networks that integrate applicator certification programs capture sticky procurement relationships.
- Biobased Polyol Feedstocks:Castor oil-derived polyurethane precursors from Brazil's Northeast agricultural belt offer carbon intensity advantages for export-oriented customers. ANVISA's accelerated registration pathway for biogenic content formulations creates regulatory tailwind for domestic producers.
Industry Challenges
- Polymer Chemist Talent Scarcity:Formulation expertise in moisture-cure silicone and two-component polyurethane systems concentrates in São Paulo's ABC industrial region. Manufacturers expanding to secondary states face recruitment friction and compensation inflation for specialized technical staff.
- Legacy Solvent-Based Inventory Stranding:Distributors holding pre-2023 toluene-based sealant stocks confront CONAMA enforcement in Rio de Janeiro and Belo Horizonte metropolitan areas. Write-down risk concentrates in regional distributor networks with limited technical service capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Sealants Market |
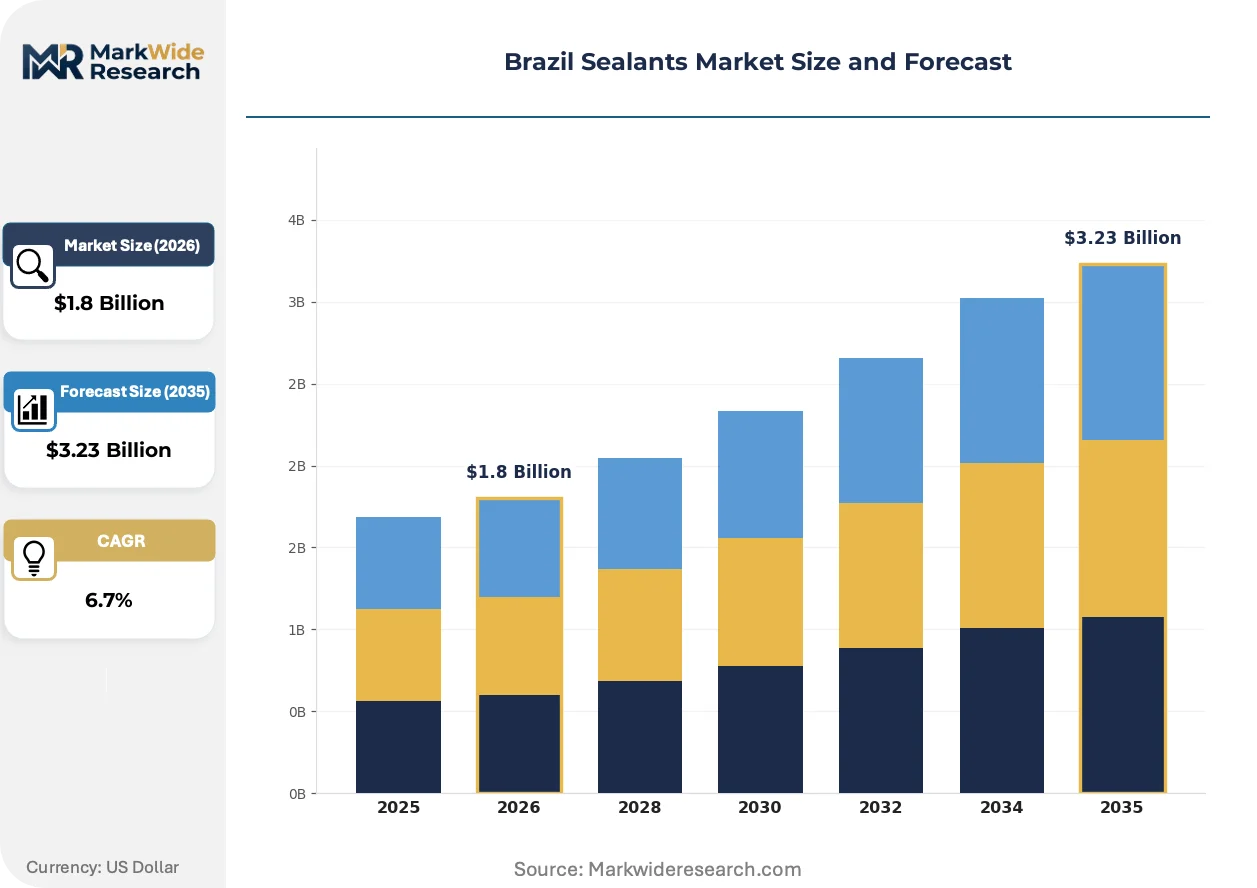
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylic, Butyl Application: Construction, Automotive, Aerospace, Electronics End User: Manufacturers, Contractors, DIY Consumers, Distributors Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | 3M, Dow, Sika AG, Arkema, Saint-Gobain, Henkel AG & Co. KGaA, Bostik, Wacker Chemie AG, H.B. Fuller Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Sealants Market Strategic Shifts
Formulation chemistry is pivoting toward hybrid systems that merge performance attributes previously siloed in single-polymer categories. This convergence is compressing traditional product segmentation and forcing manufacturers to reposition around application-specific value rather than material-type branding.
Moisture-cure silyl-terminated polyurethane (STP) technology is migrating from European industrial maintenance applications into Brazil's commercial building envelope sector. São Paulo-based façade contractors are specifying STP systems for movement joints exceeding 35% expansion capacity. These hybrid formulations are enabling single-product stocking strategies that reduce distributor SKU complexity and inventory carrying costs.
ANVISA's alignment with OECD chemical hazard classification standards is accelerating GHS label revision requirements for imported sealant formulations. Industrial distributors must now maintain dual-language safety data sheets with expanded exposure limit disclosures. Construction procurement teams in Rio de Janeiro's public housing programs are prioritizing suppliers with completed ANVISA registration renewals, creating competitive sorting based on compliance velocity rather than price.
Brazilian contractors are consolidating annual sealant procurement around specification-grade bundles that embed applicator training and warranty support. Regional distributors relying on transactional product sales are losing share to manufacturer-direct technical service models. This pattern concentrates in São Paulo state's high-rise residential segment, where developer risk transfer requirements favor suppliers assuming installation performance liability.
Brazil Sealants Market Segmentation
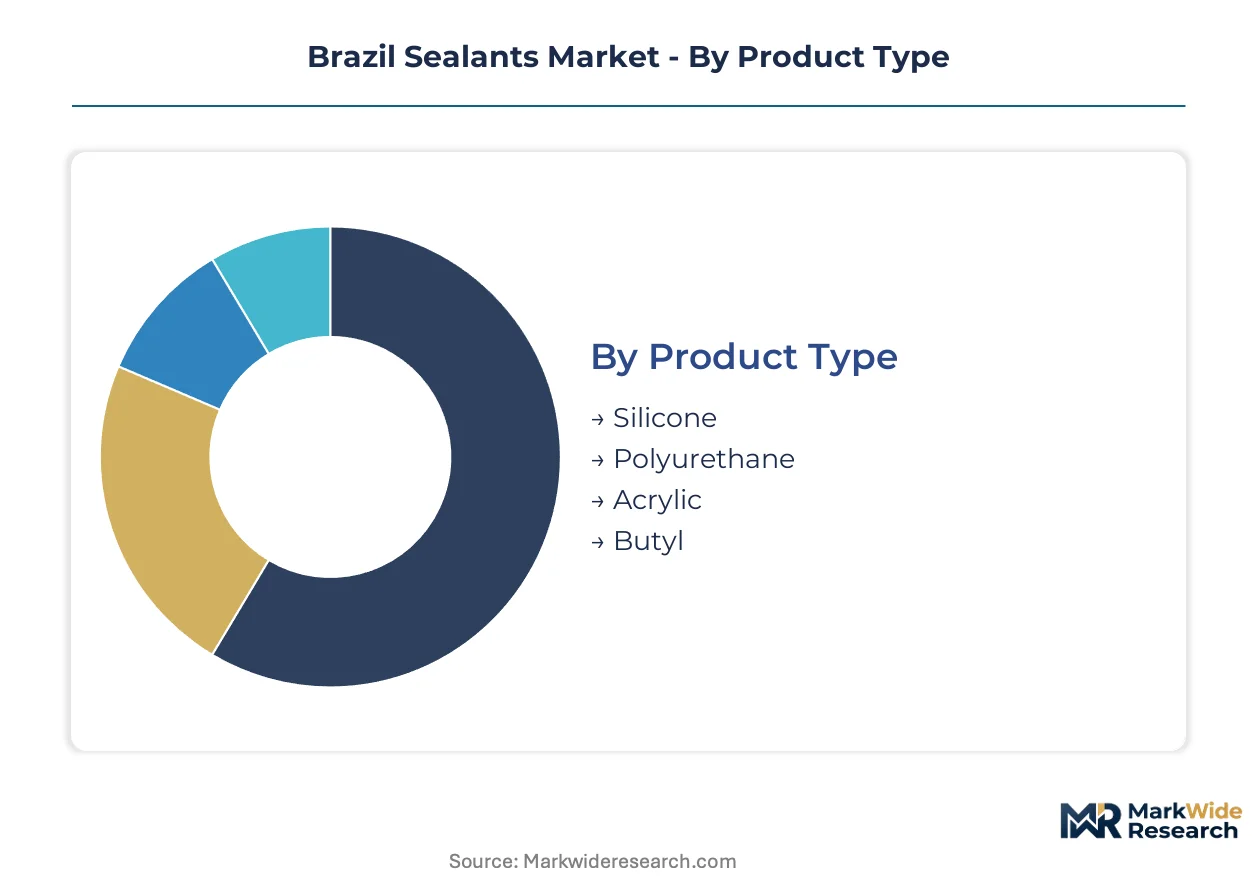
Segmentation in Brazil's sealants market reveals how technical service intensity varies dramatically across polymer chemistry and procurement channels. Manufacturers must align formulation portfolios with the support expectations embedded in each segment's buying behavior.
Product Type:
After-sales technical service intensity escalates from commodity acrylics through specification-grade silicones, with hybrid systems demanding the most embedded application engineering.
- Silicone:Formulated from silanol-terminated polydimethylsiloxane polymers with tin or oxime cure chemistry. São Paulo's high-rise glazing contractors specify neutral-cure architectural grades for movement joints exceeding 50% expansion; Dow and Wacker maintain on-site technical teams for these projects. ANVISA's D4/D5 cyclic siloxane registration requirements add compliance service layers to every sale.
- Polyurethane:Two-component systems based on isocyanate-terminated prepolymers and polyol curatives deliver structural bonding strength above 6 MPa. Automotive assembly plants in São Bernardo do Campo require viscosity-matched dispensing support and cure-cycle optimization, locking suppliers into long-term technical service contracts.
- Acrylic:Water-based emulsions of polyacrylic esters serve cost-sensitive interior sealing with faster skin-over times. DIY channels in Rio de Janeiro's retail hardware stores move volume with minimal technical intervention.
- Butyl:Preformed tapes and hot-melt formulations from isobutylene-isoprene copolymers provide vapor-barrier sealing in building envelopes. Industrial distributors stock standard dimensions with specification sheets substituting for direct service.
Silicone holds the largest share; momentum sits with polyurethane as automotive and wind energy applications expand.
Application:
Construction procurement concentrates in specification-grade bundles with embedded warranty support, while industrial applications fragment across performance tiers with varying service intensity.
- Construction:Façade glazing, expansion joints, and waterproofing membranes dominate volume. Federal PAC infrastructure tenders in Rio de Janeiro require suppliers to assume installation performance liability, forcing manufacturers to deploy certified applicator networks.
- Automotive:Direct glazing, panel bonding, and seam sealing applications in São Paulo state's assembly plants demand viscosity-matched dispensing systems and just-in-time technical support. Henkel and Sika compete through embedded production-line engineering services.
- Aerospace:Fuel tank sealing and cabin pressure boundary applications require AS9100-certified manufacturing and specialized cure-cycle documentation. Maintenance repair organizations in São José dos Campos source through distributor technical specialists.
- Electronics:Potting compounds and thermal interface materials for consumer device assembly in Manaus Free Trade Zone move through component distributors with datasheet-driven procurement and minimal field service.
Construction commands the dominant revenue position; electronics is expanding most quickly as Brazil's consumer device assembly scales.
End User:
Procurement authority is consolidating around technically sophisticated buyers who bundle specification development with volume commitments.
- Manufacturers:Automotive OEMs and wind blade fabricators in Pernambuco negotiate multi-year supply agreements with embedded formulation customization and on-site laboratory support. These relationships lock out transactional competitors.
- Contractors:São Paulo's façade specialists and Rio de Janeiro's infrastructure rehabilitation firms consolidate annual procurement around suppliers offering joint specification development and applicator certification programs.
- DIY Consumers:Price-sensitive homeowners in Belo Horizonte and Curitiba purchase through retail hardware channels with minimal technical guidance, driving margin compression in standard-grade acrylics.
- Distributors:Regional industrial distributors in the Northeast corridor are losing share to manufacturer-direct technical service models, particularly in specification-grade construction segments.
Contractors represent the highest-margin customer type; manufacturers are gaining procurement influence fastest as long-term supply agreements proliferate.
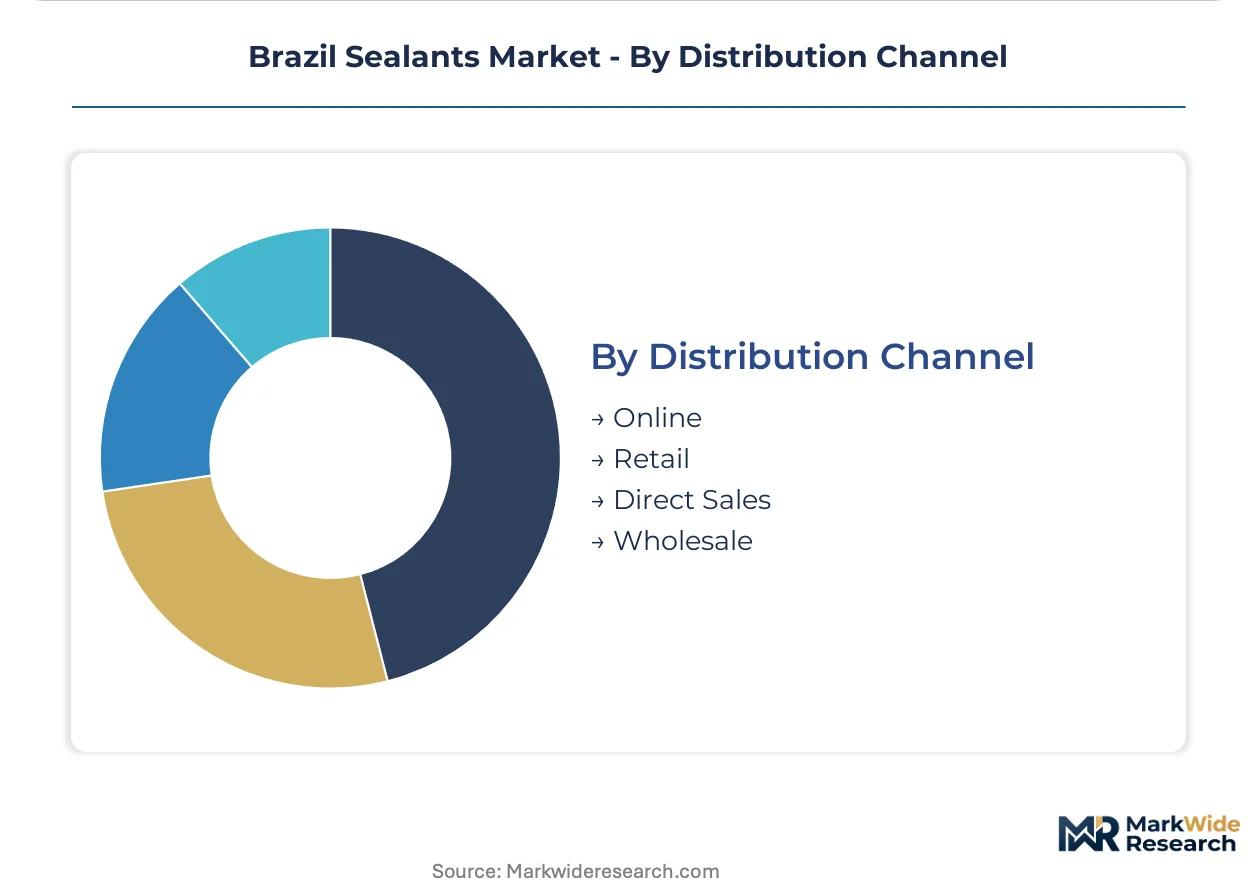
Distribution Channel:
Channel selection directly determines the technical service intensity manufacturers must embed, with direct sales requiring the deepest application engineering capabilities.
- Direct Sales:Dow and Sika deploy technical service engineers to major construction and automotive accounts for joint specification development and installation supervision. These relationships carry the highest customer lifetime value but demand specialized polymer chemistry talent concentrated in São Paulo's ABC industrial region.
- Wholesale:Industrial distributors serving Brazil's Northeast automotive corridor maintain inventory buffers and basic technical documentation, though they lack the formulation expertise for complex specification support.
- Retail:Home improvement chains in Southeast Brazil move standard-grade acrylics and silicone sealants through self-service displays with minimal staff technical knowledge.
- Online:E-commerce platforms are penetrating DIY and small-contractor segments with datasheet-driven procurement, though specification-grade construction applications resist digital migration due to liability and warranty complexity.
Direct sales captures the premium specification tier; online channels are climbing the fastest as digital procurement tools penetrate smaller contractor segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil's Northeast industrial corridor exhibit acute price sensitivity on standard-grade formulations, while São Paulo's specification-grade procurement shows inelastic demand for embedded technical service. This elasticity divergence shapes regional competitive positioning.
São Paulo
Federal PAC infrastructure tenders accelerate bridge and commercial façade restoration projects across the state. ANVISA's low-VOC formulation mandates redirect manufacturer R&D spending toward water-borne systems. The ABC industrial region concentrates polymer chemist talent for moisture-cure silicone and two-component polyurethane formulation.
Rio de Janeiro
Public housing programs and tunnel rehabilitation projects drive specification-grade silicone and polyurethane procurement. CONAMA Resolution 491 restricts solvent-based sealants in metropolitan zones, forcing distributor inventory write-downs. The state's infrastructure rehabilitation firms consolidate annual procurement around suppliers offering joint specification development.
Minas Gerais
Belo Horizonte's retail hardware channels move cost-sensitive acrylic sealant volume with minimal technical guidance. State environmental agencies align with federal chemical policy on VOC enforcement. DIY consumers in Curitiba-facing trade zones drive margin compression in standard-grade product categories.
Pernambuco
Automotive assembly and wind energy manufacturing attract polyurethane structural bonding applications in blade fabrication. ANVISA's accelerated registration pathway for biogenic content formulations creates regulatory tailwind for castor oil-derived polyol producers. The Recife industrial corridor remains underpenetrated by established Southeast suppliers.
Ceará
Wind blade fabricators negotiate multi-year supply agreements with embedded formulation customization requirements. State environmental councils implement CONAMA-aligned emission standards in metropolitan Fortaleza. The Pecém industrial complex anchors demand for high-performance bonding systems in renewable energy manufacturing.
Brazil Sealants Market Competitive Environment
Capability concentration sits with specialized polymer formulators; scale advantage sits with diversified chemical conglomerates. The market structures around three tiers: multinational integrated suppliers with captive silicone feedstock, European specialty chemical houses with polyurethane expertise, and regional distributors with logistics reach but limited technical service depth. Dominant competitive moves include embedded application support contracts and biobased formulation registration acceleration.
Among multinational integrated suppliers, Dow and Sika AG occupy positions that exemplify divergent strategic archetypes. Dow anchors premium architectural project supply through silicone manufacturing presence. Sika AG exemplifies the specialty polyurethane systems approach for commercial building envelope applications. Henkel AG & Co. KGaA represents the distributor-loyalty model via contractor training infrastructure.
| Leading Market Players |
|---|
| 3M |
| Dow |
| Sika AG |
| Arkema |
| Saint-Gobain |
| Henkel AG & Co. KGaA |
| Bostik |
| Wacker Chemie AG |
| H.B. Fuller Company |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Brazil's acrylic water-based sealant segment compresses margins for commodity-grade producers while simultaneously freeing working capital for specification-grade silicone and polyurethane investments. This utilization asymmetry rewards manufacturers with captive technical service capabilities and punishes distributors holding undifferentiated inventory.
Pricing Analysis
Embedded application support contracts now drive lifetime value more than per-unit transactional pricing. Three-tier pricing structure across premium specification-grade, standard industrial-grade, and economy DIY levels separates Dow's architectural silicone bundles from regional acrylic suppliers. Cost compression in economy acrylic channels intensifies because DIY consumers in Belo Horizonte and Curitiba trade down to private-label alternatives. Specification-grade buyers in São Paulo's high-rise glazing segment exhibit the lowest price sensitivity, prioritizing installation performance liability transfer over unit cost.
Supply Chain Analysis
Tariff exposure between China and Brazil dominates raw material cost volatility for silicone monomer imports. D4 and D5 cyclic siloxane supply concentrates in Chinese and German chemical clusters, exposing Brazilian formulators to freight cost fluctuations and currency risk. The market rests on castor oil-derived polyol feedstocks from Pernambuco's agricultural belt for biobased polyurethane precursors. Distribution runs through manufacturer-direct technical service models for specification-grade construction segments, while wholesale distributors retain economy acrylic volume in retail hardware channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's sealants market sits in early-cycle expansion as silyl-modified polymer technology penetrates industrial maintenance applications previously served by single-polymer systems. ANVISA's accelerated registration pathway for biogenic content formulations creates additional tailwind for domestic producers with Northeast agricultural supply chain access.
For Market Incumbents: Pre-empt hybrid polymer displacement by consolidating applicator certification networks before regional distributors develop comparable technical service depth. Dow and Sika should anchor São Paulo's ABC industrial region talent pools through specialized compensation structures, as polymer chemist scarcity in secondary states threatens expansion timelines. Backward integration into castor oil polyol processing in Pernambuco defends margin position against Southeast feedstock cost volatility. For New Entrants and Emerging Players: Mid-market wind blade fabricators in Ceará's Pecém industrial complex represent the most penetrable entry point, as established Southeast suppliers lack embedded formulation customization relationships. Automotive assembly plants in Pernambuco negotiating multi-year supply agreements seek viscosity-matched dispensing support that transactional competitors cannot replicate. A go-to-market angle through ANVISA biogenic registration acceleration differentiates against import-dependent incumbents facing D4/D5 compliance friction. For Investors and Strategic Acquirers: Long-term, this sits as a capability consolidation play because specification-grade procurement is concentrating around technically sophisticated suppliers with captive polymer chemistry talent. Acquisition targets should display embedded application support contracts with São Paulo façade contractors or Rio de Janeiro infrastructure rehabilitation firms. The signal to watch is distributor inventory write-down velocity in metropolitan zones enforcing CONAMA Resolution 491, which indicates compliance velocity sorting among competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Oil Polyol Processing | Pernambuco agricultural belt access reduces carbon intensity for export-oriented polyurethane customers. |
| Embedded Applicator Certification Programs | São Paulo high-rise glazing contractors consolidate procurement around suppliers assuming installation liability. |
| ANVISA Biogenic Content Registration Acceleration | Castor oil-derived formulations secure preferential pathway against import-dependent silicone competitors. |
| Silyl-Modified Polymer R&D Capacity Expansion | Hybrid systems penetrate industrial maintenance segments with reduced primer requirements. |
| Joint Specification Development Contracts | Rio de Janeiro infrastructure rehabilitation firms bundle annual procurement with technical service partners. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polymer chemists at São Paulo ABC industrial region formulators, procurement leads at Pernambuco automotive assembly plants, façade contractors in Rio de Janeiro infrastructure rehabilitation, and distribution channel partners in Northeast Brazil. Secondary validation drew from ANVISA chemical registration databases, ABNT NBR standard certification records, CONAMA resolution enforcement disclosures, and customs trade data on D4/D5 cyclic siloxane imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Calibration against historical volume and value progression anchored projections across the analysis window. Segmentation dimensions modeled include polymer chemistry tier, application performance requirement, end-user procurement sophistication, and regional regulatory enforcement intensity. CAGRs derived from elasticity-adjusted demand curves incorporating silyl-modified polymer substitution rates and biobased formulation adoption patterns. Industry-specific forecast inputs captured ANVISA registration timeline friction and INMETRO laboratory capacity constraints.
Practitioners should monitor CONAMA state-level enforcement variance and silicone monomer freight cost volatility for early signals of margin compression or inventory stranding risk. Forecasts reflect assumptions about hybrid polymer technology migration rates and biogenic registration pathway efficiency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
2K Epoxy Adhesives Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Europe Waterborne Adhesives Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
Flexible Packaging Adhesive Market