
 South America Construction Adhesives Market | 2026-2036
South America Construction Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Construction Adhesives Market Analytics
Application-specific technical support and on-site bonding audits is broadening what adhesive suppliers monetize beyond raw material volumes. Henkel AG & Co. KGaA leverages its technical service infrastructure to anchor premium positioning across Brazilian infrastructure tenders. Sika AG dominates concrete repair applications through specialized polyurethane formulations and direct contractor relationships. BASF SE extends its reach via distributor networks that control last-mile access in secondary Argentine cities.
Construction adhesives comprise formulated polymer systems—typically polyurethane, epoxy, acrylic, or silane modified polymer bases—engineered to bond structural and non-structural building elements under load-bearing, thermal, and moisture stress conditions, with tensile shear strengths ranging from 2 MPa to 25 MPa depending on chemistry. These materials serve primarily to replace mechanical fasteners, reduce thermal bridging, and enable lightweight panelized construction across residential, commercial, and infrastructure end uses. Polyurethane adhesives lead volume due to flexibility and cure speed, while silane modified polymer segments capture margin pools through premium pricing in facade and window applications where movement accommodation exceeds 15% elongation. Epoxy systems occupy the structural repair niche, with demand concentrating in Brazil's aging bridge and highway rehabilitation programs.
ANVISA in Brazil and Argentina's national chemical regulator enforce VOC emission thresholds and occupational exposure limits that filter import eligibility and domestic formulation requirements. ABNT NBR standards and MERCOSUR technical regulations further harmonize product testing protocols across the customs union, reducing compliance fragmentation for suppliers operating in multiple member states. Stakeholders must monitor how pending updates to Chile's Supreme Decree 594 building code and Colombia's green building certification expansion reshape specification authority among architects and project financiers.
Market Dynamics
ABNT NBR sustainability standards in Brazil are redirecting procurement flows toward certified low-VOC adhesive suppliers, compressing margins for uncertified imports while rewarding domestic formulation investments. This regulatory pivot is reshaping competitive positioning across the Mercosur customs union.
Growth Catalysts
- Brazilian Infrastructure Tenders:Federal highway and bridge rehabilitation programs specify polyurethane structural bonding systems, creating pull-through demand for high-shear formulations in concrete repair applications.
- ANVISA VOC Thresholds:Emission limits on solvent-based products are filtering import eligibility, advantaging domestic producers with compliant waterborne and silane-modified polymer portfolios.
- Prefabricated Panel Installation:Lightweight construction methods across São Paulo's commercial high-rise sector are displacing mechanical fasteners with elastic bonding systems that accommodate thermal movement.
Market Restraints
- Petrochemical Input Volatility:Polyol and isocyanate feedstock costs fluctuate with international crude benchmarks, compressing formulation margins for Brazilian producers lacking backward integration into basic chemicals.
- Import Dependency for Specialty Additives:Curing agents and rheology modifiers concentrate in German and Swiss supplier networks, exposing South American blenders to currency risk and extended lead times.
- Cure Speed Limitations in Humid Climates:Epoxy systems face application windows below four hours during Rio de Janeiro's wet season, restricting their deployment in emergency infrastructure repairs.
Strategic Opportunities
- Chilean Green Building Certification Expansion:Pending updates to Supreme Decree 594 are expected to mandate low-emission materials in public-financed projects, opening specification channels for certified adhesive suppliers.
- Silane-Modified Polymer Convergence:Hybrid chemistries combining MS polymer flexibility with polyurethane strength are capturing specification authority in Argentine facade retrofit programs requiring movement accommodation above fifteen percent elongation.
- Technical Service Monetization:On-site bonding audits and application training are enabling suppliers to capture value beyond raw material volumes, particularly in Brazilian infrastructure tenders requiring contractor certification.
Industry Challenges
- Certified Applicator Shortage:ABNT-mandated installer credentials for structural bonding applications are scarce outside São Paulo and Minas Gerais, constraining project execution in Brazil's northern construction corridor.
- MERCOSUR Harmonization Delays:Divergent testing protocols between Brazilian ABNT NBR standards and Argentine IRAM specifications force dual certification investments, extending product launch timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Construction Adhesives Market |
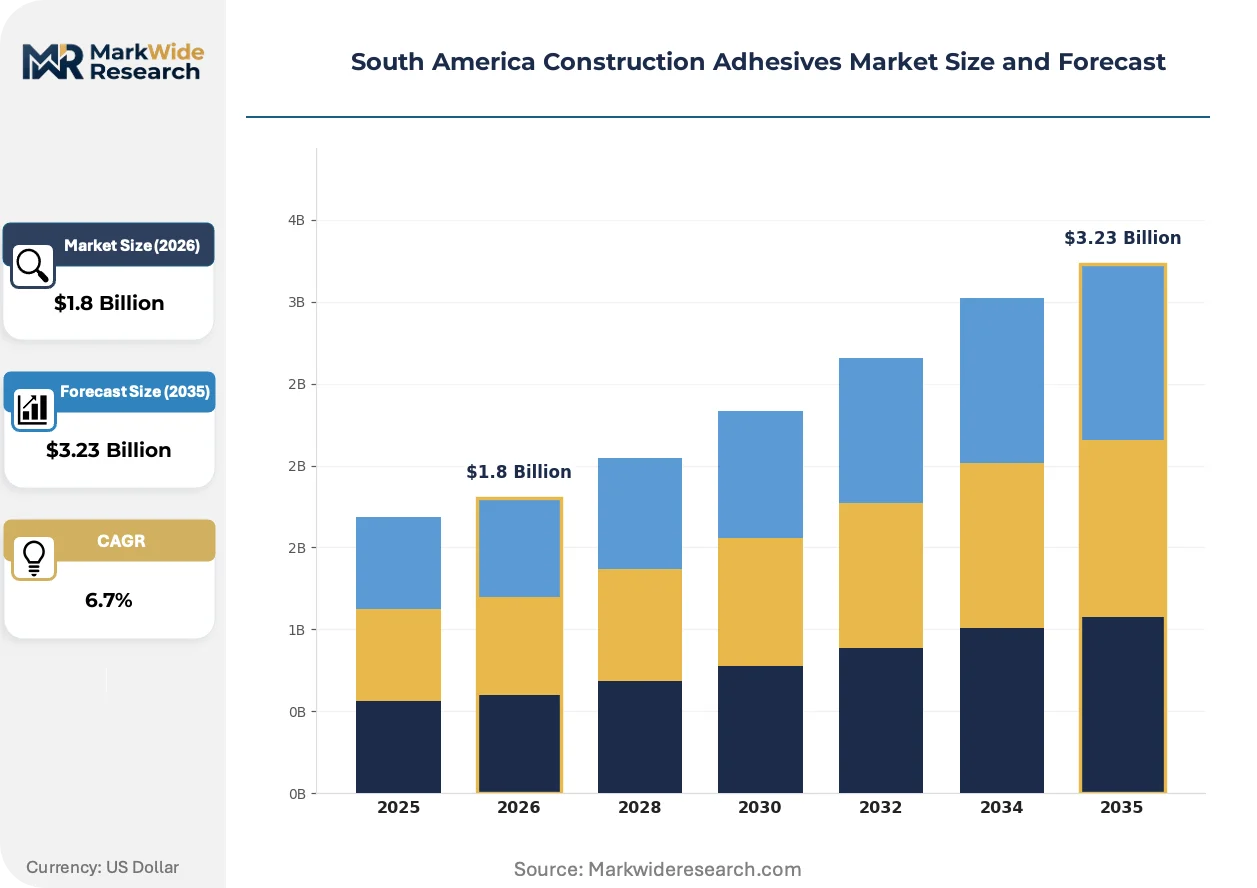
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Silane Modified Polymer End User: Residential, Commercial, Industrial, Infrastructure Application: Flooring, Walls, Roofs, Windows Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Henkel AG & Co. KGaA, Arkema Group, 3M, Huntsman International LLC, BASF SE, H.B. Fuller Company, Sika AG, MAPEI, Dow, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Construction Adhesives Market Evolving Landscape
Formulation chemistry and specification authority are converging as regulatory thresholds harden and end-users demand validated performance data. Three developments are restructuring how value is captured across the value chain.
Silane-terminated polyurethane hybrids are converging with traditional construction adhesive categories, delivering combined UV resistance and elastic recovery for Brazilian facade applications. São Paulo-based glazing contractors are specifying these systems at accelerating rates for high-rise curtain wall installations. The technology is converging with established specification workflows, displacing separate primer-and-sealant approaches in favor of single-product solutions that reduce labor hours and warranty exposure.
ANVISA's updated occupational exposure limits for isocyanate-containing products are forcing reformulation investments across Brazilian production facilities. Industrial consequence includes accelerated R&D spending on waterborne polyurethane dispersions and hot-melt reactive systems. Concrete repair contractors in Brazil's southeastern corridor are responding by pre-qualifying suppliers with demonstrated compliance documentation, narrowing tender eligibility to established domestic blenders.
Project financiers in Chile and Colombia are embedding material certification requirements directly into green bond covenants and construction loan disbursement conditions. Specification authority is migrating from contractors to financial intermediaries who demand third-party validated environmental product declarations. This pattern is most visible in Santiago's commercial real estate sector, where LEED-equivalent ratings now determine adhesive selection before architectural specification begins.
South America Construction Adhesives Market Segmentation
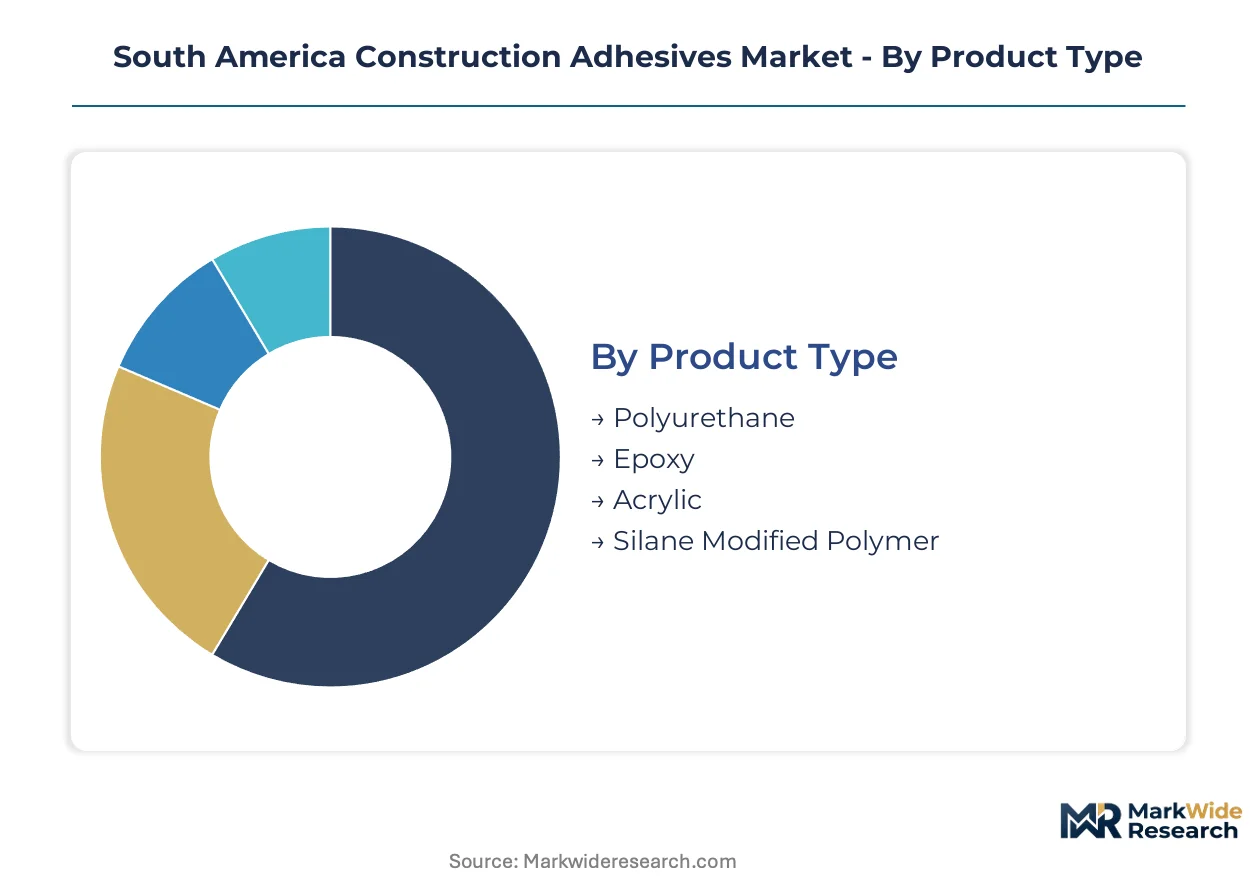
Construction adhesive procurement in South America follows distinct technical and commercial logics that vary by project scale, regulatory exposure, and supply chain access. Understanding how demand fragments across chemistry types, end-use sectors, and specification channels reveals where formulation investments and distribution partnerships generate sustainable margin capture.
Product Type:
Buyer decisions here pivot on load-bearing requirements, environmental exposure, and installer certification availability rather than unit cost alone.
- Polyurethane:These elastomeric systems cure through moisture-activated isocyanate reactions, delivering tensile shear strengths of 8-15 MPa with elongation exceeding 400%. Demand concentrates in Brazil's southeastern corridor for prefabricated panel installation, where thermal cycling resistance and rapid cure speed reduce labor hours on São Paulo high-rise sites. ANVISA's updated occupational exposure limits are forcing reformulation toward waterborne dispersions, advantaging domestic blenders with compliant production infrastructure.
- Silane Modified Polymer:Hybrid chemistry combining silyl-terminated backbone with polyurethane toughness achieves UV stability plus 15-25% movement accommodation without primers. Argentine facade retrofit programs in Buenos Aires and Córdoba specify these systems for curtain wall bonding where joint movement exceeds conventional adhesive limits. Premium positioning reflects elimination of separate primer-and-sealant steps.
- Epoxy:Two-part thermoset systems deliver structural repair performance above 20 MPa tensile shear for concrete rehabilitation.
- Acrylic:Waterborne dispersions serve interior finishing applications with lower VOC profiles and faster tack development.
Polyurethane leads on scale; silane modified polymer leads on momentum.
End User:
Volume distribution across end-use sectors tracks infrastructure spending cycles and green building certification penetration.
- Infrastructure:Federal highway and bridge rehabilitation programs in Brazil specify high-shear polyurethane systems for concrete repair, with demand concentrating in Minas Gerais state tenders. Project scale and warranty requirements favor suppliers with technical service capabilities and ABNT-certified applicator networks.
- Commercial:São Paulo's commercial high-rise sector drives specification of elastic bonding systems for lightweight panelized construction, displacing mechanical fasteners to reduce thermal bridging. LEED-equivalent ratings in Chile and Colombia increasingly determine adhesive selection before architectural specification.
- Residential:Flooring and interior finishing applications favor cost-optimized acrylic and waterborne polyurethane formulations.
- Industrial:Manufacturing facility construction demands chemical-resistant epoxy systems for containment areas and equipment anchoring.
Infrastructure commands the largest volume commitment; commercial construction exhibits the steepest specification upgrade trajectory.
Application:
Application-specific performance requirements determine chemistry selection and whether technical support services become mandatory purchase components.
- Flooring:Elastic polyurethane adhesives dominate large-format tile and engineered wood installation across Brazilian residential and commercial projects, accommodating subfloor movement while eliminating mechanical fasteners that penetrate moisture barriers.
- Windows:Silane modified polymer systems capture specification authority for high-performance glazing in Argentine and Chilean commercial retrofits, where movement accommodation and UV resistance outweigh unit cost considerations.
- Walls:Panelized construction methods favor rapid-cure polyurethane systems for interior partition bonding.
- Roofs:Membrane bonding and waterproofing applications demand weather-resistant formulations with proven tropical climate durability.
Flooring absorbs the highest absolute volume; window applications generate the most pronounced premium pricing capture.
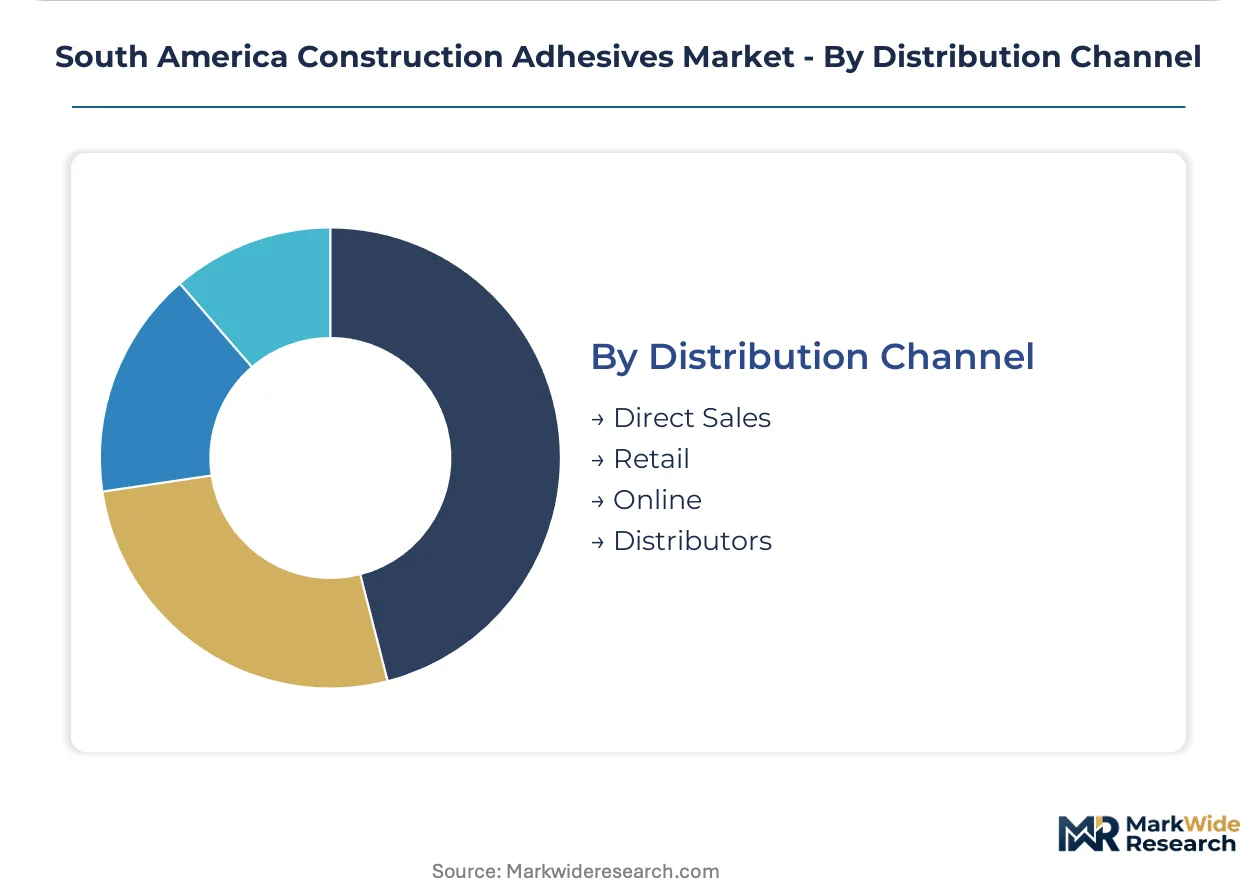
Distribution Channel:
Channel selection reflects project scale, geographic access constraints, and whether specification authority resides with contractors or financiers.
- Distributors:Networks controlling last-mile access in secondary Argentine cities and Brazil's northern construction corridor extend reach for multinational suppliers lacking direct sales infrastructure. Inventory holding and credit extension capabilities determine competitive positioning in working-capital-constrained markets.
- Direct Sales:Large-scale infrastructure tenders in Brazil require supplier-contractor relationships with embedded technical service and on-site bonding audit capabilities. Direct engagement enables pre-qualification for ABNT-mandated certification requirements.
- Retail:Hardware and construction material outlets serve residential renovation and small contractor demand in urban centers.
- Online:Digital procurement channels gain traction for standardized product categories with established specification parameters.
Distributors maintain the broadest geographic coverage; direct sales channels deliver the highest margin capture per unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands construction adhesive volumes that dwarf Argentina and Chile combined, yet regulatory momentum in Santiago and Buenos Aires is compressing specification timelines faster than in São Paulo's mature tender markets.
Brazil
Federal highway rehabilitation and prefabricated panel installation drive polyurethane consumption across the southeastern corridor. ANVISA enforces updated occupational exposure limits for isocyanate-containing products, filtering import eligibility toward compliant domestic blenders. São Paulo and Minas Gerais states concentrate demand, with contractors pre-qualifying suppliers for ABNT-certified structural bonding applications.
Argentina
Facade retrofit programs in Buenos Aires and Córdoba specify silane modified polymer systems for curtain wall bonding with movement accommodation above fifteen percent elongation. The national chemical regulator enforces VOC emission thresholds that parallel MERCOSUR technical regulations, reducing compliance fragmentation for cross-border suppliers. Secondary cities rely on distributor networks controlling last-mile access and inventory holding capabilities.
Chile
Green building certification expansion reshapes specification authority, with project financiers embedding material certification into construction loan disbursement conditions. Pending updates to Supreme Decree 594 mandate low-emission materials in public-financed projects. Santiago's commercial real estate sector leads, where LEED-equivalent ratings determine adhesive selection before architectural specification begins.
Colombia
Infrastructure spending and residential construction pull demand toward cost-optimized acrylic and waterborne polyurethane formulations. Green building certification expansion is accelerating specification upgrades in Bogotá's commercial high-rise sector. Regional distributors extend multinational reach where direct sales infrastructure remains thin.
South America Construction Adhesives Market Competitive Landscape
Top-tier vendors anchor premium infrastructure tenders, while mid-scale blenders compete on reformulation speed and regional distributor relationships. The market exhibits tiered concentration: multinational chemical conglomerates with technical service infrastructure capture large-scale Brazilian contracts, while domestic formulators defend share through ANVISA compliance agility and localized inventory positions. Three archetypes dominate: integrated polymer suppliers with backward chemical control, specialized construction chemical houses with certified applicator networks, and regional blenders with distributor-anchored geographic coverage. Competitive intensity centers on M&A to acquire compliant production assets and strategic partnerships to secure curing agent supply chains.
Within the multinational tier, Henkel AG & Co. KGaA, Sika AG, and BASF SE exemplify divergent route-to-market strategies. Henkel leverages technical service infrastructure to anchor premium positioning across Brazilian infrastructure tenders requiring contractor certification. Sika occupies a position concentrated on concrete repair applications through specialized formulations and direct contractor relationships. BASF extends reach via distributor networks that control last-mile access in secondary Argentine cities and Brazil's northern construction corridor.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Arkema Group |
| 3M |
| Huntsman International LLC |
| BASF SE |
| H.B. Fuller Company |
| Sika AG |
| MAPEI |
| Dow |
| Others |
Value Network & Pricing Analysis
ANVISA's updated occupational exposure limits for isocyanate-containing products gate both qualified supply and premium-tier pricing access, compressing margins for non-compliant imports while rewarding domestic blenders with certified waterborne polyurethane portfolios. This regulatory pivot concentrates pricing power among Brazilian producers with backward integration into compliant formulation infrastructure.
Pricing Analysis
Capacity additions in Brazil's southeastern chemical corridor are reshaping price floors for waterborne polyurethane systems, intensifying competition among domestic blenders while import-dependent suppliers face currency-driven cost compression. Three-tier pricing structure across certified premium, standard-grade, and economy formulations separates ABNT-compliant structural bonding systems from uncertified commodity alternatives. Pricing pressure stems from petrochemical input volatility, with polyol and isocyanate feedstock costs tracking international crude benchmarks. Residential flooring contractors exhibit the highest price sensitivity, while infrastructure tenders prioritize technical service bundling over unit cost.
Supply Chain Analysis
Returns of non-compliant solvent-based inventories and reformulation runs for ANVISA-aligned waterborne systems are creating reverse-logistics flows that strain working capital across Brazilian distribution networks. Raw material sourcing draws from German and Swiss supplier networks for specialty curing agents and rheology modifiers, exposing South American blenders to extended lead times and currency risk. Geographic supply concentration centers on Brazil for formulation, Argentina for facade retrofit demand, and Chile for green-certified commercial projects. Single-source vulnerability for isocyanate feedstocks represents the dominant structural risk. Distribution runs through authorized networks controlling last-mile access in secondary Argentine cities and Brazil's northern construction corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with ANVISA's VOC thresholds and ABNT certification requirements continuously upgrading specification barriers that favor incumbent technical service infrastructure over commodity supply.
For Market Incumbents: Cement premium positioning through exclusive ABNT-certified applicator networks in São Paulo and Minas Gerais, defending against emerging domestic blenders with rapid reformulation capabilities. Prioritize backward integration into waterborne polyurethane dispersion capacity to offset petrochemical input volatility and secure margin capture in infrastructure tenders requiring contractor certification. For New Entrants and Emerging Players: Secondary Argentine cities with distributor-dependent supply access represent the most penetrable white-space target, where last-mile inventory holding constraints create service gaps for agile regional blenders. Target Chile's pending Supreme Decree 594 compliance window with pre-certified silane modified polymer portfolios, leveraging green building certification expansion ahead of incumbent specification lock-in. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Brazilian blenders with ANVISA-compliant production assets because regulatory fragmentation across MERCOSUR member states extends product launch timelines and rewards acquired certification infrastructure. Monitor ABNT NBR standard updates and Chilean green bond covenant expansion as inflection indicators for specification authority migration toward financier-driven material selection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waterborne Polyol Supply | Captures margin compression from isocyanate feedstock volatility in Brazilian formulation corridors. |
| ABNT-Certified Applicator Network Expansion | Locks out uncertified competitors from federal infrastructure tenders requiring bonded contractor relationships. |
| Silane Modified Polymer Portfolio Launch | Targets Argentine facade retrofit demand with movement accommodation exceeding conventional adhesive limits. |
| Chilean Green Building Pre-Certification | Positions compliant suppliers ahead of Supreme Decree 594 mandates in Santiago commercial real estate. |
| Strategic Distributor Partnership in Northern Brazil | Extends reach beyond southeastern corridor concentration into working-capital-constrained secondary markets. |
Research Methodology
Bottom-up construction end-use modeling reconciled against top-down adhesive formulation capacity tracking forms the analytical core, combining primary interviews with plant managers at Brazilian blenders, procurement leads at São Paulo commercial contractors, distribution channel partners across Argentina, and technical R&D directors at multinational suppliers. Secondary validation draws from ANVISA regulatory filings, ABNT NBR standard documentation, MERCOSUR technical regulations, customs trade data for polyol and isocyanate imports, and SEC 10-K disclosures from listed construction chemical conglomerates. Triangulation between demand-side project pipelines and supply-side production runs ensures volume reconciliation.
Historical trendline analysis of infrastructure spending cycles, green building certification penetration, and formulation chemistry shifts informs projection parameters across the analysis window. Segmentation dimensions modeled include chemistry type, end-use sector, application method, and specification channel authority. CAGRs derive from elasticity-adjusted demand curves calibrated against petrochemical input cost trajectories and regulatory compliance timeline assumptions. Industry-specific forecast inputs incorporate ABNT certification adoption curves and Chilean green bond issuance patterns.
Underlying measurement precision varies by segment; polyurethane volume estimates carry tighter precision than emerging silane modified polymer categories where specification data remains sparse. Forecasts reflect documented assumptions regarding infrastructure tender award timelines and regulatory harmonization progress across MERCOSUR member states. Practitioners should monitor ANVISA enforcement intensity and Chilean Supreme Decree 594 implementation schedules for early signals of specification authority migration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
India Construction Chemicals Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Mexico Sealants Market