
 Global Electrically Conductive Adhesives Market | 2026-2036
Global Electrically Conductive Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrically Conductive Adhesives Market Foresight
Automotive electronics is shifting toward electrically conductive adhesives as EV inverters, battery management systems, and advanced driver-assistance modules demand thermal cycling reliability beyond solder capabilities. Henkel AG & Co. KGaA leverages its European formulation heritage to dominate high-reliability automotive qualifications. 3M Company sustains broad patent coverage across acrylic and epoxy conductive platforms. Dow Inc. competes through silicone-based systems optimized for flexible printed circuit assemblies in telecommunications infrastructure.
Electrically conductive adhesives are polymeric systems loaded with metallic or carbon fillers that achieve volumetric resistivity below 10^-3 ohm-cm while maintaining bondline integrity across -40°C to 150°C operational windows; they replace mechanical fasteners and solder in assemblies where thermal damage or galvanic corrosion risks prohibit traditional joining. Silver-based formulations command the dominant margin pool due to filler cost pass-through mechanisms and established qualification protocols in aerospace electronics. Carbon-based alternatives are capturing share in renewable energy system busbar attachments where cost-per-watt sensitivity overrides conductivity optimization. Screen printing technology leads volume throughput for printed circuit board assemblers, though dispensing systems are gaining traction in semiconductor fabricator flip-chip applications requiring sub-50-micron placement accuracy.
EPA guidelines on volatile organic compound emissions constrain solvent-based adhesive formulations in US manufacturing facilities, while REACH registration requirements in Europe enforce full chemical substance disclosure across imported filler materials. China's GB standards on electronic product pollution control, administered by MEE, mandate recyclability assessments that reshape adhesive selection for consumer electronics exports. Semiconductor fabricators and automotive electronics suppliers must monitor evolving dual carbon compliance timelines in China and EU Green Deal carbon border adjustments that will alter silver filler sourcing economics and regional production footprints.
Market Dynamics
EV powertrain electrification is forcing semiconductor packaging and automotive electronics suppliers to abandon solder interconnects in favor of adhesive solutions that survive thermal cycling from -40°C to 150°C without joint degradation or galvanic corrosion.
Growth Catalysts
- RoHS and REACH compliance mandates:European electronics manufacturers face binding restrictions on lead-containing solders and high-VOC formulations, accelerating qualification of silver-filled epoxy alternatives in automotive and aerospace supply chains.
- Flip-chip semiconductor packaging:Advanced packaging architectures for AI accelerators and high-performance computing chips require sub-50-micron bondline precision that dispensing-system conductive adhesives deliver where solder bumping fails.
- China's dual carbon trajectory:MEE-administered recyclability assessments and carbon border preparation timelines are redirecting domestic electronics exports toward adhesives with documented lifecycle footprints and regional silver sourcing.
Market Restraints
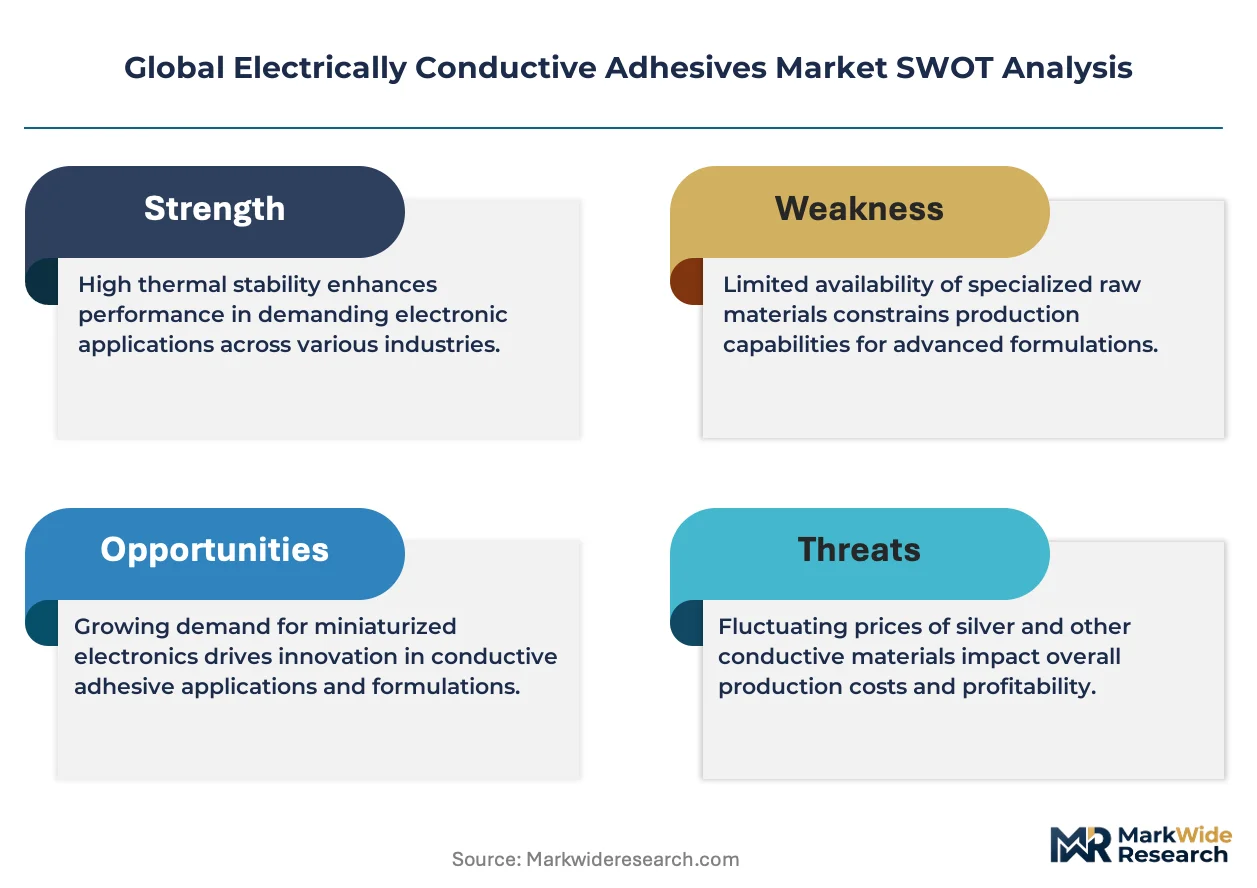
- Silver price volatility:Conductive formulations containing 60-80% silver filler by weight expose formulators and end-users to London Metal Exchange price swings that compress margins and destabilize contract pricing.
- Japanese filler supply concentration:High-purity flake and spherical silver particles for semiconductor-grade adhesives concentrate among Tokyo and Osaka-based metallurgical suppliers, creating single-source vulnerability for qualified automotive electronics programs.
- Thermal conductivity ceiling:Polymeric matrices max out at 5-15 W/mK even with optimal filler loading, restricting adhesive use in EV inverter modules where die-attach materials must exceed 50 W/mK.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor assembly and mobile device production are creating first-mover advantage for adhesive suppliers establishing local formulation and technical service capabilities.
- Renewable energy busbar attachment:Utility-scale solar and battery energy storage systems favor carbon-filled conductive adhesives where cost-per-watt sensitivity overrides the conductivity premium of silver systems.
- EU Green Deal carbon border adjustments:Impending CBAM implementation on imported electronics is incentivizing European OEMs to source adhesives with verified low-carbon silver and regional production footprints to avoid tariff exposure.
Industry Challenges
- Automotive qualification timelines:AEC-Q100 and AEC-Q200 stress-testing protocols demand 1,000+ hour thermal cycling and 85°C/85%RH aging studies that extend new adhesive validation to 18-24 months.
- Dispensing equipment integration:Semiconductor fabricators face retrofit complexity when migrating from solder bumping to jet-dispensed conductive adhesives, requiring coordinated capital deployment across assembly lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrically Conductive Adhesives Market |
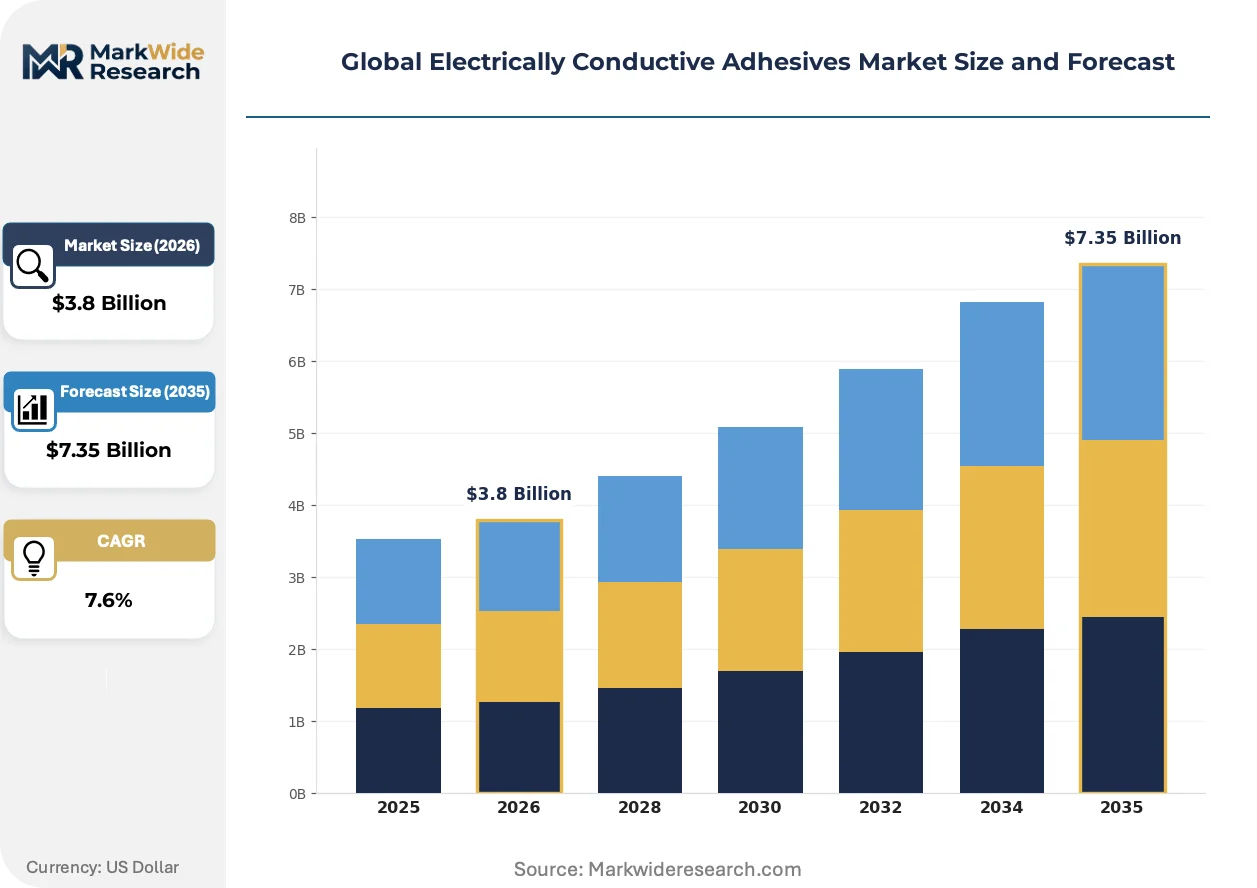
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver-Based, Carbon-Based, Nickel-Based, Copper-Based, Aluminum-Based Technology: Screen Printing, Dispensing, Dipping, Spraying, Coating Application: Consumer Electronics, Aerospace Electronics, Telecommunications, Military Equipment, Renewable Energy Systems End User: Electronic Manufacturing Services, Printed Circuit Board Assemblers, Semiconductor Fabricators, Automotive Electronics Suppliers, Industrial Equipment Producers |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Dow Inc., H.B. Fuller Company, Panacol-Elosol GmbH, Master Bond Inc., Aremco Products Inc., Parker Hannifin Corporation, Creative Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrically Conductive Adhesives Market Shifts & Advancements
Formulation chemistry, regulatory compliance architecture, and procurement operating models are simultaneously restructuring how conductive adhesives are specified, qualified, and supplied across automotive and semiconductor value chains.
Jet dispensing equipment combined with machine vision alignment is automating sub-50-micron adhesive placement in flip-chip and fan-out wafer-level packaging. TSMC and Samsung Foundry process engineers are expanding adhesive-based die-attach flows for heterogeneous integration packages where solder reflow temperatures damage adjacent components. This automation is compressing throughput differentials between adhesive and solder-based assembly while expanding addressable package geometries.
REACH Annex XVII restrictions on microplastics and evolving ECHA substance evaluation protocols are forcing reformulation of acrylic conductive adhesives containing persistent polymer fractions. German and French electronics suppliers now require full SCIP database disclosure for imported adhesive systems. Aerospace and medical device segments are responding fastest, shifting procurement toward epoxy and silicone platforms with established polymer safety dossiers.
Automotive tier-one electronics suppliers are consolidating adhesive vendor panels from 6-8 qualified sources to 2-3 strategic partnerships with integrated formulation, dispensing equipment, and field application engineering support. This consolidation is displacing spot-buying through distribution channels in favor of multi-year supply agreements with technical collaboration clauses. The pattern is most visible in Germany and Japan, where Bosch, Continental, and Denso procurement organizations are centralizing conductive material qualification under global commodity management structures.
Global Electrically Conductive Adhesives Market Segmentation
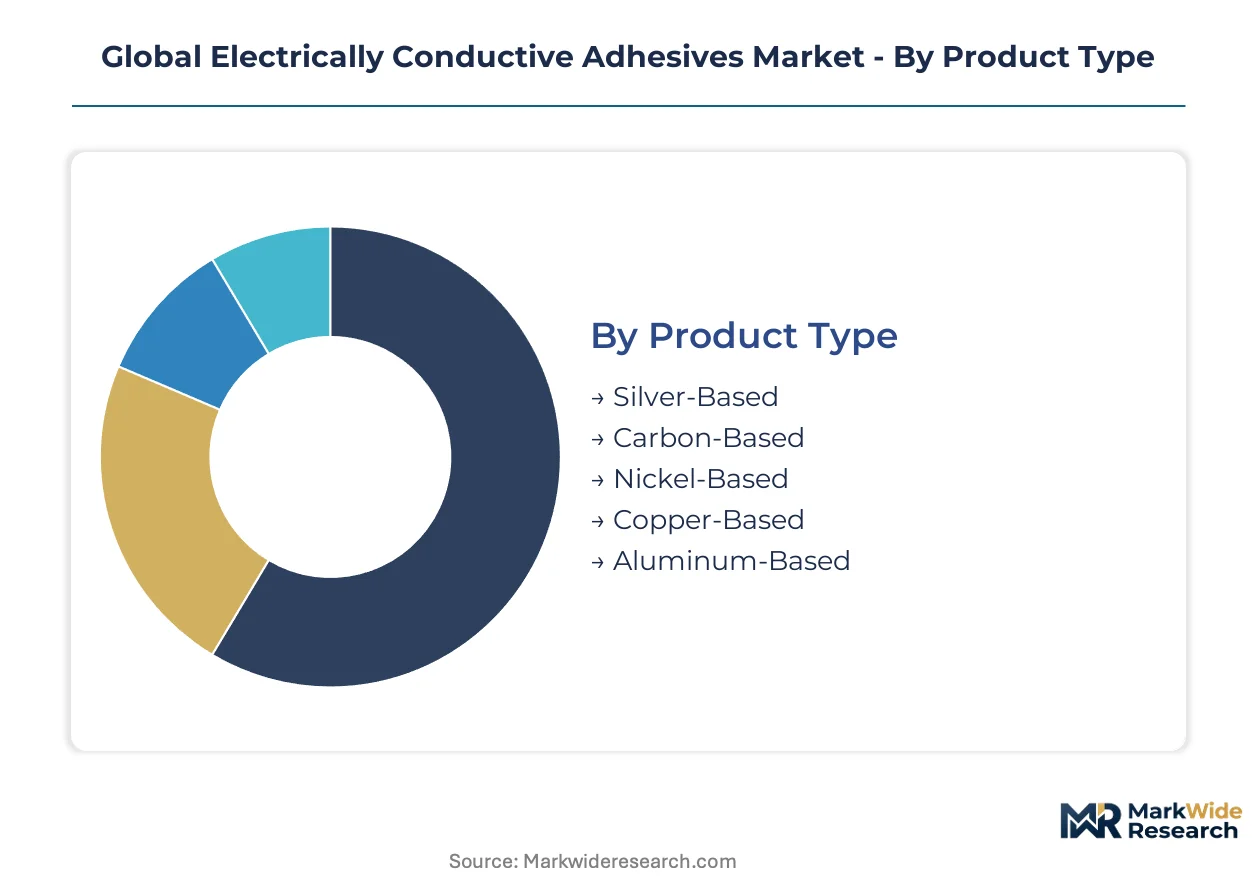
Electrically conductive adhesives fragment across filler chemistry, deposition method, and customer technical requirements. Each segmentation axis reveals distinct margin structures, qualification barriers, and procurement patterns that shape supplier competitive strategy.
Product Type:
Silver-based formulations dominate premium applications where conductivity and reliability justify material cost, while carbon and copper alternatives capture cost-sensitive volume segments.
- Silver-Based:These formulations incorporate 60-80% silver flake or spherical particles to achieve volumetric resistivity below 10^-3 ohm-cm. Semiconductor fabricators in Taiwan and South Korea specify silver-filled epoxies for flip-chip die-attach where thermal cycling reliability outweighs filler expense. REACH and RoHS compliance in European automotive electronics accelerates substitution of lead-bearing solders with qualified silver adhesive interconnects.
- Carbon-Based:Graphite and carbon nanotube-loaded systems trade conductivity for cost efficiency in applications tolerating higher resistivity. Utility-scale solar installations in India and Brazil specify carbon-filled adhesives for busbar attachment where cost-per-watt sensitivity overrides conductivity optimization. The PLI scheme for renewable energy manufacturing in India is expanding procurement volumes for these formulations.
- Nickel-Based:Nickel flake formulations offer electromagnetic interference shielding performance at intermediate cost points for telecommunications infrastructure enclosures.
- Copper-Based:Oxidation-stabilized copper fillers target cost-reduction initiatives in consumer electronics assembly where silver price volatility disrupts contract economics.
- Aluminum-Based:Emerging formulations address weight-sensitive aerospace applications where density reduction complements conductivity requirements.
Today's leader: Silver-Based. Tomorrow's challenger: Carbon-Based.
Technology:
Deposition method selection hinges on bondline precision requirements, throughput economics, and capital equipment integration complexity.
- Screen Printing:High-volume stencil-based application dominates printed circuit board assembly lines where 100-micron-plus bondlines satisfy interconnect requirements. Chinese and Vietnamese electronics manufacturing services deploy screen printing for smartphone and tablet motherboard production where speed and material efficiency outweigh placement precision.
- Dispensing:Jet and needle dispensing systems achieve sub-50-micron placement accuracy for flip-chip and fan-out wafer-level packaging. TSMC and Samsung Foundry process engineers specify dispensing-based adhesive flows for heterogeneous integration packages where solder reflow temperatures damage adjacent components. EPA VOC emission guidelines constrain solvent-based formulations in US facilities using these systems.
- Dipping:Batch immersion processes coat complex geometries in connector and sensor manufacturing where complete surface coverage matters.
- Spraying:Aerosol deposition suits large-area EMI shielding applications in military and telecommunications enclosures.
- Coating:Roll and slot-die coating methods integrate with continuous web processing for flexible printed circuit manufacturing.
Screen printing commands current volume leadership; dispensing technology is climbing the fastest as semiconductor packaging architectures evolve.
Application:
End-use specifications diverge sharply across thermal cycling demands, regulatory compliance requirements, and qualification timeline tolerance.
- Consumer Electronics:High-volume, short-lifecycle production prioritizes cost efficiency and rapid curing. Mobile device assemblers in China and Vietnam specify fast-cure acrylic formulations where GB standards on electronic product pollution control mandate recyclability assessments.
- Aerospace Electronics:Extended qualification protocols and extreme reliability requirements sustain premium pricing. German and French aerospace suppliers demand full SCIP database disclosure under REACH Annex XVII restrictions, favoring epoxy and silicone platforms with established polymer safety dossiers.
- Telecommunications:5G infrastructure deployment drives demand for low-loss, high-frequency compatible adhesive systems in base station and antenna assembly.
- Military Equipment:MIL-SPEC qualification requirements and supply chain security protocols favor domestic sourcing in US and European defense electronics.
- Renewable Energy Systems:Solar module and battery energy storage manufacturers prioritize cost-per-watt optimization over conductivity maximization.
Consumer Electronics generates present volume concentration; Aerospace Electronics sustains the steepest expansion trajectory as satellite and electric aircraft programs multiply.
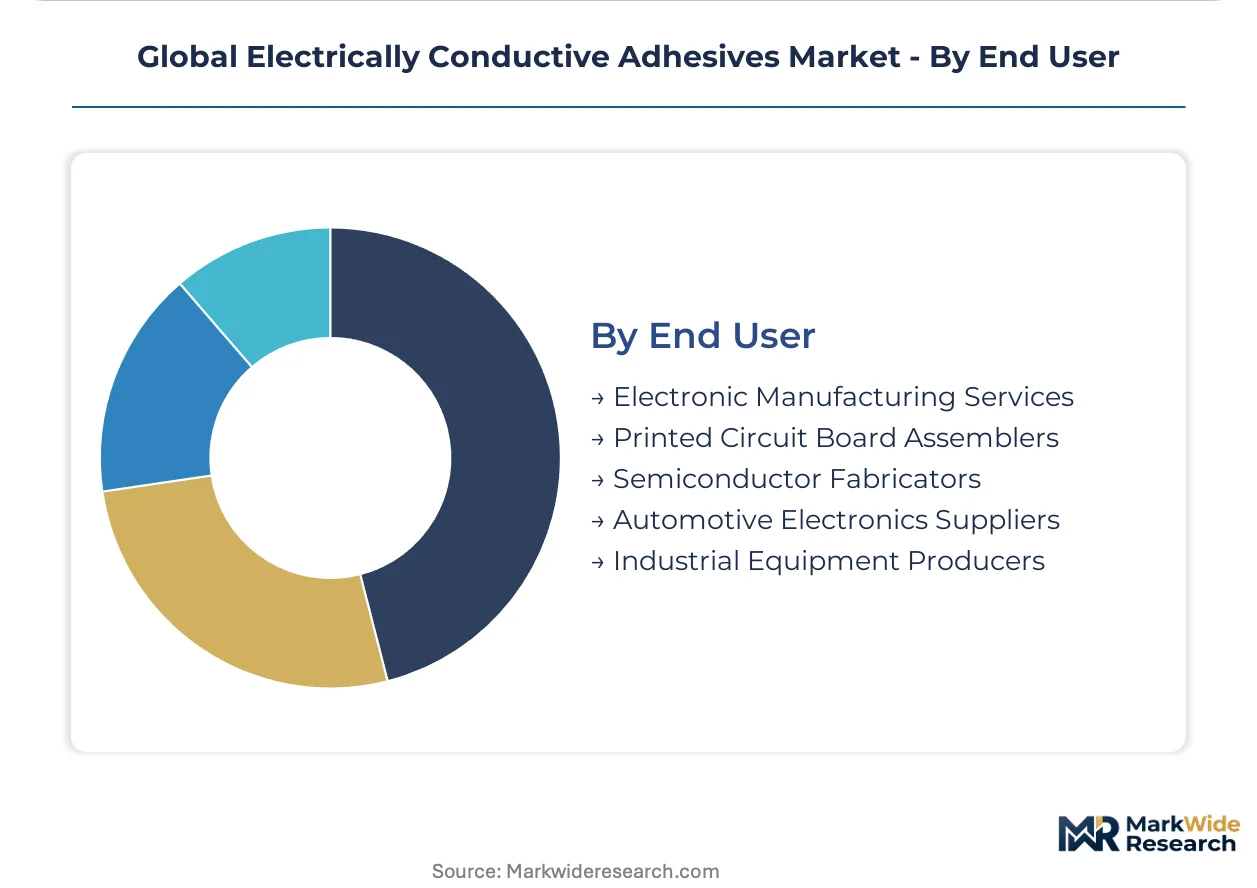
End User:
Customer technical capabilities and procurement sophistication determine adhesive specification authority and vendor relationship structure.
- Electronic Manufacturing Services:Foxconn, Jabil, and Flex operate global assembly networks where adhesive selection follows OEM customer mandates. These providers consolidate purchasing across multiple programs to extract volume pricing from qualified suppliers.
- Printed Circuit Board Assemblers:Regional specialists in Germany, Japan, and Taiwan differentiate through high-mix, low-volume capabilities requiring broad adhesive formulation portfolios.
- Semiconductor Fabricators:TSMC, Intel, and Samsung Foundry exercise direct formulation development partnerships with adhesive suppliers for advanced packaging nodes. Sub-50-micron placement precision requirements drive dispensing equipment integration investments.
- Automotive Electronics Suppliers:Bosch, Continental, and Denso procurement organizations centralize conductive material qualification under global commodity management structures, consolidating vendor panels from 6-8 sources to 2-3 strategic partnerships.
- Industrial Equipment Producers:Diverse machinery and instrumentation manufacturers specify adhesives for sensor integration and power electronics assembly with moderate technical intensity.
Semiconductor Fabricators currently anchor premium demand; Automotive Electronics Suppliers are gaining share fastest as EV powertrain electrification accelerates adhesive substitution for solder interconnects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting conductive adhesive production toward jurisdictions with lower compliance costs for silver sourcing and VOC emissions, while advanced packaging demand concentrates in East Asian semiconductor clusters.
China
Domestic EV inverter and battery management system manufacturers are displacing solder interconnects with silver-filled epoxies. MEE-administered GB standards on electronic product pollution control mandate recyclability assessments for consumer electronics exports. Yangtze River Delta semiconductor fabricators in Shanghai and Suzhou are expanding adhesive-based die-attach flows for heterogeneous integration packages.
Germany
Automotive electronics suppliers Bosch and Continental are consolidating adhesive vendor panels under centralized global commodity management. REACH Annex XVII restrictions on microplastics and ECHA substance evaluation protocols force reformulation of acrylic conductive adhesives. Bavarian aerospace clusters around Munich demand full SCIP database disclosure, favoring epoxy platforms with established polymer safety dossiers.
United States
EPA guidelines on volatile organic compound emissions constrain solvent-based formulations in domestic manufacturing facilities. 5G infrastructure deployment drives procurement of low-loss adhesive systems for base station assembly. Pacific Northwest flexible printed circuit manufacturers specify silicone-based systems for telecommunications infrastructure applications.
Japan
High-purity flake and spherical silver particle supply concentrates among Tokyo and Osaka-based metallurgical suppliers, creating qualification dependencies for automotive electronics programs. Denso procurement organizations are centralizing conductive material qualification under global structures. Kansai semiconductor packaging clusters are adopting jet dispensing systems for sub-50-micron adhesive placement in flip-chip applications.
India
PLI scheme incentives for semiconductor assembly and mobile device production create first-mover advantage for adhesive suppliers establishing local formulation capabilities. Utility-scale solar installations specify carbon-filled adhesives for busbar attachment where cost-per-watt sensitivity overrides conductivity optimization. Gujarat and Maharashtra electronics manufacturing zones are expanding procurement volumes for renewable energy system applications.
Global Electrically Conductive Adhesives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise commanding premium positioning in automotive and aerospace qualifications while volume production concentrates among integrated material suppliers. The vendor base organizes around three strategic archetypes: European heritage formulators with REACH-compliant portfolios, diversified chemical conglomerates with silicone and epoxy platforms, and regional specialists serving semiconductor packaging niches. Competitive moves center on multi-year supply agreements with technical collaboration clauses and backward integration into silver filler sourcing to mitigate London Metal Exchange price volatility.
Among European heritage formulators, Henkel AG & Co. KGaA and Panacol-Elosol GmbH exemplify the high-reliability automotive qualification tier, occupying positions where REACH compliance and AEC-Q100 validation protocols create multi-year barriers to substitution. Dow Inc. represents the diversified chemical conglomerate archetype, leveraging silicone-based system expertise across telecommunications and flexible printed circuit applications. These three companies anchor the competitive structure through distinct filler-matrix specializations that align with end-use thermal cycling and regulatory requirements.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Dow Inc. |
| H.B. Fuller Company |
| Panacol-Elosol GmbH |
| Master Bond Inc. |
| Aremco Products Inc. |
| Parker Hannifin Corporation |
| Creative Materials Inc. |
| Others |
Supply & Pricing Matrix
Automotive qualification tiers split the conductive adhesives landscape into AEC-Q100 validated premium formulations and uncertified commodity alternatives, with that bifurcation driving divergent margin structures and procurement behaviors across European OEMs and Asian electronics manufacturing services. Silver filler pass-through mechanisms anchor pricing in London Metal Exchange volatility, while REACH compliance costs concentrate qualified supply among heritage European formulators.
Pricing Analysis
Distributor margins compress in carbon-filled commodity segments where Indian solar manufacturers negotiate direct volume offtakes, while semiconductor fabricators absorb premium markups for qualified silver epoxies through multi-year supply agreements. Pricing stratifies across automotive-grade, industrial-standard, and economy-level tiers based on thermal cycling certification and filler purity. Cost compression in carbon-based alternatives intensifies because renewable energy procurement teams prioritize cost-per-watt metrics over conductivity optimization. EMS providers in Vietnam exhibit highest price sensitivity; aerospace suppliers in Germany show least.
Supply Chain Analysis
Dual-sourcing requirements from Bosch and Continental procurement teams mandate qualified alternative suppliers for silver flake feedstock, mitigating concentration risk among Tokyo and Osaka-based metallurgical specialists. Raw material flows draw from Japanese high-purity silver processors, German epoxy resin specialists, and Chinese carbon nanotube producers. Single-source vulnerability concentrates in semiconductor-grade spherical silver particle supply. Distribution runs through authorized distributor networks for qualified automotive programs, with direct technical service relationships for semiconductor fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conductive adhesives market has entered a late-cycle quality phase where AEC-Q100 validation and REACH Annex XVII compliance separate viable suppliers from commodity players, with EV powertrain electrification accelerating specification upgrades.
For Market Incumbents: Deploy backward integration into silver filler sourcing to neutralize London Metal Exchange volatility exposure. Secure AEC-Q200 pre-qualification for emerging die-attach formulations before automotive electronics suppliers consolidate vendor panels. Carbon nanotube-loaded alternatives threaten margin pools in renewable energy applications. For New Entrants and Emerging Players: Jet dispensing compatibility for sub-50-micron placement offers the most penetrable wedge into semiconductor packaging workflows. Target India's PLI-supported electronics manufacturing zones where local formulation capabilities remain underdeveloped. Partner with dispensing equipment OEMs for integrated technical service offerings. For Investors and Strategic Acquirers: Consolidation pressure builds where automotive qualification timelines exceed 18 months and vendor panel reduction programs concentrate share among 2-3 strategic suppliers. Mid-cap European formulators with REACH-compliant portfolios and established AEC-Q100 dossiers represent prime acquisition targets. Monitor silver price volatility spikes as inflection signals for margin compression events.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Filler Processing | Henkel and Panacol-Elosol mitigate London Metal Exchange price swings through captive flake supply. |
| AEC-Q100 Pre-Qualification Investment | Automotive electronics suppliers at Bosch and Denso consolidate vendor panels around pre-validated adhesive platforms. |
| Jet Dispensing Equipment Partnership | TSMC and Samsung Foundry process engineers specify adhesive-dispenser integrated workflows for heterogeneous integration. |
| India Local Formulation Facility | PLI scheme incentives for semiconductor assembly create first-mover advantage for technical service presence. |
| REACH Annex XVII Reformulation Program | German aerospace clusters demand SCIP database disclosure, favoring epoxy platforms with established safety dossiers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive formulators, automotive Tier 1 procurement directors, semiconductor packaging engineers, and dispensing equipment specialists with secondary validation from SEC 10-K filings, customs trade data, and ECHA substance registration databases. Bottom-up demand modeling across filler chemistry segments triangulated against top-down market sizing from regional production cluster analysis.
Comparable historical periods anchored the projection horizon, with CAGRs derived from segment-level growth rate reconciliation across silver-based, carbon-based, and copper-based formulation categories. The analytical framework modeled technology adoption curves for dispensing versus screen printing deposition methods, EV powertrain content-per-vehicle trajectories, and semiconductor packaging node migration patterns. Silver price volatility scenarios and automotive qualification timeline distributions served as key forecast sensitivity inputs.
The model holds under stable regulatory compliance timelines and continued EV powertrain electrification; deviation in REACH enforcement intensity or solder substitution reversal would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
Global Elastic Adhesive Market
Adhesives & Sealants
United States Sealants Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
Ocular Adhesives and Sealants Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Indonesia Sealants Market