
 Roofing Adhesive Market | 2026-2036
Roofing Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Roofing Adhesive Market Outlook
Capital-intensity divergence between integrated chemical conglomerates and specialty adhesive formulators is bifurcating competitive dynamics. Dow leverages backward integration into petrochemical feedstocks to control raw material costs across polyurethane roofing adhesive lines. Sika AG sustains premium positioning through R&D intensity focused on cold-applied membrane bonding systems. H.B. Fuller Company competes via geographic dominance in North American commercial re-roofing channels.
Roofing adhesive comprises polymeric bonding agents formulated to secure waterproofing membranes, insulation boards, and protective surfacing to structural roof decks, typically exhibiting elastomeric recovery exceeding 200% after ASTM D412 testing. These materials seal building envelopes against moisture intrusion while accommodating thermal cycling stress across membrane assemblies. Polyurethane formulations command margin pools in commercial low-slope applications where tensile strength and low-temperature flexibility prove critical. Water-based technology segments are gaining share in residential markets as contractors navigate VOC compliance thresholds without sacrificing open-time performance. Solvent-based systems retain structural importance in metal roofing applications where substrate compatibility and rapid green strength development remain non-negotiable.
EPA VOC regulations constrain solvent-based formulation options across US commercial roofing projects, while REACH chemical authorization requirements in Europe filter candidate substances for long-term membrane bonding applications. OSHA workplace exposure standards influence contractor purchasing decisions regarding heat-applied versus cold-applied installation systems. Stakeholders must monitor evolving embodied carbon accounting methodologies as these frameworks increasingly determine specification eligibility for publicly funded building renovation programs.
Market Dynamics
Commercial building envelope retrofits are accelerating specification velocity for high-performance bonding systems as energy codes tighten across developed economies. Cold-applied membrane attachment is displacing torch-applied methods in urban cores where fire risk restrictions proliferate.
Growth Catalysts
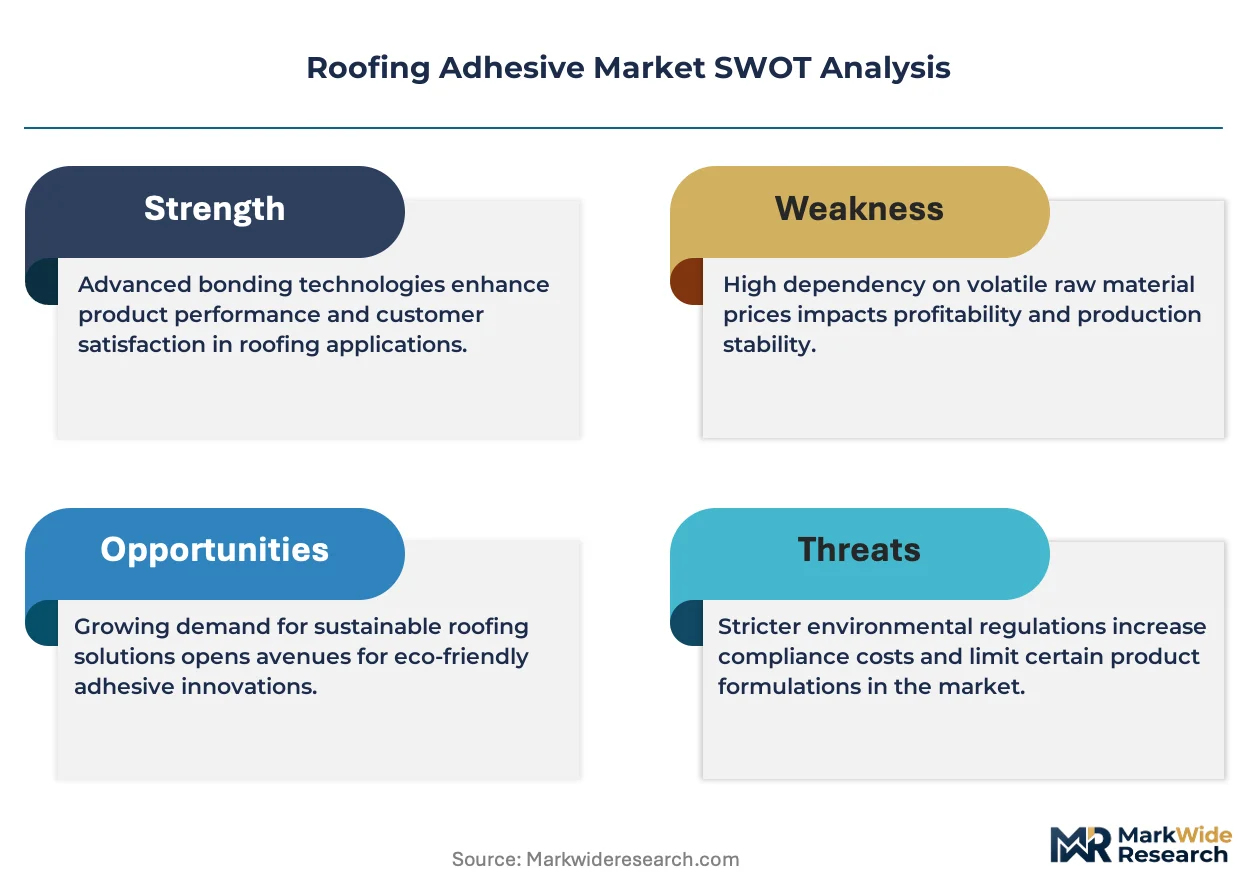
- EU Green Deal embodied carbon mandates:Member states now require lifecycle carbon accounting for publicly funded renovation projects, elevating low-carbon adhesive formulations in specification hierarchies across Germany, France, and the Netherlands.
- Low-slope commercial re-roofing cycles:Aging membrane infrastructure in North American retail and logistics facilities is driving pull for polyurethane systems that bond directly over existing substrates without tear-off.
- Polyurethane spray foam integration:Roofing contractors are specifying dual-purpose adhesive-foam systems that combine membrane attachment with continuous insulation, compressing installation timelines on steep-slope metal retrofits.
Market Restraints
- MDI feedstock volatility:Methylene diphenyl diisocyanate prices fluctuate with crude oil and benzene derivatives, squeezing margin pools for polyurethane formulators without captive petrochemical supply.
- REACH authorization bottlenecks:ECHA's candidate list scrutiny for isocyanates and heavy-metal catalysts is extending reformulation timelines by 18-24 months for European product registrations.
- Solvent-based substitution ceiling:Waterborne acrylics still fail to match the green strength and substrate tolerance of solvent systems on oxidized metal decks, preserving legacy chemistry in industrial roofing segments.
Strategic Opportunities
- India commercial construction acceleration:BIS certification harmonization with ISO standards is lowering import barriers for cold-applied membrane adhesives in Bangalore and Mumbai high-rise markets.
- Photovoltaic-integrated roofing:Bifacial solar module attachment demands flexible, thermally stable bonding layers that accommodate differential expansion between glass and membrane substrates.
- US Inflation Reduction Act renovation credits:Tax incentives for building envelope improvements are redirecting facility manager capital toward full membrane replacement versus patch repairs.
Industry Challenges
- Cold-application technician certification:Contractor licensing boards in multiple US states lack standardized curricula for spray polyurethane foam and adhesive application, creating labor supply bottlenecks during peak roofing seasons.
- Membrane-adhesive compatibility testing:TPO and PVC membrane manufacturers maintain proprietary approval lists, forcing adhesive suppliers to run parallel qualification programs with fragmented technical requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roofing Adhesive Market |
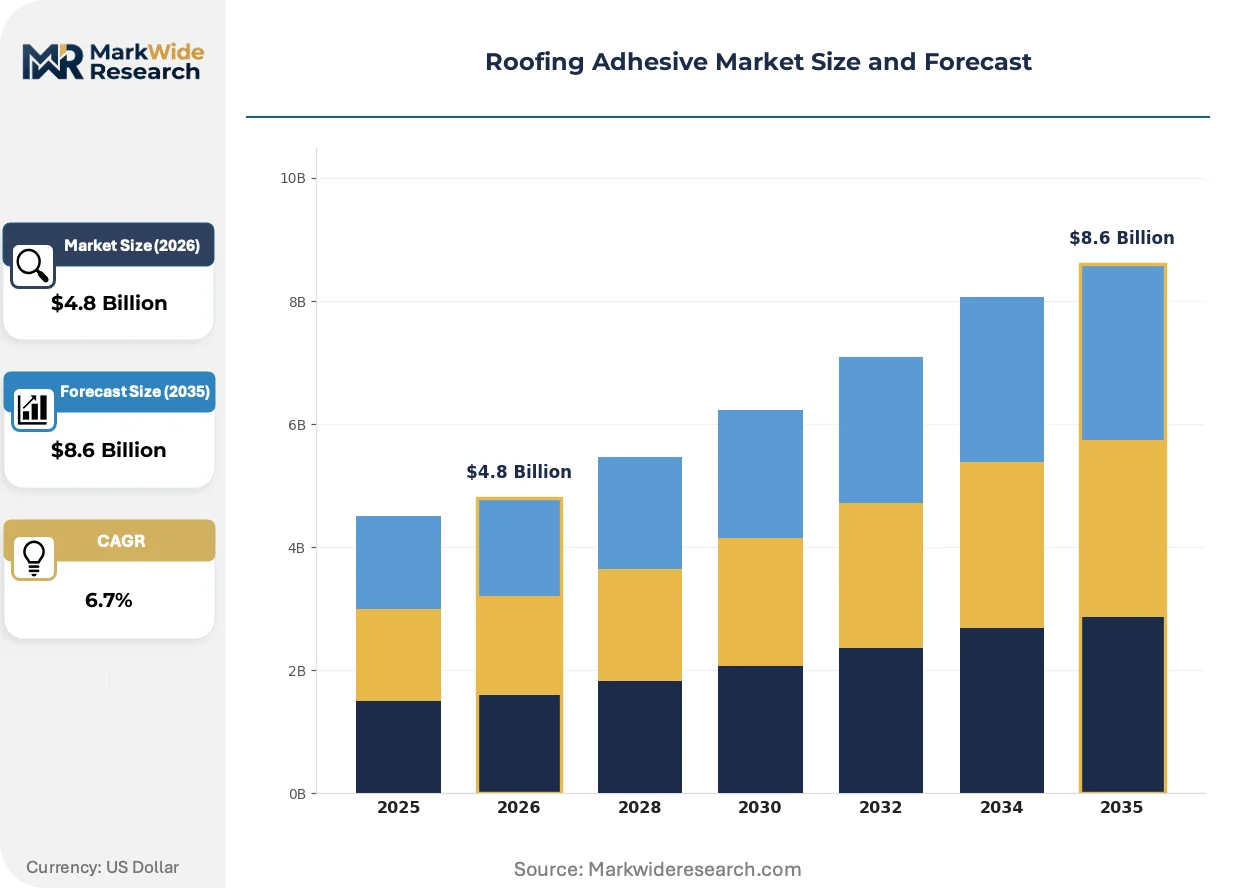
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, Bitumen, Silicone Application: Residential Roofing, Commercial Roofing, Industrial Roofing, Metal Roofing Technology: Heat-Applied, Solvent-Based, Water-Based, Cold-Applied End User: Contractors, DIY Users, Manufacturers, Distributors |
| Companies Covered | Sika AG, Henkel AG & Co. KGaA, Dow, BASF, 3M, H.B. Fuller Company, MAPEI S.p.A., Tremco, GAF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roofing Adhesive Market Strategic Shifts
Formulation chemistry is diverging along performance-versus-compliance axes as regional regulatory thresholds harden. Manufacturers are pursuing parallel development tracks rather than universal product platforms.
Hybrid polyurethane-silane adhesive technology is fragmenting specification patterns across commercial low-slope segments. These systems combine the tensile strength of urethane backbones with moisture-cure versatility for humid climate installation. Large retail chain facility managers in the US Southeast are specifying hybrid systems for 24-hour cure requirements on occupied buildings. The technology is fragmenting competitive positioning between pure polyurethane specialists and silane-modified polymer entrants.
REACH microplastic restriction proposals are forcing reformulation of protective surfacing granules and reflective coating systems across European roofing supply chains. ECHA's 2023 restriction roadmap targets intentionally added microplastics in construction materials with phase-out deadlines approaching 2028. German and Nordic membrane manufacturers are accelerating bio-based granule development while adhesive suppliers validate compatibility with novel surfacing chemistries.
Specification authority is migrating from general contractors to building envelope consultants with forensic failure expertise. Large commercial owners in California and New York now require third-party adhesion testing and long-term warranty underwriting before adhesive approval. This consultant-driven gatekeeping favors suppliers with documented ASTM D6083 and D6848 test portfolios over low-bid commodity options.
Roofing Adhesive Market Segmentation
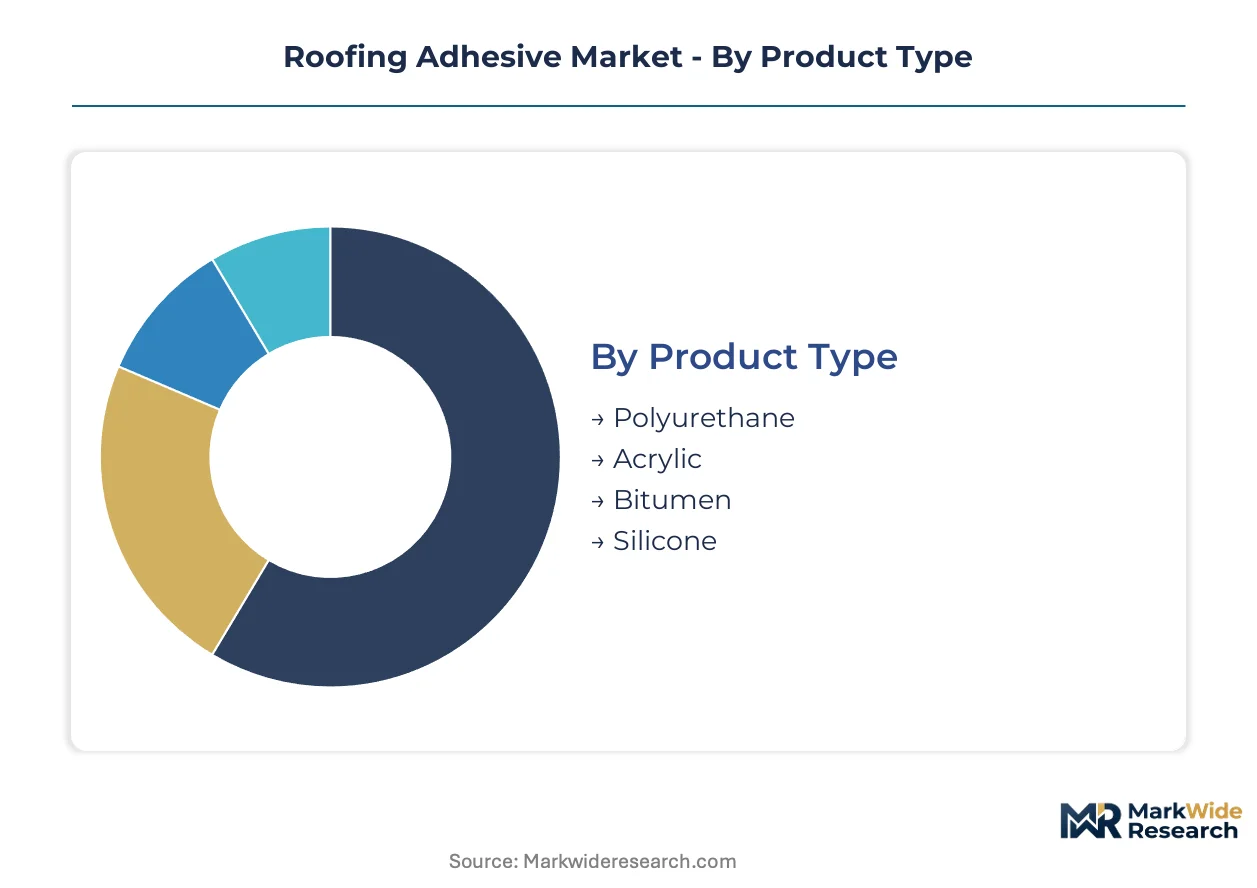
Roofing adhesive specification patterns diverge sharply across building types and regulatory environments. Understanding these segment boundaries reveals where formulation investments concentrate and which technology platforms face substitution pressure.
Product Type:
Polyurethane formulations dominate export flows to high-performance commercial markets, while bitumen and acrylic segments serve more localized, cost-sensitive applications.
- Polyurethane:These two-component systems combine isocyanate resins with polyol blends to achieve tensile strength exceeding 1000 psi and elastomeric recovery above 200%. Demand concentrates in German and US commercial low-slope retrofits where direct-to-substrate bonding eliminates tear-off costs and compresses project timelines.
- Acrylic:Waterborne acrylic emulsions offer VOC compliance below 50 g/L for residential re-roofing in California and Northeast US markets. Growth is accelerating fastest in contractor segments navigating EPA air quality management district thresholds without sacrificing open-time workability.
- Bitumen:Modified asphalt adhesives retain dominance in Indian and Southeast Asian cost-driven markets where torch-applied SBS membranes remain standard practice.
- Silicone:Neutral-cure silicone systems command premium positioning in photovoltaic-integrated roofing across Arizona and Nevada solar installations.
Polyurethane holds the largest share; momentum sits with acrylic as regulatory pressure intensifies.
Application:
Commercial roofing drives margin capture through specification complexity, while residential and industrial segments reward volume scale and distribution efficiency.
- Commercial Roofing:Low-slope membrane attachment in retail, logistics, and healthcare facilities demands adhesives with 30-year lifecycle performance. Specification authority has migrated to building envelope consultants in California and New York who require ASTM D6083 adhesion testing before approval.
- Residential Roofing:Steep-slope asphalt shingle and metal roofing applications favor water-based and solvent-based systems with rapid green strength development. Demand clusters in Texas and Florida reroofing cycles following hurricane season damage assessments.
- Industrial Roofing:Chemical processing and food manufacturing facilities specify chemical-resistant epoxy-modified adhesives for containment areas and washdown environments.
- Metal Roofing:Standing seam and corrugated panel attachment requires high-bond-strength formulations compatible with oil-contaminated and oxidized galvanized substrates common in agricultural and warehouse construction.
Commercial roofing commands the deepest specification barriers; residential is climbing fastest on renovation tax credit tailwinds.
Technology:
Installation method selection increasingly follows fire code geography rather than contractor preference, fragmenting technology adoption patterns.
- Cold-Applied:These pump-grade or sprayable systems eliminate open-flame hazards in urban cores with strict fire restrictions. Chicago, Boston, and London have accelerated adoption through municipal ordinances prohibiting torch-applied methods on occupied buildings.
- Heat-Applied:Hot-melt bitumen and thermoplastic adhesive application retains cost advantages in unoccupied new construction across suburban US markets and emerging Asian economies.
- Solvent-Based:High-solids formulations maintain structural importance in metal roofing where substrate tolerance and rapid tack development outweigh VOC compliance costs.
- Water-Based:Zero-VOC acrylic and hybrid polymer systems are gaining specification share in school and hospital projects across EPA-designated non-attainment zones.
Cold-applied technology holds the largest share; water-based systems are expanding most quickly on regulatory momentum.
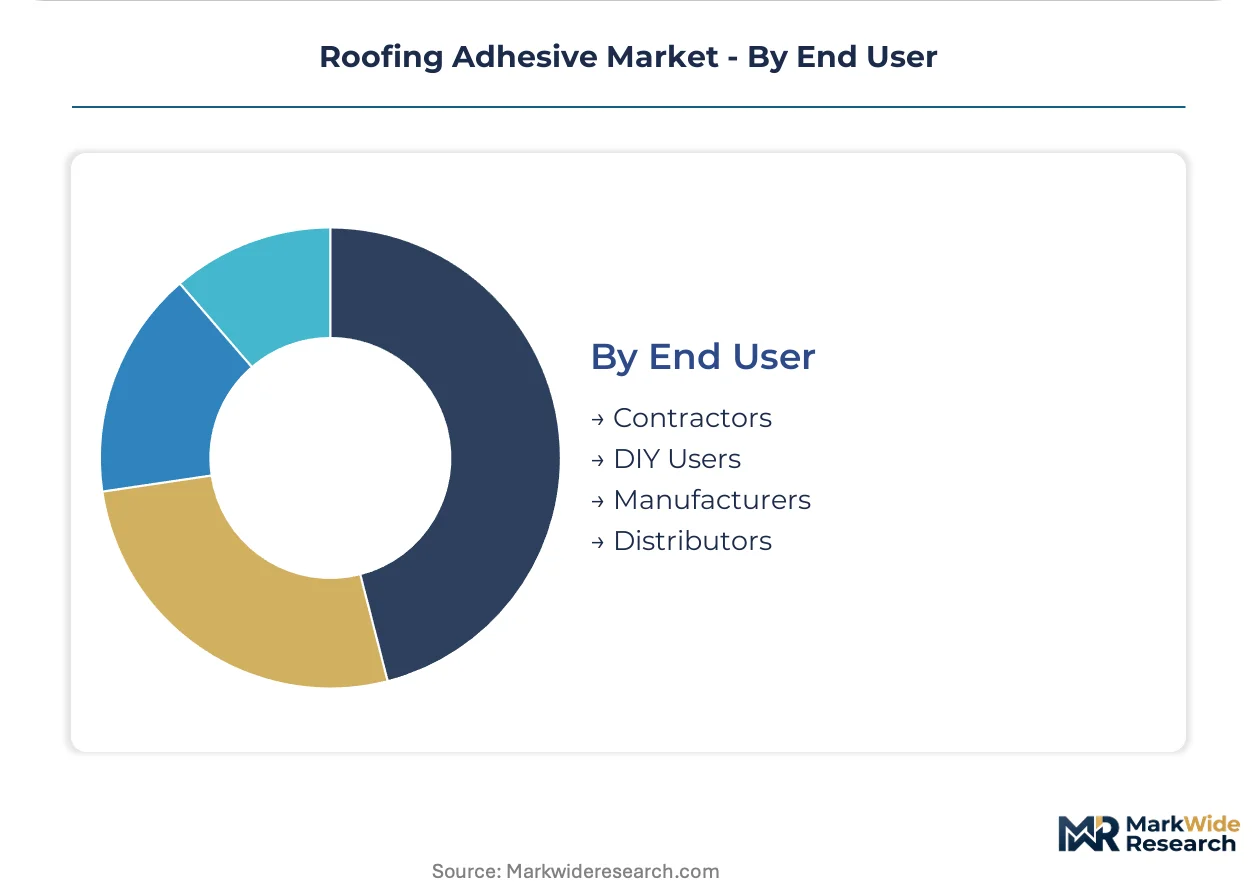
End User:
Procurement authority splits between specification-driven contractor channels and price-sensitive distributor bulk purchasing.
- Contractors:Licensed roofing contractors in Germany and the US Northeast specify approved adhesive-membrane combinations to secure manufacturer warranties and reduce callback liability.
- Distributors:Beacon Roofing Supply and ABC Supply aggregate demand across fragmented contractor bases, pushing formulators toward pallet-volume pricing and just-in-time regional inventory.
- Manufacturers:TPO and PVC membrane producers maintain captive adhesive approval programs, forcing parallel qualification testing from suppliers seeking specification.
- DIY Users:Retail channel purchasers in home improvement centers drive small-format packaging demand for residential repair and shed applications.
Contractors hold the largest share; distributors are gaining procurement leverage through consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity for high-performance systems, while Indian and Southeast Asian markets prioritize cost minimization over specification complexity. This demand-elasticity contrast shapes where formulators invest in premium chemistry versus commodity volume scale.
United States
Commercial re-roofing cycles in retail and logistics facilities drive specification of polyurethane systems that bond directly over existing substrates. The EPA enforces VOC thresholds through regional air quality management districts, particularly in California and the Northeast. Chicago and Boston municipal ordinances now prohibit torch-applied methods on occupied buildings, accelerating cold-applied adhesive uptake.
Germany
Deep renovation targets under the EU Green Deal sustain pull for low-carbon adhesive formulations in publicly funded building projects. ECHA REACH authorization requirements filter candidate substances for long-term membrane bonding applications. Industrial clusters in North Rhine-Westphalia concentrate formulation R&D and membrane manufacturer headquarters, creating tight supplier-integrator relationships.
India
Commercial construction acceleration in Bangalore and Mumbai high-rise markets drives demand for cold-applied membrane adhesives. BIS certification harmonization with ISO standards is lowering import barriers for foreign suppliers. Cost-driven procurement favors modified bitumen systems in tier-2 and tier-3 cities where torch-applied SBS membranes remain standard practice.
China
Urban renewal programs and energy efficiency retrofits in coastal provinces generate specification volume for building envelope bonding systems. The country's national environmental regulator enforces emissions controls on solvent-based formulations in key manufacturing zones. Yangtze River Delta industrial clusters concentrate domestic adhesive production capacity serving both domestic and export markets.
Japan
Seismic retrofit mandates and aging commercial building stock sustain demand for flexible, thermally stable bonding systems. METI building energy codes tighten requirements for envelope thermal performance, elevating specification standards. Kanto region facility managers prioritize 30-year lifecycle performance and documented adhesion testing before adhesive approval.
Roofing Adhesive Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with chemical conglomerates leveraging captive petrochemical supply against focused adhesive formulators competing on R&D intensity and channel relationships. The market structure rewards backward integration into MDI and polyol feedstocks for cost control, while specialty players defend position through membrane manufacturer approval programs and building envelope consultant specification authority. Two strategic archetypes dominate: integrated chemical conglomerates with global manufacturing footprints, and regional specialists with deep certification portfolios. Competitive moves concentrate on geographic expansion into BIS-harmonized Indian markets and portfolio diversification toward photovoltaic-integrated roofing systems.
Within the integrated chemical tier, Dow and BASF occupy positions anchored by upstream control over petrochemical feedstocks. Sika AG exemplifies the premium specialist archetype, with its Swiss AG structure signaling focused formulation expertise rather than commodity chemical breadth. H.B. Fuller Company represents the North American channel-dominant model, its incorporated US structure reflecting geographic concentration in commercial re-roofing contractor networks.
| Leading Market Players |
|---|
| Sika AG |
| Henkel AG & Co. KGaA |
| Dow |
| BASF |
| 3M |
| H.B. Fuller Company |
| MAPEI S.p.A. |
| Tremco |
| GAF |
| Others |
Value Chain & Pricing Dynamics
REACH authorization requirements for isocyanates and heavy-metal catalysts simultaneously gate supplier qualification and stratify price tiers across European membrane bonding applications. This regulatory filter forces parallel reformulation investments that concentrate pricing power among formulators with captive petrochemical supply and established ECHA dossier portfolios.
Pricing Analysis
Extended warranty and membrane manufacturer approval programs drive lifetime value capture for premium adhesive suppliers. Three-tier pricing structure across certified-system, approved-list, and commodity tiers separates Sika and Dow from regional specialists and import competitors. Cost compression in waterborne acrylic segments is intensifying because EPA regional air quality districts tighten VOC thresholds faster than formulation innovation cycles. Commercial contractors in Germany and the US Northeast demonstrate lowest price sensitivity, while Indian tier-2 distributors drive hardest bargain on modified bitumen alternatives.
Supply Chain Analysis
Just-in-time regional inventory preferences dominate North American distributor channels, while European formulators maintain strategic stockpiles of MDI and specialty polyols against benzene derivative volatility. Supply concentrates in Germany, the United States, and China, with Yangtze River Delta clusters serving export markets and North Rhine-Westphalia anchoring EU formulation R&D. Raw material dependencies center on methylene diphenyl diisocyanate, polyol blends, and acrylic emulsion feedstocks. Single-source vulnerability runs through MDI supply from integrated petrochemical complexes. Distribution runs through Beacon Roofing Supply and ABC Supply in North America, with captive direct sales in German commercial contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-adhesive compatibility platforms are consolidating specification authority, creating winner-take-most dynamics where approved-system status gates market access. Interoperability requirements between TPO membrane warranties and adhesive bonding layers are shifting procurement toward integrated envelope solution providers.
For Market Incumbents: Fortify membrane manufacturer approval portfolios through parallel qualification testing with GAF, Tremco, and Sika membrane divisions. Backward integration into MDI feedstocks at Gulf Coast petrochemical hubs defends margin pools against benzene price volatility. Cold-application technician certification programs in Texas and Florida address labor supply bottlenecks that constrain peak-season volume capture. For New Entrants and Emerging Players: Differentiate on photovoltaic-integrated roofing compatibility, where bifacial solar module attachment demands thermally stable bonding layers that incumbent pure-play urethane specialists have not optimized. Target Indian commercial high-rise construction in Bangalore and Mumbai, where BIS-ISO harmonization lowers import barriers faster than domestic supply scales. Lead with hybrid polyurethane-silane technology for 24-hour cure requirements in US Southeast retail chain facilities. For Investors and Strategic Acquirers: EU Green Deal embodied carbon mandates reshape the acquisition landscape toward low-carbon formulation capabilities and lifecycle accounting expertise. Long-term viability hinges on positioning for publicly funded renovation program eligibility as carbon accounting methodologies harden. Acquisition target archetype: regional specialists with deep ASTM D6083 and D6848 test portfolios and established building envelope consultant relationships. Watch ECHA microplastic restriction implementation timelines as signal for surfacing chemistry reformulation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Feedstocks | Gulf Coast petrochemical proximity secures cost control against benzene derivative volatility squeezing polyurethane margins. |
| Membrane Manufacturer Approval Expansion | Parallel qualification with GAF, Tremco, and Sika membrane divisions gates warranty-backed specification in commercial low-slope. |
| Cold-Application Technician Certification Programs | State licensing board partnerships in Texas and Florida address peak-season labor bottlenecks constraining spray foam and adhesive volume. |
| Hybrid Polyurethane-Silane Formulation Launch | 24-hour cure positioning captures US Southeast retail chain demand for occupied building installation without disruption. |
| Photovoltaic-Integrated Roofing Compatibility Development | Thermal stability validation for bifacial solar module attachment opens Arizona and Nevada solar installation specification. |
Study Parameters
Cross-validation between primary fieldwork with roofing contractors and building envelope consultants anchors the qualitative findings against secondary validation from customs records and SEC filings. Interviews with plant managers at formulation facilities, procurement leads at membrane manufacturers, distribution channel partners at Beacon and ABC Supply, and technical R&D directors at adhesive suppliers generated demand-side and supply-side perspectives. Secondary sources included EPA enforcement actions, ECHA authorization dossiers, ASTM standard test protocols, and trade flow data. Bottom-up project pipeline analysis and top-down chemical consumption estimates triangulate market sizing.
Sensitivity analysis across MDI price scenarios, regulatory phase-in timelines, and membrane replacement cycle assumptions stress-tests projection robustness. Segmentation dimensions modeled include formulation chemistry, installation technology, building type application, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation adjusted for construction cycle inflection points. Industry-specific inputs include commercial re-roofing permit data and membrane manufacturer warranty approval list dynamics.
The analysis sits within stated boundaries; outcomes outside EU Green Deal implementation pace, REACH authorization timelines, and US regional air quality district enforcement intensity would require recalibration. Forecasts reflect documented assumptions about membrane replacement cycles, feedstock cost trajectories, and specification authority migration. Practitioners should keep alternative scenarios live as embodied carbon accounting methodologies and microplastic restriction implementations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Silicone Sealants Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
Bio-Based Adhesives Market
Adhesives & Sealants
Europe Waterborne Adhesives Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Malaysia Adhesives Market