
 Global Emulsion Adhesives Market | 2026-2036
Global Emulsion Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emulsion Adhesives Market Foresight
Packaging converters is collapsing as the dominant buyer archetype in emulsion adhesives, while furniture producers and automotive component suppliers gain procurement share. Henkel leverages its geographic footprint across European formulation plants to serve woodworking and laminating demand. BASF SE anchors acrylic emulsion supply through backward integration into monomer production, giving it cost leverage over smaller blenders. Dow competes on styrene-butadiene chemistry for paper bonding, where its Gulf Coast petrochemical network sustains feedstock reliability.
Emulsion adhesives are water-based bonding systems comprising polymer particles dispersed in aqueous continuous phases, typically with solids content ranging from 40% to 60% by weight and viscosities engineered between 500 and 5000 centipoise for roller, spray, or extrusion application. These formulations bond porous and semi-porous substrates without volatile organic compound release, serving industries where workplace air quality and flammability codes restrict solvent alternatives. Acrylic emulsions command premium positioning in textile laminating and footwear assembly due to UV stability and flexibility retention, while polyvinyl acetate remains the volume backbone of woodworking and paper bonding where cost sensitivity dominates. Polyurethane emulsions represent the fastest-expanding chemistry cluster as construction and automotive component suppliers seek structural bonds with moisture resistance and heat activation profiles that rival reactive hot-melts.
REACH registration requirements in Europe and EPA air quality standards in the United States are eliminating solvent-based alternatives from packaging and furniture production lines, directly expanding addressable demand for compliant water-based systems. China's GB standards on indoor air quality and Japan's JIS specifications for construction adhesives add compliance layers that favor established emulsion producers with testing infrastructure. Stakeholders must monitor how the EU Green Deal's embodied carbon tracking extends from raw material extraction to finished adhesive formulation, reshaping supplier qualification criteria before procurement decisions lock in for the next manufacturing cycle.
Market Dynamics
REACH registration timelines and EU Green Deal carbon accounting are compressing supplier qualification windows, forcing procurement teams to lock in compliant water-based bonding systems before solvent alternatives become unavailable.
Growth Catalysts
- REACH phase-out schedules:ECHA's sunset dates for hazardous substance authorizations are eliminating solvent-based options from European packaging lines, expanding captive demand for compliant emulsion platforms.
- Automotive lightweighting:Component suppliers in Germany and Japan are bonding composite interior panels with heat-activated polyurethane emulsions that withstand thermal cycling without VOC release.
- Construction moisture barriers:China's GB standards for indoor air quality are mandating low-emission adhesives in flooring and wallcovering installation across residential and commercial builds.
Market Restraints
- Acrylic monomer volatility:Crude-linked feedstock costs for acrylic acid and esters create margin compression for formulators lacking backward integration into monomer production.
- Freeze-thaw instability:Water-based emulsions require climate-controlled logistics chains, limiting distribution reach into regions with inadequate cold-chain infrastructure.
- Hot-melt substitution:Reactive polyurethane hot-melts are capturing structural bonding applications where rapid green strength and moisture resistance outweigh water-based environmental advantages.
Strategic Opportunities
- India construction boom:BIS certification requirements for low-VOC building materials are opening procurement channels for acrylic emulsion suppliers as domestic infrastructure spending accelerates.
- Textile digital printing:UV-curable ink adhesion to synthetic fabrics requires specialized polyurethane emulsion primers, creating premium formulation demand from sportswear manufacturers.
- EU Green Deal embodied carbon tracking:Suppliers with verified lifecycle data for raw material extraction through finished formulation gain preferential supplier status in automotive and furniture tender processes.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in colloidal stability and rheology modification for water-based systems is concentrating at established European and Japanese producers, constraining new entrant scale-up.
- Multi-standard certification burden:Simultaneous compliance with EPA Method 24, JIS K 6804, and GB 18583 testing protocols extends product launch timelines and multiplies qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emulsion Adhesives Market |
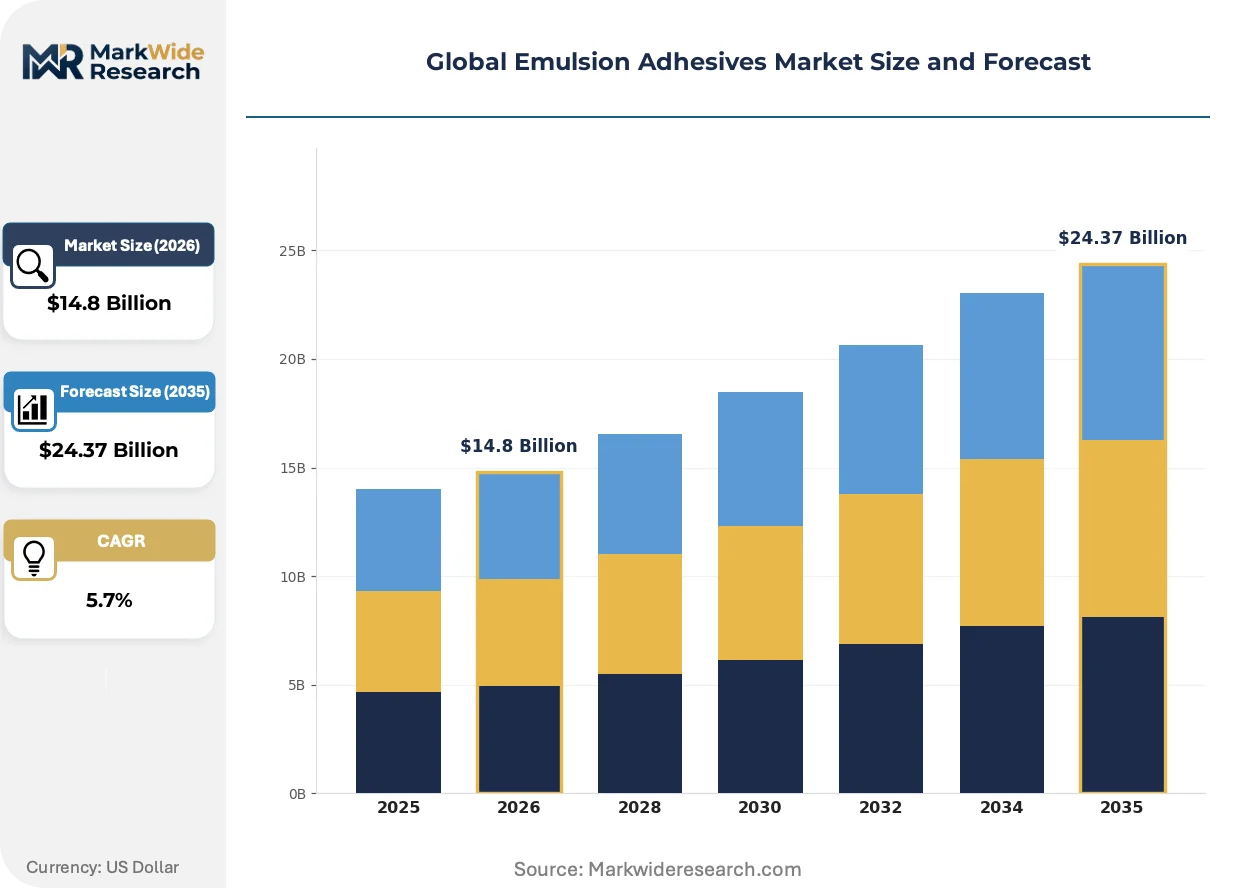
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Acetate, Styrene-Butadiene, Acrylic, Epoxy, Polyurethane Application: Woodworking, Paper Bonding, Textile Laminating, Footwear Assembly, Packaging End User Industry: Construction, Printing, Apparel Manufacturing, Automotive Component Suppliers, Furniture Production Packaging Type: Cartridges, Buckets, Drums, Pails, Totes |
| Companies Covered | Wacker Chemie AG, H.B. Fuller Company, Henkel, Ashland, 3M, Arkema, Dow, BASF SE, Pidilite Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emulsion Adhesives Market Shifts & Advancements
Formulation chemistry is diverging along performance-specialization lines as end-users reject universal adhesives in favor of substrate-optimized bonding systems with documented environmental credentials.
Hybrid acrylic-polyurethane emulsion technology is fragmenting the mid-performance adhesive segment. These copolymer systems combine UV stability with moisture resistance for outdoor signage and marine applications. Specialty laminators in Germany and South Korea are specifying hybrid platforms for membrane structures where single-chemistry alternatives fail. The technology is fragmenting procurement patterns as buyers abandon legacy one-size-fits-all specifications.
EPA air quality standards under the Clean Air Act are tightening VOC limits for consumer product adhesives, directly affecting spray-applied formulations in DIY and professional construction channels. Formulators are reducing residual monomer content and switching to zero-VOC coalescing aids to maintain shelf stability. Paper and packaging converters in the United States are accelerating water-based system adoption ahead of anticipated state-level amendments to OTC Model Rules.
Specification-driven procurement is consolidating buyer power among large furniture and automotive OEMs with dedicated adhesive engineering teams. These technical buyers are unbundling formulation supply from application equipment and technical service, pressuring traditional full-service distributors. The shift is most visible in Germany's Mittelstand woodworking sector, where purchasing cooperatives now negotiate direct supply agreements with emulsion producers.
Global Emulsion Adhesives Market Segmentation
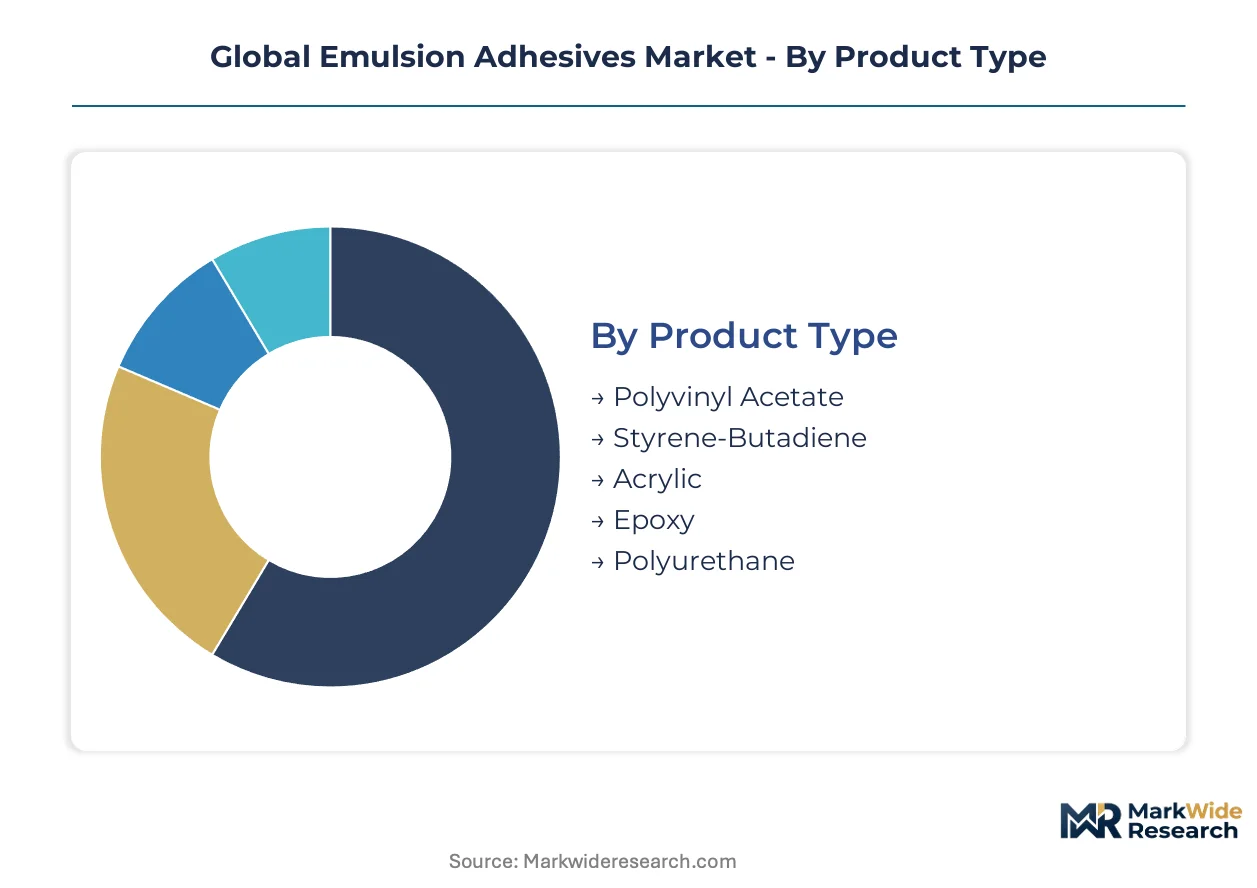
Emulsion adhesive procurement splits along chemistry-performance lines and packaging logistics. Buyers optimize formulation selection against substrate compatibility, regulatory compliance burdens, and cold-chain distribution constraints.
Product Type:
Channel mix varies sharply by chemistry—polyvinyl acetate moves through mass distribution to woodworking shops, while polyurethane emulsions route through technical specialists serving automotive and construction accounts.
- Polyvinyl Acetate:Vinyl acetate monomer polymerized in aqueous dispersion yields 45-55% solids content with fast set speed on porous cellulosic substrates. Demand concentrates in German and Chinese furniture manufacturing where cost sensitivity dominates bonding decisions for panel assembly and edge banding. REACH-compliant low-formaldehyde grades command modest premiums over standard formulations.
- Polyurethane:Aliphatic and aromatic polyurethane dispersions provide structural bonds with heat activation and moisture resistance rivaling reactive hot-melts. Automotive component suppliers in Germany and Japan specify these for composite interior panel laminating where thermal cycling durability is mandatory. Construction moisture barrier applications in China are accelerating procurement under GB indoor air quality standards.
- Acrylic:UV-stable copolymers serve textile laminating and outdoor signage with flexibility retention across temperature extremes.
- Styrene-Butadiene:Carboxylated SBR latex dominates paper bonding and carpet backing where low cost and high filler tolerance matter.
- Epoxy:Waterborne epoxy dispersions penetrate industrial maintenance coatings and structural composites requiring chemical resistance.
By volume, polyvinyl acetate leads. By growth pace, polyurethane is climbing the fastest.
Application:
Cost tier stratification separates commodity bonding from specification-driven laminating—paper and woodworking sit at economy pricing while textile and automotive applications support premium formulation margins.
- Woodworking:Edge banding, panel assembly, and veneer laminating consume emulsion adhesives in continuous roller and extrusion application. German Mittelstand furniture producers and Chinese export manufacturers drive procurement volume, with specification tightening around formaldehyde emission limits under CARB ATCM and EN 13986. Polyvinyl acetate dominates; polyurethane gains share in moisture-resistant kitchen and bathroom applications.
- Textile Laminating:Synthetic fabric bonding for sportswear, protective equipment, and automotive interiors requires soft hand, wash durability, and heat resistance. German and South Korean specialty laminators specify hybrid acrylic-polyurethane systems for membrane structures. UV-curable ink adhesion primers for digital textile printing represent an emerging premium sub-segment.
- Paper Bonding:Corrugated board manufacture and paper sack construction rely on starch-emulsion blends and SBR latex for speed and cost efficiency.
- Footwear Assembly:Upper-to-sole bonding and lining attachment use flexible acrylic and polyurethane emulsions with heat reactivation capability.
- Packaging:Folding carton and flexible packaging converters are switching from solvent systems to water-based platforms under EPA Method 24 and EU VOC directives.
Woodworking generates the largest absolute volume. Textile laminating shows the steepest expansion trajectory as technical performance requirements intensify.
End User Industry:
Customer type determines procurement sophistication—automotive and furniture OEMs employ dedicated adhesive engineering teams, while construction and printing buyers rely on distributor technical service.
- Construction:Flooring installation, wallcovering, and moisture barrier applications specify low-emission emulsion adhesives under tightening indoor air quality regimes. China's GB 18583 and Japan's JIS A 6920 constrain formulation choices. BIS certification requirements in India are opening procurement channels as infrastructure spending accelerates.
- Automotive Component Suppliers:Interior panel laminating, headliner assembly, and composite bonding demand heat-activated polyurethane emulsions with documented lifecycle carbon data. German suppliers face EU Green Deal embodied carbon tracking requirements extending from raw material extraction through finished formulation.
- Furniture Production:Panel furniture and upholstered goods manufacturing in Germany, Poland, and China drives polyvinyl acetate consumption with formaldehyde emission compliance as a qualifier threshold.
- Printing:Label and packaging print applications use emulsion adhesives for laminating and varnishing with low odor and food-contact compliance.
- Apparel Manufacturing:Sportswear and outdoor gear producers specify specialized polyurethane emulsion primers for digital printing adhesion and seam sealing.
Construction commands the highest tonnage. Automotive component supply is gaining share fastest as lightweighting and interior air quality specifications tighten.
Packaging Type:
Volume scale and logistics infrastructure dictate packaging selection—bulk totes and drums serve integrated manufacturers while cartridges and pails reach fragmented trade channels.
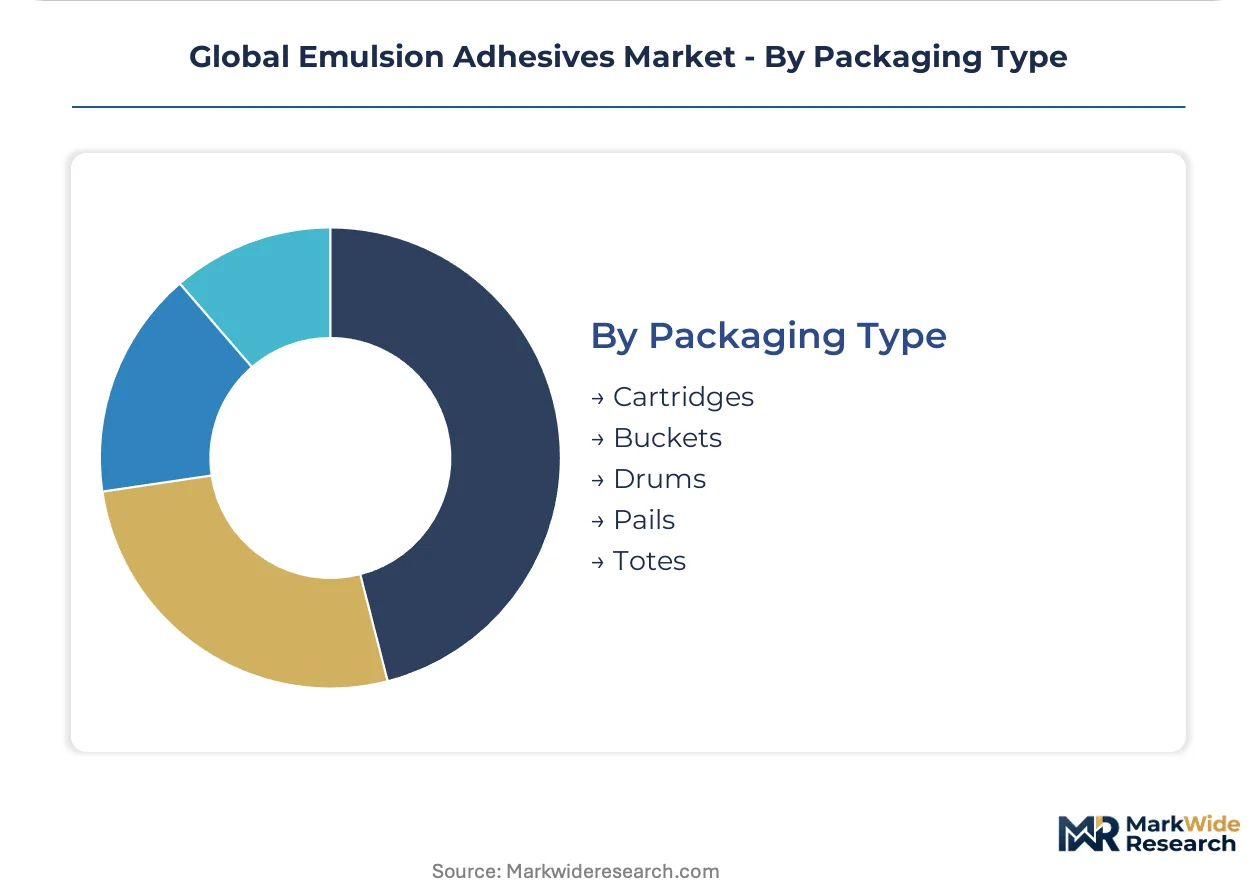
- Drums:200-liter steel and plastic drums dominate industrial procurement for woodworking and automotive plants with continuous consumption and bulk storage capability. Climate-controlled warehousing addresses freeze-thaw stability requirements.
- Totes:Intermediate bulk containers serve large packaging converters and construction material distributors with reduced handling cost per kilogram. German and US Gulf Coast logistics hubs concentrate tote-based supply.
- Buckets:20-25 liter polyethylene pails reach mid-scale furniture manufacturers and professional flooring installers through distributor networks.
- Cartridges:300-600ml cartridges serve professional construction and repair applications requiring precise application control.
- Pails:5-10 liter containers bridge industrial and trade channels for smaller woodworking and paper bonding accounts.
Drums lead by volume moved. Totes are expanding most quickly as procurement consolidates among large integrated manufacturers seeking handling efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation capacity clusters in Germany, China, and the United States, with specialized production of acrylic and polyurethane dispersions serving distinct regional compliance regimes. REACH phase-outs in Europe, GB standards in China, and EPA enforcement in North America create divergent qualification timelines that shape local competitive dynamics.
Germany
Automotive component suppliers in Bavaria and Baden-Württemberg specify heat-activated polyurethane emulsions for composite interior panel bonding. ECHA sunset dates for hazardous substance authorizations eliminate solvent-based alternatives from packaging lines. The Mittelstand woodworking sector around Stuttgart and Bielefeld drives polyvinyl acetate procurement with formaldehyde emission limits tightening under EN 13986.
China
Construction moisture barrier applications in the Yangtze River Delta and Pearl River Delta accelerate under GB 18583 indoor air quality mandates. Furniture export manufacturers in Guangdong and Zhejiang switch from solvent systems to water-based platforms for EU and US market access. The dual carbon goals framework pressures domestic formulators to document embodied carbon from monomer extraction through finished goods.
United States
Packaging converters in Wisconsin and Pennsylvania adopt water-based systems ahead of anticipated state-level amendments to OTC Model Rules. EPA Method 24 testing protocols determine VOC compliance for folding carton and flexible packaging applications. The Gulf Coast petrochemical corridor sustains styrene-butadiene latex supply for paper bonding and carpet backing.
Japan
Automotive interior laminators in Aichi Prefecture specify polyurethane emulsions with documented lifecycle carbon data for thermal cycling durability. METI guidance on construction material emissions reinforces JIS A 6920 compliance for flooring and wallcovering adhesives. Specialty laminators in Osaka and Nagoya drive hybrid acrylic-polyurethane formulation demand for membrane structures.
India
Infrastructure spending in Maharashtra and Gujarat opens procurement channels for acrylic emulsion suppliers as BIS certification requirements for low-VOC building materials take effect. Domestic furniture manufacturing in Tamil Nadu and Karnataka expands water-based bonding capacity for export compliance. Construction activity in Delhi-NCR and Hyderabad drives moisture barrier adhesive specification under tightening indoor air quality norms.
Global Emulsion Adhesives Market Competitive Landscape
Concentration sits with diversified chemical conglomerates controlling monomer supply and formulation expertise. Three tiers structure competitive positioning: integrated petrochemical players with backward integration into acrylic acid and polyurethane precursors; regional formulators serving woodworking and construction accounts through distributor networks; and specialty laminating suppliers focused on automotive and textile applications. Capacity expansion and portfolio diversification dominate strategic moves, with players adding hybrid chemistry platforms and securing multi-standard certification infrastructure.
Among European-based chemical conglomerates, Wacker Chemie AG, BASF SE, and Henkel occupy positions spanning monomer production through formulated adhesives. H.B. Fuller Company represents North American formulator archetypes with technical service capabilities in packaging and woodworking channels. Dow anchors styrene-butadiene chemistry supply through Gulf Coast feedstock integration. Arkema and Ashland exemplify specialty chemical positioning with focused portfolios in pressure-sensitive and industrial adhesives. 3M sits within diversified technology conglomerates leveraging application engineering capabilities. Pidilite Industries Ltd represents emerging market formulators building regional distribution density in construction and consumer DIY segments.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| H.B. Fuller Company |
| Henkel |
| Ashland |
| 3M |
| Arkema |
| Dow |
| BASF SE |
| Pidilite Industries Ltd |
| Others |
Supply & Pricing Matrix
REACH registration deadlines and EU Green Deal embodied carbon tracking gate both supplier qualification and price differentiation simultaneously, compressing procurement windows while segmenting formulations into compliance-premium tiers based on lifecycle documentation depth.
Pricing Analysis
REACH phase-out schedules dictate the pricing tier structure across the European market, separating premium polyurethane emulsions with full ECHA dossier compliance from standard acrylic formulations and economy-grade polyvinyl acetate alternatives. Price differentiation rests on certification grade—suppliers with verified carbon footprint data command 15-25% premiums in automotive tenders—and volume scale, with bulk tote procurement from integrated manufacturers undercutting distributor-delivered pails. Pricing pressure stems from acrylic monomer volatility linked to crude derivatives, squeezing margins for formulators lacking backward integration into monomer production. Woodworking accounts in Germany and China show highest price sensitivity, while automotive component suppliers in Bavaria prioritize thermal cycling performance over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability fluctuations at Rotterdam and Hamburg elevate inbound logistics costs for acrylic acid and specialty polyurethane precursors sourced from Gulf Coast and Northeast Asian petrochemical hubs. Geographic supply concentrates in Germany, China, and the United States, with BASF SE and Wacker Chemie AG anchoring European formulation capacity while Dow's Gulf Coast network sustains styrene-butadiene latex feedstock. Raw material dependencies center on vinyl acetate monomer, acrylic acid esters, and aromatic isocyanates. Single-source vulnerability for aliphatic polyurethane dispersions from Japanese specialty producers creates qualification risk. Distribution runs through climate-controlled warehousing networks serving drum and tote formats to integrated manufacturers, with pails and cartridges reaching fragmented trade channels via technical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized colloidal stability expertise and multi-standard certification infrastructure represent scarce capabilities that constrain new entrant scale-up while rewarding incumbents with documented compliance histories across REACH, EPA Method 24, and GB 18583 protocols.
For Market Incumbents: Compound defensive positioning by securing captive acrylic acid supply through backward integration or long-term offtake agreements with petrochemical partners, insulating margins from feedstock volatility. Expand certification infrastructure to cover India's BIS requirements and Japan's JIS A 6920 amendments ahead of competitor qualification, locking in automotive and construction procurement channels before regulatory deadlines eliminate solvent alternatives. For New Entrants and Emerging Players: BIS certification fast-tracks for low-VOC construction adhesives open procurement channels in Maharashtra and Gujarat as infrastructure spending accelerates. Target textile digital printing primers for sportswear manufacturers in South Korea and Germany, where hybrid acrylic-polyurethane specification gaps exist between established laminators and commodity suppliers. Partner with regional distributors possessing climate-controlled logistics to overcome freeze-thaw stability barriers in underserved markets. For Investors and Strategic Acquirers: EU Green Deal carbon accounting milestones reshape the acquisition landscape toward suppliers with verified lifecycle data and backward-integrated monomer positions. Prioritize mid-cap formulators with established REACH dossiers and automotive qualification histories over commodity woodworking players facing margin compression. Monitor ECHA sunset date announcements as inflection indicators for accelerated consolidation among distributors lacking technical service capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive monomer supply insulates BASF SE and integrated players from crude-linked feedstock volatility. |
| Multi-Standard Certification Infrastructure | Simultaneous EPA Method 24, REACH, and GB 18583 compliance accelerates product launch timelines for qualified formulators. |
| Climate-Controlled Distribution Expansion | Cold-chain warehousing investments extend emulsion adhesive reach into regions with inadequate logistics infrastructure. |
| Hybrid Chemistry Platform Development | Acrylic-polyurethane copolymer systems capture premium positioning in outdoor signage and marine membrane applications. |
| Lifecycle Carbon Documentation Systems | Verified embodied carbon tracking secures preferential supplier status under EU Green Deal procurement criteria. |
Research Methodology
Desk research of customs trade databases, ECHA registration filings, and SEC 10-K disclosures preceded structured interviews with adhesive formulation chemists, automotive Tier 1 procurement managers, furniture manufacturing plant directors, and construction material distributors. Primary fieldwork captured specification evolution, qualification timeline compression, and procurement pattern shifts across German Mittelstand woodworking cooperatives and Chinese export manufacturers. Secondary validation drew from ACC and Cefic industry reports, BIS certification registries, and EPA enforcement action records. Bottom-up demand modeling triangulated against top-down chemical consumption estimates.
Variance decomposition across chemistry type, application performance tier, packaging format, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product chemistry, end-use industry, and customer procurement sophistication level. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection timing and substitution elasticity between water-based and solvent systems. Industry-specific forecast inputs incorporated automotive lightweighting content per vehicle trends and construction moisture barrier specification tightening under evolving indoor air quality mandates.
Underlying assumptions cover REACH sunset date adherence, continued acrylic monomer price correlation with crude derivatives, and cold-chain logistics infrastructure expansion in target markets, with deviation risk concentrated in regulatory delay, hot-melt substitution acceleration, and feedstock supply disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Middle East and Africa Flock Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Water Based Adhesive Market