
 Global Adhesion Barrier Market | 2026-2036
Global Adhesion Barrier Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adhesion Barrier Market Foresight
Aftermarket service revenue from adhesion barrier training and surgical support is tilting toward integrated device vendors. Johnson & Johnson leverages its broad surgical portfolio to bundle barrier products with stapling and energy platforms. Baxter International anchors its position through deep distribution into hospital operating rooms across North America and Europe. Integra LifeSciences Holdings Corporation specializes in regenerative tissue applications that extend barrier utility into complex reconstructive procedures.
An adhesion barrier is a biocompatible implantable material, typically formulated from hyaluronic acid, carboxymethyl cellulose, or polylactic acid, that mechanically separates tissues during the critical healing window to prevent fibrous scar formation. Films dominate current surgical practice due to their established handling characteristics and predictable resorption profiles, while gel formulations capture expanding share in laparoscopic and minimally invasive settings where spray application proves technically challenging. Hyaluronic acid-based compositions lead material demand owing to their native biocompatibility and lower inflammatory potential, though synthetic polymer blends gain traction where extended barrier duration is clinically indicated.
FDA 510(k) premarket notification requirements and the EU MDR conformity assessment process govern product commercialization, with both frameworks intensifying clinical evidence demands for novel barrier formulations. The EPA regulates manufacturing waste streams for solvent-based film casting processes, particularly at facilities in the United States. Surgeons, procurement officers, and product developers must track evolving reimbursement coding for spray versus film delivery methods as payer differentiation hardens.
Market Dynamics
EU MDR conformity assessment timelines are compressing product entry windows and forcing manufacturers to front-load clinical evidence generation before commercialization, fundamentally restructuring how barrier technologies reach surgical suites.
Growth Catalysts
- EU MDR Article 120 transition extensions:Legacy device certifications now require earlier renewal submissions, pulling forward replacement purchases of next-generation barriers.
- Laparoscopic procedural volume expansion:Spray-applied gel formulations capture share as minimally invasive abdominal surgeries displace open procedures in tertiary hospitals.
- Hyaluronic acid supply chain maturation:Fermentation-based production scaling in South Korea and Japan reduces raw material cost volatility for film manufacturers.
Market Restraints
- Clinical evidence thresholds:FDA 510(k) pathways now demand larger comparator-arm studies for novel synthetic polymer blends, extending development cycles.
- Single-source sodium hyaluronate dependence:Three contract manufacturers in Germany control pharmaceutical-grade supply, concentrating input risk.
- Autologous tissue flap substitution:Omentum and peritoneal graft techniques persist in cost-constrained healthcare systems, capping barrier penetration.
Strategic Opportunities
- Brazilian ANVISA fast-track pathway:Streamlined review for devices with prior FDA or EMA clearance enables earlier Latin American market entry.
- Robotic surgical platform integration:Barrier gel applicators designed for da Vinci instrument compatibility open procedural expansion in urologic and gynecologic specialties.
- Japan PMDA regenerative medicine framework:Cell-seeded barrier hybrids qualify for conditional approval with smaller pivotal trials, accelerating commercialization.
Industry Challenges
- Sterile manufacturing capacity constraints:Lyophilization suite availability at contract facilities in Ireland and Switzerland bottlenecks film production scaling.
- Bioresorption rate standardization gaps:ISO 10993 subcommittee deliberations on in vivo testing protocols delay harmonized shelf-life claims across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adhesion Barrier Market |
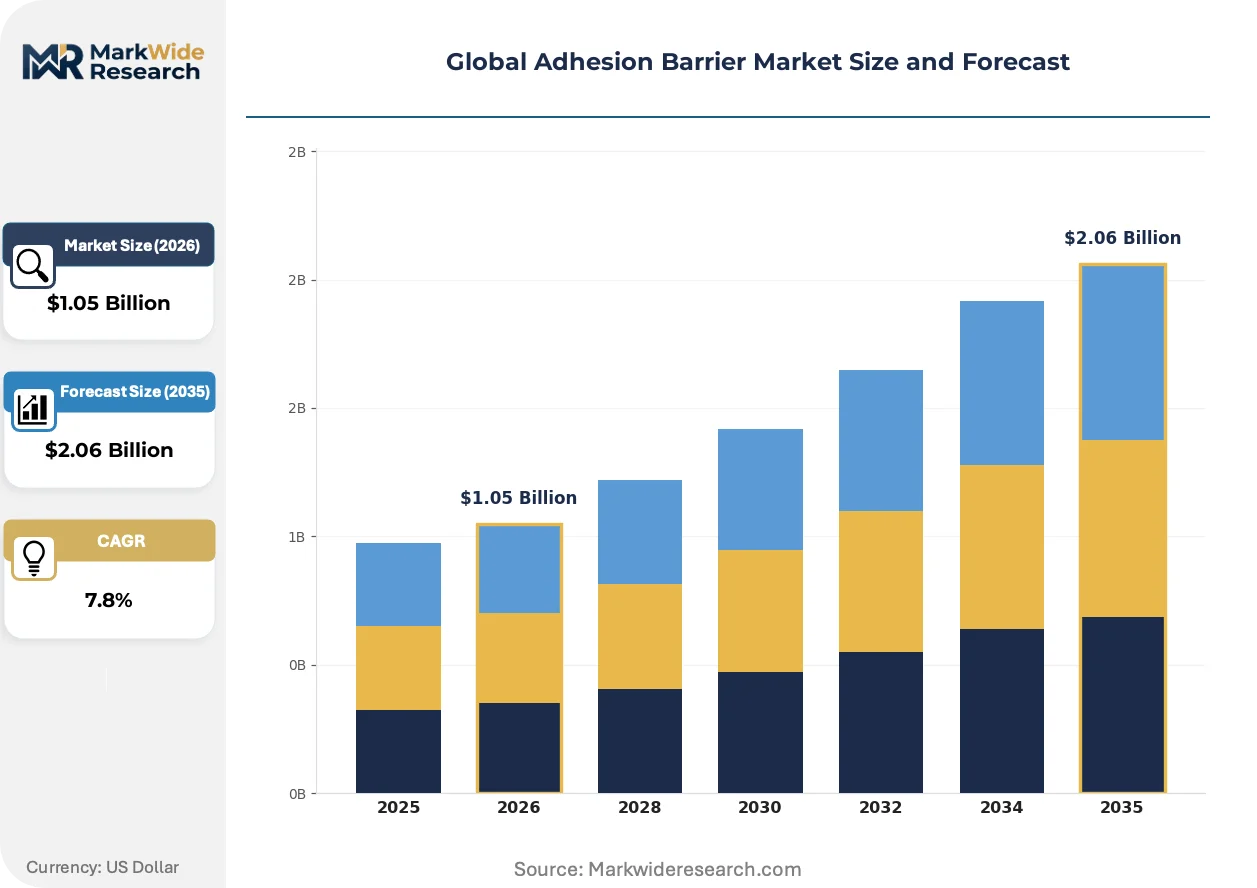
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Sprays, Gels, Solutions, Powders Application: Gynecology, General Surgery, Orthopedic, Cardiovascular, Neurosurgery End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Institutes Material Composition: Hyaluronic Acid, Carboxymethyl Cellulose, Polylactic Acid, Gelatin, Collagen |
| Companies Covered | Johnson & Johnson, Baxter International, Integra LifeSciences Holdings Corporation, Anika Therapeutics, Leader Biomedical, Atrium Medical Corporation, Becton Dickinson and Company, FzioMed, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adhesion Barrier Market Shifts & Advancements
Spray application systems are displacing manual film placement in minimally invasive procedures, while regulatory frameworks on both sides of the Atlantic tighten evidentiary requirements for novel bioresorbable materials.
Electrospun nanofiber matrices with tunable pore architectures are rendering obsolete conventional cast films in complex pelvic reconstructive applications. Tertiary academic medical centers in Germany and the United States have adopted these constructs for multilayer adhesion prevention. The technology is rendering obsolete standardized 14-day barrier duration assumptions, enabling patient-matched resorption profiles.
REACH Annex XIV authorization requirements for solvent residues in polymer casting processes are forcing manufacturing relocations from European facilities to EPA-regulated sites in the United States. Film producers face reformulation costs or supply chain reconfiguration. Small-batch specialty manufacturers in Switzerland are absorbing compliance costs through premium positioning rather than volume scaling.
Hospital procurement consortiums are consolidating barrier purchasing through integrated delivery networks, displacing individual surgeon preference contracting. Group purchasing organizations in the United States now mandate standardized film-versus-gel formularies based on robotic surgery compatibility. This concentration is most visible in the southeastern United States, where IDN expansion has compressed vendor counts from twelve to four in three years.
Global Adhesion Barrier Market Segmentation
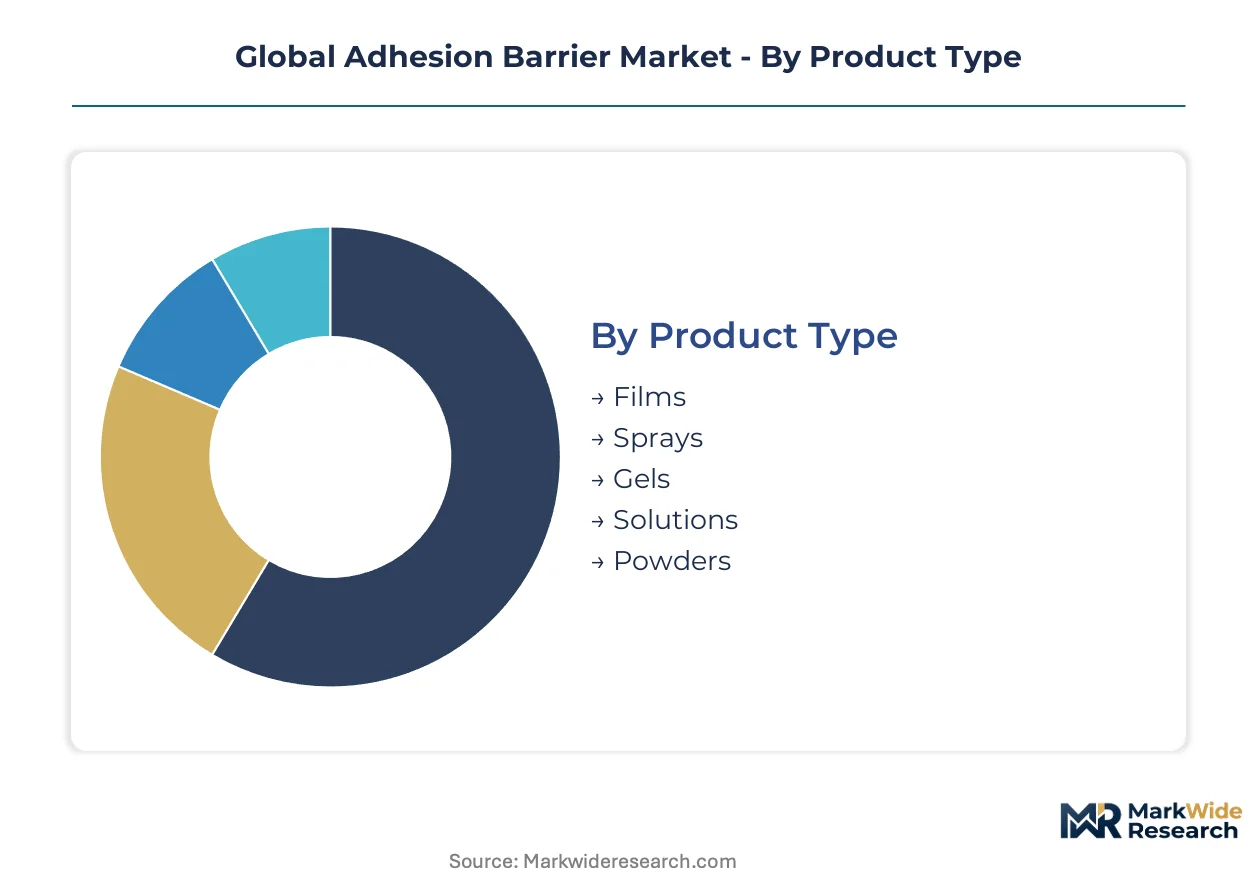
Adhesion barrier segmentation reveals how formulation chemistry, surgical application, and care setting interact to determine purchasing patterns. Manufacturers configure product portfolios across these dimensions to match reimbursement codes and procedural workflows.
Product Type:
Cost tiers separate established film technologies from premium spray and gel delivery systems.
- Films:Cast polymer sheets of hyaluronic acid or carboxymethyl cellulose provide predictable 7-14 day barrier duration with standardized handling. Demand concentrates in open abdominal procedures at tertiary hospitals in Germany and the United States where surgeons prioritize tactile placement control.
- Sprays:Aerosolized gel formulations enable laparoscopic application through trocar ports, eliminating manual unfolding in confined spaces. Adoption accelerates in minimally invasive gynecologic suites across Japan and South Korea where robotic surgery penetration is highest.
- Gels:Viscous liquid barriers conform to irregular tissue surfaces without fixation sutures. Usage is expanding in pelvic reconstructive applications.
- Solutions:Dilute instillates for irrigation during closure. Penetration remains limited to specific cardiac protocols.
- Powders:Lyophilized particulates reconstituted intraoperatively. Niche positioning in research settings.
Films command the established base. The steepest expansion runs through Sprays.
Application:
Procedure volume and reimbursement generosity determine which surgical specialties absorb barrier inventory fastest.
- Gynecology:Myomectomy and endometriosis excision drive consistent demand as fertility-preserving surgery expands. Tertiary centers in the United States and Japan prioritize hyaluronic acid films for uterine cavity protection.
- General Surgery:Colorectal resection and hernia repair generate the largest absolute procedure counts. Spray formulations gain traction in laparoscopic colectomy across European university hospitals.
- Orthopedic:Tendon and peripheral nerve wrapping applications utilize collagen-based matrices. Demand clusters in sports medicine centers.
- Cardiovascular:Pericardial and pleural barrier placement follows coronary bypass and valve replacement. Volume ties to cardiac surgery program scale.
- Neurosurgery:Dural substitutes and laminectomy site protection require extended resorption profiles. Synthetic polymer blends dominate this segment.
General Surgery absorbs the highest unit volume. Gynecology is climbing the fastest as fertility-sparing procedures multiply.
End User:
Customer type dictates purchasing authority, formulary constraints, and training requirements.
- Hospitals:Integrated delivery networks in the southeastern United States and NHS trusts in England consolidate barrier procurement through standardized formularies. Film-versus-gel decisions now flow through value analysis committees rather than individual surgeons.
- Ambulatory Surgery Centers:Freestanding facilities in Germany and the Netherlands favor pre-cut film formats to minimize OR turnover time. Reimbursement compression limits premium product adoption.
- Specialty Clinics:Gynecologic and orthopedic-focused centers in Japan maintain surgeon-directed purchasing for complex reconstructive cases.
- Research Institutes:Academic medical centers in Switzerland and the United States evaluate next-generation electrospun matrices under institutional review protocols.
Hospitals anchor procurement volume. Ambulatory Surgery Centers are expanding most quickly as procedure migration accelerates.
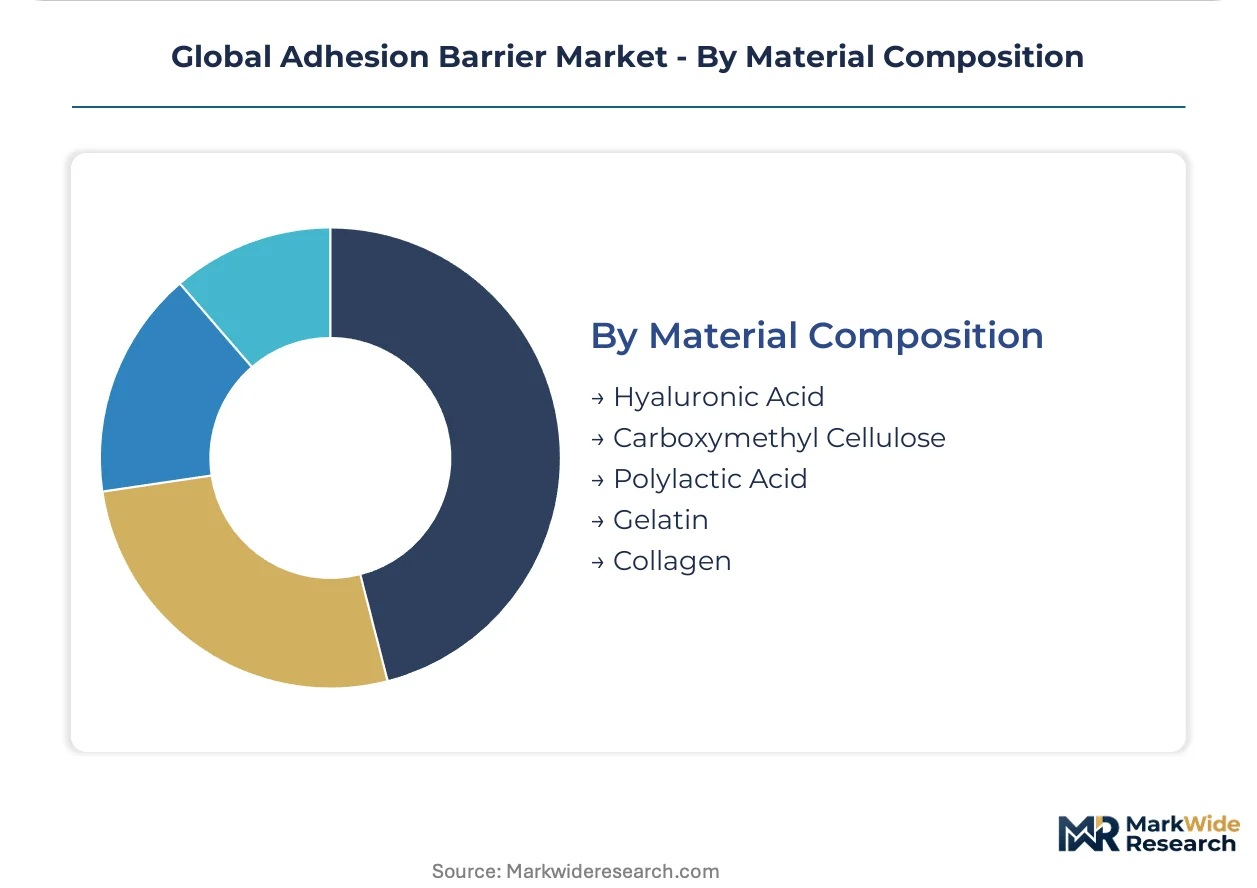
Material Composition:
Supply concentration and biocompatibility profiles differentiate raw material tiers.
- Hyaluronic Acid:Fermentation-derived pharmaceutical-grade sodium hyaluronate from South Korean and Japanese suppliers dominates film production. Native tissue compatibility minimizes inflammatory response in peritoneal applications.
- Carboxymethyl Cellulose:Semisynthetic cellulose derivatives offer cost-advantaged alternatives with tunable viscosity. Demand concentrates in high-volume general surgery applications where reimbursement is tightest.
- Polylactic Acid:Synthetic polyester barriers provide extended 4-6 week protection for slow-healing orthopedic and neurosurgical sites.
- Gelatin:Denatured collagen matrices from bovine or porcine sources serve cost-sensitive markets with shorter duration requirements.
- Collagen:Native extracellular matrix scaffolds support cell infiltration in regenerative applications. Premium positioning in complex reconstructive procedures.
Hyaluronic Acid retains the largest installed base. Polylactic Acid is gaining share fastest where extended barrier duration justifies synthetic polymer pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrier consumption patterns diverge sharply by geography: the United States favors spray-applied gels for robotic surgery integration, while Germany and Japan maintain film dominance in open abdominal procedures. These modality preferences reshape how manufacturers configure regional product portfolios.
United States
Integrated delivery networks in the southeastern states consolidate procurement through standardized formularies, compressing vendor counts from twelve to four since 2022. FDA 510(k) clearance pathways govern product entry, with larger comparator-arm studies now required for novel synthetic polymer blends. The Boston-Cambridge corridor anchors regenerative medicine research, where academic medical centers evaluate electrospun nanofiber matrices under institutional review protocols.
Germany
Tertiary university hospitals in Bavaria and North Rhine-Westphalia drive film demand for open colorectal and gynecologic procedures, prioritizing tactile placement control. EU MDR conformity assessment timelines compress product entry windows, forcing manufacturers to front-load clinical evidence generation. Three contract manufacturers in southern Germany control pharmaceutical-grade sodium hyaluronate supply, concentrating input risk for film producers.
Japan
Fertility-preserving myomectomy and endometriosis excision propel hyaluronic acid film adoption in Tokyo and Osaka metropolitan surgical suites. PMDA's regenerative medicine framework enables conditional approval for cell-seeded barrier hybrids with smaller pivotal trials. The Kansai region hosts fermentation-based sodium hyaluronate production facilities that supply raw material across Asia-Pacific film manufacturing networks.
South Korea
Laparoscopic procedural volume expansion in Seoul and Busan accelerates spray-applied gel capture share as minimally invasive abdominal surgeries displace open procedures. MFDS regulatory alignment with FDA pathways streamlines market entry for devices with prior US clearance. Domestic fermentation capacity for pharmaceutical-grade hyaluronate reduces raw material cost volatility for regional film manufacturers.
Brazil
Cost-constrained public health systems in São Paulo and Rio de Janeiro sustain autologous tissue flap substitution using omentum and peritoneal graft techniques, capping barrier penetration. ANVISA fast-track pathways for devices with prior FDA or EMA clearance enable earlier commercialization. Private hospital networks in southeastern states represent the addressable premium segment for imported barrier technologies.
Global Adhesion Barrier Market Competitive Landscape
Capability concentration sits with specialized regenerative medicine developers; scale advantage sits with diversified surgical portfolio holders. The market structure tiers across three distinct player categories: integrated surgical conglomerates with broad stapling and energy platforms, mid-cap specialists focused on tissue regeneration applications, and regional contract manufacturers supplying pharmaceutical-grade raw materials. Dominant competitive moves include strategic bundling of barrier products with complementary surgical devices and backward integration into sodium hyaluronate fermentation capacity.
Within the integrated surgical tier, Johnson & Johnson and Baxter International exemplify scale-driven positioning through deep operating room distribution networks across North America and Europe. Integra LifeSciences Holdings Corporation occupies a specialist position, representing the regenerative medicine archetype with concentrated expertise in complex reconstructive applications. These three anchors demonstrate how competitive positioning splits between portfolio breadth and clinical specialization depth.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Baxter International |
| Integra LifeSciences Holdings Corporation |
| Anika Therapeutics |
| Leader Biomedical |
| Atrium Medical Corporation |
| Becton Dickinson and Company |
| FzioMed |
| Sanofi |
| Others |
Supply & Pricing Matrix
Lyophilization suite undercapacity at contract facilities in Ireland and Switzerland is compressing film production scaling and forcing manufacturers toward premium positioning rather than volume competition. This utilization squeeze simultaneously elevates input costs for standard-grade barriers while concentrating margin capture among small-batch specialty producers with locked-in sterile manufacturing access.
Pricing Analysis
Long-term offtake agreements for pharmaceutical-grade sodium hyaluronate dominate raw material procurement, insulating large film manufacturers from spot price volatility while locking smaller competitors into less favorable contract terms. Three-tier pricing structure across premium electrospun matrices, standard cast films, and economy gelatin-based alternatives reflects certification grade and barrier duration claims. Cost compression in the economy tier is intensifying because autologous tissue flap substitution persists in cost-constrained healthcare systems. Ambulatory surgery centers in Germany and the Netherlands exhibit the highest price sensitivity due to reimbursement compression, while tertiary academic medical centers in the United States and Japan absorb premium pricing for patient-matched resorption profiles.
Supply Chain Analysis
Tariff exposure between the United States and China in medical device component trade dominates supply chain risk planning for barrier applicator manufacturers. Sodium hyaluronate fermentation capacity concentrates in South Korea and Japan, while pharmaceutical-grade purification and lyophilization capacity clusters in Germany, Ireland, and Switzerland. Raw material dependencies center on fermentation-derived hyaluronic acid, synthetic polylactic acid resins, and cellulose derivatives for carboxymethyl cellulose production. Single-source vulnerability at three German contract manufacturers controlling pharmaceutical-grade sodium hyaluronate supply concentrates input risk for film producers. Distribution runs through integrated delivery networks in the United States and NHS trusts in England, displacing individual surgeon preference contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement authorities as integrated delivery networks in the southeastern United States compress vendor counts from twelve to four. This consolidation fragments pricing leverage for manufacturers while concentrating formulary control among value analysis committees.
For Market Incumbents: Build regulatory evidence moats through preemptive EU MDR Article 120 renewal submissions and expanded comparator-arm studies for novel synthetic polymer blends. Deepen backward integration into sodium hyaluronate fermentation capacity in South Korea or Japan to escape single-source German contract manufacturer dependence. Channel control through robotic surgical platform integration with da Vinci-compatible gel applicators defends against spray formulation commoditization. For New Entrants and Emerging Players: Establish a beachhead in Brazilian private hospital networks through ANVISA fast-track pathways for devices with prior FDA or EMA clearance. Target Japan's PMDA regenerative medicine framework for cell-seeded barrier hybrids, where conditional approval with smaller pivotal trials accelerates commercialization. A go-to-market angle anchored in electrospun nanofiber technology for complex pelvic reconstructive applications bypasses entrenched film competition in general surgery. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap regenerative medicine specialists with concentrated expertise in tissue engineering and existing hospital system partnerships. Long-term viability hinges on differentiation through patient-matched resorption profiles rather than commodity barrier duration claims. The signal to watch is FDA 510(k) pathway evolution for novel bioresorbable materials, where larger comparator-arm study requirements will separate evidence-rich platforms from undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways now demand larger comparator-arm studies for synthetic polymer blends. |
| CE Marking Pathway | EU MDR conformity assessment timelines compress product entry windows for film manufacturers. |
| Hospital System Partnership | Integrated delivery networks in the United States consolidate procurement through standardized formularies. |
| Backward Integration | Fermentation capacity acquisition in South Korea or Japan reduces sodium hyaluronate input risk. |
| Reimbursement Strategy | Payer differentiation between spray and film delivery methods shapes formulary positioning. |
Research Methodology
The analysis maps film, spray, gel, solution, and powder formulation sub-sectors, each validated through operating room procurement officers, biomedical engineers, GPO contracts managers, and regulatory affairs specialists. Primary interviews with hospital value analysis committees and secondary validation through FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data inform segment sizing. Bottom-up triangulation across material composition, application specialty, and end-user channel overlays with top-down macroeconomic boundary conditions.
Assumption sets held regulatory pathway timelines and reimbursement coding evolution fixed while varying procedural volume trajectories and raw material cost scenarios across the projection horizon. Segmentation dimensions modeled include product type, application specialty, end-user channel, and material composition, with regional regulatory cluster effects layered across geographies. CAGRs derive from procedure volume elasticity to demographic aging, surgical robot installation rates, and barrier penetration by procedure type. Forecast inputs center on lyophilization capacity utilization at contract facilities and fermentation yield improvements for pharmaceutical-grade sodium hyaluronate.
Sensitivities concentrate around EU MDR transition timeline extensions, FDA evidentiary requirement shifts for novel bioresorbable materials, and sterile manufacturing capacity expansion delays in Ireland and Switzerland. Forecasts reflect these documented assumptions with explicit scenario boundaries. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Firestop Sealants Market
Adhesives & Sealants
Europe Waterborne Adhesives Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Conductive Adhesive Market