
 Rubber-Based Adhesives Market | 2026-2036
Rubber-Based Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber-Based Adhesives Market Intelligence
Southeast Asian petrochemical producers is recalibrating synthetic rubber output as feedstock volatility reshapes adhesive raw material economics. Henkel AG & Co. KGaA leverages its European R&D footprint to dominate high-performance automotive bonding applications. 3M Company sustains technology leadership in pressure-sensitive adhesive tapes through proprietary polymer synthesis capabilities.
Rubber-based adhesives comprise elastomeric compounds—natural rubber, styrene-butadiene, or nitrile—formulated with tackifiers and curing agents to deliver flexible, high-peel-strength bonds across dissimilar substrates. Solvent-based technology retains manufacturing scale advantages in heavy-duty industrial bonding despite tightening emissions rules. Water-based formulations capture packaging and footwear demand as converters seek lower-VOC alternatives. Pressure sensitive adhesives occupy the fastest-expanding application niche, driven by label and tape consumption in e-commerce logistics.
EPA regulations in the US limit hazardous air pollutants from adhesive coating operations, compelling facility upgrades and formulation changes. REACH and the EU Green Deal accelerate substitution of petrochemical-derived tackifiers with bio-based alternatives in European supply chains. Stakeholders must monitor polymer feedstock cost trajectories and regional compliance divergence to optimize manufacturing location and product portfolio decisions.
Market Dynamics
The rubber-based adhesives sector is experiencing fundamental restructuring as automotive OEMs accelerate lightweight vehicle assembly programs and regulatory frameworks tighten volatile organic compound limits across manufacturing jurisdictions.
Growth Catalysts
- EV Platform Expansion:Electric vehicle manufacturers in China are scaling adhesive-intensive battery pack bonding and thermal management assembly, creating concentrated demand for high-temperature-resistant formulations.
- REACH Phase-Down Mandates:The EU Green Deal's VOC reduction timeline is compelling converters toward water-based alternatives, expanding addressable market for compliant rubber adhesive suppliers.
- E-Commerce Logistics Surge:Pressure-sensitive adhesive consumption for shipping labels and protective tapes is accelerating across fulfillment networks in Germany and the United States.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic rubber monomer costs fluctuate with naphtha and butadiene pricing, compressing margin stability for solvent-based formulation producers.
- Southeast Asian Supply Concentration:Natural rubber latex sourcing clusters in Thailand and Indonesia create geographic vulnerability to climate-related harvest disruptions.
- Curing Speed Limitations:Water-based rubber adhesives require extended drying cycles versus solvent systems, restricting adoption in high-throughput automotive assembly lines.
Strategic Opportunities
- India Industrial Manufacturing:PLI scheme incentives for domestic electronics and footwear production are opening procurement channels for localized adhesive formulation facilities.
- Bio-Based Tackifier Convergence:Rosin ester and terpene resin technologies are intersecting with synthetic rubber chemistry to create renewable-content adhesives qualifying for EU taxonomy alignment.
- Direct Distribution Platforms:Specialized chemical marketplaces are enabling mid-sized converters to bypass traditional distributor markups for standard-grade rubber adhesives.
Industry Challenges
- Polymer Synthesis Expertise Gap:Formulation chemists capable of balancing peel strength, temperature resistance, and regulatory compliance remain scarce in emerging manufacturing regions.
- Multi-Jurisdiction Certification Burden:Adhesive producers must simultaneously navigate EPA hazardous air pollutant permits, REACH substance registration, and China GB standards for cross-border supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber-Based Adhesives Market |
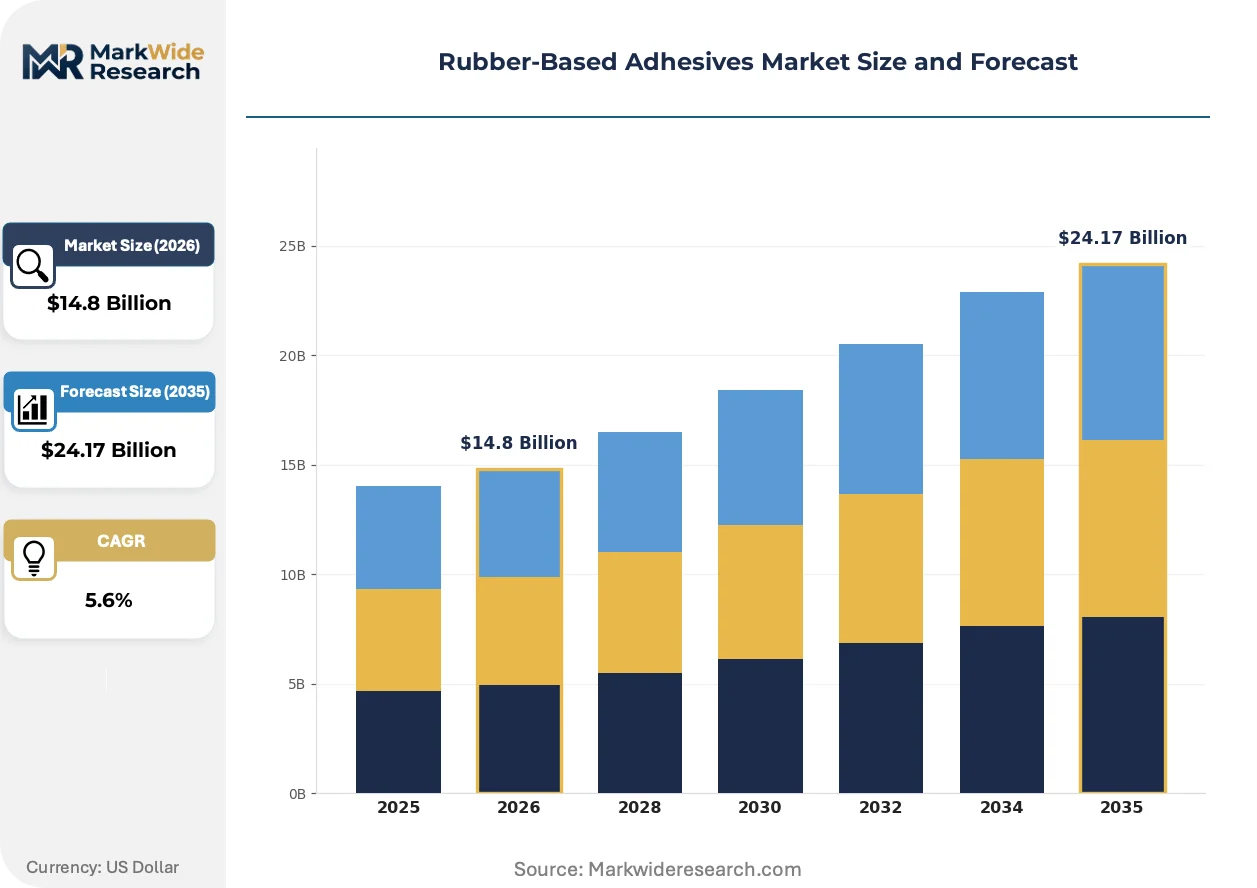
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Adhesives, Hot Melt Adhesives, Pressure Sensitive Adhesives, Polyurethane Adhesives End User: Automotive, Packaging, Construction, Footwear Technology: Solvent-based, Water-based, Bio-based, Reactive Application: Bonding, Coatings, Sealants, Laminating |
| Companies Covered | Sika AG, H.B. Fuller Company, Henkel AG & Co. KGaA, Huntsman Corporation, Avery Dennison, 3M Company, Dow Inc., Momentive, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber-Based Adhesives Market Strategic Shifts & Innovations
Formulation science and regulatory compliance are converging to reshape competitive advantage in rubber-based bonding technologies, with sustainability credentials and processing efficiency emerging as primary differentiation vectors.
Hot-melt rubber adhesive technology is overtaking solvent-based systems in packaging and hygiene applications through elimination of drying stages and VOC emissions. Major converters in the United States are retrofitting coating lines to accommodate reactive polyurethane hot-melt systems. This transition is compressing capital recovery timelines for equipment investments while raising barriers for smaller competitors lacking upgrade capacity.
REACH authorization requirements for diisocyanates and certain tackifier precursors are forcing reformulation investments across European supply chains. Manufacturers serving automotive and construction sectors must substitute restricted substances with compliant alternatives by designated sunset dates. German and French adhesive producers are accelerating R&D partnerships with polymer suppliers to secure approved substance pipelines ahead of enforcement deadlines.
Specification-driven procurement is consolidating buyer power among automotive tier-one suppliers and multinational packaging groups. Long-term supply agreements with embedded technical service provisions are displacing spot-market purchasing for critical bonding applications. This pattern is most pronounced in Japan and South Korea, where electronics manufacturers demand dedicated formulation development support alongside volume commitments.
Rubber-Based Adhesives Market Segmentation
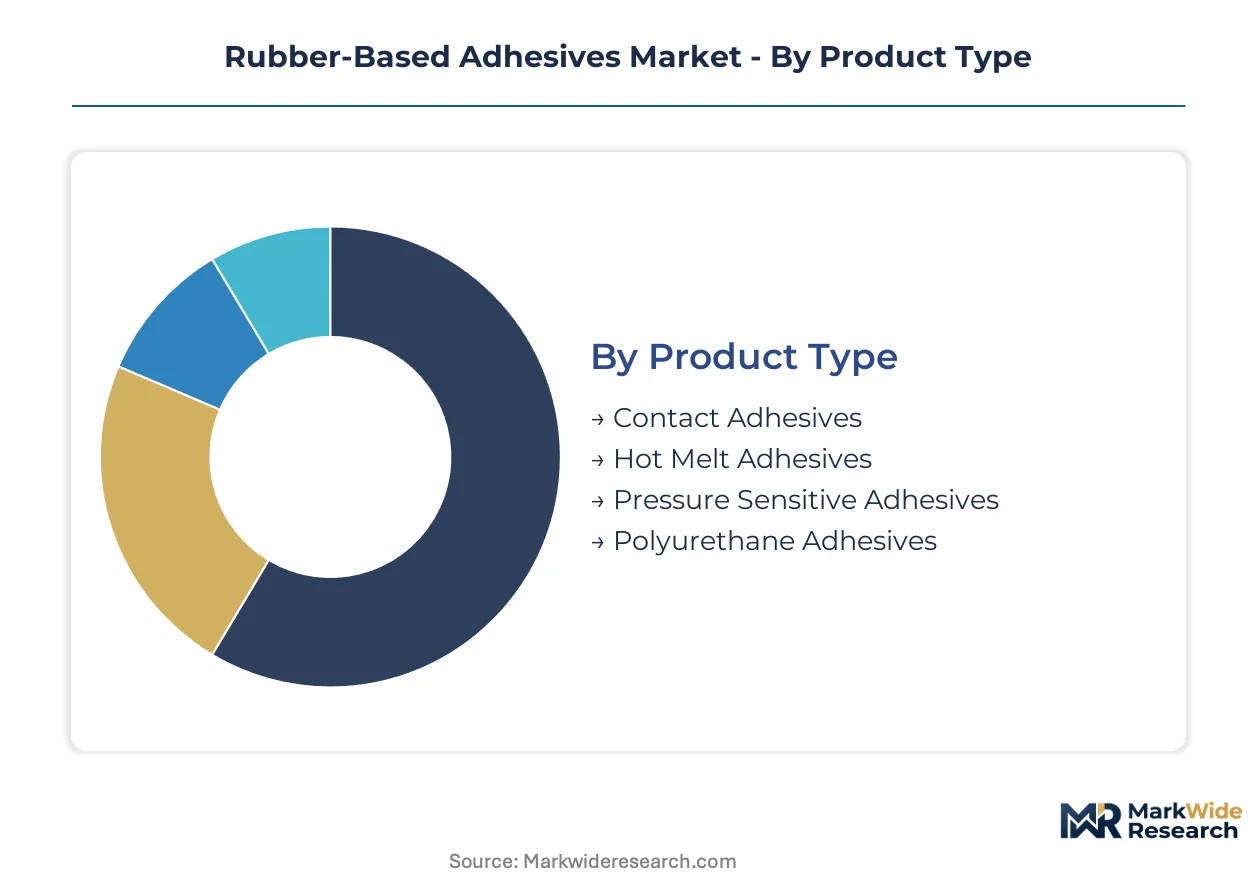
Rubber-based adhesive producers configure manufacturing assets around curing chemistry and viscosity requirements, not interchangeable equipment. Capital allocation decisions lock producers into specific segment positions for years.
Product Type:
Pressure sensitive adhesives and hot melt systems demand the heaviest upfront investment in precision coating lines and temperature-controlled storage infrastructure.
- Pressure Sensitive Adhesives:Acrylic-modified natural rubber formulations deliver instant tack without activation. E-commerce fulfillment centers in Germany and the United States are scaling label and tape consumption, though silicone release liner costs constrain margin expansion.
- Hot Melt Adhesives:Block copolymer rubber compounds formulated with tackifying resins eliminate solvent drying stages. Packaging converters are retrofitting coating lines to capture VOC compliance advantages under EPA regulations.
- Contact Adhesives:Neoprene or nitrile rubber dissolved in solvent carriers bond decorative laminates and footwear components. REACH phase-down mandates are forcing European producers toward water-based alternatives.
- Polyurethane Adhesives:Reactive systems cure through moisture or heat activation for structural bonding applications. Automotive OEMs specify these for composite panel assembly in lightweight vehicle platforms.
Most installed capacity flows through pressure sensitive adhesives. Expansion is steepest in hot melt adhesives.
End User:
Automotive procurement concentrates volume among tier-one suppliers, while packaging demand fragments across thousands of converters.
- Automotive:Battery pack bonding and interior trim assembly consume high-temperature-resistant nitrile and polychloroprene formulations. Chinese EV manufacturers are scaling adhesive-intensive thermal management systems.
- Packaging:Corrugated box sealing and flexible film lamination drive water-based and hot melt rubber adhesive consumption. German fulfillment networks are specifying recyclable adhesive formulations for circular economy compliance.
- Construction:Flooring installation and insulation bonding employ solvent-based contact cements. EPA hazardous air pollutant permits restrict coating operations at US manufacturing facilities.
- Footwear:Outsole attachment and upper construction use natural rubber latex and polyurethane systems. India's PLI scheme incentives are stimulating domestic adhesive formulation capacity for export-oriented shoe production.
Automotive commands the highest specification premiums. Packaging generates the largest absolute tonnage.
Technology:
Solvent-based systems require enclosed coating lines and thermal oxidizers, while water-based alternatives need extended drying tunnels that consume floor space.
- Solvent-based:Hydrocarbon-dissolved synthetic rubbers deliver rapid green strength and moisture resistance. REACH VOC limits are compelling European converters toward compliant alternatives before enforcement deadlines.
- Water-based:Emulsified natural rubber and carboxylated styrene-butadiene latex eliminate hazardous air pollutants. Curing speed limitations restrict adoption in high-throughput automotive assembly lines.
- Bio-based:Rosin ester tackifiers and terpene resins replace petrochemical derivatives. EU Green Deal taxonomy alignment requirements are accelerating R&D partnerships between French adhesive producers and renewable feedstock suppliers.
- Reactive:Two-component polyurethane and silane-terminated systems cure through chemical reaction rather than solvent evaporation. Japanese electronics manufacturers demand dedicated formulation development support alongside volume commitments.
Solvent-based technology retains the most installed coating capacity. Bio-based formulations are climbing the fastest.
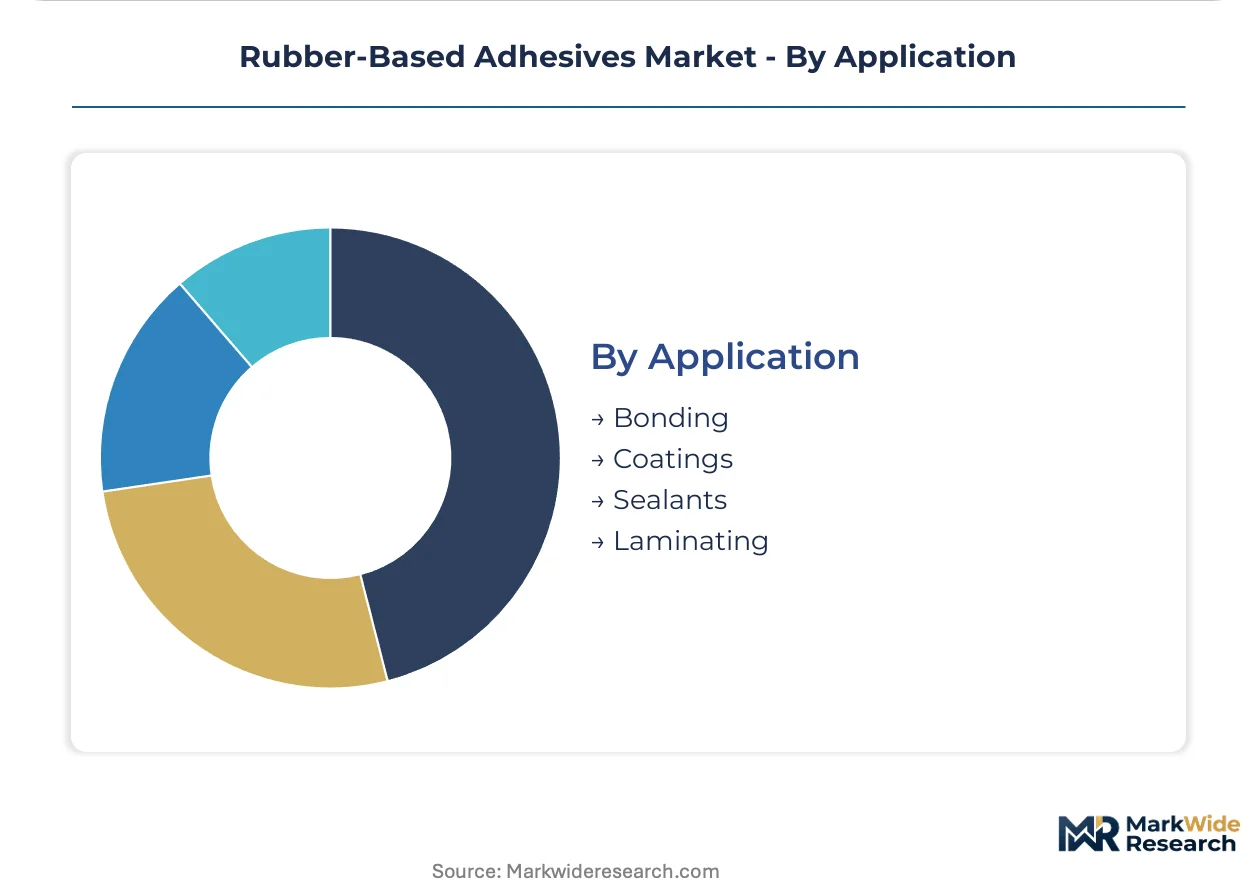
Application:
Bonding applications command formulation customization, while coatings and sealants tolerate more standardized specifications.
- Bonding:Structural assembly of dissimilar substrates requires tailored peel strength and temperature resistance profiles. South Korean battery manufacturers specify proprietary rubber adhesive systems for cell-to-pack integration.
- Sealants:Gap-filling formulations accommodate joint movement in construction and transportation applications. Chinese GB standards for building materials restrict phthalate plasticizer content in rubber sealant compounds.
- Coatings:Protective rubber layers applied to textiles and films demand controlled viscosity and film-forming characteristics. US textile laminators are shifting from solvent to water-based coating systems under EPA compliance pressure.
- Laminating:Multi-layer film and foil constructions for food packaging use pressure-sensitive or hot melt rubber adhesives. German converters are certifying recyclable adhesive formulations for extended producer responsibility schemes.
Bonding applications concentrate the highest technical service requirements. Laminating is gaining share fastest in packaging sector procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting rubber-based adhesive production toward jurisdictions with lower compliance costs and expanding domestic demand. Manufacturers are relocating coating operations to evade REACH enforcement timelines while capturing proximity to EV battery assembly clusters.
China
Domestic EV manufacturers are scaling adhesive-intensive thermal management systems and cell-to-pack bonding operations. GB standards for building materials restrict phthalate plasticizer content in rubber sealant compounds. The Yangtze River Delta hosts concentrated formulation capacity serving battery producers in Ningbo and Suzhou.
Germany
Automotive tier-one suppliers are specifying long-term supply agreements with embedded technical service provisions for composite panel assembly. ECHA authorization requirements for diisocyanates are forcing reformulation investments across industrial supply chains. The Rhine-Ruhr corridor maintains specialized coating lines for pressure-sensitive adhesive tapes.
United States
E-commerce fulfillment networks are accelerating pressure-sensitive adhesive consumption for shipping labels and protective tapes. EPA hazardous air pollutant permits restrict coating operations at manufacturing facilities in industrial Midwest states. Packaging converters in Wisconsin and Ohio are retrofitting lines for hot-melt systems.
India
PLI scheme incentives for domestic electronics and footwear production are opening procurement channels for localized formulation facilities. BIS certification requirements are tightening quality benchmarks for imported adhesive raw materials. Tamil Nadu and Gujarat are attracting greenfield investment from multinational coating specialists.
Japan
Electronics manufacturers are demanding dedicated formulation development support alongside volume commitments for semiconductor packaging applications. METI guidelines encourage substitution of solvent-based systems in precision coating operations. The Chubu region around Nagoya anchors specialized polymer synthesis expertise for high-reliability bonding.
Rubber-Based Adhesives Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and regional compliance specialization. The sector exhibits moderate consolidation with tier-one chemical conglomerates controlling formulation science and distribution infrastructure. Three archetypes dominate: integrated petrochemical players with captive rubber supply, specialized adhesive formulators with automotive certification depth, and regional converters leveraging tariff-protected domestic markets. Competitive intensity centers on capacity expansion in Southeast Asian feedstock corridors and technology licensing for water-based curing systems.
Within the integrated chemical tier, Sika AG and Dow Inc. exemplify scale-driven positioning through polymer synthesis capabilities and geographic manufacturing footprints. BASF SE anchors the European specialty chemicals vector with REACH-compliant formulation pipelines. Among diversified industrials, 3M Company represents technology leadership in pressure-sensitive adhesive architectures. Henkel AG & Co. KGaA sits within the automotive bonding specialist tier, while H.B. Fuller Company occupies the packaging-focused formulation segment.
| Leading Market Players |
|---|
| Sika AG |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Huntsman Corporation |
| Avery Dennison |
| 3M Company |
| Dow Inc. |
| Momentive |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Butadiene and naphtha feedstock costs cascade from Southeast Asian petrochemical crackers through synthetic rubber polymerization into tiered adhesive pricing. Solvent-based formulation producers absorb margin compression when monomer prices spike, while water-based alternatives command stability premiums from REACH-compliant European buyers.
Pricing Analysis
Distributor markups of 15-25% separate standard-grade rubber adhesives from direct-to-OEM contract pricing for automotive tier-one suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth: REACH-registered formulations with ECHA-compliant tackifiers sit at premium tiers, while uncertified solvent-based products compete on spot-market terms. Cost compression in solvent-based segments is intensifying because EPA hazardous air pollutant permits raise facility operating overhead. Packaging converters exhibit highest price sensitivity due to commoditized demand, whereas battery pack bonding specifications leave EV manufacturers with limited substitution options.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns for rubber adhesive raw materials. Synthetic rubber production concentrates in Thailand, South Korea, and Germany, while natural rubber latex sourcing clusters in Indonesia and Malaysia. Formulation chemistry draws from butadiene, styrene, and rosin ester tackifiers as primary inputs. Single-source vulnerability in Thai natural rubber harvests creates geographic exposure to climate disruption. Distribution runs through specialized chemical distributors serving automotive OEMs and packaging converters with divergent service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rubber-based adhesives constitute a late-cycle quality story as automotive OEMs shift procurement toward high-temperature-resistant formulations with embedded technical service provisions.
For Market Incumbents: Deploy captive polymer synthesis capabilities to secure margin stability against feedstock volatility. Henkel AG and 3M Company exemplify defensive positioning through REACH-compliant formulation pipelines and automotive certification depth. Capacity addition in the Yangtze River Delta captures proximity to Chinese EV battery assembly clusters. Certification investment in bio-based tackifier alternatives addresses EU Green Deal taxonomy alignment requirements before enforcement deadlines tighten. For New Entrants and Emerging Players: Mid-sized Indian footwear exporters represent an underserved buyer archetype seeking localized formulation with BIS-certified raw material traceability. White-space targets include water-based contact adhesives for Tamil Nadu shoe manufacturing and recyclable hot-melt systems for German packaging circular economy schemes. Direct distribution platforms bypass traditional chemical distributor markups for standard-grade procurement. Technical partnership with regional rosin ester suppliers accelerates bio-based qualification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemists capable of balancing peel strength, temperature resistance, and multi-jurisdiction compliance remain scarce in emerging manufacturing regions. Long-term viability favors specialized adhesive formulators with automotive certification depth over commodity solvent-based producers facing regulatory phase-down. Acquisition target archetype: regional coating specialists with captive distribution in India or Southeast Asia. Signal to watch: ECHA sunset date enforcement triggering distressed asset availability among non-compliant European producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tackifier Supply | Rosin ester and terpene resin partnerships with French renewable feedstock suppliers secure EU Green Deal alignment. |
| Water-Based Formulation Scale-Up | Extended drying tunnel investments capture REACH-compliant packaging demand in German fulfillment networks. |
| Automotive Technical Service Embedding | Long-term supply agreements with South Korean battery manufacturers lock in proprietary cell-to-pack bonding specifications. |
| Regional Distribution Hub Establishment | Rotterdam and Singapore centers reduce logistics exposure for Southeast Asian natural rubber latex sourcing. |
| Bio-Based Certification Program | EU taxonomy qualification opens procurement channels from sustainability-mandated automotive OEMs and packaging groups. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included technical R&D directors at adhesive formulators, procurement leads at automotive tier-one suppliers, plant managers at Southeast Asian synthetic rubber facilities, and distribution channel partners serving packaging converters. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and ECHA substance registration databases. Bottom-up volume modeling across product types, end-use industries, and regional production hubs was cross-checked against top-down market sizing from petrochemical feedstock consumption patterns.
Historical reference periods anchored volume and value trajectories across the analysis window. Segmentation dimensions modeled include curing chemistry technology, end-use industry vertical, formulation grade tier, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth curves adjusted for feedstock cost pass-through elasticity and compliance-driven substitution effects. Industry-specific forecast inputs encompassed EV platform adhesive content per vehicle, e-commerce logistics tape consumption intensity, and REACH authorization timeline impacts on formulation mix shifts.
Inputs from primary stakeholder interviews and secondary chemical industry databases were available through the study window; gaps in real-time synthetic rubber monomer pricing and confidential automotive OEM specification data introduce uncertainty bands around water-based adoption rate assumptions. Forecasts reflect documented assumptions about regulatory enforcement timelines and feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Silicone Sealants Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Reactive Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Gasket and Seal Material Market