
 Wood Adhesives Market | 2026-2036
Wood Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Adhesives Market Analysis
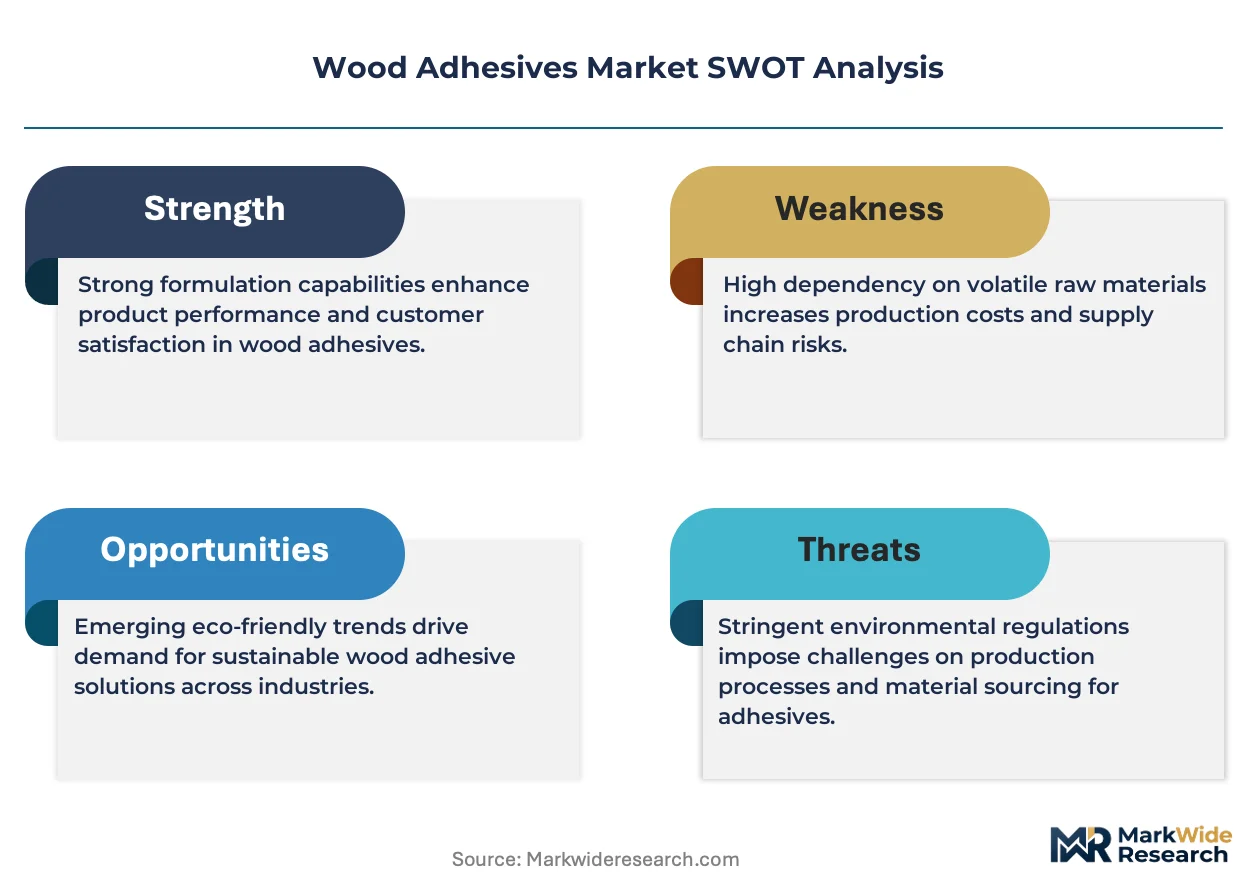
A capital-intensity divergence between integrated resin producers and specialty formulators is reorganizing competitive tiers in wood adhesives. Henkel AG & Co. KGaA leverages backward integration into polyurethane intermediates to secure margin control across European furniture accounts. H.B. Fuller Company anchors its position through geographic dominance in North American engineered wood panel mills. Sika AG differentiates via technology leadership in moisture-curing adhesives for structural timber applications.
Wood adhesives are polymeric binding systems formulated from polyurethane, polyvinyl acetate, epoxy, or phenol-formaldehyde resins, designed to create durable bonds between lignocellulosic substrates under variable moisture and load conditions. These formulations cure through chemical crosslinking or physical drying to achieve shear strengths exceeding wood failure thresholds, serving primary industrial purposes in furniture assembly, engineered panel lamination, and mass timber construction. Polyurethane adhesives occupy the premium tier in structural outdoor applications where moisture resistance and gap-filling capability command price premiums over PVA alternatives. Phenol formaldehyde maintains mature volume leadership in plywood and oriented strand board production despite regulatory pressure on free formaldehyde content. Epoxy segments concentrate in high-performance architectural joinery and marine-grade laminated beams where load-bearing certification requirements create defensible margin pools.
EPA formaldehyde emission standards under TSCA Title VI and REACH restrictions on hazardous substance classifications shape product development trajectories and market access conditions for wood adhesive suppliers. ECHA hazard classifications for isocyanates and Germany's DIBt approvals for structural timber bonding impose compliance costs that favor larger formulated product manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving mass timber building codes and procurement specifications for embodied carbon disclosure, as these frameworks increasingly determine adhesive selection criteria in public infrastructure and commercial development tenders.
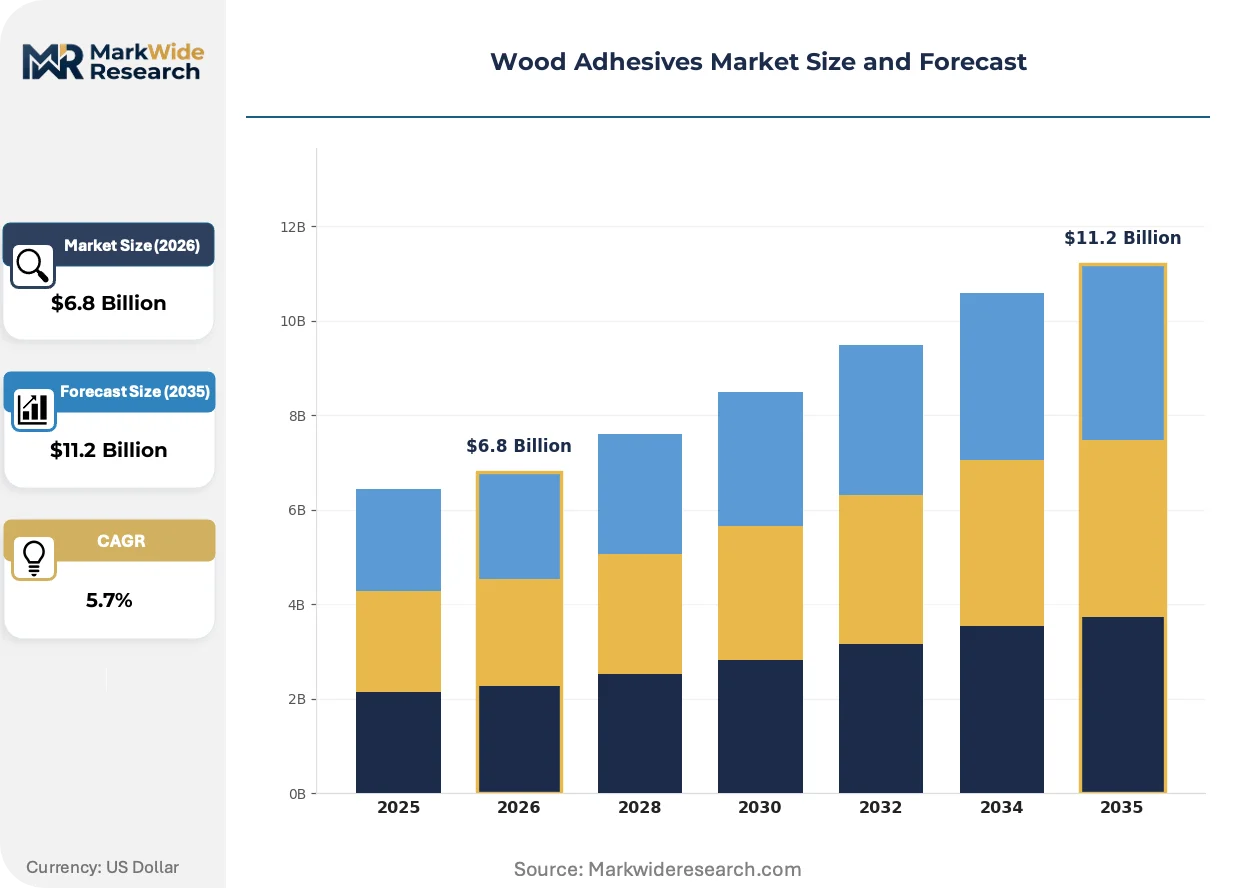
Market Dynamics
Mass timber building codes are accelerating specification of structural polyurethane and epoxy formulations as architects and developers pursue carbon-negative construction certifications. This regulatory-enabled demand shift is compressing traditional phenol-formaldehyde volumes in commercial projects while elevating performance requirements for moisture-curing systems.
Growth Catalysts
- Cross-laminated timber commercial adoption:German and Austrian building codes now permit 12-story mass timber structures, creating specification pull for DIBt-certified structural adhesives in multi-story construction.
- EPA TSCA Title VI compliance:Emission standards for composite wood products are redirecting North American panel manufacturers toward low-formaldehyde phenolic and polyurethane alternatives.
- Prefabricated housing output expansion:Factory-built component assembly in the United States and Scandinavia favors fast-curing hot-melt and moisture-curing polyurethane systems over conventional cold-press phenolics.
Market Restraints
- Isocyanate feedstock concentration:European polyurethane adhesive producers face supply vulnerability from concentrated MDI manufacturing in Germany and Belgium.
- Formaldehyde substitution technical limits:Soy-based and tannin bio-adhesives currently fail shear strength and boil-durability thresholds required for exterior structural plywood certification.
- REACH hazard classification costs:ECHA reclassification of isocyanates as respiratory sensitizers imposes mandatory worker exposure monitoring and medical surveillance burdens on small- and mid-scale formulators.
Strategic Opportunities
- India mass timber code development:Bureau of Indian Standards draft guidelines for engineered bamboo and timber structures create first-mover positioning for structural adhesive suppliers ahead of commercial building adoption.
- EU Green Deal embodied carbon procurement:Public infrastructure tenders in France and the Netherlands now require Environmental Product Declarations, favoring bio-based and low-curing-energy adhesive systems with verified lifecycle data.
- Digital manufacturing convergence:Integration of robotic dispensing with RFID-tracked adhesive batch records enables quality-assured just-in-time delivery for automated furniture and panel assembly lines.
Industry Challenges
- DIBt and ICC-ES certification timelines:Structural timber bonding approvals require 18-36 months of full-scale fire and load testing, delaying product commercialization and freezing formulation iterations.
- Specialized applicator workforce scarcity:Moisture-curing polyurethane and two-part epoxy systems demand trained technicians for proper mixing ratios and open-time management, constraining field deployment in remote construction sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Adhesives Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, PVA, Epoxy, Phenol Formaldehyde Form: Liquid, Paste, Film, Granule End User: Furniture, Flooring, Cabinetry, Construction Application: Indoor, Outdoor, Structural, Non-structural |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, H.B. Fuller Company, BASF SE, Pidilite Industries Limited, Arkema Group, AkzoNobel N.V., Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Adhesives Market Emerging Trajectories
Bio-based feedstock substitution and digital quality assurance systems are restructuring formulation priorities and supply chain verification protocols. These shifts intersect with tightening emission regulations to create new competitive differentiators beyond traditional performance metrics.
Tannin- and lignin-derived bio-adhesives are supplanting petrochemical phenolics in interior-grade particleboard and medium-density fiberboard applications. European panel producers in France and Austria have scaled commercial production of these systems for furniture and non-structural building components. The technology is supplanting approximately 15-20% of interior phenolic volume in regions with strong forest product processing clusters and carbon accounting mandates.
REACH restrictions on formaldehyde emissions and the EU Green Deal sustainable product framework are forcing reformulation of mature thermoset systems. Panel manufacturers now face mandatory Environmental Product Declarations and digital product passports tracing adhesive content through supply chains. Germany and Nordic markets are experiencing the fastest compliance-driven product turnover, with distributors demanding batch-level chemical composition data for inventory management.
Certification-driven specification is compressing buyer decision cycles and elevating technical documentation requirements. Mass timber contractors now require adhesive suppliers to provide ICC-ES or DIBt reports, ISO 9001 quality certificates, and embodied carbon calculations before bid qualification. This pattern concentrates procurement authority with technical sales engineers and away from traditional distributor relationships, most visible in United States commercial construction and Scandinavian engineered wood projects.
Wood Adhesives Market Segmentation
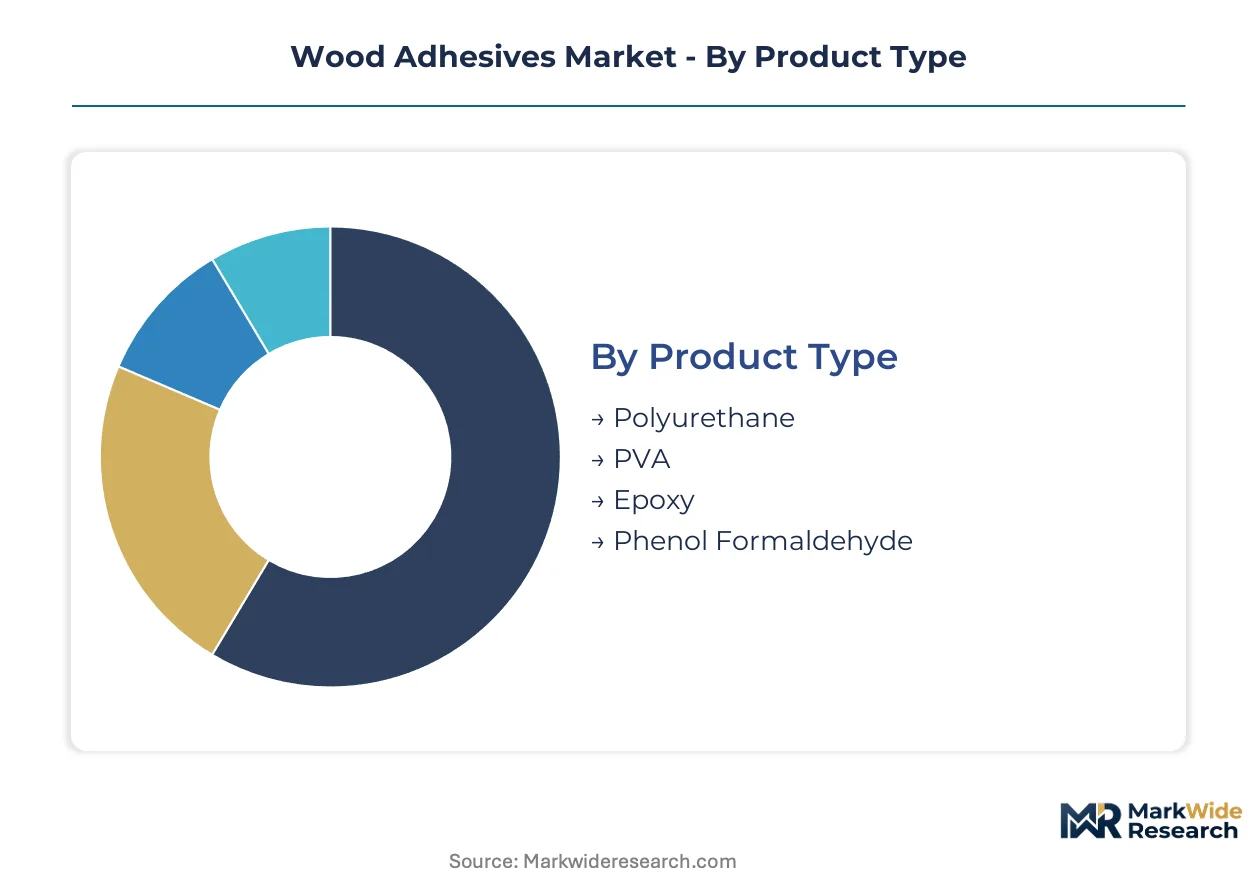
Wood adhesive procurement diverges sharply across end-use specifications, with structural certification requirements and emission standards fragmenting what appears chemically similar into distinct margin tiers. Formulators must navigate incompatible technical standards between furniture assembly and mass timber construction to capture premium positioning.
Product Type:
Margin pools concentrate in moisture-curing systems where structural certification creates defensible pricing power against commodity alternatives.
- Polyurethane:Moisture-curing formulations achieve structural bonding certification for mass timber applications. Demand concentrates in Germany and Austria where DIBt-approved systems command 40-60% price premiums over conventional alternatives for cross-laminated timber projects.
- PVA:Polyvinyl acetate emulsions dominate interior furniture and cabinetry assembly through rapid set times and water cleanup. Volume concentrates in United States prefabricated housing component factories where fast-curing hot-melt compatible systems displace slower phenolic alternatives.
- Epoxy:Two-part structural systems serve marine-grade laminated beams and architectural joinery requiring load-bearing certification.
- Phenol Formaldehyde:Thermoset resins maintain plywood and oriented strand board volume leadership despite EPA TSCA Title VI emission compliance costs.
The dominant share belongs to Phenol Formaldehyde, while Polyurethane is closing the gap fastest.
Form:
Application equipment compatibility and factory automation penetration determine which physical states capture volume versus margin.
- Liquid:Pumpable emulsions and solvent-borne systems integrate with automated spray and roller coating lines in panel manufacturing. United States engineered wood mills favor low-viscosity formulations for high-speed continuous presses.
- Film:Pre-cured adhesive sheets enable precise glue-line control in architectural laminated beams where visual quality requirements reject squeeze-out. Scandinavian mass timber producers specify film adhesives for automated layup systems in glulam manufacturing.
- Paste:Thixotropic formulations serve vertical surface bonding and gap-filling applications in furniture edgebanding.
- Granule:Solid phenolic resins require heat and pressure activation in plywood hot-press operations.
Liquid formulations hold the largest installed base, though Film formats are expanding most quickly in automated production environments.
End User:
Certification burden and specification authority vary dramatically between discretionary consumer purchases and code-governed construction procurement.
- Construction:Structural timber bonding requires ICC-ES or DIBt approval, ISO 9001 documentation, and embodied carbon disclosure for public tender qualification. German and Austrian commercial developers now specify certified adhesives for 12-story mass timber structures permitted under updated building codes.
- Furniture:Assembly operations prioritize fast tack development and sandability for automated edgebanding and dowel insertion lines. United States cabinet manufacturers favor PVA hot-melts for just-in-time component production.
- Flooring:Laminate and engineered hardwood production demands moisture-resistant bonding for kitchen and bathroom installations.
- Cabinetry:Interior-grade panel lamination for residential kitchens emphasizes low formaldehyde emission profiles.
Construction commands the highest per-kilogram pricing, while Furniture generates the steepest volume expansion trajectory.
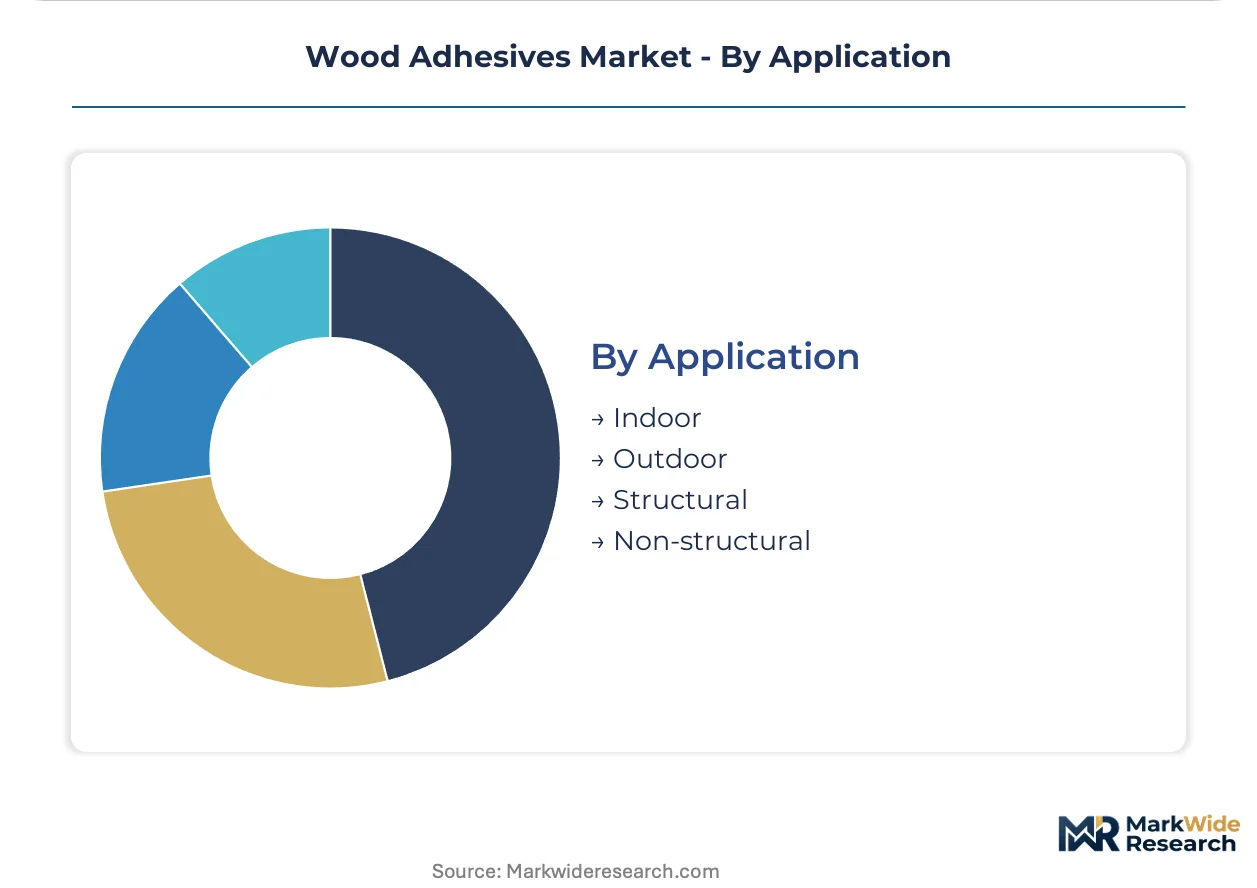
Application:
Environmental exposure classification separates commodity interior grades from premium structural tiers with multi-year certification timelines.
- Structural:Load-bearing adhesives must pass full-scale fire and load testing requiring 18-36 months for DIBt or ICC-ES approval. German mass timber contractors demand batch-level chemical composition data and RFID-tracked quality records before bid qualification.
- Outdoor:Exterior exposure systems require boil-durability and weathering resistance exceeding interior specifications. European panel producers face REACH restrictions on isocyanate classifications that elevate compliance costs for moisture-curing polyurethane deployments.
- Indoor:Interior-grade formulations serve furniture, cabinetry, and non-structural panel applications under less stringent emission standards.
- Non-structural:Decorative and aesthetic bonding applications prioritize set speed and visual finish over load-bearing performance.
Structural applications dominate value capture, with Outdoor segments climbing the fastest as mass timber codes expand commercial building eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Austria absorb 40-60% price premiums for DIBt-certified structural adhesives without volume elasticity, while furniture manufacturers in China and the United States drive procurement toward lowest-cost PVA formulations.
United States
Engineered wood panel mills in the Southeast and Pacific Northwest specify fast-curing polyurethane systems for prefabricated housing components. EPA TSCA Title VI emission standards redirect manufacturers toward low-formaldehyde phenolic alternatives. Mass timber contractors in Oregon and Washington now require ICC-ES certification and embodied carbon disclosure before bid qualification.
Germany
Commercial developers in Berlin and Munich specify DIBt-approved structural adhesives for 12-story mass timber structures permitted under updated building codes. REACH restrictions on isocyanate classifications impose mandatory worker exposure monitoring costs on formulators. The Black Forest and Bavarian timber processing clusters anchor European demand for moisture-curing polyurethane systems.
China
Furniture export manufacturers in Guangdong and Zhejiang provinces prioritize cost-optimized PVA emulsions for cabinet and flooring assembly. The country's national standards body develops guidelines for engineered bamboo structures ahead of commercial building adoption. Yangtze River Delta panel producers face dual carbon goals pressure to verify adhesive lifecycle data.
India
The Bureau of Indian Standards drafts guidelines for engineered timber structures, creating first-mover positioning for structural adhesive suppliers. Furniture manufacturing clusters in Gujarat and Punjab drive volume consumption of interior-grade formulations. Western and Southern construction markets remain underpenetrated for certified structural bonding systems.
France
Public infrastructure tenders under EU Green Deal procurement rules require Environmental Product Declarations for adhesive systems. Mass timber architects in Lyon and Bordeaux specify low-curing-energy formulations with verified carbon accounting. The Auvergne-Rhône-Alpes region hosts scaling production of tannin-derived bio-adhesives for non-structural panel applications.
Wood Adhesives Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with structural certification capabilities separating premium-tier suppliers from commodity formulators. The market organizes around three strategic groups: integrated resin producers with backward control over polyurethane intermediates, geographic specialists dominating regional panel mill supply, and technology-focused players concentrating moisture-curing innovations. Consolidation pressures favor larger manufacturers with dedicated regulatory affairs capabilities, while small-scale formulators face compliance cost disadvantages. Competitive moves concentrate on capacity expansion in high-growth mass timber corridors and portfolio diversification into bio-based feedstock systems.
Within the integrated producer tier, Henkel AG & Co. KGaA and BASF SE exemplify archetypes combining captive resin supply with formulated product distribution. Sika AG occupies a position among technology-focused specialists emphasizing structural certification leadership. These three anchors illustrate how competitive positioning stratifies across cost control, geographic density, and performance-tier specialization rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| H.B. Fuller Company |
| BASF SE |
| Pidilite Industries Limited |
| Arkema Group |
| AkzoNobel N.V. |
| Dow Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for MDI and polyol feedstocks lock in both supply access and price visibility for European polyurethane adhesive producers facing REACH-mandated isocyanate reclassification costs. These arrangements concentrate procurement power among integrated resin manufacturers while exposing smaller formulators to spot market volatility in Germany and Belgium.
Pricing Analysis
After-sales technical service contracts drive lifetime value for structural adhesive suppliers, with DIBt-certified systems commanding sustained premiums through installation supervision and batch traceability. Three-tier pricing structure across certified structural, commercial-grade, and commodity interior tiers separates margin pools by certification burden. Cost compression in commodity PVA segments is intensifying because Chinese furniture exporters prioritize lowest-unit-cost procurement. Construction contractors show least price sensitivity, while mass-market furniture manufacturers absorb volume discounts in exchange for formulation standardization.
Supply Chain Analysis
Inbound logistics costs from Rotterdam-Antwerp chemical corridors determine landed cost competitiveness for polyurethane adhesive producers serving Central European mass timber clusters. Manufacturing gravity centers on Germany, Belgium, and the United States, with formulation operations drawing from concentrated MDI production in the Rhine-Ruhr and Antwerp hubs. Raw material dependencies span aromatic isocyanates, formaldehyde resins, and bio-based tannin extracts. Single-source vulnerability in European MDI supply elevates disruption risk from regulatory shutdowns or feedstock allocation decisions. Distribution runs through direct mill supply agreements for panel manufacturers and distributor networks for furniture assembly accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough driven by mass timber building code expansion across German-speaking Europe and the Pacific Northwest. Recovery velocity hinges on certification backlog clearance and prefabricated housing order flows.
For Market Incumbents: Shield margin pools in structural certification tiers by accelerating backward integration into polyurethane intermediates before feedstock concentration tightens further. Prioritize DIBt and ICC-ES approval maintenance as regulatory documentation requirements expand. Defensive capacity positioning in high-growth corridors—Oregon, Washington, Bavaria—preserves geographic density advantages against emerging Asian suppliers.
For New Entrants and Emerging Players: Accelerated DIBt certification pathways through partnership with established testing laboratories offer fastest route to structural adhesive qualification. White-space concentration in Indian engineered timber code development and French public procurement under EU Green Deal rules rewards first-mover positioning. Target bio-based formulation segments where tannin and lignin feedstock access creates differentiation against petrochemical incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale formulators with captive certification capabilities and regional mill relationships rather than commodity PVA producers facing Chinese import pressure. Long-term viability over a five-to-ten-year window favors adhesive suppliers with demonstrated structural bonding approvals and embodied carbon accounting infrastructure. Monitor mass timber building code adoptions in India and Southeast Asia as inflection signals for geographic demand migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Intermediates | Captive MDI supply secures margin control against Belgian-German feedstock concentration. |
| DIBt Certification Fast-Track Investment | Eighteen-month approval compression captures specification pull from 12-story mass timber codes. |
| Bio-Based Feedstock Scale-Up | Tannin-derived systems satisfy EU Green Deal procurement rules in French infrastructure tenders. |
| Direct Mill Supply Agreement Expansion | Oregon and Washington panel producers demand RFID-tracked batch records for automated lines. |
| Technical Service Contract Bundling | Installation supervision and open-time management training defend premium positioning against commodity alternatives. |
Methodological Framework
Operator-level perspectives from adhesive formulation chemists, mass timber project engineers, panel mill procurement directors, and furniture factory operations managers anchored the qualitative base. These primary engagements combined with trade data from Eurostat and U.S. Census Bureau chemical shipments, SEC filings from integrated resin producers, and DIBt certification registries. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down resin production capacity assessments.
Sensitivity analysis tested forecast robustness across variable mass timber code adoption timelines and isocyanate feedstock price scenarios. The analytical framework segmented by adhesive chemistry, structural certification tier, end-use industry, and regional regulatory cluster across the analysis window. CAGRs derived from regression against historical panel production volumes and projected cross-laminated timber square footage. Key inputs included Bureau of Indian Standards draft guideline progression and EU Green Deal procurement implementation schedules.
Underlying assumptions cover stable REACH formaldehyde classifications and continued DIBt-ICC-ES mutual recognition, with deviation risk concentrated in sudden isocyanate reclassification or mass timber code reversals in key states. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
PVA Glue Market