
 Wirewound Resistor Market | 2026-2036
Wirewound Resistor Market Size, Share, and Industry Trends Forecast 2026-2036
Wirewound Resistor Market Analytics
AEC-Q200 qualification for passive automotive components is reorganizing supplier hierarchies in the wirewound resistor sector. Vishay Intertechnology leverages vertical integration across ceramic substrate and resistance wire production to sustain cost advantages in high-reliability grades. KOA Corporation anchors its position through specialized thick-film and wirewound hybrid expertise serving Japanese automotive OEMs. Yageo competes aggressively on scale, operating some of the largest axial and surface-mount wirewound production lines serving contract manufacturers across Asia.
Wirewound resistors are passive electronic components constructed by winding a resistive metal alloy wire, typically nickel-chromium or copper-nickel, around a ceramic, fiberglass, or cement core, then coating the assembly with vitreous enamel, silicone, or cement to achieve power dissipation ratings from fractions of a watt to several hundred watts. These components primarily serve to limit current, divide voltage, dissipate energy as heat, and provide precise resistance values in circuits where stability under thermal and electrical stress is critical. Precision resistors command the strongest margin pools due to tight tolerance requirements in medical devices and test instrumentation, while current sense resistors are expanding fastest as electric vehicle inverters and battery management systems demand accurate low-ohm measurement. Standard resistors remain the highest-volume category but face pricing pressure from thick-film alternatives in consumer electronics applications.
FDA device classification rules for medical electronics and EPA hazardous substance restrictions under TSCA shape material selection and documentation requirements for wirewound resistor manufacturers serving regulated end markets. NHTSA functional safety expectations for automotive systems, aligned with ISO 26262, are elevating traceability and qualification burdens on suppliers to OEMs and Tier-1 module builders. Stakeholders must monitor how evolving semiconductor packaging densities and wide-bandgap power electronics thermal profiles reshape resistor form factor and power density requirements.
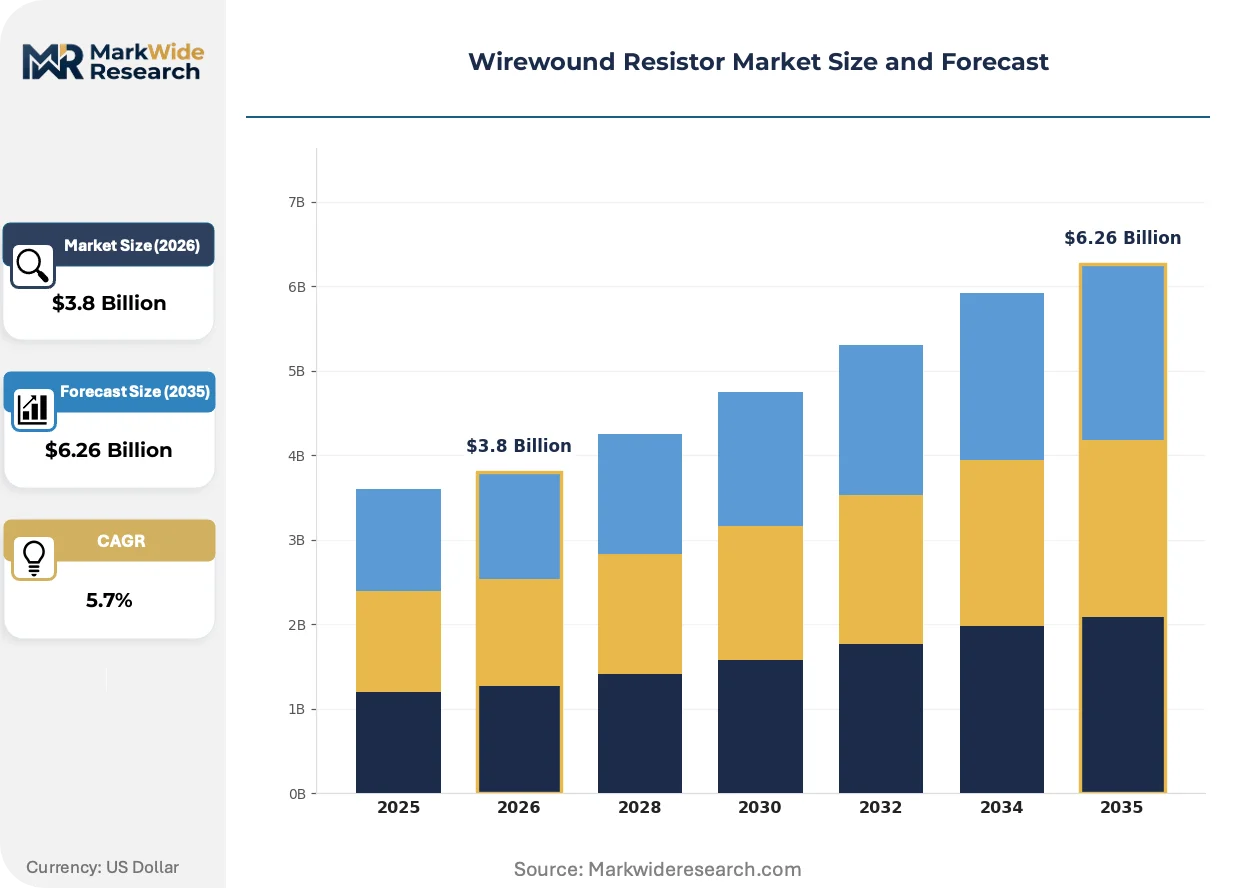
Market Dynamics
Electric vehicle powertrain electrification is forcing wirewound resistor specifications toward higher thermal cycling endurance and lower temperature coefficients, compressing traditional design margins while opening premium positioning for specialized alloy formulations.
Growth Catalysts
- EV Inverter Expansion:Battery management systems and motor drives in electric vehicles require precision current-sense resistors with sub-50 ppm stability, pulling demand from automotive Tier-1 module builders.
- EU RoHS Material Exemptions:Ongoing revisions to the Restriction of Hazardous Substances directive are redirecting R&D investment toward lead-free termination alloys and compliant ceramic substrates.
- Industrial Automation Reshoring:Motor control and variable frequency drive manufacturers in Germany and Japan are expanding captive resistor procurement to secure supply chains for factory automation equipment.
Market Restraints
- Nickel-Chromium Alloy Volatility:Resistance wire feedstock prices fluctuate with nickel mining output concentrated in Indonesia and Russia, squeezing margin predictability for precision resistor grades.
- Thick-Film Substitution:Low-power consumer electronics applications are migrating to cheaper thick-film chip resistors, eroding volume positions for standard wirewound axial formats.
- REACH Documentation Burden:European Chemicals Agency substance-of-very-high-concern listings are extending compliance timelines and testing costs for cement-encased power resistor lines.
Strategic Opportunities
- Medical Device Precision Resistors:FDA Class III implantable device regulations are creating qualification barriers that favor specialized wirewound suppliers with established biocompatibility documentation.
- Wide-Bandgap Power Electronics:Silicon carbide and gallium nitride switching frequencies above 100 kHz are demanding new low-inductance resistor geometries for snubber and gate drive circuits.
- India PLI Scheme:Production-linked incentive schemes for electronics manufacturing are attracting resistor module assembly investments serving domestic appliance and automotive markets.
Industry Challenges
- AEC-Q200 Qualification Timelines:Automotive passive component certification cycles extending 18-24 months are delaying revenue recognition for new product introductions targeting EV platforms.
- Legacy System Integration:Industrial equipment with 20-30 year service lives requires form-factor compatible replacements, constraining innovation in physical resistor dimensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wirewound Resistor Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Resistors, High-Power Resistors, Precision Resistors, Current Sense Resistors Application: Industrial Equipment, Consumer Electronics, Automotive Electronics, Medical Devices Size: Small, Medium, Large, Custom End User: OEMs, Electronics Manufacturers, Research Institutions, Contract Manufacturers |
| Companies Covered | AVX Corporation, KOA Corporation, Vishay Intertechnology, Panasonic, Yageo, TE Connectivity, Cyntec, Hong Kong Resistors Manufactory, Ohmite Mfg Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wirewound Resistor Market Evolving Landscape
Material science advances and thermal management imperatives are restructuring how wirewound resistors dissipate power and maintain stability under electrical stress. These developments are compressing traditional product lifecycles while opening specialized niches.
Ceramic core formulations with enhanced alumina purity are fragmenting the thermal performance landscape for high-power applications. Aerospace and defense contractors are qualifying these substrates for radar and power supply modules operating above 200°C ambient. The technology is fragmenting supplier tiers between commodity ceramic houses and specialized high-reliability substrate manufacturers.
REACH substance restrictions on cadmium and hexavalent chromium coatings are compelling European resistor makers to accelerate conversion to zinc-aluminum and tin-based termination platings. Surface-mount power resistor lines face the steepest reformulation costs due to solderability requirements. German automotive suppliers are pushing their resistor vendors to complete coating transitions ahead of regulatory deadlines.
Direct procurement contracts between automotive OEMs and resistor manufacturers are compressing traditional distribution channels. Tier-1 module builders in Japan and South Korea are establishing approved manufacturer lists with volume commitments and technical collaboration clauses. This pattern is most pronounced in battery management system resistor sourcing, where traceability requirements favor direct relationships over broad-line distributors.
Wirewound Resistor Market Segmentation
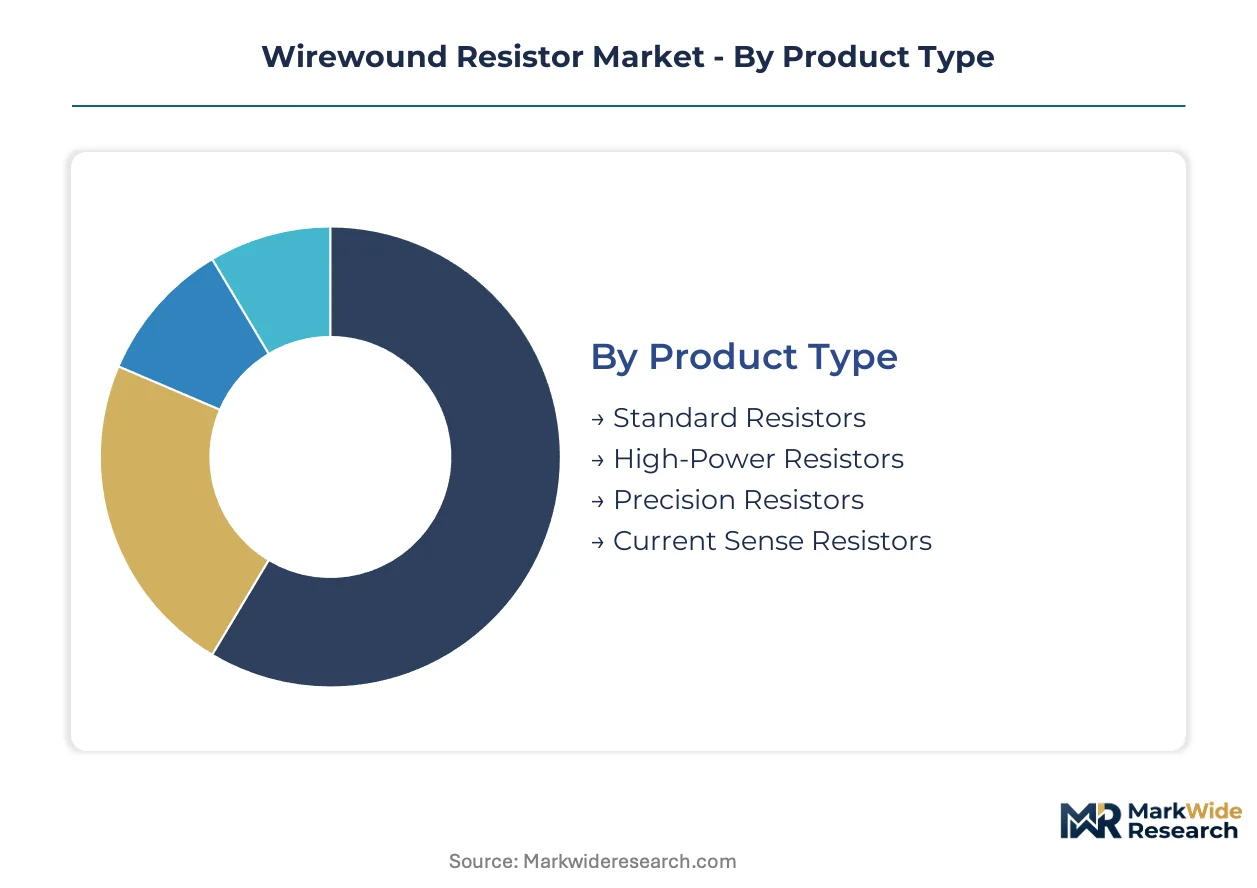
Wirewound resistor procurement patterns diverge sharply across product tiers and end-use specifications. Substitution threats from thick-film and metal-film alternatives reshape competitive intensity differently in each segment category.
Product Type:
Thick-film chip resistors exert the strongest displacement pressure on commodity wirewound formats, while specialized alloy formulations defend premium positions against substitution.
- Standard Resistors:Axial-lead and surface-mount constructions using nickel-chromium or copper-nickel alloys wound on ceramic cores serve general-purpose current limiting and voltage division. Consumer electronics manufacturers in China and contract manufacturers across Southeast Asia absorb the highest volumes, though pricing pressure from thick-film alternatives erodes margin pools in sub-2-watt ratings.
- Precision Resistors:Tight-tolerance designs achieving sub-0.1% resistance stability through controlled winding geometry and thermal compensation serve medical device OEMs and test instrumentation builders. FDA Class III implantable device regulations and ISO 17025 calibration requirements in German metrology labs sustain premium positioning despite higher unit costs.
- High-Power Resistors:Cement-encased or aluminum-housed designs dissipating 50-500 watts for motor braking and power conversion applications.
- Current Sense Resistors:Low-ohm precision shunts with sub-50 ppm temperature coefficients for battery management systems and motor drives.
Standard resistors retain volume leadership; current sense resistors hold the steepest expansion curve.
Application:
Automotive electrification and industrial automation reshoring are reallocating demand share across end-use categories at divergent rates.
- Automotive Electronics:Battery management systems, motor inverters, and onboard chargers in electric vehicles demand AEC-Q200 qualified current-sense and snubber resistors with thermal cycling endurance above 1000 cycles. Tier-1 module builders in Japan and South Korea are consolidating approved manufacturer lists with direct procurement clauses, bypassing traditional distribution channels.
- Industrial Equipment:Variable frequency drives, servo motors, and power supplies for factory automation require high-power wirewound resistors with pulse-energy ratings above 10 joules. German and Japanese equipment manufacturers are expanding captive procurement to secure supply chains against nickel alloy feedstock volatility.
- Medical Devices:Implantable cardioverter-defibrillators and infusion pumps using biocompatible precision resistors with established FDA 510(k) documentation.
- Consumer Electronics:Audio amplifiers and power supplies facing rapid thick-film substitution in sub-5-watt applications.
Industrial equipment commands the most stable demand base; automotive electronics is climbing the fastest.
Size:
Legacy equipment replacement cycles and semiconductor packaging densification are pulling resistor dimensions in opposing directions.
- Small:Surface-mount formats below 3 watts with low-inductance geometries for wide-bandgap power electronics gate drives and snubber circuits. Silicon carbide switching frequencies above 100 kHz in EV inverters are forcing new winding configurations to minimize parasitic inductance.
- Medium:Axial and radial-lead constructions from 3-25 watts serving industrial motor controls and telecom power supplies.
- Large:Aluminum-housed and chassis-mount resistors above 50 watts for dynamic braking and load bank applications.
- Custom:Application-specific form factors matching obsolete dimensions for 20-30 year service life equipment in aerospace and defense systems.
Medium sizes retain volume leadership; small formats are gaining share fastest.
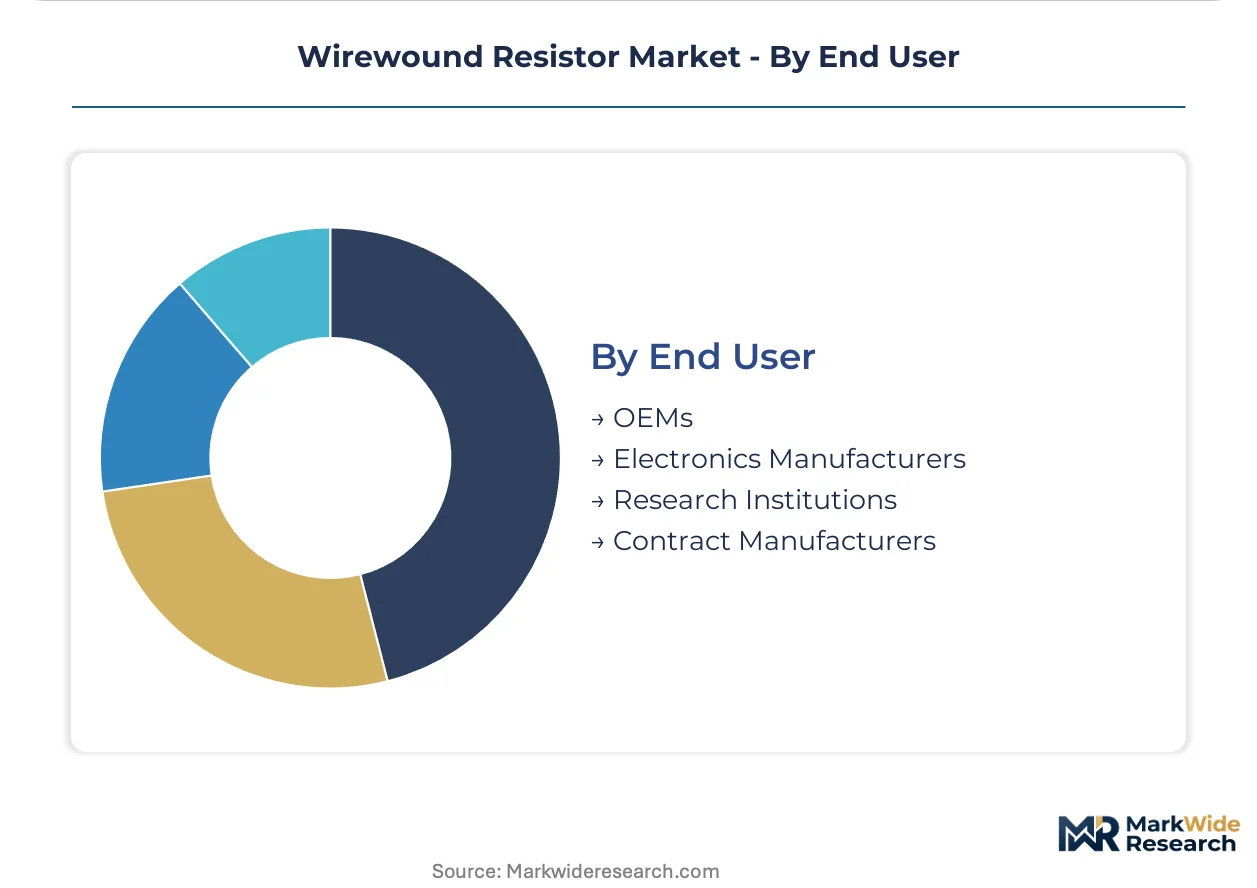
End User:
Procurement centralization and traceability mandates are restructuring buyer-supplier relationships across customer categories.
- OEMs:Automotive and industrial equipment builders with direct sourcing agreements, volume commitments, and technical collaboration clauses. NHTSA functional safety expectations aligned with ISO 26262 are elevating documentation burdens for resistor qualification.
- Electronics Manufacturers:Tier-2 board assembly houses serving multiple end markets with flexible volume requirements.
- Contract Manufacturers:Foxconn, Jabil, and Flex facilities absorbing standardized resistor volumes across consumer and industrial programs.
- Research Institutions:National laboratories and university engineering departments with small-batch, high-mix procurement patterns.
Electronics manufacturers retain volume leadership; OEMs are consolidating supplier relationships fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes in India and China's dual carbon goals are redirecting wirewound resistor manufacturing investments across Asia. The EU RoHS directive and REACH regulations are forcing European suppliers toward compliant alloy formulations. Demand clusters concentrate in automotive electronics hubs and industrial automation corridors.
China
Electric vehicle production in Shenzhen and Shanghai is absorbing precision current-sense resistors for battery management systems. MIIT's dual carbon goals are pressuring manufacturers toward energy-efficient winding processes. The Yangtze River Delta hosts dense concentrations of surface-mount wirewound production serving domestic automotive Tier-1 module builders.
Germany
Industrial automation reshoring in Bavaria and Baden-Württemberg is expanding captive procurement for motor control resistors. KBA functional safety expectations aligned with ISO 26262 are elevating qualification burdens on suppliers. The Stuttgart automotive cluster is consolidating approved manufacturer lists with direct sourcing clauses for EV inverter components.
United States
Wide-bandgap power electronics development in Silicon Valley and Austin is demanding low-inductance resistor geometries for silicon carbide applications. NHTSA traceability mandates are restructuring supplier relationships for automotive passive components. The Southeast manufacturing corridor is attracting resistor module assembly investments serving domestic appliance markets.
Japan
Automotive OEM technical collaboration clauses in Toyota City and Hiroshima are compressing traditional distribution channels. METI's supply chain security initiatives are encouraging backward integration into ceramic substrate production. The Nagoya industrial belt maintains specialized expertise in thick-film and wirewound hybrid constructions.
India
Domestic electronics manufacturing under the PLI scheme is expanding resistor consumption for appliance and automotive applications. BIS certification requirements are creating compliance barriers for imported components. The Gujarat and Tamil Nadu industrial corridors are attracting assembly investments from contract manufacturers serving export markets.
Wirewound Resistor Market Competitive Landscape
Player mix skews toward vertically integrated specialists and scale-driven Asian fabricators. The vendor base concentrates around three strategic tiers: premium-grade automotive suppliers with AEC-Q200 qualification, mid-market industrial specialists with captive alloy production, and high-volume consumer electronics houses competing on unit economics. Dominant competitive moves include backward integration into ceramic substrate manufacturing and direct procurement contracting with automotive OEMs bypassing distribution channels.
Among Japanese specialists, KOA Corporation exemplifies the premium-tier archetype through its hybrid thick-film and wirewound expertise. Vishay Intertechnology anchors the vertically integrated segment with in-house control over resistance wire and ceramic substrate production. Yageo occupies the scale-driven position operating large-format axial and surface-mount production lines serving Asian contract manufacturers. These three represent distinct competitive vectors rather than overlapping market positions.
| Leading Market Players |
|---|
| AVX Corporation |
| KOA Corporation |
| Vishay Intertechnology |
| Panasonic |
| Yageo |
| TE Connectivity |
| Cyntec |
| Hong Kong Resistors Manufactory |
| Ohmite Mfg Co |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with nickel-chromium alloy indexation lock in both supply access and price visibility for automotive Tier-1 module builders sourcing AEC-Q200 qualified resistors. These arrangements compress spot market exposure while binding manufacturers to volume commitments that stabilize feedstock procurement against Indonesian and Russian mining volatility.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate precision and high-power resistor procurement. Price differentiation hinges on AEC-Q200 certification grade and volume scale, with automotive OEM direct contracts commanding premiums over distributor-sourced volumes. Pricing pressure stems from thick-film substitution in sub-5-watt consumer electronics, eroding standard wirewound margins. Contract manufacturers exhibit highest price sensitivity; medical device OEMs with FDA Class III documentation requirements show lowest.
Supply Chain Analysis
China and Japan anchor ceramic substrate and resistance wire production for wirewound resistor manufacturing. Feedstock draws from Indonesian nickel mining and Chinese alumina refining, creating geographic concentration risks. Single-source vulnerability in nickel-chromium alloy supply threatens margin stability for precision grades. Distribution runs through authorized distributors serving industrial and medical segments, with direct procurement channels expanding fastest in automotive battery management systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical collaboration and qualification support services attach to hardware sales at expanding margins, with AEC-Q200 certification assistance and traceability documentation outpacing component revenue growth in automotive segments.
For Market Incumbents: Compound defensive positioning through backward integration into ceramic substrate production and captive resistance wire alloying to offset nickel feedstock volatility. Prioritize AEC-Q200 qualification investment to defend against thick-film hybrid substitutes encroaching on current-sense applications. Secure direct procurement clauses with Japanese and South Korean Tier-1 module builders to bypass distributor margin compression. For New Entrants and Emerging Players: Post-qualification technical support for mid-size German industrial automation OEMs represents a service-layer gap where established players under-serve. Target captive procurement expansion in Bavaria and Baden-Württemberg for motor control resistor replacement cycles. Lead with rapid custom form-factor matching for 20-30 year service life equipment in aerospace and defense aftermarket channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with in-house substrate and wire production. Long-term viability centers on qualification moats rather than scale economics, favoring targets with established FDA and ISO 26262 documentation libraries. Monitor REACH substance restriction timelines as inflection indicators for coating reformulation capex requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Production | Captive alumina supply insulates Vishay and KOA against commodity ceramic price swings. |
| AEC-Q200 Certification Investment | Automotive qualification opens direct procurement channels with Toyota and Hyundai Tier-1 suppliers. |
| REACH-Compliant Coating Transition | Zinc-aluminum termination plating conversion ahead of ECHA deadlines secures European market access. |
| Direct OEM Procurement Contracting | Bypassing Arrow and Avnet distribution captures margin in battery management system resistor sourcing. |
| Custom Form-Factor Development | Application-specific geometries for obsolete aerospace equipment defend replacement cycle revenue. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with resistor procurement managers at German automotive Tier-1 suppliers, Japanese industrial equipment OEMs, and Chinese contract manufacturers; and secondary validation through MIIT production statistics, ECHA REACH substance filings, customs trade records, and AEC-Q200 qualification databases. Bottom-up volume builds across product type, application, and size segments triangulated against top-down spending pattern analysis from industrial electronics and automotive electronics end-use categories.
The forecasting boundary spans the projection horizon with segmentation across standard, precision, high-power, and current sense product types; automotive, industrial, medical, and consumer electronics applications; and small, medium, large, and custom size formats. CAGRs derive from regression analysis of historical procurement patterns adjusted for EV inverter expansion rates and wide-bandgap power electronics adoption curves. Nickel alloy price volatility indices and semiconductor packaging densification trends inform sensitivity scenarios.
Forecasts assume regulatory continuity in EU REACH and RoHS regimes, FDA device classification stability, and NHTSA functional safety alignment with ISO 26262; material policy shifts in any of these would require re-modeling. Recalibration cycles align with substantive revisions to hazardous substance restrictions and automotive qualification standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Beryllium Copper for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
Galvanic Isolators Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
High Density Interconnect Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market