
 Global Passive Electronic Components Market | 2026-2036
Global Passive Electronic Components Market Size, Share, and Industry Trends Forecast 2026-2036
Global Passive Electronic Components Market Foresight
REACH substance restrictions is broadening the cost-of-entry calculus for passive component manufacturers serving European automotive and industrial clients. Yageo Corporation leverages its vertically integrated ceramic powder operations to absorb compliance costs internally. Panasonic Corporation anchors its competitive position through sustained R&D intensity in high-voltage film capacitor architectures. TDK Corporation dominates the multilayer ceramic capacitor segment through manufacturing scale across Japanese and Southeast Asian facilities.
Passive electronic components are non-powered circuit elements—resistors, capacitors, inductors, transformers, and varistors—that store, filter, or regulate electrical energy without amplification, typically specified by tolerance ratings, temperature coefficients, and equivalent series resistance. These components form the foundational layer of every electronic system, from smartphone motherboards to wind turbine inverters. Capacitors command the largest value share within component type segmentation, driven by proliferation of DC-link applications in renewable energy inverters and EV onboard chargers. Thin film technology leads precision applications in aerospace and defense, while ceramic formulations compete aggressively on cost in high-volume consumer electronics. Wirewound inductors sustain premium positioning in industrial automation where saturation current tolerance proves critical.
The EU Green Deal, RoHS recast, and China's GB standards collectively reshape material sourcing, mandating lead-free terminations and restricted substance documentation across supply chains. EMA and FDA requirements for medical device traceability further tighten lot-level certification demands on component vendors. Stakeholders must monitor regulatory divergence between European substance restrictions and Asian manufacturing standards when qualifying second-source suppliers.
Market Dynamics
Automotive electrification is compressing component qualification timelines while multiplying specification complexity, forcing suppliers to reconcile AEC-Q200 reliability standards with RoHS recast substance restrictions simultaneously.
Growth Catalysts
- EV Powertrain Expansion:DC-link capacitor demand from onboard chargers and inverters is pulling multilayer ceramic and film technologies into high-voltage architectures across automotive OEM supply chains.
- REACH Recast Compliance:European substance restrictions are creating competitive separation between suppliers with in-house material science capabilities and those dependent on external certification.
- Renewable Energy Deployment:Wind and solar inverter installations in China, Germany, and the United States are consuming high-capacitance film components for grid-stabilization applications.
Market Restraints
- Palladium and Nickel Volatility:Terminal plating materials face price swings that compress margin structures for mid-tier resistor and inductor manufacturers without captive metal sourcing.
- East Asian Foundry Concentration:Over 70% of multilayer ceramic capacitor substrate production sits in Japan and South Korea, creating geographic vulnerability to seismic or trade policy disruptions.
- Aluminum Electrolytic Substitution Ceiling:Solid polymer capacitors cannot match the energy density of wet aluminum designs in high-temperature industrial motor drives, limiting technology migration.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives and tariff structures are attracting passive component assembly operations to serve domestic smartphone and appliance production.
- Medical Device Traceability:FDA Unique Device Identification requirements and EMA lot-level certification demands create premium positioning for suppliers with serialized production systems.
- Silicon Carbide Convergence:Pairing wide-bandgap semiconductors with low-ESR ceramic capacitors enables faster switching frequencies that reduce magnetics size in compact power converters.
Industry Challenges
- AEC-Q200 Certification Timelines:Automotive qualification cycles spanning 18-24 months delay revenue recognition for new component families and strain R&D cash conversion.
- Legacy System Integration Friction:Industrial automation retrofit projects require pin-compatible replacements that match obsolete through-hole form factors, constraining design freedom for surface-mount innovations.
- Cross-Border Documentation Complexity:Divergent substance declaration formats between REACH SCIP database entries, China GB standards, and US TSCA reporting create compliance overhead for multi-territory suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Passive Electronic Components Market |
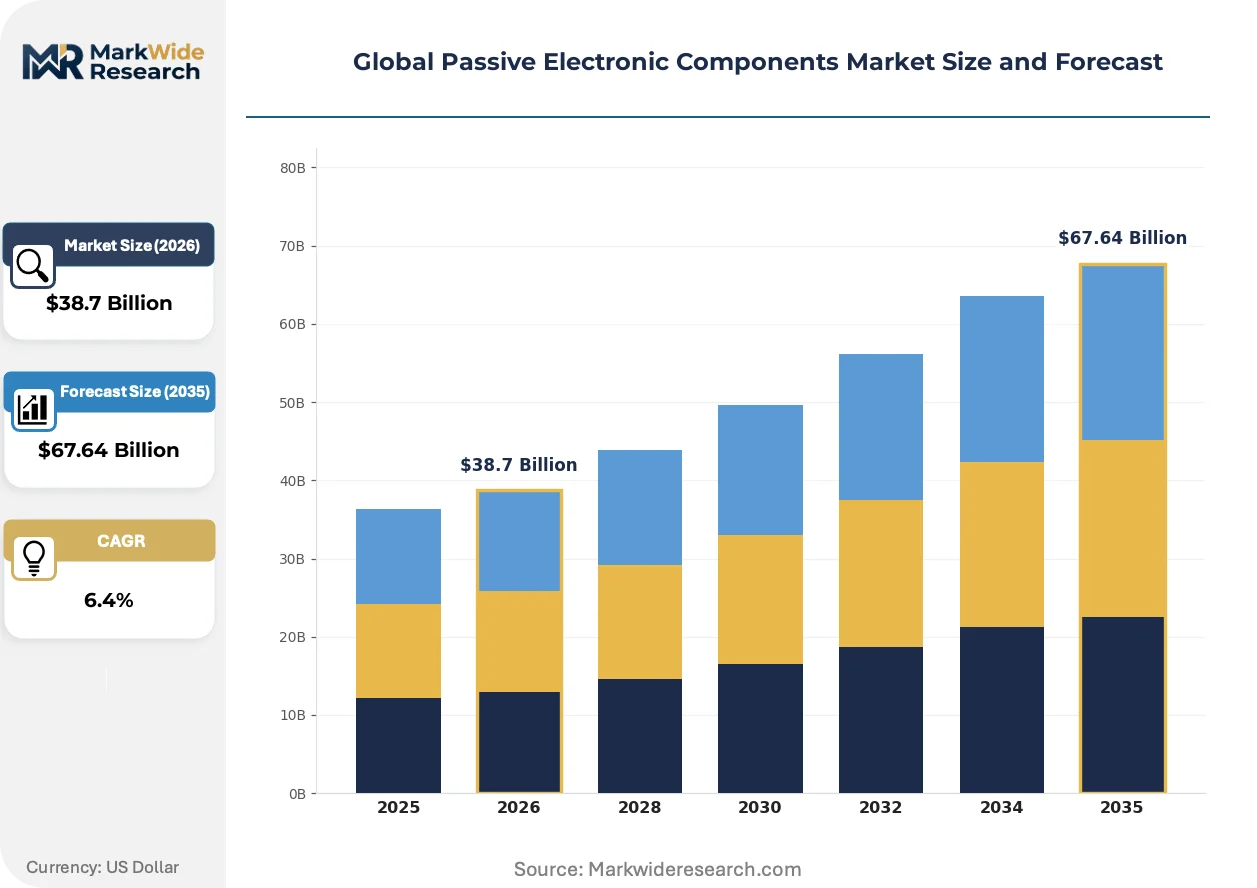
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Resistors, Capacitors, Inductors, Transformers, Varistors Technology: Thin Film, Thick Film, Metal Oxide, Ceramic, Wirewound Application: Consumer Electronics, Aerospace & Defense, Telecommunications, Industrial Automation, Renewable Energy End User: Original Equipment Manufacturers, Electronics Contract Manufacturers, System Integrators, Aftermarket Suppliers |
| Companies Covered | Yageo Corporation, Panasonic Corporation, Murata Manufacturing Co. Ltd., Samsung Electro-Mechanics Co. Ltd., KYOCERA AVX Components Corporation, TDK Corporation, Taiyo Yuden Co. Ltd., TE Connectivity, Vishay Intertechnology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Passive Electronic Components Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are redefining competitive advantage around environmental compliance integration rather than standalone performance metrics.
Nickel-barrier termination metallization is overtaking traditional silver-palladium systems in high-reliability automotive applications. Tier-1 suppliers are adopting this architecture to eliminate silver migration risks under humid operating conditions. The shift is compressing qualification timelines for new ceramic capacitor families while raising the technical bar for second-source approvals.
REACH SCIP database requirements are mandating supply chain transparency for articles containing candidate list substances above threshold limits. Component vendors must now map sub-supplier material flows to satisfy downstream OEM documentation obligations. Medical device and industrial automation segments are experiencing the steepest compliance cost escalation as lot-level traceability becomes non-negotiable.
Consolidated procurement functions at major automotive and renewable energy OEMs are unbundling component specification from logistics execution. Category managers now issue engineering-approved vendor lists that purchasing executes through contracted distributors, compressing direct sales relationships. This pattern is most pronounced in Germany and Japan, where keiretsu-style supplier development programs have historically dominated component selection processes.
Global Passive Electronic Components Market Segmentation
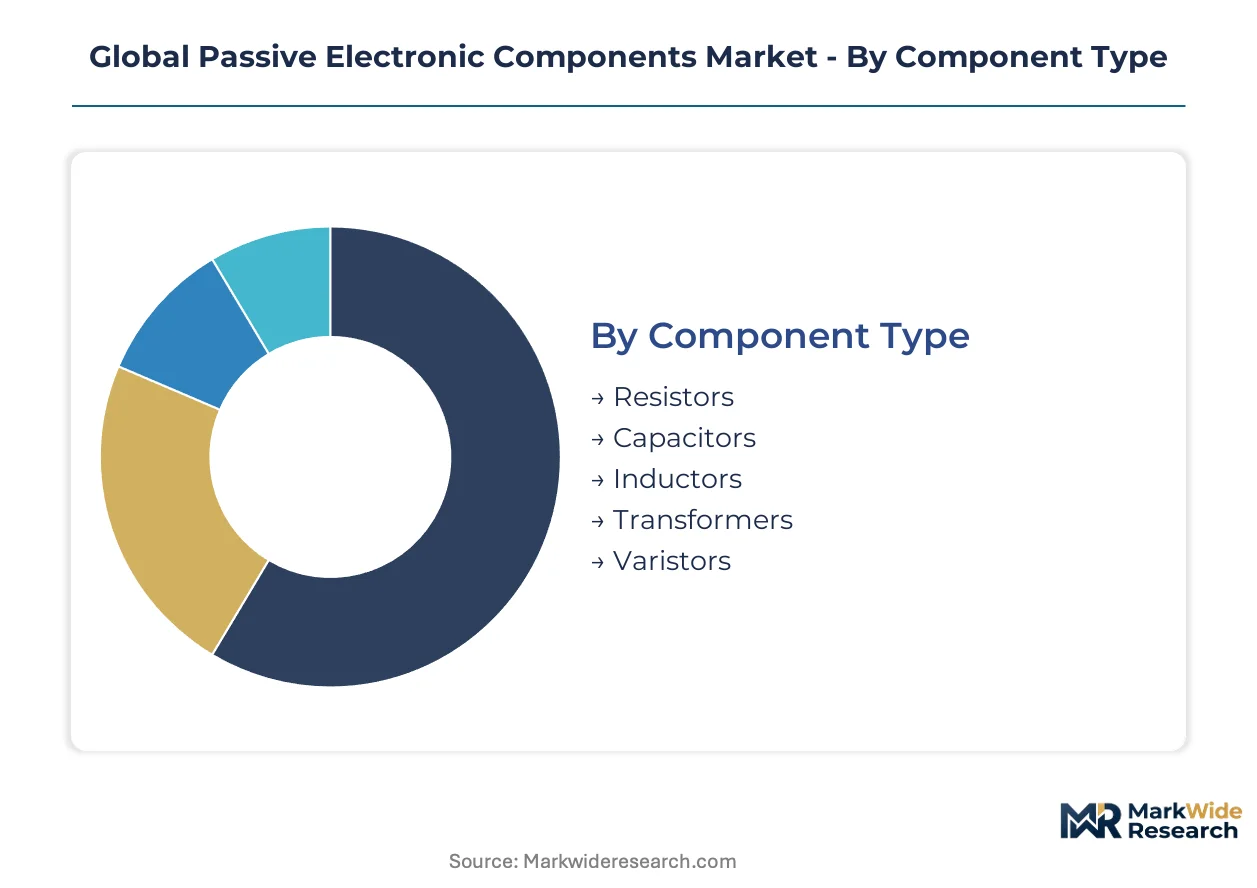
Component segmentation in passive electronics reveals divergent margin structures across material technologies and qualification tiers. Automotive and renewable energy applications are compressing specification windows while fragmenting procurement channels.
Component Type:
Capacitors command volume dominance while resistors compete on price density across high-volume consumer electronics.
- Capacitors:Electrochemical energy storage devices specified by capacitance value, voltage rating, and equivalent series resistance. DC-link applications in EV onboard chargers and solar inverters in Germany and China are pulling multilayer ceramic and film formulations into high-voltage architectures. The segment absorbs the largest material science R&D allocation across tier-1 suppliers.
- Resistors:Passive two-terminal components dissipating electrical energy as heat, characterized by resistance value, tolerance, and temperature coefficient. Precision thin-film variants serve aerospace calibration requirements in France and the United States while thick-film carbon compositions dominate cost-sensitive smartphone production in India and Vietnam.
- Inductors:Magnetically coupled coils storing energy in electromagnetic fields, specified by inductance value and saturation current. Wirewound constructions maintain premium positioning in industrial motor drives where core saturation tolerance proves critical.
- Transformers:Magnetically coupled inductor pairs enabling voltage conversion and galvanic isolation. High-frequency planar designs serve compact switch-mode power supplies in telecommunications infrastructure.
- Varistors:Voltage-dependent resistors clamping transient overvoltage events, specified by clamping voltage and energy absorption capacity. Metal-oxide formulations protect grid-tied inverter installations against lightning-induced surges.
Today's leader: Capacitors. Tomorrow's challenger: Inductors.
Technology:
Thin film precision commands 3-5x pricing multiples over thick film commodity production, with ceramic formulations capturing intermediate positioning.
- Thin Film:Vacuum-deposited metal layers on ceramic substrates achieving tight tolerance and low temperature coefficient. Sputtered nichrome and tantalum nitride systems serve satellite avionics in the United States and medical imaging equipment requiring drift stability below 25 ppm per degree Celsius.
- Thick Film:Screen-printed resistive and conductive pastes fired on alumina substrates. Ruthenium oxide compositions balance cost against performance in automotive sensor modules and white goods control boards.
- Metal Oxide:Tin oxide and zinc oxide ceramic formulations providing nonlinear voltage-current characteristics. These materials form the functional core of surge protection devices in wind turbine installations.
- Ceramic:Barium titanate and related perovskite dielectrics enabling high volumetric efficiency in multilayer capacitor stacks. Japanese and South Korean manufacturers concentrate substrate production for Class II dielectric formulations serving consumer electronics.
- Wirewound:Conductive wire coils wound on ceramic or ferrite cores achieving high inductance with precise saturation characteristics. These constructions sustain industrial automation applications where magnetic core tolerance determines system reliability.
Thin film holds premium positioning. Ceramic scales fastest.
Application:
Automotive electrification and renewable energy deployment are reshaping application mix toward high-reliability qualification tiers.
- Consumer Electronics:Smartphones, laptops, and wearable devices consuming compact surface-mount components in billion-unit annual volumes. Chinese OEM procurement is consolidating around qualified vendor lists with AEC-Q200-adjacent reliability requirements even for non-automotive applications.
- Aerospace & Defense:Satellite systems, radar platforms, and avionics requiring MIL-PRF qualification and extended temperature range performance. Thin-film precision resistors and hermetic capacitors serve mission-critical signal conditioning in United States and European defense programs.
- Telecommunications:Base station infrastructure and optical networking equipment requiring high-frequency passive performance. 5G massive MIMO deployments in South Korea and Germany are pulling low-loss ceramic and precision RF inductor technologies.
- Industrial Automation:Motor drives, programmable logic controllers, and power conversion systems. Wirewound inductors and high-voltage film capacitors sustain operation in harsh factory environments with extended thermal cycling.
- Renewable Energy:Solar inverters, wind turbine converters, and energy storage systems. DC-link film capacitors from German and Chinese installations dominate procurement volumes for grid-stabilization applications.
Renewable energy claims steepest expansion trajectory. Consumer electronics retains volume crown.
End User:
Procurement authority is concentrating at consolidated OEM category management functions while distributor relationships handle logistics execution.
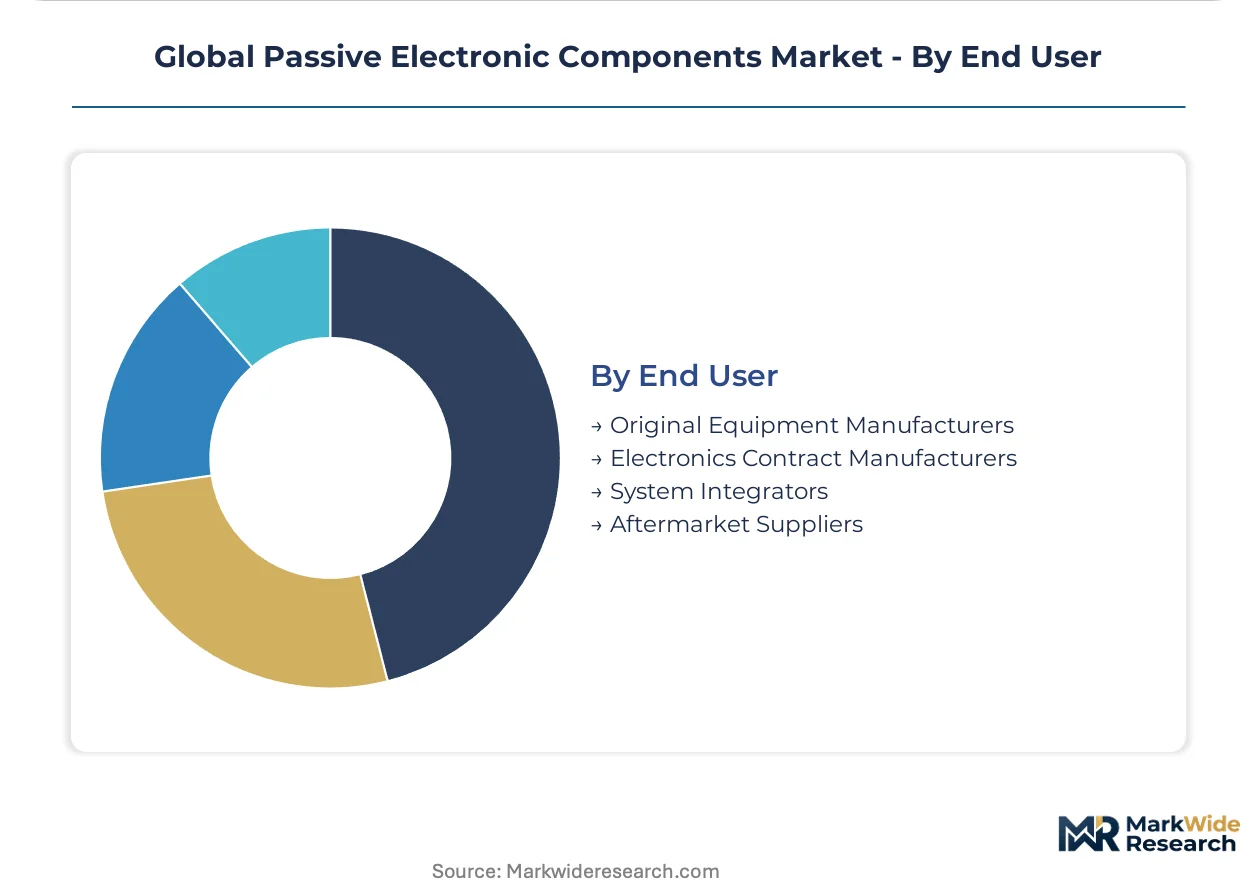
- Original Equipment Manufacturers:Automotive, industrial, and consumer electronics brands specifying components through engineering-approved vendor lists. Volkswagen, Siemens, and Apple procurement organizations unbundle technical qualification from purchasing execution.
- Electronics Contract Manufacturers:Foxconn, Jabil, and Flex facilities consuming passives in assembly operations across Mexico, Poland, and Vietnam. These intermediaries buffer inventory positions against OEM demand volatility.
- System Integrators:Industrial automation and renewable energy project developers specifying component portfolios for customized power conversion and control systems.
- Aftermarket Suppliers:Repair and replacement channels serving industrial maintenance operations and consumer electronics service networks. Traceability requirements from FDA and EMA are tightening documentation obligations for medical device component vendors.
OEMs control specification authority. Contract manufacturers intermediate physical flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean manufacturing clusters anchor the industry's technical workforce concentration, with Chinese production scaling fastest across capacitor and inductor substrate operations.
Japan
Multilayer ceramic capacitor substrate production concentrates in Nagoya and Kyoto prefectures, serving automotive OEM qualification pipelines. METI's dual carbon goals and JIS standards compliance reshape material sourcing for high-reliability component families. TDK Corporation and Murata Manufacturing anchor manufacturing scale across Chubu and Kansai industrial corridors.
South Korea
Samsung Electro-Mechanics and passive component suppliers feed DC-link demand from Hyundai-Kia EV powertrain programs. MFDS medical device traceability requirements and K-Battery regulations extend certification obligations to component vendors. Busan-Ulsan manufacturing complexes dominate film capacitor output for renewable energy inverter exports.
China
GB standards compliance and dual carbon targets accelerate lead-free termination adoption across Shenzhen and Suzhou production bases. Domestic EV brands BYD and NIO compress component qualification timelines while expanding procurement volumes. Yangtze River Delta clusters absorb the largest capacity additions for multilayer ceramic manufacturing.
Germany
Volkswagen, BMW, and Siemens procurement functions unbundle technical specification from logistics execution through consolidated category management. REACH SCIP database mandates and RoHS recast substance restrictions tighten documentation overhead for automotive component suppliers. Bavaria and Baden-Württemberg host the densest concentration of industrial automation and renewable energy system integrators.
United States
Defense and aerospace programs in California and Texas sustain demand for thin-film precision resistors with MIL-PRF qualification. FDA Unique Device Identification requirements and EPA substance reporting create compliance layering for medical device component vendors. Department of Energy grid modernization funding accelerates film capacitor procurement for utility-scale solar and wind installations.
Global Passive Electronic Components Market Competitive Landscape
The competitive structure tilts toward vertically integrated material science specialists with captive ceramic powder and metal terminal operations. Japanese and South Korean conglomerates dominate multilayer ceramic capacitor manufacturing through manufacturing scale and AEC-Q200 qualification density. Three archetypes define positioning: integrated material science conglomerates controlling upstream dielectric formulations, precision specialists serving aerospace and medical qualification tiers, and high-volume assemblers competing on cost in consumer electronics. Capacity expansion and backward integration into ceramic powder production represent the dominant competitive moves as suppliers absorb REACH compliance costs internally.
Among Japanese material science conglomerates, TDK Corporation, Murata Manufacturing Co. Ltd., and Panasonic Corporation exemplify the integrated archetype through in-house control over barium titanate dielectric formulations and termination metallization. These entities occupy positions where AEC-Q200 certification density and RoHS recast compliance capabilities create separation from second-source competitors. Yageo Corporation and Samsung Electro-Mechanics Co. Ltd. represent scale-driven challengers expanding through manufacturing footprint additions in Southeast Asia and China. KYOCERA AVX Components Corporation, Taiyo Yuden Co. Ltd., and Vishay Intertechnology Inc. sit within precision-specialist positioning where MIL-PRF and medical-grade qualification sustain pricing premiums. TE Connectivity occupies a hybrid position bridging industrial automation and automotive connector-adjacent passive integration.
| Leading Market Players |
|---|
| Yageo Corporation |
| Panasonic Corporation |
| Murata Manufacturing Co. Ltd. |
| Samsung Electro-Mechanics Co. Ltd. |
| KYOCERA AVX Components Corporation |
| TDK Corporation |
| Taiyo Yuden Co. Ltd. |
| TE Connectivity |
| Vishay Intertechnology Inc. |
| Others |
Supply & Pricing Matrix
Captive ceramic powder production anchors both cost absorption capacity and pricing power for tier-1 Japanese and South Korean suppliers serving AEC-Q200 qualification pipelines. Backward integration into barium titanate dielectric formulations allows TDK Corporation and Murata Manufacturing to internalize REACH compliance costs while mid-tier competitors face margin compression from external certification dependencies.
Pricing Analysis
Unbundled component specification from logistics execution defines the dominant pricing split, with Volkswagen and Siemens procurement functions issuing engineering-approved vendor lists that purchasing executes through contracted distributors. Three-tier pricing structure across AEC-Q200 automotive, industrial-grade, and consumer electronics levels separates qualification-intensive film capacitors from commodity ceramic stacks. Cost compression in standard-grade multilayer ceramic capacitors intensifies as Chinese OEMs consolidate procurement around qualified vendor lists. Contract manufacturers at Foxconn and Jabil facilities exhibit the highest price sensitivity, while aerospace and medical device buyers prioritize MIL-PRF and FDA lot-level certification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle automotive and renewable energy demand, while distributor relationships manage logistics execution for contract manufacturers and aftermarket suppliers. Substrate production concentrates in Japan, South Korea, and China, with Nagoya and Kyoto prefectures hosting multilayer ceramic capacitor manufacturing clusters. Palladium and nickel terminal plating materials, plus barium titanate dielectric powders, constitute critical input dependencies. Single-source vulnerability in Japanese and South Korean substrate operations creates geographic concentration risk from seismic events or trade policy disruptions. Distribution runs through consolidated category management functions at automotive OEMs and specialized industrial distributors serving medical device traceability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as automotive electrification and renewable energy deployment shift procurement toward AEC-Q200 and high-voltage film capacitor specifications that reward in-house material science capabilities.
For Market Incumbents: Extend AEC-Q200 certification density across multilayer ceramic capacitor families to defend against emerging Chinese suppliers with GB standards compliance but limited automotive qualification track records. Deepen backward integration into nickel-barrier termination metallization to eliminate silver-palladium cost volatility and compress second-source approval timelines for new ceramic formulations.
For New Entrants and Emerging Players: Capture India electronics manufacturing demand under PLI scheme incentives, where domestic smartphone and appliance production lacks qualified passive component assembly capacity. Target medical device traceability segments requiring FDA Unique Device Identification and EMA lot-level certification, as incumbent suppliers struggle with serialized production system investments. Lead with REACH SCIP database documentation capabilities as a differentiated service layer.
For Investors and Strategic Acquirers: Roll-up economics work for precision-specialist passive component manufacturers because aerospace and medical device qualification tiers sustain 3-5x pricing multiples over commodity production with limited customer concentration risk. Target mid-cap suppliers with MIL-PRF certification and captive thin-film sputtering capabilities. Watch silicon carbide power semiconductor adoption rates as the inflection signal for low-ESR ceramic capacitor demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Production | Captive barium titanate supply internalizes REACH compliance costs for European automotive clients. |
| AEC-Q200 Certification Expansion | Extended qualification density creates competitive separation from emerging Chinese suppliers. |
| Serialized Production System Deployment | FDA and EMA lot-level traceability mandates drive premium positioning in medical device segments. |
| India Manufacturing Footprint Addition | PLI scheme incentives attract assembly operations to serve domestic smartphone production. |
| Silicon Carbide Power Module Partnership | Low-ESR ceramic capacitor pairing enables faster switching frequencies in compact converters. |
Research Methodology
Coverage spans Japan, South Korea, China, Germany, and the United States, with primary inputs from each market cluster. Primary interviews with passive component procurement directors at automotive OEMs, regulatory affairs leads managing REACH SCIP compliance, and plant managers at multilayer ceramic capacitor facilities combined with secondary validation from METI production statistics, ECHA substance restriction updates, SEC 10-K filings from listed suppliers, and customs data on capacitor and inductor trade flows. Bottom-up demand modeling from EV powertrain and renewable energy inverter deployments triangulates against top-down market sizing from industry association reports.
Rate-of-change decomposition separates volume growth from value mix shifts across the projection horizon. The analytical framework models component type, technology tier, application segment, and end-user channel dimensions alongside regional regulatory cluster effects. CAGRs derive from regression analysis of historical production data against EV penetration curves and renewable energy installation forecasts. Silicon carbide semiconductor adoption rates and REACH recast substance restriction timelines serve as key industry-specific forecast inputs.
Raw material price volatility, automotive qualification timeline delays, and regulatory divergence between European substance restrictions and Asian manufacturing standards are the dominant revision risks. Forecasts reflect assumptions about EV powertrain expansion trajectories and renewable energy deployment rates that warrant periodic reassessment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Wirewound Variable Resistors Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Elastomeric Connectors Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Ultra-Thin Electronic PI Film Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market