
 Beryllium Copper for Consumer Electronics Market | 2026-2036
Beryllium Copper for Consumer Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Beryllium Copper for Consumer Electronics Market Insights
Procurement strategy among consumer electronics OEMs is shifting from single-source beryllium copper contracts toward qualified multi-source arrangements. Materion leverages captive mining and refining assets in Utah to sustain supply security for North American connector makers. NGK Insulators anchors Japanese domestic demand through long-term supply agreements with precision spring manufacturers. IBC Advanced Alloys competes on custom alloy formulations for aerospace-grade reliability specifications that downstream electronics vendors increasingly require.
Beryllium copper designates a family of precipitation-hardenable copper alloys containing beryllium in concentrations from 0.2% to 2.0%, achieving tensile strengths exceeding 200,000 psi after age-hardening heat treatment while retaining electrical conductivity superior to steel alternatives. Manufacturers deploy these alloys where repeated mechanical cycling, corrosion resistance, and stable contact resistance converge in miniature electronic assemblies. Alloy 25 dominates connector pin production due to its optimal strength-conductivity balance, while Alloy 190 captures expanding relay and switch applications demanding higher fatigue resistance. Wire form shipments to spring coiling operations represent the fastest-growing consumption channel as wearable device architectures proliferate.
OSHA enforces permissible exposure limits for beryllium in U.S. fabrication facilities, compelling investment in local exhaust ventilation and worker monitoring programs that elevate production costs. REACH registration requirements in the European Union constrain alloy import volumes and mandate supply chain disclosure for beryllium content above threshold concentrations. China's GB standards for hazardous substance restriction in electronic products align with international RoHS directives, creating compliance convergence across major manufacturing jurisdictions. Stakeholders must monitor evolving particulate exposure regulations and pre-position recycling infrastructure ahead of anticipated end-of-life material recovery mandates.
Market Dynamics
REACH restrictions on beryllium compounds in the European Union are compressing alloy import volumes while simultaneously accelerating closed-loop recycling infrastructure investments among European fabricators. This regulatory pressure is restructuring supply relationships across the value chain.
Growth Catalysts
- Miniaturization imperatives:Smartphone connector assemblies below 0.35mm pitch specifications require precipitation-hardenable copper alloys that retain fatigue resistance under mechanical cycling stress.
- OSHA exposure protocols:U.S. fabrication facilities investing in local exhaust ventilation and worker monitoring programs are qualifying for preferred supplier status among medical device and aerospace-tier electronics vendors.
- Pearl River Delta concentration:Contract manufacturers serving Apple, Samsung, and domestic Chinese OEMs are consolidating beryllium copper procurement through designated alloy service centers to reduce inbound logistics variance.
Market Restraints
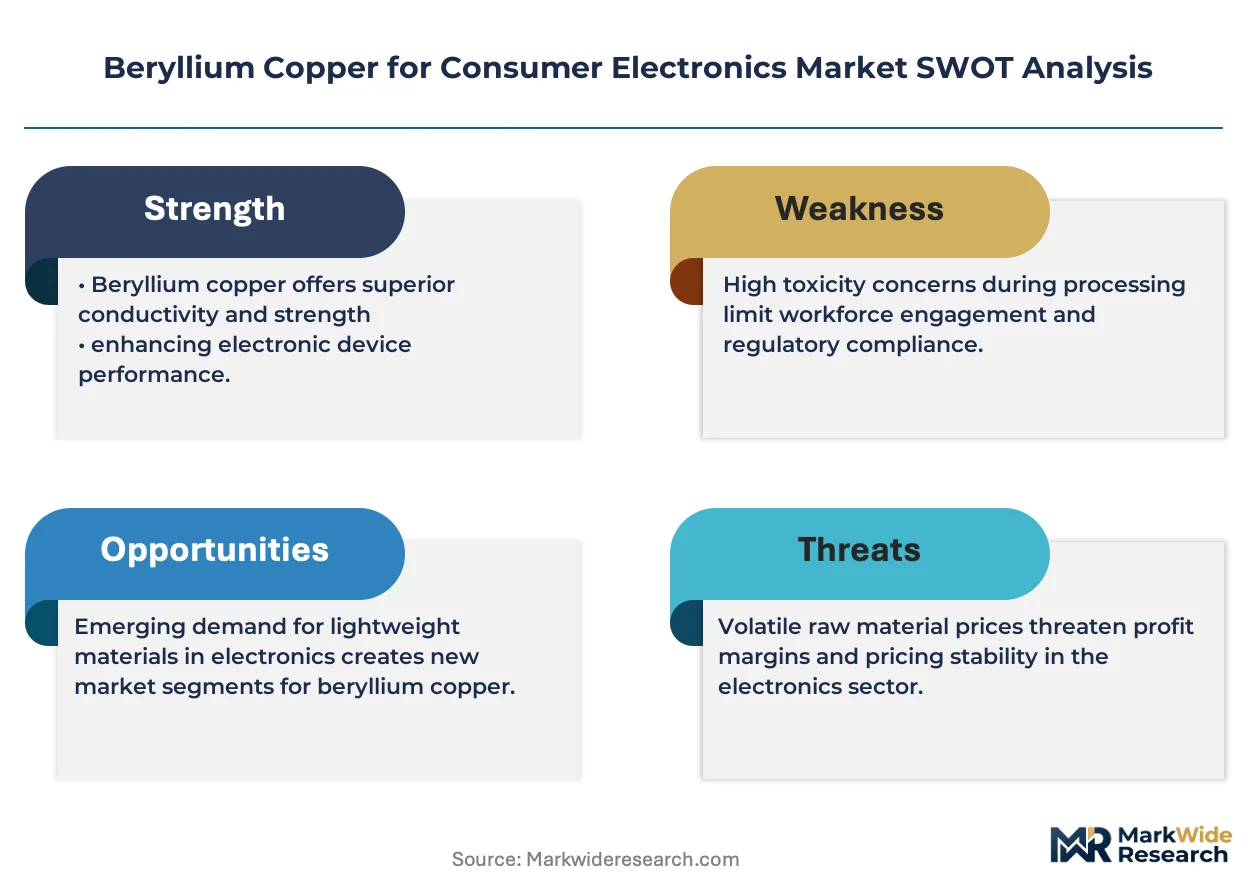
- Beryllium oxide toxicity:Particulate exposure limits during melting and machining operations elevate capital expenditure requirements for ventilation systems and personal protective equipment.
- Utah supply concentration:Captive mining and refining assets controlled by dominant North American producers create single-source vulnerability for connector makers without qualified secondary suppliers.
- Aluminum bronze substitution:Lower-cost copper alloys with comparable electrical conductivity are capturing relay and switch applications where fatigue resistance specifications permit material relaxation.
Strategic Opportunities
- Wearable device architectures:Wire form shipments to precision spring coiling operations are expanding as hearables and health-monitoring wearables proliferate form factors requiring sub-millimeter contact elements.
- GB standards alignment:China's hazardous substance restriction frameworks harmonizing with international RoHS directives are enabling export-qualified domestic producers to capture regional contract manufacturing flows.
- Closed-loop recovery mandates:Anticipated end-of-life material recovery regulations across multiple jurisdictions are creating first-mover advantage for alloy producers pre-positioning recycling infrastructure ahead of compliance deadlines.
Industry Challenges
- Age-hardening process control:Precipitation heat treatment cycles requiring tight temperature tolerance windows demand specialized furnace operators whose training pipelines have narrowed as semiconductor fabrication competes for metallurgical talent.
- Multi-source qualification timelines:Electronics OEMs shifting from single-source contracts toward qualified alternative suppliers face 18-24 month validation cycles for alloy chemistry consistency and lot-to-lot mechanical property stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beryllium Copper for Consumer Electronics Market |
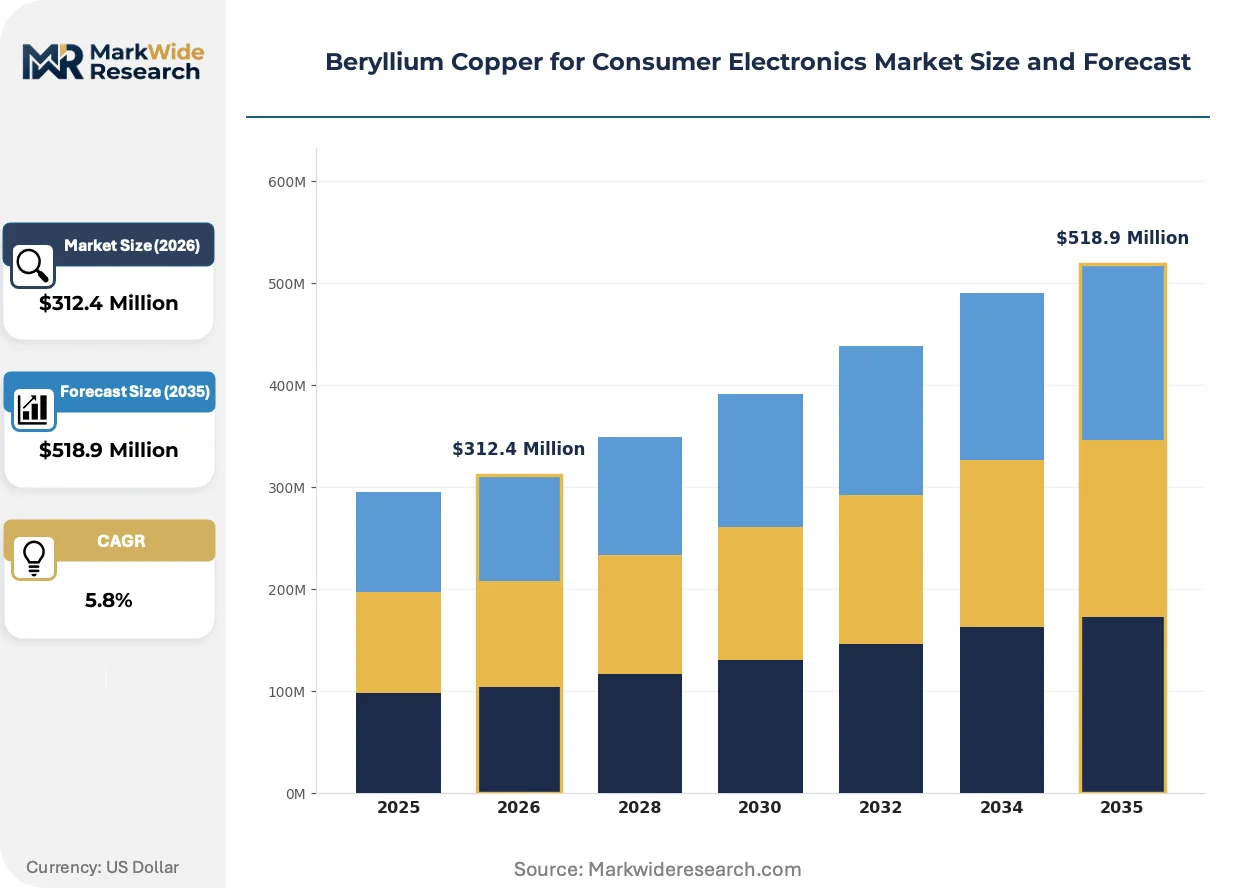
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy 25, Alloy 175, Alloy 190, Alloy 165 Application: Connectors, Springs, Switches, Relays End User: OEMs, Aftermarket Suppliers, Tier-1 Vendors, Contract Manufacturers Form: Sheets, Plates, Rods, Wire |
| Companies Covered | Materion, NGK Insulators, Kazatomprom, Aviva Metals, IBC Advanced Alloys, Belmont Metals, AMPCO Metal, China Minmetals Beryllium, JinDian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beryllium Copper for Consumer Electronics Market Trends and Innovations
Alloy formulation precision and regulatory compliance automation are converging to reshape competitive positioning among beryllium copper suppliers serving electronics miniaturization requirements.
Ultra-fine wire drawing capabilities below 50 micrometer diameters are rewriting connector design constraints for next-generation device architectures. Medical implantable electronics manufacturers are adopting these wire forms for hermetic feedthrough assemblies at accelerated qualification paces. This capability compression is enabling sub-millimeter pitch connectors previously unachievable with conventional alloy processing.
REACH registration requirements for beryllium content disclosure above threshold concentrations are mandating supply chain transparency investments across European import channels. Alloy producers are deploying blockchain-traceable lot documentation to satisfy ECHA compliance verification. Electronics assemblers in Germany and France are most affected, responding by consolidating supplier relationships with registrant-compliant mills.
Multi-source qualification arrangements are displacing legacy single-source contracting among consumer electronics OEMs with substantial procurement volumes. Designated service centers with metallurgical laboratory capabilities are capturing distributor functions previously held by raw material merchants. This channel restructuring is most visible in China's Pearl River Delta manufacturing cluster where contract manufacturers face compressed switching timelines between qualified alloy suppliers.
Beryllium Copper for Consumer Electronics Market Segmentation
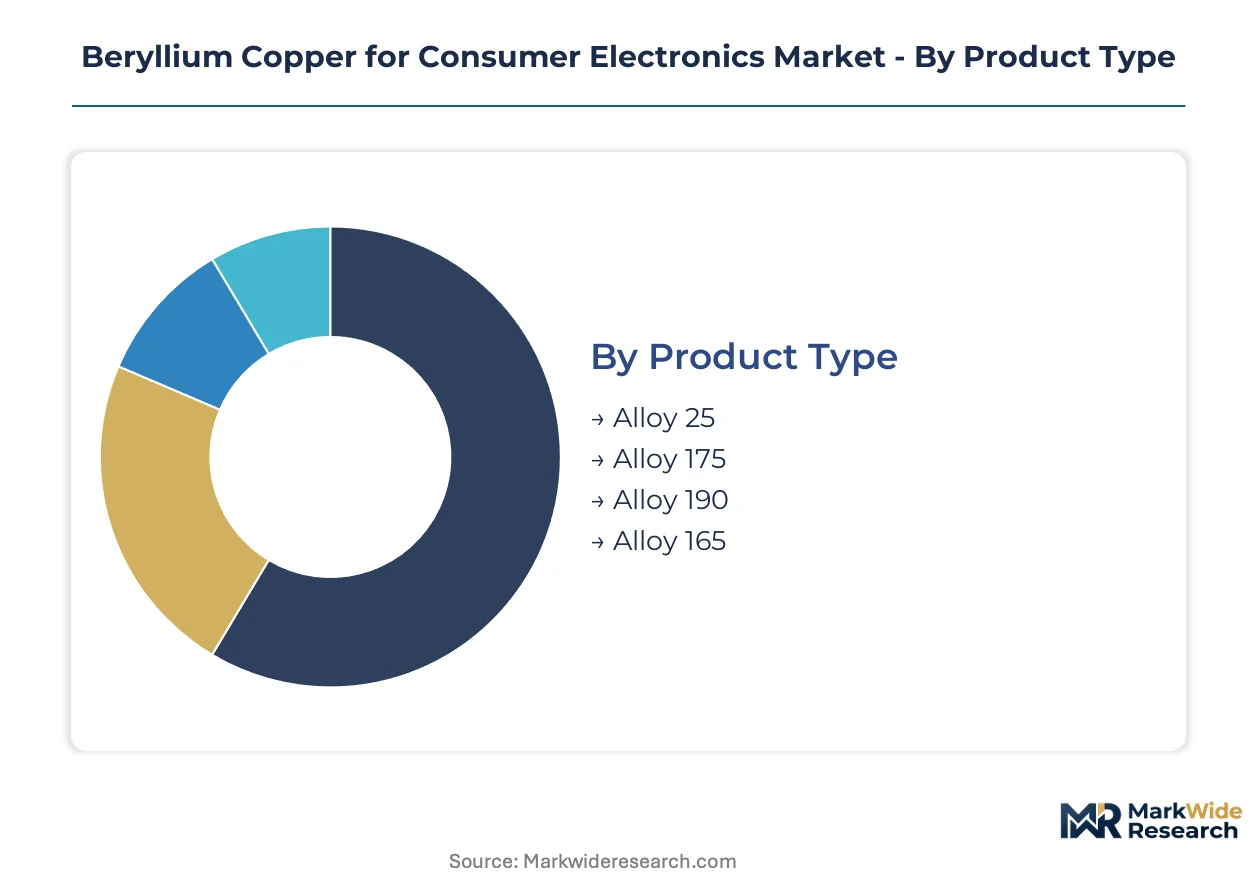
Beryllium copper alloys serve electronics manufacturers through differentiated material specifications that balance conductivity against mechanical fatigue resistance. Each segmentation dimension reveals distinct procurement patterns and technical qualification requirements that shape supplier relationships across the value chain.
Product Type:
The customization-to-standardization spectrum spans from high-beryllium formulations demanding precise age-hardening control to lower-beryllium variants suited for less critical electrical contacts.
- Alloy 25:Contains 1.8-2.0% beryllium with cobalt additions, achieving tensile strengths exceeding 200,000 psi after precipitation hardening. Connector pin manufacturers in China's Pearl River Delta specify this grade for sub-0.35mm pitch smartphone assemblies where mechanical cycling durability is paramount.
- Alloy 190:Formulated with higher beryllium content and optimized for fatigue resistance under repeated deflection stress. Relay and precision switch producers in Japan's precision component sector favor this specification for miniature contact elements in automotive-grade electronics.
- Alloy 175:Moderate beryllium concentration offering balanced conductivity and formability for general-purpose electrical contacts.
- Alloy 165:Lower beryllium content variant selected where cost sensitivity outweighs peak mechanical performance requirements.
Leading the category by volume: Alloy 25. Expanding most quickly: Alloy 190.
Application:
Cost tier stratification separates high-reliability aerospace-medical specifications from consumer-grade commodity applications with relaxed qualification protocols.
- Connectors:Miniaturized pin-and-socket assemblies for smartphones, tablets, and wearable devices. Demand concentrates in Shenzhen and Dongguan contract manufacturing facilities serving Apple and Samsung procurement specifications.
- Springs:Precision coiled contact elements requiring sub-millimeter wire forms. Hearables and health-monitoring wearables are driving wire form consumption as device architectures shrink.
- Switches:Toggle and pushbutton contacts where stable resistance through mechanical cycling is essential.
- Relays:Electromechanical switching elements for power management circuits in consumer electronics.
Connectors dominate procurement volumes. Springs demonstrate the steepest expansion trajectory.
End User:
Customer type segmentation tracks procurement sophistication from captive alloy service centers to fragmented aftermarket distributors.
- OEMs:Apple, Samsung, and domestic Chinese brands qualify multiple alloy sources through 18-24 month validation cycles for chemistry consistency and lot stability.
- Contract Manufacturers:Foxconn, Luxshare, and comparable assemblers in the Pearl River Delta consolidate beryllium copper procurement through designated service centers to reduce inbound logistics variance.
- Tier-1 Vendors:Precision connector and relay specialists supplying directly to OEM assembly lines with certified quality systems.
- Aftermarket Suppliers:Replacement component distributors serving repair and refurbishment channels with less stringent material traceability requirements.
Contract manufacturers lead by volume. OEMs are gaining share fastest as vertical integration pressures intensify.
Form:
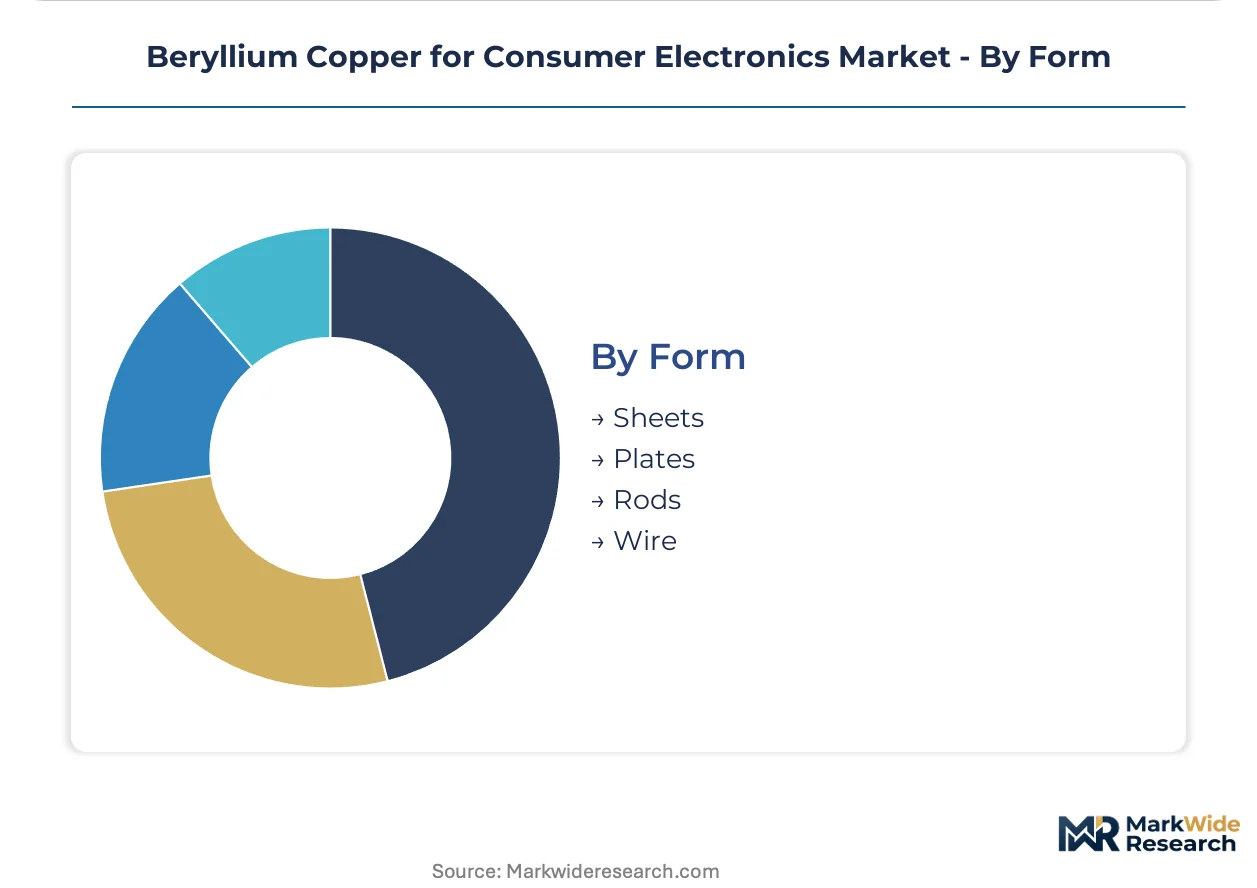
Supply concentration varies by processing complexity, with ultra-fine wire drawing capabilities below 50 micrometers held by limited qualified suppliers.
- Wire:Drawn to sub-50 micrometer diameters for spring coiling and miniature connector pins. Medical implantable electronics manufacturers are accelerating qualification of these wire forms for hermetic feedthrough assemblies.
- Rods:Round bar stock for machined contact components and pin headers in industrial-grade connectors.
- Sheets:Rolled strip for stamped contact fingers and EMI shielding applications.
- Plates:Thicker flat stock for structural components and heat sink interfaces in power electronics.
Wire leads the category by volume. Rods are climbing the fastest as automotive-electronics crossover applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utah's captive beryllium mining and refining operations anchor North American supply security for connector manufacturers. China's Pearl River Delta electronics cluster concentrates downstream fabrication demand. Regulatory divergence across major manufacturing jurisdictions is reshaping alloy procurement geography.
United States
OSHA enforces permissible exposure limits for beryllium in fabrication facilities, compelling investment in local exhaust ventilation and worker monitoring programs. The EPA coordinates with state agencies to oversee hazardous air pollutant standards for secondary smelting operations. Utah's Spor Mountain mining complex and Elmore refining assets supply Materion's captive vertical integration, serving connector makers in California's Silicon Valley and Texas semiconductor corridors.
China
GB standards for hazardous substance restriction in electronic products align with international RoHS directives, creating compliance convergence for export-qualified producers. The Ministry of Ecology and Environment enforces dual carbon goals that elevate energy costs for alloy melting operations. Shenzhen and Dongguan contract manufacturers serving Apple, Samsung, and domestic OEMs consolidate procurement through designated service centers to reduce inbound logistics variance.
Japan
METI oversees industrial standards for copper alloy specifications in precision electronics applications. The PMDA regulates material biocompatibility for medical device crossover applications. Nagoya and Osaka precision component manufacturers anchor domestic demand through long-term supply agreements with spring and relay specialists.
Germany
ECHA REACH registration requirements constrain alloy import volumes and mandate supply chain disclosure for beryllium content above threshold concentrations. The KBA influences automotive-electronics material specifications that cascade into consumer-grade component standards. Bavarian industrial electronics clusters are accelerating closed-loop recycling infrastructure investments ahead of anticipated end-of-life recovery mandates.
South Korea
MFDS regulates material traceability for electronics components with medical device adjacencies. The Seoul Capital Area concentrates smartphone and wearable device OEM headquarters that drive alloy specification requirements. Busan-Ulsan fabrication corridors host precision connector manufacturers qualifying wire forms for sub-millimeter pitch assemblies.
Beryllium Copper for Consumer Electronics Market Competitive Landscape
Multi-source qualification arrangements dominate the current landscape as procurement strategy shifts away from legacy single-source contracting. The vendor base organizes around three tiers: integrated miners with captive refining assets, specialized alloy formulators with metallurgical laboratory capabilities, and regional distributors with designated service center functions. Strategic archetypes include vertical integrators controlling upstream beryllium supply, custom formulation specialists serving aerospace-grade reliability specifications, and logistics-optimized service centers reducing inbound variance for contract manufacturers. Competitive moves concentrate on recycling infrastructure pre-positioning and blockchain-traceable lot documentation for regulatory compliance.
Among North American integrated producers, Materion occupies a position exemplifying captive mining-to-refining vertical control. Japanese specialists in precision alloy formulations include NGK Insulators, which anchors domestic demand through long-term supply structures. IBC Advanced Alloys represents the custom formulation archetype competing on aerospace-grade reliability specifications that downstream electronics vendors increasingly require.
| Leading Market Players |
|---|
| Materion |
| NGK Insulators |
| Kazatomprom |
| Aviva Metals |
| IBC Advanced Alloys |
| Belmont Metals |
| AMPCO Metal |
| China Minmetals Beryllium |
| JinDian |
| Others |
Pricing and Supply Chain Analysis
Multi-source qualification mandates from Apple and Samsung procurement teams are forcing alloy service centers to maintain redundant inventory positions, compressing margins through carrying cost accumulation while elevating working capital requirements for distributors serving the Pearl River Delta cluster.
Pricing Analysis
Metallurgical certification bundling separates quoted alloy grades: REACH-registered material with blockchain-traceable lot documentation commands premium positioning against unbundled spot-market equivalents lacking ECHA disclosure compliance. Three-tier pricing structure across aerospace-certified, automotive-grade, and standard electronics tiers reflects differentiation by fatigue testing protocol intensity. Cost compression in standard connector alloys is intensifying because aluminum bronze substitutes are capturing relay applications where specifications permit material relaxation. Contract manufacturers in Shenzhen exhibit highest price sensitivity due to thin assembly margins, while medical implantable electronics vendors show lowest sensitivity given biocompatibility liability exposure.
Supply Chain Analysis
Single-source vulnerability sits with Utah's Spor Mountain mining complex and Elmore refining assets that feed Materion's captive North American supply. Raw material flows draw from beryllium ore concentrates, cobalt master alloys for precipitation hardening, and high-purity copper cathodes sourced from Chile and Zambia. Tariff exposure on refined beryllium compounds imported into the European Union elevates landed cost variance for German and French fabricators. Distribution runs through designated alloy service centers with metallurgical laboratory capabilities that consolidate inbound logistics for Foxconn and Luxshare procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration requirements and OSHA permissible exposure limits have erected compliance moats that favor incumbent producers with pre-positioned ventilation infrastructure and ECHA disclosure systems, marginalizing speculative entrants lacking capital reserves for regulatory adherence.
For Market Incumbents: Lock in multi-year supply agreements with Pearl River Delta contract manufacturers before 18-24 month qualification windows expire for alternative suppliers. Pre-position closed-loop recycling infrastructure ahead of anticipated end-of-life recovery mandates in Germany and France. Aluminum bronze substitution in relay applications represents the most credible material threat requiring specification-defense investment. For New Entrants and Emerging Players: Enter via precision wire drawing capabilities below 50 micrometers for medical implantable electronics feedthrough assemblies, where qualification paces are accelerating and incumbent capacity is constrained. Target South Korean wearable device OEMs in the Seoul Capital Area for spring coiling applications. Pursue joint development agreements with hermetic packaging specialists rather than direct alloy sales to establish technical credibility. For Investors and Strategic Acquirers: The window for entry favors custom formulation specialists with aerospace-grade reliability certifications that electronics vendors increasingly require as insurance against contact failure liability. Long-term viability hinges on backward integration into beryllium refining or captive recycling infrastructure to decouple from Utah supply concentration. Watch for MFDS medical device traceability rule expansion as the signal indicating accelerated consolidation among qualified alloy service centers.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure | Positions alloy producers ahead of ECHA end-of-life recovery mandates in Bavarian industrial clusters. |
| Ultra-Fine Wire Drawing Capacity | Enables sub-50 micrometer spring forms for PMDA-regulated medical implantable feedthrough assemblies. |
| Blockchain-Traceable Lot Documentation | Satisfies REACH registration requirements for beryllium content disclosure above threshold concentrations. |
| Multi-Source Qualification Arrangements | Reduces inbound logistics variance for Foxconn and Luxshare contract manufacturing operations. |
| Metallurgical Laboratory Service Centers | Captures distributor functions through chemistry consistency validation and lot-to-lot mechanical property testing. |
Research Methodology
SEC 10-K filings, ECHA REACH registration databases, and customs/trade flow records formed the secondary backbone for supply chain mapping and competitive positioning assessment. Primary interviews with alloy procurement managers at Tier-1 connector manufacturers, metallurgical laboratory directors at designated service centers, and EHS compliance officers at fabrication facilities provided qualitative validation of regulatory cost structures. Bottom-up and top-down triangulation reconciled shipment volume estimates from wire drawing operations against OEM bill-of-materials penetration rates.
Bottom-up modeling aggregated alloy consumption by form factor across smartphone, wearable, and medical device architectures, while top-down analysis calibrated aggregate market size against Utah mining output and Japanese import statistics. Segmentation dimensions included beryllium concentration grade, application type, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from year-over-year growth rate reconciliation across these independent estimation pathways. Forecast inputs incorporated OSHA enforcement intensity indices and GB standards alignment timelines for hazardous substance restriction.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated aluminum bronze substitution or unanticipated REACH beryllium compound bans. Forecasts reflect assumptions regarding qualification cycle durations, age-hardening furnace operator availability, and contract manufacturer inventory policy stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Global Precision Resistor Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Thick Film Resistor Market
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Global EMI Shielding Market