
 Fuse Market | 2026-2036
Fuse Market Size, Share, and Industry Trends Forecast 2026-2036
Fuse Market Analysis
Solid-state fuse integration with wide-bandgap semiconductors is reconfiguring protection architecture across high-power applications. Littelfuse leverages its SiC-compatible fuse portfolio to anchor premium positioning in electric vehicle inverters. Eaton sustains manufacturing scale across North American industrial infrastructure, while Mersen specializes in high-speed fuses for semiconductor fabrication equipment.
A fuse is a sacrificial overcurrent protection device containing a metal element that melts when current exceeds rated capacity, interrupting fault current within specified time-current curves. Blade fuses dominate automotive harness applications due to standardized ATO and Mini footprints, while cartridge fuses command industrial margin pools through high-breaking-capacity ceramic body designs. Resettable fuses represent the fastest-expanding component category as consumer electronics manufacturers adopt polymeric positive temperature coefficient devices for rechargeable battery packs.
IEC 60269, UL 248, and China's GB 13539 standards govern fuse breaking capacity, time-current characteristics, and construction materials across major manufacturing regions. EMA and FDA device safety directives indirectly shape medical equipment fuse specifications in Europe and the United States. Stakeholders must monitor wide-bandgap semiconductor compatibility requirements as silicon carbide and gallium nitride adoption redefines protection device performance thresholds.
Market Dynamics
Wide-bandgap semiconductor adoption in EV inverters and industrial motor drives is forcing fuse manufacturers to redesign interruption architectures around faster fault-clearing requirements and higher thermal cycling tolerance.
Growth Catalysts
- EV powertrain electrification:Battery pack voltages climbing toward 800V architectures in passenger and commercial vehicles necessitate upgraded fuse specifications across OEM supply chains.
- China's dual carbon goals:MIIT mandates for energy efficiency in industrial equipment are accelerating replacement cycles for legacy protection devices in manufacturing clusters.
- IEC 60269-4 standard expansion:Tighter semiconductor protection requirements are pulling high-speed fuse demand from solar inverter and wind turbine installations.
Market Restraints
- Silver price volatility:Primary fuse element material costs swing with precious metal markets, compressing margin stability for manufacturers dependent on electroplated strip production.
- Ceramic body supply concentration:High-purity alumina substrate production clusters in specific Asian manufacturing regions create single-source vulnerability for high-breaking-capacity cartridge designs.
- Resettable PTC device substitution:Polymeric positive temperature coefficient devices are displacing traditional one-time fuses in consumer electronics battery protection applications.
Strategic Opportunities
- India industrial electrification:CEA grid modernization mandates and PLI scheme incentives for domestic manufacturing equipment are opening fuse specification windows for infrastructure buildouts.
- Solid-state circuit breaker convergence:Integration of SiC MOSFET protection with traditional fuse backup architectures creates hybrid product categories for data center power distribution.
- Direct-to-OEM digital channels:Configurator platforms allowing engineers to specify time-current curves and breaking capacity online are bypassing traditional electrical distributor markups.
Industry Challenges
- Wide-bandgap compatibility testing:Validating fuse performance under silicon carbide switching speeds requires capital-intensive arc-quenching characterization labs that mid-tier manufacturers struggle to fund.
- Multi-standard certification timelines:Simultaneous UL 248, IEC 60269, and GB 13539 approval processes extend product launch windows by 18-24 months for global platform designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuse Market |
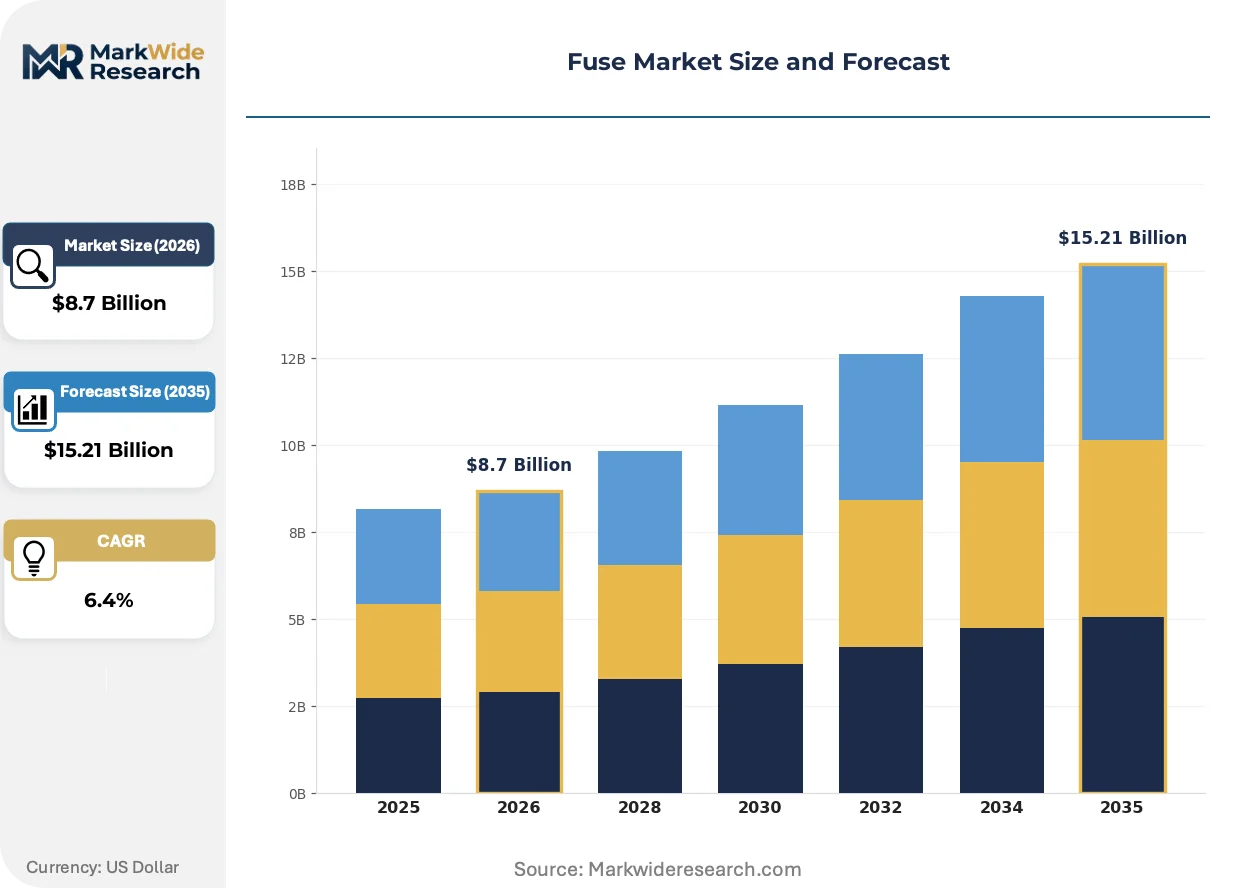
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Blade Fuses, Cartridge Fuses, Plug Fuses, Resettable Fuses Application: Automotive, Industrial Equipment, Consumer Electronics, Renewable Energy Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale End User: OEMs, Maintenance Providers, Retailers, Contractors |
| Companies Covered | Littelfuse, Eaton, Mersen, ABB, Schneider Electric, Siemens, AEM Components, Pacific Engineering Corporation, Siba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuse Market Emerging Trajectories
Protection device architecture is converging with power electronics semiconductor roadmaps, creating demand for fuses that coordinate with active switching rather than simply clearing faults independently.
Silicon carbide-compatible fuse designs are digitizing protection coordination in 800V EV inverters. Automotive Tier-1 suppliers are specifying arc-voltage limiting geometries that match SiC switching speeds. This convergence is digitizing the traditional electromechanical protection layer into software-coordinated safety systems.
REACH substance restrictions on lead-bearing alloys are forcing fuse element metallurgy redesigns across European industrial markets. Manufacturers are migrating to tin-antimony-copper compositions that maintain time-current precision without restricted materials. Industrial motor drive OEMs in Germany and Italy are prioritizing RoHS-compliant suppliers in procurement specifications.
Specifying engineers are consolidating fuse vendor lists around full-line capability rather than sourcing specialty devices from niche suppliers. Procurement teams at multi-site industrial operators are awarding sole-source contracts to manufacturers offering cartridge, blade, and semiconductor protection from unified catalogs. This concentration is most visible in North American heavy manufacturing where maintenance standardization drives purchasing decisions.
Fuse Market Segmentation
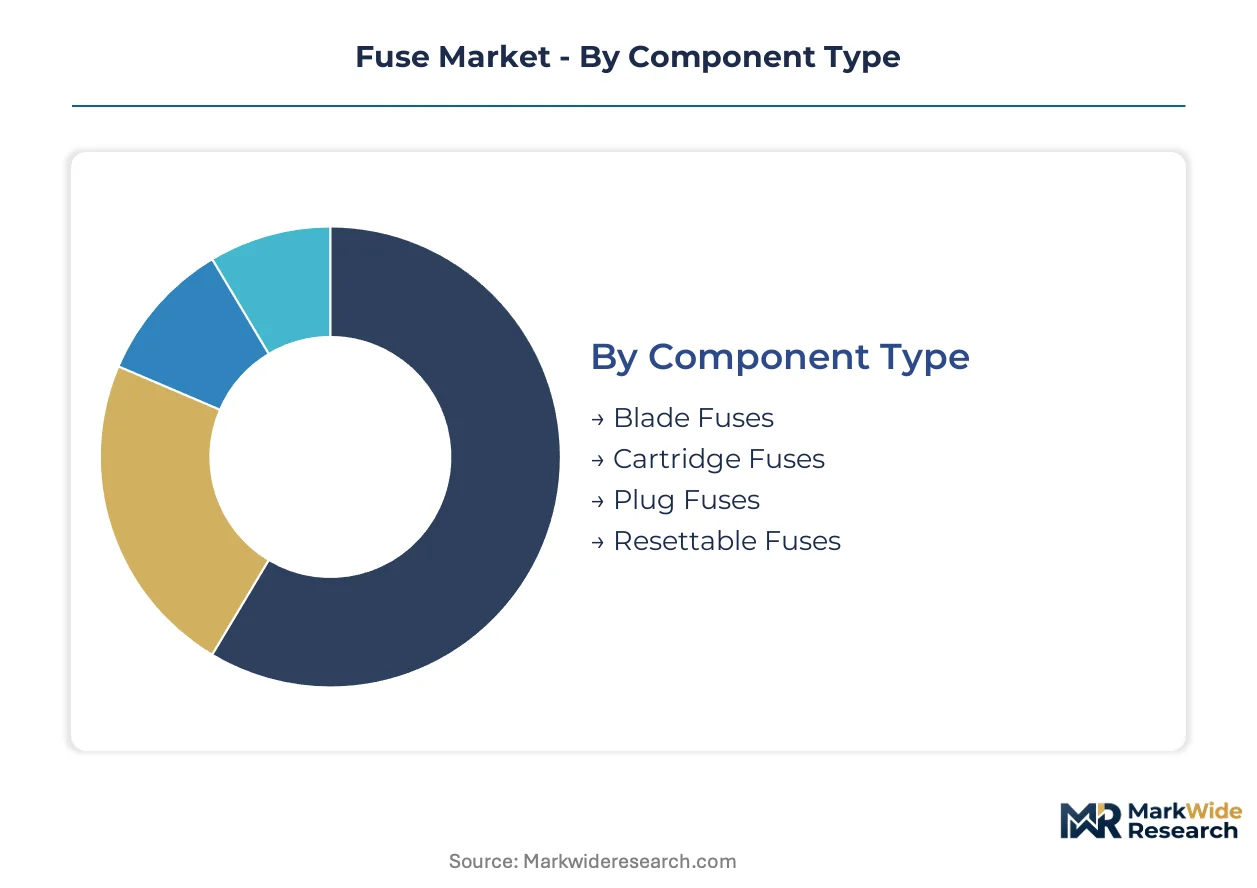
Fuse segmentation reveals how protection device architectures diverge across voltage, current, and resettability requirements. Component type determines manufacturing processes and margin structures, while application verticals dictate certification standards and procurement cycles.
Component Type:
Mature fuse technologies dominate installed bases while emerging designs capture electrification-driven replacement cycles.
- Blade Fuses:Standardized ATO and Mini footprint designs with zinc or alloy strip elements housed in colored plastic bodies for amperage identification. Automotive harness manufacturers in Germany and the United States specify these for 12V and 48V vehicle electrical systems as OEMs consolidate supplier lists around full-line capability.
- Cartridge Fuses:Ceramic or fiber tube constructions with high-breaking-capacity designs interrupt fault currents up to 100kA in industrial motor drives. Demand concentrates in Chinese manufacturing clusters around Shanghai where MIIT energy efficiency mandates accelerate replacement of legacy protection devices.
- Plug Fuses:Edison-base and Type-S thread configurations for residential and light commercial electrical panels.
- Resettable Fuses:Polymeric positive temperature coefficient devices self-reset after overcurrent events, displacing traditional one-time fuses in rechargeable battery packs for consumer electronics manufacturers.
Cartridge fuses handle the majority of industrial throughput; resettable fuses are climbing the fastest on share as battery-powered devices proliferate.
Application:
Cost tier differentiation separates commodity automotive volumes from premium industrial and renewable energy specifications.
- Automotive:Blade and high-voltage DC fuses protect 12V accessory circuits through 800V battery pack architectures in passenger and commercial vehicles. Tier-1 suppliers coordinate fuse specifications with SiC inverter switching speeds.
- Industrial Equipment:High-speed semiconductor protection fuses and general-purpose cartridge designs safeguard motor drives, transformers, and distribution panels. German and Italian industrial OEMs prioritize REACH-compliant suppliers with RoHS-certified metallurgy.
- Consumer Electronics:Miniature surface-mount and resettable PTC devices protect smartphones, laptops, and portable power banks.
- Renewable Energy:GPV and high-speed DC fuses isolate faults in solar string inverters and wind turbine power conversion systems.
Automotive applications generate the highest unit volumes; renewable energy specifications command the steepest expansion trajectory as IEC 60269-4 standard expansion pulls demand from solar and wind installations.
Distribution Channel:
Customer type determines whether procurement flows through specification engineers, maintenance buyers, or price-sensitive retail channels.
- Direct Sales:Fuse manufacturers field application engineers to automotive Tier-1s and industrial OEMs for custom time-current curve specification. Configurator platforms now allow engineers to specify breaking capacity online, bypassing traditional electrical distributor markups.
- Distributors:Electrical wholesalers like WESCO and Rexel stock blade and cartridge inventories for contractor and maintenance provider demand.
- Online Retail:E-commerce platforms serve hobbyist, small contractor, and replacement part procurement with standardized ATO and Mini blade assortments.
- Wholesale:Volume purchasing agreements supply multi-site industrial operators with maintenance standardization requirements.
Direct sales channels capture the premium specification tier; online retail is gaining share fastest among small-volume buyers and replacement markets.
End User:
Volume concentration sits with large-scale manufacturing purchasers while margin pools align with specification authority.
- OEMs:Automotive, industrial equipment, and renewable energy system manufacturers specify fuses at design-in stage with 5-10 year supply agreements. Multi-standard certification timelines of 18-24 months for simultaneous UL 248, IEC 60269, and GB 13539 approval extend product launch windows.
- Maintenance Providers:Facility management and industrial maintenance contractors replace fuses during scheduled downtime, prioritizing inventory availability over unit cost.
- Retailers:Auto parts chains and electrical supply stores stock consumer-accessible blade fuse assortments for vehicle owners and small contractors.
- Contractors:Electrical installation professionals specify fuses for new construction and panel upgrades based on local code requirements.
OEMs dominate specification authority and contract value; maintenance providers represent the most stable recurring demand segment across economic cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fuse manufacturers export high-breaking-capacity cartridge designs to industrial OEMs across the European Union and North America, while Chinese producers supply blade and automotive fuse volumes to EV assembly plants in Southeast Asia and Europe.
China
MIIT energy efficiency mandates accelerate replacement cycles for legacy protection devices in industrial motor drives. The dual carbon goals framework tightens equipment standards across manufacturing sectors. Fuse demand concentrates in Shanghai and Shenzhen EV manufacturing clusters where 800V battery pack architectures necessitate upgraded high-voltage DC specifications.
Germany
Industrial motor drive OEMs in Bavaria and Baden-Württemberg prioritize REACH-compliant fuse suppliers with RoHS-certified metallurgy. ECHA substance restrictions on lead-bearing alloys force element redesigns across European markets. Stuttgart and Munich automotive hubs coordinate fuse specifications with silicon carbide inverter switching speeds for next-generation powertrains.
United States
NHTSA vehicle safety standards and FERC grid modernization mandates pull fuse demand from automotive and utility infrastructure sectors. Eaton sustains manufacturing scale across North American industrial corridors. Detroit automotive suppliers and Texas energy equipment fabricators specify UL 248-certified devices for platform standardization.
India
CEA grid modernization mandates and PLI scheme incentives for domestic manufacturing equipment open fuse specification windows. The country's national electrical regulator accelerates infrastructure buildouts across industrial zones. Maharashtra and Gujarat manufacturing clusters import high-breaking-capacity cartridge designs while scaling local blade fuse production for automotive harness applications.
Japan
METI industrial efficiency programs drive semiconductor fabrication equipment upgrades requiring high-speed fuse protection. JIS standards govern breaking capacity and time-current characteristics for domestic and export markets. Kyushu and Chubu industrial corridors specialize in precision fuse elements for robotics and automation OEMs supplying Asian electronics manufacturers.
Fuse Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Electrical distributors and direct OEM specification channels concentrate volume with full-line manufacturers, while niche suppliers capture margin in semiconductor protection and resettable device categories. Three archetypes dominate: diversified industrial conglomerates with fuse divisions, pure-play protection device specialists, and component distributors with private-label sourcing. Competitive moves center on multi-standard certification acceleration and configurator platform deployment to bypass traditional distributor markups.
Among diversified industrial conglomerates, Eaton and ABB occupy positions spanning electrical distribution and protection device portfolios. Littelfuse exemplifies the pure-play protection specialist archetype, anchoring premium positioning through wide-bandgap semiconductor compatibility. These three entities represent distinct strategic postures: scale-driven manufacturing breadth, technology-specialized specification authority, and integrated electrical infrastructure solutions.
| Leading Market Players |
|---|
| Littelfuse |
| Eaton |
| Mersen |
| ABB |
| Schneider Electric |
| Siemens |
| AEM Components |
| Pacific Engineering Corporation |
| Siba |
| Others |
Supply Flow & Price Mechanics
Shanghai's EV manufacturing clusters concentrate high-breaking-capacity ceramic fuse production, translating upstream alumina substrate scarcity into pricing leverage for Tier-1 automotive suppliers negotiating 800V battery protection specifications.
Pricing Analysis
Long-term supply agreements with London Metal Exchange silver price indexation dominate industrial fuse procurement, insulating manufacturers from electroplated strip volatility while compressing margins on spot purchases. Three-tier pricing structure across IEC 60269-4 certified premium, UL 248 standard, and uncertified economy levels separates renewable energy project developers from maintenance contractors. Pricing pressure stems from resettable PTC device substitution in consumer electronics, eroding traditional one-time fuse volumes. Aftermarket maintenance providers exhibit lowest price sensitivity, prioritizing inventory availability over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese trading houses anchor raw material procurement for precision fuse element manufacturers. High-purity alumina ceramic bodies draw from Chinese and Japanese substrate specialists, while silver and copper element metallurgy rests on Chilean and Peruvian mining output. Single-source vulnerability concentrates in Shanghai ceramic tube production clusters. Distribution runs through WESCO and Rexel electrical wholesalers stocking blade and cartridge inventories for North American contractor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of wide-bandgap semiconductor-compatible arc-quenching characterization capabilities constrains mid-tier manufacturers from certifying next-generation EV inverter protection, consolidating specification authority with capital-intensive specialists.
For Market Incumbents: Build certification moats around simultaneous UL 248, IEC 60269, and GB 13539 approval capabilities to extend product launch windows for global platform designs. Add captive high-purity alumina ceramic body production in Germany or Japan to mitigate Shanghai supply concentration. Defend against solid-state circuit breaker convergence by integrating SiC MOSFET coordination into hybrid fuse-backup architectures. For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial electrification under CEA grid modernization mandates represents the most penetrable entry point for cartridge fuse specification. Target maintenance provider digital procurement through configurator platforms bypassing traditional electrical distributor markups. Partner with PLI scheme beneficiaries for domestic manufacturing equipment qualification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play protection specialists with wide-bandgap semiconductor compatibility roadmaps over diversified industrial conglomerates. Long-term viability hinges on 5-10 year SiC and GaN adoption curves in EV powertrains. Watch IEC 60269-4 standard expansion velocity as inflection indicator for high-speed fuse demand acceleration from solar and wind installations.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Acceleration | Simultaneous UL 248, IEC 60269, and GB 13539 approvals compress 18-24 month launch windows for global automotive platforms. |
| Wide-Bandgap Semiconductor Compatibility Investment | SiC and GaN switching speed validation anchors premium positioning in 800V EV inverter specifications. |
| Ceramic Body Backward Integration | Captive high-purity alumina production mitigates Shanghai substrate concentration vulnerability. |
| Digital Configurator Platform Deployment | Online time-current curve specification bypasses WESCO and Rexel distributor markups for direct OEM engagement. |
| REACH-Compliant Metallurgy Migration | Tin-antimony-copper element compositions replace lead-bearing alloys for German and Italian industrial OEM procurement. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with fuse application engineers, automotive Tier-1 procurement directors, industrial OEM specification leads, and electrical distributor category managers; and secondary validation through IEC standard revision documents, UL certification databases, MIIT energy efficiency mandate filings, and customs trade records for silver and alumina substrate flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Forecast inputs considered component type segmentation across blade, cartridge, and resettable architectures; application verticals spanning automotive voltage tiers, industrial motor drives, and renewable energy installations; and distribution channel evolution toward direct digital specification. CAGRs derived from regression analysis of historical replacement cycles against electrification-driven upgrade trajectories. Wide-bandgap semiconductor adoption curves and multi-standard certification timelines served as industry-specific demand modifiers across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in silver price volatility, Chinese industrial policy implementation, or EV powertrain electrification pace would shift the trajectory. Forecasts reflect documented assumptions on standard harmonization timelines and substrate supply concentration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Elastomeric Connectors Market
Passive And Interconnecting Electronic Components
Beryllium Copper for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Precision Chip Resistors Market
Passive And Interconnecting Electronic Components
Passive Tunable Integrated Circuits Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market