
 Electrical Wiring Interconnection System (EWIS) Market | 2026-2036
Electrical Wiring Interconnection System (EWIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Wiring Interconnection System (EWIS) Market Analysis
The EWIS supply base is rebalancing between premium aerospace-grade harnesses and commodity industrial cable assemblies. RTX Corporation leverages its defense and commercial aviation verticals to sustain long-term program positions across multiple OEM platforms. Safran specializes in integrated wiring solutions for narrow-body and wide-body jet programs, while TE Connectivity dominates connector and sensor-integrated architectures that reduce weight and installation complexity.
An Electrical Wiring Interconnection System comprises wire harnesses, connectors, terminals, and insulation materials engineered to transmit power, signals, and data across complex platforms, typically operating between -65°C and 260°C depending on conductor and jacket specifications. Wire harness assemblies occupy the largest value share due to labor-intensive fabrication and platform-specific routing requirements, while connectors command disproportionate margin pools from miniaturization and harsh-environment sealing demands. Signal transmission applications within aerospace end-use segments exhibit the steepest trajectory as fly-by-wire architectures and avionics integration multiply discrete circuit counts per aircraft.
FAA airworthiness directives, EASA CS-25 certification standards, and SAE AS50881 military specifications collectively dictate conductor plating, fire resistance, and electromagnetic interference shielding requirements that OEMs and tier suppliers must satisfy for market access. Regulatory pressure on aging fleet wiring integrity inspections is expanding aftermarket retrofit and custom installation volumes beyond original production demand. Stakeholders must monitor how evolving electrification standards for hybrid propulsion and more-electric aircraft architectures reshape material specifications and qualification timelines across the supply chain.
Market Dynamics
The EWIS market is experiencing structural compression as fly-by-wire architectures multiply circuit density per aircraft while weight reduction mandates intensify material substitution pressures across OEM specification sheets.
Growth Catalysts
- FAA Airworthiness Directives:Aging fleet wiring inspection mandates are expanding aftermarket retrofit volumes beyond original production demand, particularly for narrow-body operators facing compliance deadlines.
- More-Electric Aircraft Architectures:Hybrid propulsion programs are redefining conductor ampacity and thermal management specifications, creating qualification opportunities for advanced insulation material suppliers.
- United States Defense Procurement:Pentagon modernization programs for next-generation aerial platforms are sustaining long-term harness and connector demand through multi-year indefinite-delivery contracts.
Market Restraints
- Copper Price Volatility:Conductor raw material cost swings compress margin predictability for harness fabricators locked into fixed-price OEM supply agreements.
- Specialized Labor Concentration:Certified wire harness technicians cluster in specific aerospace manufacturing corridors, creating regional production bottlenecks during demand surges.
- Polyimide Supply Concentration:High-temperature insulation film production concentrates among limited chemical compounders, exposing the supply chain to single-source disruption risk.
Strategic Opportunities
- Urban Air Mobility Certification:Emerging eVTOL airframe manufacturers require simplified, lightweight EWIS architectures that bypass legacy military specification complexity.
- India Defense Indigenization:The country's PLI scheme for aerospace components creates localized production incentives for harness and connector manufacturers establishing domestic assembly capacity.
- Digital Thread Integration:Convergence of model-based systems engineering with automated harness routing software is compressing design-to-manufacturing cycle times for custom installations.
Industry Challenges
- AS50881 Certification Timeline:Military specification qualification protocols extend 18-24 months, delaying supplier entry into defense platform supply chains.
- Legacy Platform Documentation Gaps:Aging aircraft wiring diagrams often lack digital records, complicating accurate harness reproduction for MRO providers.
- Electromagnetic Interference Testing Capacity:Limited certified laboratory availability for shielding effectiveness validation creates program schedule risk for new entrant suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Wiring Interconnection System (EWIS) Market |
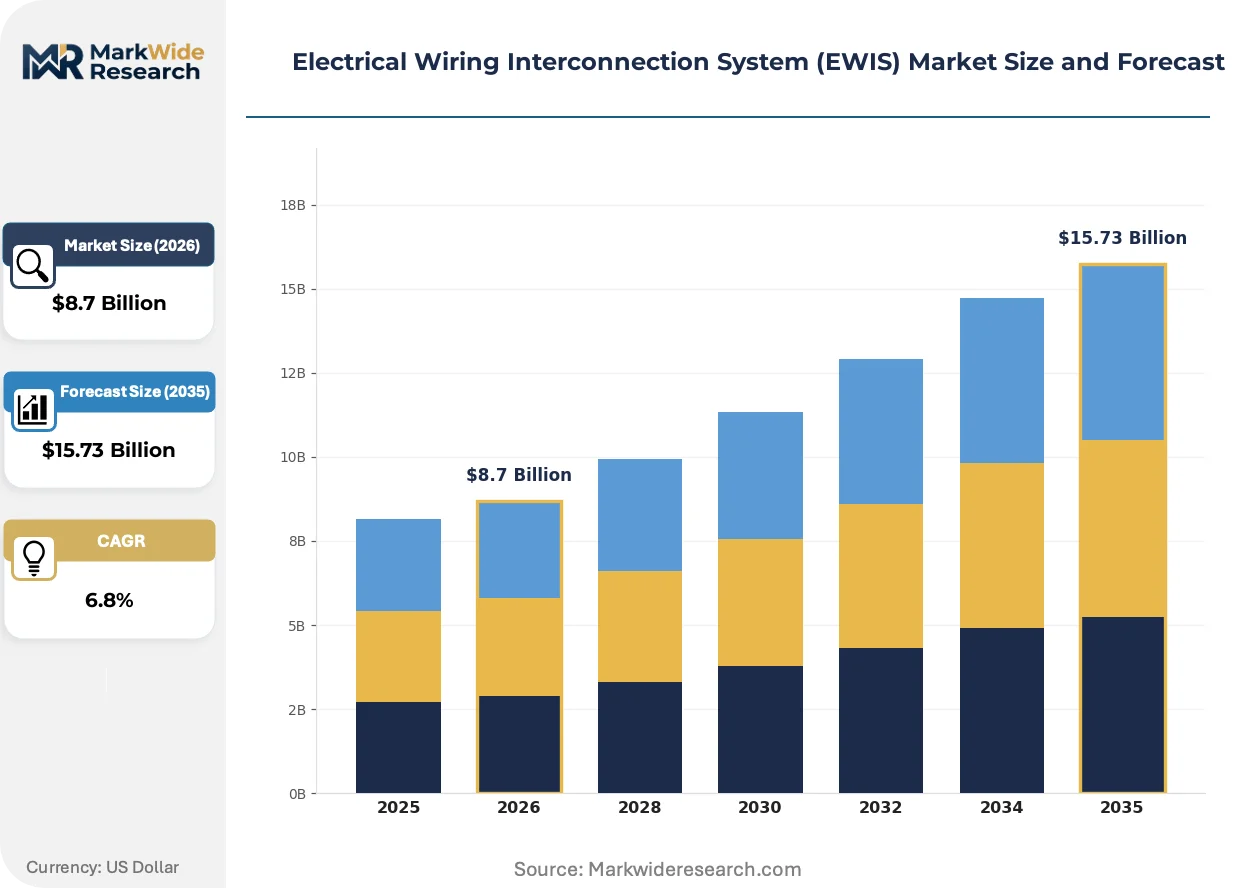
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Harness, Connectors, Terminals, Insulation Materials End User: Aerospace, Automotive, Marine, Industrial Equipment Application: Power Distribution, Signal Transmission, Data Communication, Control Systems Installation Type: Onboard, Ground Support, Retrofit, Custom Installation |
| Companies Covered | RTX Corporation, Latécoère, Safran, InterConnect Wiring, Ducommun, TE Connectivity, GKN Aerospace, Radiall, Amphenol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Wiring Interconnection System (EWIS) Market Emerging Trajectories
Active developments across materials science, regulatory frameworks, and procurement architectures are restructuring how EWIS specifications propagate from OEM engineering departments to tiered fabrication networks.
Fiber-optic data transmission is decentralizing signal routing architecture within modern airframes. Avionics integration teams at major commercial OEMs are specifying optical harnesses for high-bandwidth applications previously served by copper twisted pairs. This displacement is compressing electromagnetic interference mitigation requirements while introducing new termination skill demands across the installation base.
REACH substance restrictions on halogenated flame retardants are forcing insulation compound reformulation across European supply chains. ECHA regulatory pressure is accelerating adoption of phosphorus-based and metal-hydrate alternatives in cabin and cargo bay wiring applications. German and French harness manufacturers are front-loading qualification testing to maintain EASA CS-25 certification continuity.
OEMs are consolidating harness procurement under systems integration contracts rather than discrete component purchasing. Tier-one aerostructures suppliers now assume full EWIS design responsibility, displacing traditional tier-two harness houses from direct OEM relationships. This concentration is most visible in United States-based Boeing and Airbus final assembly line supply agreements.
Electrical Wiring Interconnection System (EWIS) Market Segmentation
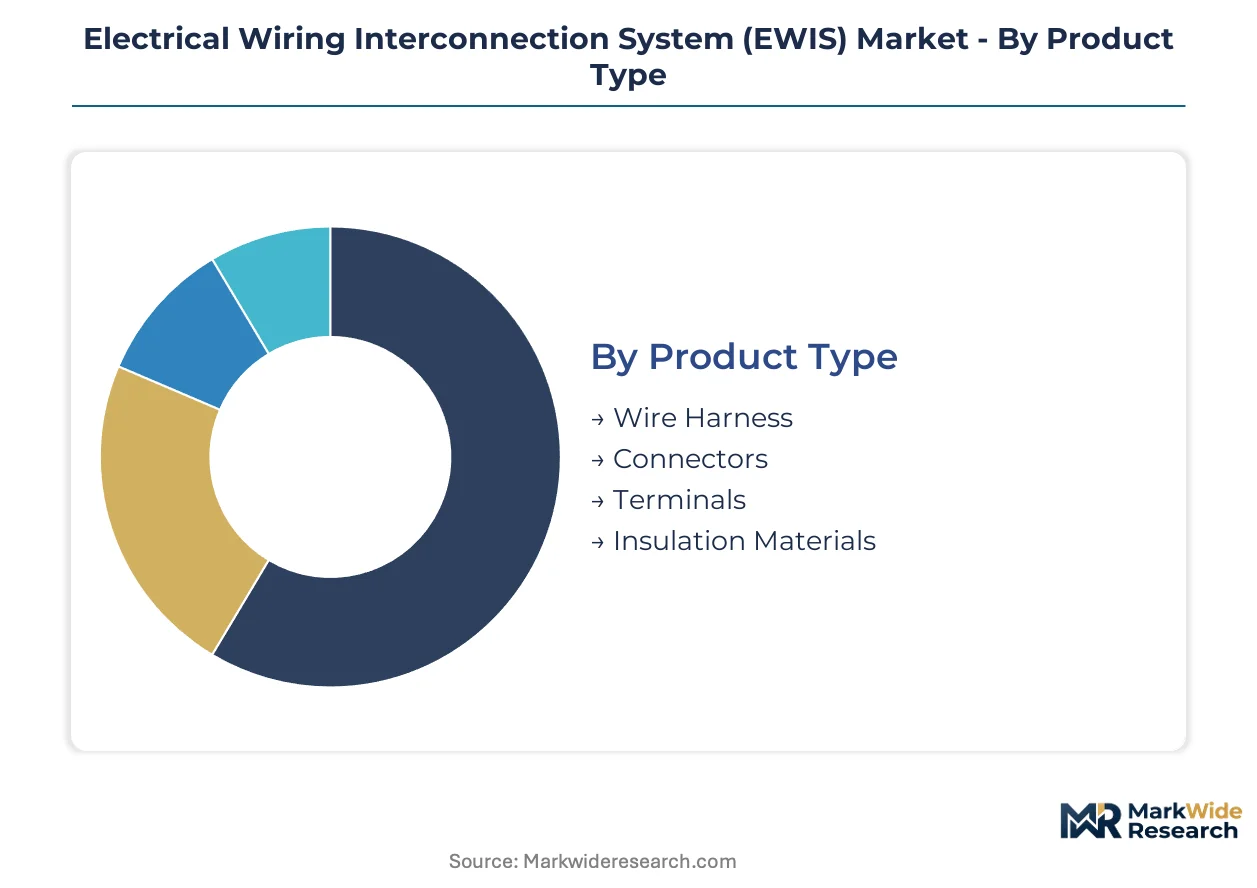
EWIS procurement patterns diverge sharply between platform-optimized harnesses and catalog-standard components. Understanding these segmentation boundaries clarifies where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
Customization intensity varies from build-to-print harness assemblies to off-the-shelf connector families, reshaping supplier qualification requirements and inventory strategies across the value chain.
- Wire Harness:Labor-intensive assemblies bundling conductors, shielding, and protective sleeving into platform-specific routing configurations. Demand concentrates in United States-based Boeing and defense prime supply chains, where FAA certification continuity and AS50881 military specification compliance create multi-year supplier lock-in effects.
- Connectors:Miniaturized electromechanical interfaces integrating harsh-environment sealing, EMI shielding, and quick-disconnect functionality. Procurement from TE Connectivity and Amphenol dominates aerospace programs, as gram-level weight reductions and installation labor savings justify premium positioning against commodity alternatives.
- Terminals:Crimp, solder, and compression-style termination hardware completing circuit integrity at harness endpoints.
- Insulation Materials:Polyimide films, fluoropolymer jackets, and composite sleeving rated for -65°C to 260°C operational envelopes.
Leading the category by volume: Wire Harness. Growing fastest: Connectors.
End User:
Specification authority shifts from OEM engineering departments to tier-one systems integrators, with certification burden and liability exposure varying dramatically across end-use verticals.
- Aerospace:Commercial aviation and defense platforms demanding traceable lot control, fire resistance per FAA/EASA standards, and electromagnetic compatibility validation. Narrow-body fleet replacement cycles in the United States and European Union sustain aftermarket retrofit volumes beyond original equipment demand.
- Automotive:High-voltage harness architectures for battery electric vehicles, where 800V+ systems impose partial discharge resistance and thermal runaway containment requirements distinct from conventional 12V/48V applications.
- Marine:Salt-spray resistant interconnection systems for naval and commercial vessel propulsion controls.
- Industrial Equipment:Factory automation and energy infrastructure applications tolerating broader specification variance.
Aerospace commands the highest certification barrier. Automotive exhibits the steepest specification change velocity.
Application:
Signal integrity requirements scale with data throughput demands, bifurcating procurement between copper conductor optimization and fiber-optic substitution pathways.
- Power Distribution:High-ampacity bus structures and feeder cables managing thermal loads across propulsion and auxiliary systems. Hybrid-electric aircraft architectures in development at United States and European Union OEMs are redefining conductor sizing standards and cooling integration requirements.
- Signal Transmission:Discrete analog and digital circuits for sensor, actuator, and avionics interfaces. Fly-by-wire flight control proliferation multiplies circuit counts per airframe, with shielded twisted pair demand climbing fastest in new-generation narrow-body programs.
- Data Communication:High-bandwidth avionics networking previously served by copper now migrating to optical harness specifications.
- Control Systems:Safety-critical command pathways requiring redundant routing and fault isolation.
Power Distribution retains the largest installed base. Signal Transmission is expanding most quickly.
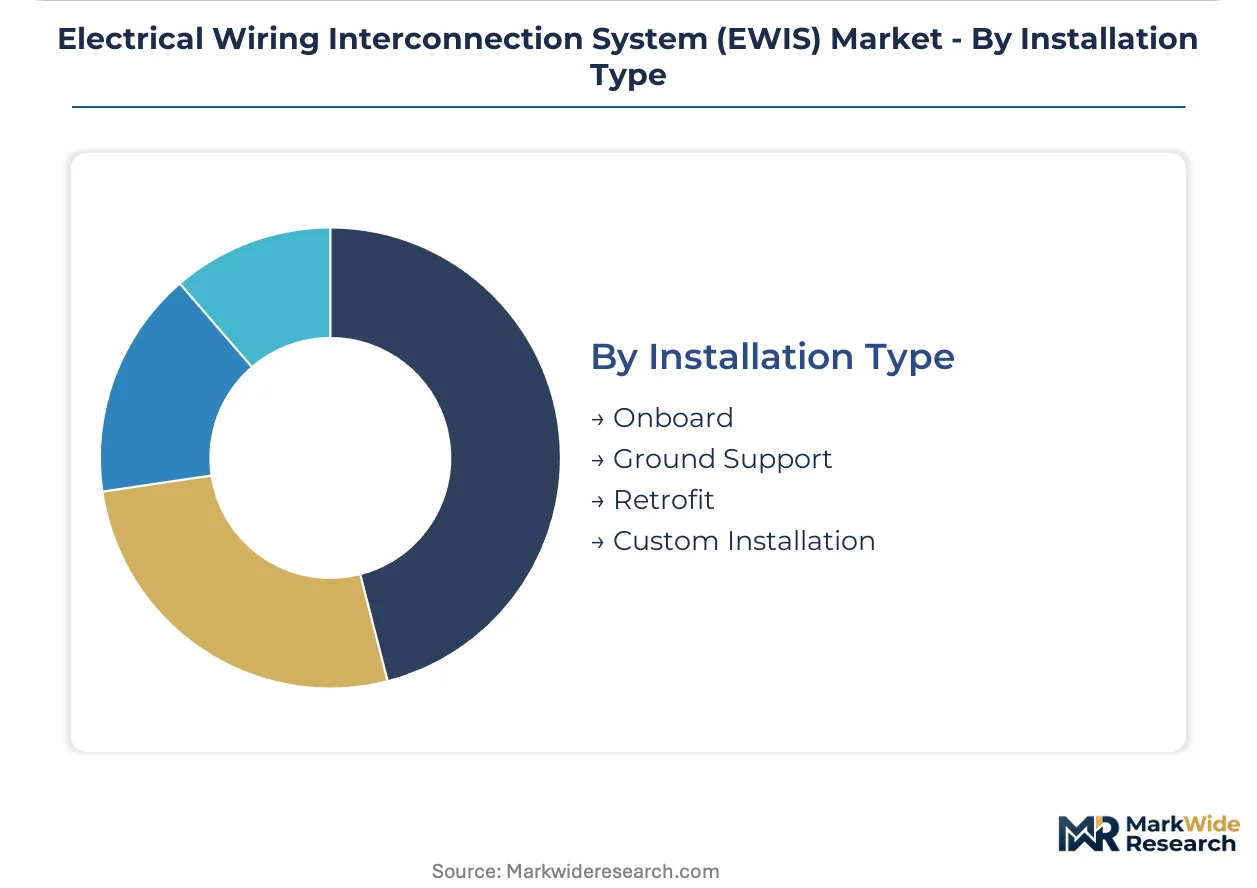
Installation Type:
Lifecycle positioning determines documentation burden and regulatory oversight intensity, with aftermarket retrofit commanding distinct skill and tooling requirements from production-line installation.
- Onboard:Factory-original harness routing integrated during final assembly at OEM facilities. Boeing's Everett and Charleston lines, alongside Airbus Hamburg and Toulouse operations, anchor demand for production-schedule synchronized harness delivery with zero defect tolerance.
- Retrofit:Post-delivery modification and aging fleet wiring replacement mandated by FAA airworthiness directives. United States narrow-body operators face compressed compliance timelines, expanding MRO provider demand for custom harness reproduction where legacy documentation gaps complicate accurate replication.
- Ground Support:External power, test, and maintenance interface cabling for hangar and flight line operations.
- Custom Installation:One-off engineering solutions for special mission aircraft and prototype platforms.
Onboard installation dominates value concentration. Retrofit activity is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors aerospace EWIS demand through Boeing's Everett and Renton final assembly corridors, where production-schedule synchronized harness delivery commands zero-defect tolerance from tier suppliers.
United States
Pentagon modernization programs for next-generation aerial platforms sustain multi-year indefinite-delivery contracts for defense-grade harness and connector suppliers. FAA airworthiness directives on aging fleet wiring integrity tighten compliance timelines for narrow-body operators. Wichita's aviation manufacturing cluster concentrates MRO retrofit capacity where legacy documentation gaps complicate accurate harness reproduction.
France
Airbus final assembly operations at Toulouse and Hamburg drive specification authority toward tier-one systems integrators. EASA CS-25 certification standards and REACH substance restrictions on halogenated flame retardants force insulation compound reformulation across French and German supply chains. The Bordeaux-Toulouse aerospace corridor hosts specialized harness manufacturers front-loading qualification testing for EASA continuity.
Germany
More-electric aircraft architectures in development at Airbus and regional OEMs redefine conductor ampacity and thermal management specifications. ECHA regulatory pressure accelerates adoption of phosphorus-based flame retardant alternatives in cabin and cargo bay applications. Bavaria's industrial automation ecosystem supplies automated harness routing software compressing design-to-manufacturing cycle times.
United Kingdom
Defense prime contractors at BAE Systems and Rolls-Royce anchor demand for AS50881 military specification-compliant interconnection systems. SAE qualification protocols extending 18-24 months delay supplier entry into UK defense platform supply chains. The South West England aerospace cluster around Bristol and Yeovil concentrates electromagnetic interference testing capacity for shielding effectiveness validation.
India
The PLI scheme for aerospace components creates localized production incentives for harness and connector manufacturers establishing domestic assembly capacity. Defense indigenization mandates under the Ministry of Defence's Make in India framework redirect procurement toward indigenous suppliers. Bangalore's aerospace and defense manufacturing corridor attracts joint ventures targeting regional MRO retrofit demand.
Electrical Wiring Interconnection System (EWIS) Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and platform-access dimensions, with FAA/EASA qualification continuity creating multi-year supplier lock-in effects at the top tier. The vendor base stratifies between defense-anchored conglomerates, commercial aviation specialists, and connector-centric component houses. Three archetypes dominate: integrated systems integrators assuming full EWIS design responsibility, harness fabricators locked into build-to-print OEM relationships, and connector manufacturers capturing disproportionate margin pools from miniaturization demands. Consolidation pressure and tier-one aerostructures integration contracts represent the dominant competitive vectors reshaping direct OEM relationships.
Within the integrated systems tier, RTX Corporation and Safran exemplify players leveraging defense and commercial aviation verticals to sustain long-term program positions across multiple OEM platforms. TE Connectivity occupies a position exemplifying the connector-centric archetype, where gram-level weight reductions and installation labor savings justify premium positioning against commodity alternatives. These three entities anchor the competitive structure without exhaustive market coverage.
| Leading Market Players |
|---|
| RTX Corporation |
| Latécoère |
| Safran |
| InterConnect Wiring |
| Ducommun |
| TE Connectivity |
| GKN Aerospace |
| Radiall |
| Amphenol Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FAA/EASA-qualified harness suppliers and commodity cable assemblers bifurcates both margin structures and procurement pathways across the EWIS value chain. Premium-tier suppliers commanding multi-year OEM lock-in effects extract value through qualification continuity, while commodity players compete on copper weight and labor arbitrage with compressed pricing power.
Pricing Analysis
Value-based pricing anchored to aircraft operational uptime and maintenance interval extension dominates aerospace-grade EWIS procurement. Three-tier pricing structure across premium, standard, and economy levels separates AS50881-certified military harnesses from commercial aviation build-to-print assemblies and industrial cable commodities. Price differentiation stems from certification tier and geographic delivery cost, with United States-based Boeing supply chain proximity commanding premiums against offshore alternatives. Pricing pressure stems from copper price volatility compressing margin predictability for harness fabricators locked into fixed-price OEM agreements. Defense prime contractors exhibit least price sensitivity due to specification rigidity, while emerging eVTOL manufacturers demonstrate highest sensitivity as they bypass legacy military complexity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Boeing's Everett and Charleston final assembly lines, where production-schedule synchronized delivery commands zero-defect tolerance. Geographic supply concentration centers on the United States, France, and Germany, with Seattle and Toulouse anchoring aerospace manufacturing corridors. Raw material dependencies draw from copper conductor suppliers, polyimide film compounders, and fluoropolymer resin producers. Single-source vulnerability in high-temperature insulation film production exposes the supply chain to disruption risk among limited chemical compounders. Distribution runs through tier-one aerostructures integrators assuming full EWIS design responsibility, displacing traditional tier-two harness houses from direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EWIS market consolidation accelerates as tier-one aerostructures integration contracts force traditional tier-two harness houses toward acquisition or exit. OEM procurement consolidation under systems integration mandates compresses direct supplier relationships to a narrowing qualified base.
For Market Incumbents: Anchor long-term program positions through backward integration into polyimide film and fluoropolymer jacket production, capturing margin pools currently extracted by chemical compounders. Deepen certification investment in EASA CS-25 and SAE AS50881 qualification continuity to defend against emerging connector-centric component houses threatening harness assembly margins. Prioritize capacity addition in India's Bangalore aerospace corridor to intercept PLI scheme incentives and defense indigenization procurement redirection. For New Entrants and Emerging Players: Tier-two MRO providers serving United States narrow-body retrofit compliance timelines represent the most penetrable channel partner type for bypassing OEM direct procurement barriers. Target urban air mobility certification pathways requiring simplified, lightweight EWIS architectures that bypass legacy military specification complexity. Exploit electromagnetic interference testing capacity scarcity in South West England and Germany by positioning as specialized validation partners for new entrant suppliers facing program schedule risk. For Investors and Strategic Acquirers: Exit pathways concentrate in defense-anchored conglomerates seeking commercial aviation diversification and connector-centric component houses pursuing harness assembly vertical integration. Long-term viability favors suppliers with dual-use defense-commercial certification portfolios spanning multiple OEM platforms. Acquisition target archetype: mid-cap harness fabricators with established FAA/EASA qualification continuity and underutilized capacity in Wichita or Bordeaux-Toulouse corridors. Watch fiber-optic substitution rates in avionics networking as inflection indicator for copper conductor demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Insulation Materials | Captive polyimide film production reduces single-source vulnerability exposure for tier-one integrators. |
| Urban Air Mobility Certification Pathway | Simplified EWIS architectures for eVTOL platforms bypass AS50881 timeline barriers blocking defense entry. |
| India Domestic Assembly Capacity | PLI scheme incentives redirect procurement toward Bangalore joint ventures serving regional MRO demand. |
| Digital Thread Integration Investment | Automated harness routing software compresses design-to-manufacturing cycle times for custom installations. |
| Electromagnetic Interference Testing Expansion | Certified laboratory capacity in Bristol and Yeovil addresses shielding validation bottlenecks for new entrants. |
Methodological Framework
SEC 10-K filings, EASA certification databases, and Pentagon procurement records formed the secondary backbone for supply chain mapping and regulatory trajectory assessment. Primary interviews with harness fabrication plant managers, OEM procurement leads at Boeing and Airbus, MRO retrofit specialists, and electromagnetic interference testing laboratory directors validated qualification timeline assumptions and pricing structure intelligence. Bottom-up triangulation across wire harness, connector, and insulation material value chain participants converged with top-down aerospace production forecast reconciliation.
Historical trendline analysis of narrow-body fleet replacement cycles and defense modernization program award patterns informed projection framework construction across the analysis window. Segmentation dimensions modeled include product type, end-user vertical, application function, and installation lifecycle positioning alongside platform-specific certification tier. CAGRs were derived from production schedule synchronization requirements and aftermarket retrofit compliance deadline clustering. Industry-specific forecast inputs incorporated copper price volatility scenarios and REACH substance restriction implementation timelines.
Caveats apply where FAA airworthiness directive acceleration, ECHA regulatory expansion, or hybrid propulsion architecture specification shifts could materially shift the outlook. Forecasts reflect assumptions regarding tier-one aerostructures integration contract persistence and polyimide supply concentration stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Global Precision Resistor Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market
Passive And Interconnecting Electronic Components
Thick Film Resistor Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market