
 Power and Utilities MLCC Market | 2026-2036
Power and Utilities MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
Power and Utilities MLCC Market Insights
Project finance for utility-scale energy storage is tilting procurement toward vendors with balance-sheet stamina. Murata Manufacturing Co., Ltd. leverages its ceramic materials dominance to anchor long-term supply agreements with grid operators. Samsung Electro-Mechanics Co., Ltd. competes through captive semiconductor packaging capabilities that reduce lead times for power module integrators.
Power and Utilities MLCCs are multilayer ceramic capacitors engineered with dielectric compositions—typically barium titanate-based Class 2 or C0G/NP0 Class 1 formulations—to deliver high capacitance density, low equivalent series resistance, and thermal stability across voltage ranges from 50V to several kilovolts in DC-link and snubber applications. High Voltage MLCCs command premium positioning due to insulation reliability requirements in photovoltaic inverters and wind turbine converters, while Flexible MLCCs address mechanical stress tolerance in EV onboard chargers where thermal cycling is severe. Specialty MLCCs occupy narrow but high-margin niches in nuclear plant instrumentation and subsea cable terminations.
FERC Order 2222 in the United States, the EU Green Deal's energy efficiency directives, and Japan's METI carbon neutrality roadmap collectively tighten performance benchmarks for grid-interactive power electronics. These frameworks elevate demand for capacitors certified to IEC 60384 and AEC-Q200 stress-test protocols, effectively filtering out suppliers lacking accredited testing infrastructure. Stakeholders must track how regional content requirements in subsidy-eligible renewable projects redirect sourcing decisions toward domestically qualified component lines.
Market Dynamics
Smart grid deployment cycles are compressing procurement timelines for power conditioning hardware, forcing capacitor suppliers to synchronize production schedules with utility infrastructure rollouts rather than traditional electronics manufacturing rhythms.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation mandates in the United States are expanding addressable demand for grid-interactive MLCCs in inverter and converter modules.
- Barium titanate dielectric refinements:Advanced ceramic formulations are extending voltage tolerance ranges in DC-link applications without sacrificing volumetric efficiency.
- South Korea's semiconductor corridor:Concentrated manufacturing of power modules near captive MLCC fabrication is shortening qualification cycles for utility-scale deployments.
Market Restraints
- Palladium electrode costs:Precious metal price volatility in base electrode formulations is compressing margin structures for Class 2 dielectric producers.
- East Asian supply concentration:Overreliance on Japanese and South Korean ceramic powder suppliers creates geographic vulnerability to seismic and geopolitical disruptions.
- Film capacitor substitution:Polypropylene film technologies are capturing share in high-ripple current inverter applications where thermal cycling tolerance is less critical.
Strategic Opportunities
- India's transmission expansion:Central Electricity Authority mandates for grid modernization are opening procurement channels for IEC 60384-certified components in substation automation.
- Offshore wind converter demand:Subsea cable termination applications require specialty MLCCs with pressure-rated insulation systems absent from standard catalogs.
- EU Green Deal efficiency tiers:Stricter standby power limits are forcing redesigns of auxiliary power supplies in smart meters and grid sensors.
Industry Challenges
- AEC-Q200 qualification timelines:Extended stress-test protocols for automotive-grade crossover products are delaying utility certification parallel tracks.
- Legacy SCADA integration:New capacitor banks must interface with decades-old control architectures without triggering harmonic resonance issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power and Utilities MLCC Market |
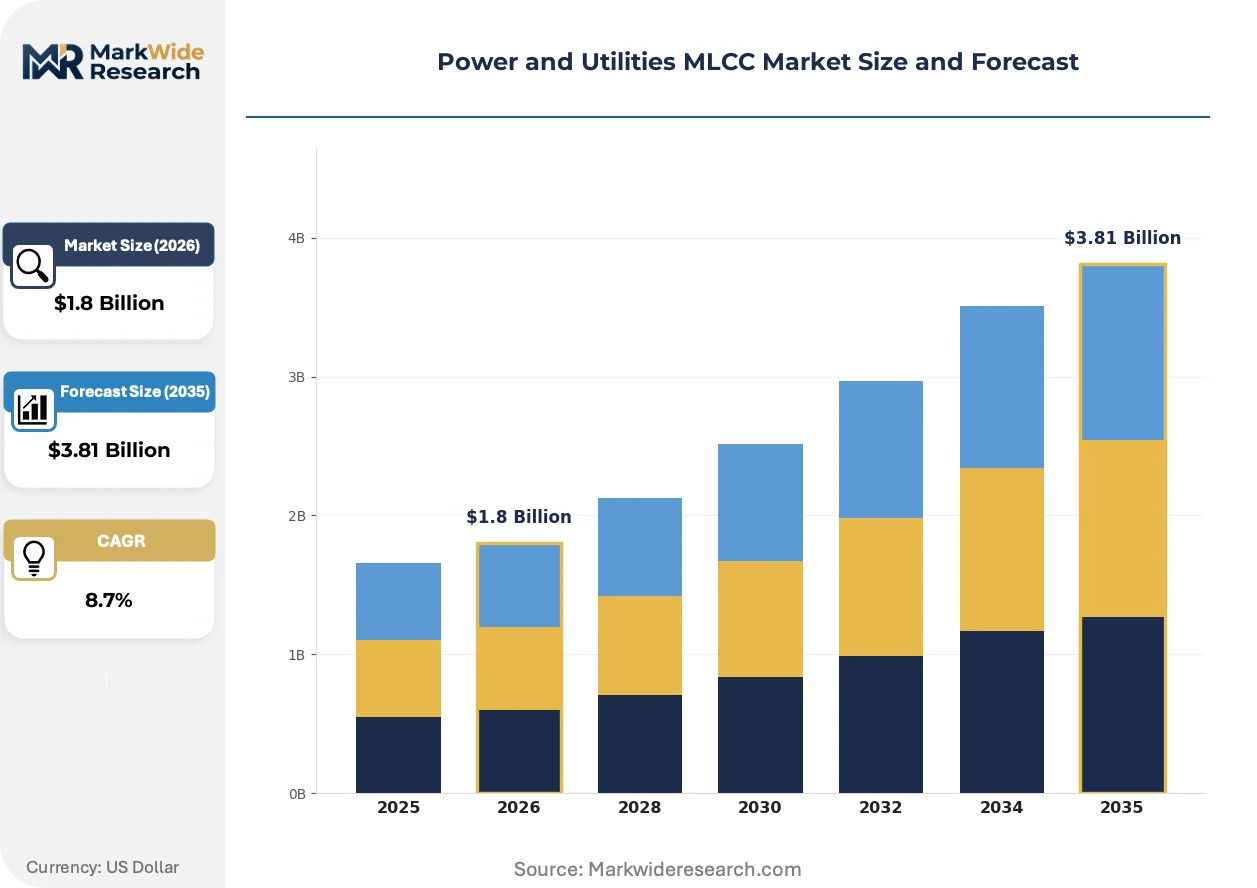
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard MLCCs, High Voltage MLCCs, Flexible MLCCs, Specialty MLCCs Application: Energy Storage Systems, Power Supply Units, Renewable Energy, Electric Vehicles End User: Utilities, OEMs, Industrial Manufacturers, Electric Grid Operators Technology: Hybrid Capacitors, Ceramic, Film Capacitors, Aluminum Electrolytic |
| Companies Covered | Murata Manufacturing Co., Ltd., TDK Corporation, KYOCERA AVX Components Corporation, Samsung Electro-Mechanics Co., Ltd., Taiyo Yuden Co., Ltd., Yageo Corporation, Vishay Intertechnology Inc., Maruwa Co., Ltd., Walsin Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power and Utilities MLCC Market Trends and Innovations
Dielectric material science and regulatory pressure on energy conversion efficiency are jointly redefining performance benchmarks for power electronics passive components.
Nanoscale barium titanate particle engineering is rendering obsolete traditional coarse-grain ceramic structures in high-voltage DC-link applications. Photovoltaic inverter manufacturers in Germany and Japan are adopting these formulations for 1500V string architectures. The shift is compressing qualification cycles for suppliers lacking in-house powder synthesis capabilities.
REACH restrictions on nickel electrode formulations are forcing migration to copper-terminated architectures across EU-bound product lines. The industrial consequence is retooling of firing atmospheres and termination metallization lines. High-voltage MLCC categories for wind turbine converters are experiencing the most acute compliance-driven redesign activity.
Utility procurement departments are consolidating vendor lists around suppliers with accredited IECQ QC 080000 hazardous substance management systems. Direct contracting with capacitor manufacturers is displacing traditional distribution channels for projects above 10 MW. This pattern is most pronounced in Scandinavian markets where state-owned grid operators maintain centralized sourcing functions.
Power and Utilities MLCC Market Segmentation
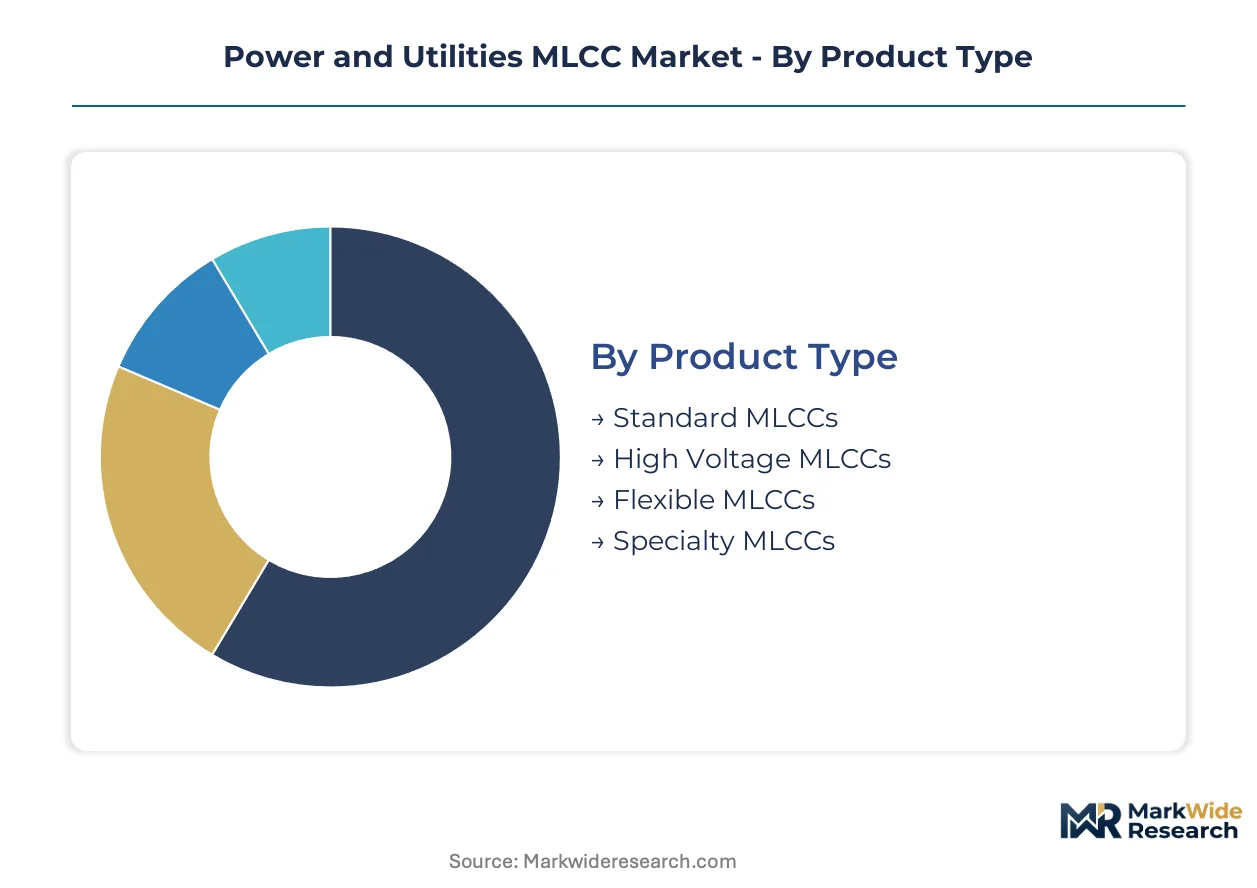
Segmentation in the Power and Utilities MLCC market reveals how dielectric performance requirements diverge across voltage classes and installation environments. Procurement specifications from grid operators and renewable integrators create tiered demand patterns that suppliers must match with distinct qualification pathways.
Product Type:
After-sales service intensity varies sharply across voltage classes, with high-voltage and specialty categories demanding field engineering support that standard commodity lines rarely require.
- Standard MLCCs:These capacitors employ X7R and Y5V dielectric formulations for general-purpose filtering and decoupling below 100V. Demand concentrates in smart meter auxiliary power supplies across Germany and Japan, where EU Green Deal standby power limits are forcing component refreshes in legacy installations.
- High Voltage MLCCs:Barium titanate-based Class 2 dielectrics with optimized grain structures deliver capacitance stability across 500V to 3kV ranges for DC-link applications. Procurement from photovoltaic inverter manufacturers in South Korea's semiconductor corridor is accelerating as 1500V string architectures displace 1000V legacy systems.
- Flexible MLCCs:Polymer-terminated architectures tolerate mechanical stress and thermal cycling in EV onboard chargers.
- Specialty MLCCs:Pressure-rated insulation systems serve subsea cable terminations and nuclear plant instrumentation with extended qualification protocols.
By volume, Standard MLCCs lead. By growth pace, High Voltage MLCCs are expanding most quickly.
Application:
Application-driven segmentation tracks how duty cycles and environmental exposure reshape reliability specifications across deployment contexts.
- Energy Storage Systems:Grid-scale battery installations require MLCCs with extended ripple current tolerance in power conditioning modules. Procurement from US utility-scale developers is tightening around FERC Order 2222 compliance for distributed resource aggregation.
- Power Supply Units:Auxiliary converters in substation automation demand high-temperature stability across -55°C to 150°C operational windows.
- Renewable Energy:Wind turbine converters and solar inverters subject capacitors to voltage transients and harmonic stress. India's Central Electricity Authority mandates for transmission expansion are opening procurement channels for IEC 60384-certified components in new substation builds.
- Electric Vehicles:Onboard chargers and DC-DC converters prioritize volumetric efficiency and thermal cycling resilience.
Renewable Energy commands the largest addressable base. Energy Storage Systems demonstrate the steepest expansion trajectory.
End User:
End-user segmentation exposes how procurement centralization and technical sophistication create divergent commercial relationships.
- Utilities:State-owned grid operators in Scandinavia and South Korea consolidate vendor lists around IECQ QC 080000-certified suppliers, bypassing distribution channels for projects above 10 MW.
- OEMs:Power module integrators in Japan's ceramic component belt synchronize production schedules with captive MLCC fabrication to compress lead times.
- Industrial Manufacturers:Factory automation and process control systems require MLCCs with extended operational lifespans in harsh environments.
- Electric Grid Operators:Transmission and distribution network managers specify components for SCADA integration without triggering harmonic resonance in legacy control architectures.
Utilities represent the highest-value contracting channel. OEMs are gaining share fastest through vertical integration into power module assembly.
Technology:
Technology segmentation captures how dielectric material science and construction methods partition the competitive landscape.
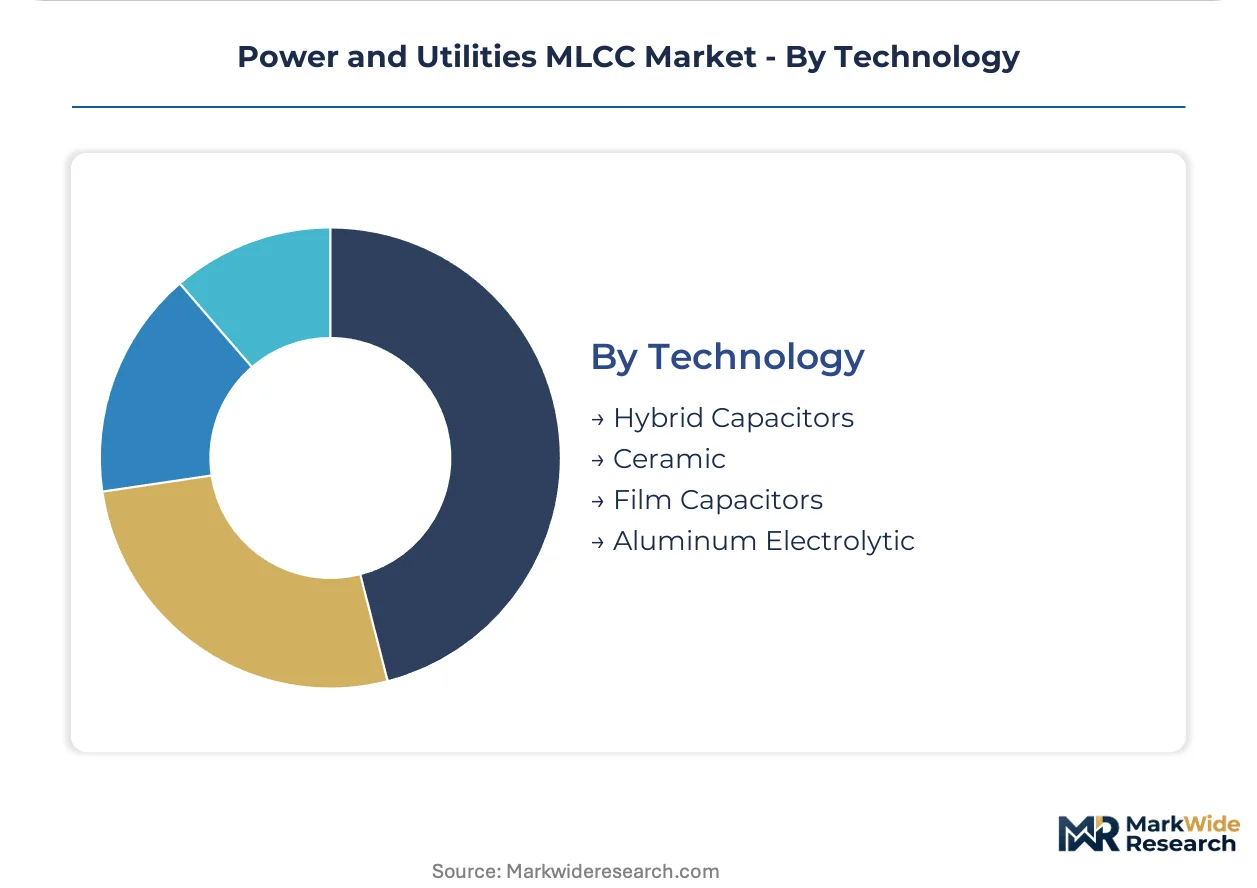
- Hybrid Capacitors:Polymer-ceramic composite constructions combine high capacitance density with low equivalent series resistance for pulsed power applications.
- Ceramic:Barium titanate and C0G/NP0 formulations dominate high-frequency filtering and precision timing circuits. REACH restrictions on nickel electrodes are forcing copper-terminated redesigns across EU-bound product lines.
- Film Capacitors:Polypropylene dielectrics are capturing share in high-ripple current inverter applications where thermal cycling tolerance is less critical than in EV onboard chargers.
- Aluminum Electrolytic:Wet and solid polymer constructions serve bulk energy storage in DC-link applications with lower switching frequency requirements.
Ceramic technology anchors volume production. Hybrid Capacitors are climbing the fastest as power density requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 2222 and the EU Green Deal are redirecting procurement flows toward domestic qualification pathways. Japan's METI carbon neutrality roadmap and India's Central Electricity Authority mandates are compressing vendor selection timelines. East Asian manufacturing clusters retain ceramic powder supply dominance.
United States
Utility-scale energy storage procurement is accelerating under FERC Order 2222 distributed resource aggregation mandates. Grid operators in Texas and California are consolidating vendor lists around IEC 60384-certified suppliers for substation automation projects. The Southwest power corridor is seeing direct contracting displacement of traditional distribution channels for installations above 10 MW.
Germany
Photovoltaic inverter manufacturers are adopting nanoscale barium titanate formulations for 1500V string architectures. REACH restrictions on nickel electrode formulations are forcing copper-terminated redesigns across EU-bound product lines. Bavarian power electronics clusters are experiencing the most acute compliance-driven qualification activity for wind turbine converter applications.
Japan
METI's carbon neutrality roadmap is tightening performance benchmarks for grid-interactive power electronics. The ceramic component belt in Nagoya and surrounding prefectures maintains captive MLCC fabrication synchronized with power module integrator production schedules. Tokyo-area utilities are specifying AEC-Q200 stress-test protocols for automotive-grade crossover products entering utility certification tracks.
South Korea
The semiconductor corridor near Seoul is shortening qualification cycles through concentrated manufacturing of power modules near captive MLCC fabrication. Samsung Electro-Mechanics anchors long-term supply agreements with domestic grid operators. State-owned Korea Electric Power Corporation is centralizing sourcing functions around IECQ QC 080000-certified hazardous substance management systems.
India
Central Electricity Authority mandates for transmission expansion are opening procurement channels for IEC 60384-certified components in new substation builds. Renewable energy integrators in Gujarat and Tamil Nadu are specifying capacitors for 1500V solar architectures. Maharashtra-based power module assemblers are compressing lead times through regional sourcing from East Asian ceramic powder suppliers.
Power and Utilities MLCC Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base organizes around three strategic archetypes: integrated ceramic materials producers with captive powder synthesis, power module integrators with backward integration into passive component supply, and specialty fabricators serving narrow pressure-rated insulation niches. Dominant competitive moves include capacity expansion in high-voltage dielectric formulations and strategic partnerships between inverter manufacturers and accredited testing infrastructure holders.
Within the integrated materials tier, Murata Manufacturing Co., Ltd. and TDK Corporation exemplify channel control through ceramic powder dominance. Samsung Electro-Mechanics Co., Ltd. occupies a position bridging captive semiconductor packaging with utility-scale procurement cycles. These three Japanese and South Korean entities anchor the supply concentration that defines competitive positioning in grid-interactive MLCC sourcing.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| KYOCERA AVX Components Corporation |
| Samsung Electro-Mechanics Co., Ltd. |
| Taiyo Yuden Co., Ltd. |
| Yageo Corporation |
| Vishay Intertechnology Inc. |
| Maruwa Co., Ltd. |
| Walsin Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in South Korea's semiconductor corridor is compressing lead times and hardening supplier bargaining power against procurement officers at European inverter manufacturers. This utilization squeeze feeds directly into pricing posture, as MLCC fabricators prioritize long-term offtake agreements over spot market exposure.
Pricing Analysis
Certification level creates the primary spread between standard commodity MLCCs and premium high-voltage grades. Project-based contract pricing dominates utility-scale procurement, with AEC-Q200 and IEC 60384 certification tiers commanding substantial premiums over uncertified alternatives. Cost compression in standard dielectric formulations is intensifying because palladium electrode volatility squeezes Class 2 producer margins. Price sensitivity peaks among industrial manufacturers sourcing general-purpose filtering components, while utilities demonstrate lowest sensitivity due to reliability-weighted procurement criteria.
Supply Chain Analysis
Barium titanate powder synthesis anchors upstream feedstock control in Japan's ceramic component belt and South Korea's semiconductor corridor, with secondary refinement capacity concentrated in Taiwan. Finished MLCC production draws from ceramic powder, palladium and nickel electrode pastes, and copper termination materials. Single-source vulnerability in Japanese ceramic powder suppliers exposes the chain to seismic disruption risk. Distribution runs through direct manufacturer contracting for projects above 10 MW, displacing traditional electronics distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as state-owned grid operators in Scandinavia and South Korea consolidate vendor lists, compressing supplier margins and forcing qualification investments.
For Market Incumbents: Build certification moats around IECQ QC 080000 hazardous substance management systems to lock out unaccredited competitors. Expand high-voltage dielectric capacity in South Korea's semiconductor corridor to capture FERC Order 2222-driven procurement cycles. Defensive moves must counter film capacitor substitution threats in high-ripple current inverter applications through thermal cycling performance upgrades. For New Entrants and Emerging Players: Pursue India's transmission expansion opportunity under Central Electricity Authority mandates, where IEC 60384 certification gaps create penetrable procurement channels. Target subsea cable termination specialty MLCCs, a narrow niche with extended qualification protocols that deter established commodity producers. Go-to-market leverage rests on pressure-rated insulation system engineering partnerships with offshore wind EPC contractors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated ceramic materials producers with captive powder synthesis and long-term utility supply agreements. Five-to-ten year viability favors suppliers with backward integration into barium titanate formulation rather than merchant powder dependence. Watch for inflection signals in EU Green Deal efficiency tier enforcement, which would accelerate component refresh cycles in legacy smart meter installations.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in High-Voltage Dielectrics | Captures procurement cycles from 1500V solar inverter adoption in Germany and South Korea. |
| Backward Integration into Ceramic Powder Synthesis | Insulates margin structures from Japanese supplier concentration and seismic disruption exposure. |
| Long-term Supply Agreement with State-Owned Utilities | Locks revenue visibility through direct contracting displacement of distribution channels. |
| Copper-Terminated Architecture Migration | Ensures REACH compliance for EU-bound product lines in wind turbine converter applications. |
| Joint Venture with Offshore Wind EPC Contractors | Secures qualification pathways for pressure-rated specialty MLCCs in subsea terminations. |
Research Methodology
The analysis maps high-voltage, flexible, and specialty MLCC sub-sectors, each validated through procurement directors at state-owned utilities, power module integrators, inverter manufacturers, and ceramic materials R&D heads. Primary interview intelligence triangulates against secondary sources including FERC filings, EU Green Deal implementation documents, METI carbon neutrality roadmaps, and IEC certification registries. Bottom-up demand modeling from application-level bill-of-materials analysis converges with top-down market sizing from trade flow data.
Forecast assumptions hold regulatory enforcement timelines and palladium price volatility bands fixed across the projection horizon, while varying smart grid deployment cadence and renewable capacity addition rates. Segmentation dimensions span dielectric class, voltage rating, application duty cycle, and end-user procurement centralization. CAGRs derive from fitted growth curves against historical qualification cycle compression. Industry-specific inputs include utility-scale energy storage project pipelines and photovoltaic inverter architecture migration from 1000V to 1500V systems.
Sensitivities concentrate around EU Green Deal standby power limit enforcement timing and East Asian seismic event probability. Forecasts reflect documented assumptions on ceramic powder supply continuity and REACH electrode formulation phase-out schedules. Material shifts in FERC Order 2222 implementation pace or India Central Electricity Authority procurement centralization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Elastomeric Connectors Market
Passive And Interconnecting Electronic Components
Wirewound Variable Resistors Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Passive Electronic Components in Aerospace & Defense Market
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Germany MLCC Market