
 Wireless Transmitter Chip Market | 2026-2036
Wireless Transmitter Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Transmitter Chip Market Insights
Market Context
China is fragmenting as new foundry capacity reshapes competitive dynamics across the wireless transmitter chip landscape. Qualcomm Incorporated leverages its integrated modem-RF platforms to sustain premium-tier design wins in smartphones and automotive telematics. Broadcom Inc. anchors Wi-Fi 7 chipset supply for enterprise access points and residential routers, while MediaTek Inc. competes aggressively on cost-engineered solutions targeting mid-range consumer electronics and emerging IoT verticals.
Technical Definition and Segment Structure
A wireless transmitter chip is a semiconductor device that modulates baseband signals onto radio-frequency carriers for over-the-air transmission, typically operating across frequency bands from sub-1 GHz to millimeter-wave spectra depending on protocol requirements. These chips enable cordless data exchange in commercial and industrial systems where wired connectivity proves impractical or cost-prohibitive. High-frequency chips dominate margin pools as 5G mmWave and Wi-Fi 6E/7 deployments expand, while Bluetooth technology sustains volume leadership through audio streaming and wearable tethering applications. Digital chips are displacing analog architectures in smart home devices where software-defined radio flexibility reduces BOM complexity and extends protocol upgradability.
Regulatory Environment and Outlook
The FCC governs spectrum allocation and emission limits in the United States, while the EU's Radio Equipment Directive and CE marking framework shape product compliance across European member states. China's MIIT enforces domestic wireless certification through SRRC approval, creating non-tariff barriers that favor local suppliers for government and enterprise procurement. Stakeholders must monitor evolving spectrum harmonization between the FCC and EU bodies, as divergent 6 GHz band rules threaten chipset SKU proliferation and inventory complexity.
Market Dynamics
Automotive OEMs are forcing wireless transmitter chip architectures toward integrated V2X modems as regulatory mandates for connected vehicle safety systems harden across major economies. This demand pull is compressing development cycles and concentrating procurement power among Tier 1 telematics suppliers.
Growth Catalysts
- 5G Infrastructure Deployment:China's MIIT has accelerated domestic baseband certification timelines, creating captive demand for locally produced sub-6 GHz and mmWave chipsets in cellular base stations and industrial IoT gateways.
- EU Cyber Resilience Act:Mandatory baseline security standards for wireless components entering European supply chains are upgrading replacement cycles in industrial automation and smart metering equipment.
- Wi-Fi 7 Protocol Maturation:Enterprise access point manufacturers are absorbing tri-band chipsets for low-latency applications in healthcare imaging and manufacturing machine vision systems.
Market Restraints
- Advanced Node Concentration:Sub-7 nm RF-CMOS fabrication for mmWave transceivers remains concentrated among Taiwan-based foundries, exposing automotive and smartphone OEMs to single-source geopolitical risk.
- Compound Semiconductor Cost Volatility:Gallium nitride substrate prices for high-power base station amplifiers fluctuate with rare earth export licensing from Chinese suppliers.
- Spectrum Fragmentation:Divergent 6 GHz band power rules between the FCC and EU Radio Equipment Directive force chipset vendors to maintain multiple SKUs, inflating inventory carrying costs.
Strategic Opportunities
- India Production-Linked Incentive:The PLI scheme for semiconductor and component manufacturing offers 50% capex reimbursement for domestic wireless transmitter assembly and testing facilities.
- Software-Defined Radio Convergence:Integration of AI-driven beamforming algorithms with reconfigurable RF front-ends is collapsing hardware refresh cycles in private 5G networks for mining and port logistics.
- Direct-to-Module Distribution:Chipset vendors are bypassing traditional distributors to supply calibrated RF modules directly to IoT device OEMs, compressing margin capture at the component level.
Industry Challenges
- RF-Analog Design Talent Scarcity:The specialized skill set combining millimeter-wave circuit design with digital signal processing faces acute shortages in both developed and emerging semiconductor hubs.
- Multi-Protocol Certification Complexity:Simultaneous Bluetooth, Wi-Fi, and cellular regulatory approvals for converged IoT chipsets extend time-to-revenue by 8-14 months across FCC, CE marking, and SRRC frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Transmitter Chip Market |
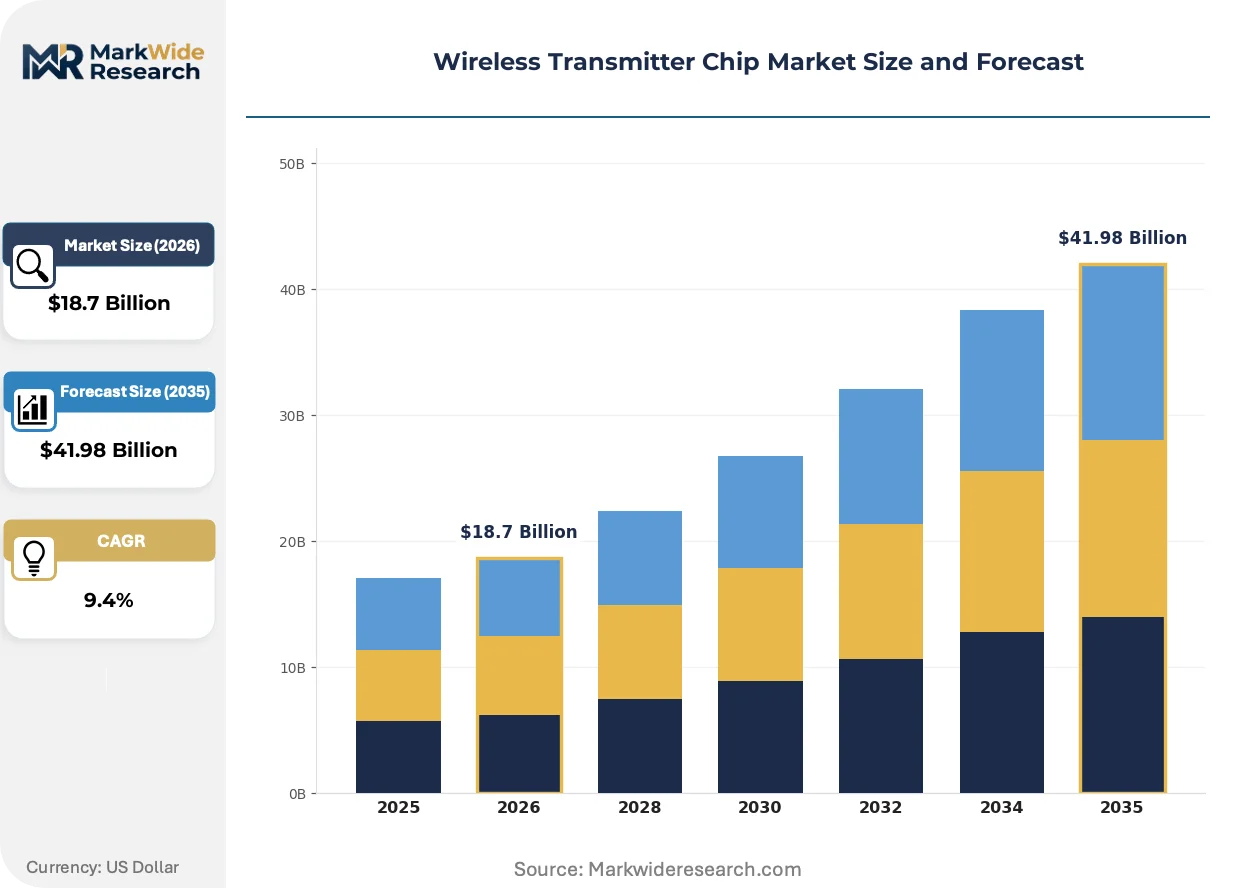
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Frequency Chips, Low-Frequency Chips, Analog Chips, Digital Chips Technology: Wi-Fi, Bluetooth, Zigbee, NFC End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Application: Smart Home Devices, Wearable Technology, Medical Devices, Remote Monitoring |
| Companies Covered | Qualcomm Incorporated, Broadcom Inc., Texas Instruments Incorporated, MediaTek Inc., NXP Semiconductors, STMicroelectronics, Skyworks Solutions, Infineon Technologies, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Transmitter Chip Market Trends and Innovations
Silicon-to-antenna integration is collapsing traditional boundaries between semiconductor fabrication and RF system design, compressing supply chain tiers and reallocating value capture toward module-level suppliers.
Digital pre-distortion and envelope tracking techniques are collapsing the power amplifier efficiency gap between CMOS and gallium nitride processes. Smartphone OEMs are absorbing these architectures to extend battery endurance in 5G mmWave handsets. The structural consequence is collapsing discrete PA vendor margins as modem-RF integration advances.
The EU Cyber Resilience Act mandates vulnerability disclosure and software update guarantees for wireless devices with network connectivity. Industrial automation vendors are reconfiguring product roadmaps to embed over-the-air firmware architectures. Automotive telematics modules face the steepest compliance burden, with OEMs accelerating partnerships with security-certified chipset suppliers.
Consolidated procurement of multi-protocol wireless chipsets is displacing single-function RF component purchasing among IoT device manufacturers. Direct sourcing from fabless semiconductor houses is replacing distribution through broadline electronics distributors. This pattern concentrates most visibly in China's consumer electronics manufacturing clusters, where vertical integration into module assembly compresses supplier counts.
Wireless Transmitter Chip Market Segmentation
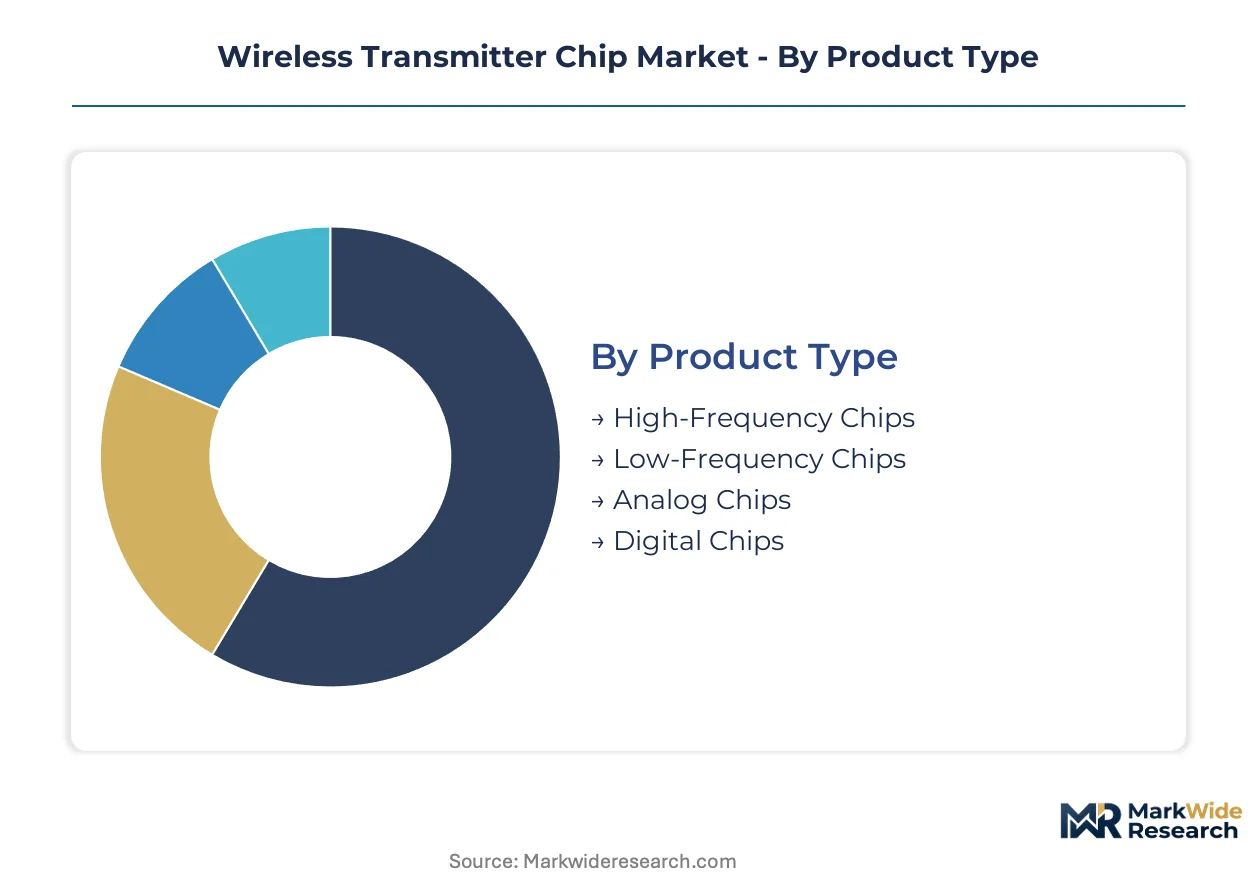
Wireless transmitter chip segmentation reveals divergent margin structures and replacement cycles across frequency bands, protocols, and end-use verticals. Procurement patterns vary sharply between automotive telematics programs with decade-long design locks and consumer electronics with annual refresh cadences.
Product Type:
High-frequency chips turn inventory fastest as mmWave base stations and Wi-Fi 7 routers drive aggressive procurement, while analog architectures face extended replacement cycles in legacy industrial installations.
- High-Frequency Chips:These devices operate above 6 GHz, encompassing sub-6 GHz cellular and mmWave spectra for 5G infrastructure and advanced Wi-Fi protocols. Demand concentrates in China's domestic base station buildout where MIIT certification timelines compress supplier qualification windows. Automotive radar modules at 77-81 GHz are pulling silicon-germanium BiCMOS capacity from traditional foundry allocations.
- Digital Chips:Software-defined radio architectures integrate baseband processing with reconfigurable RF front-ends, collapsing discrete component counts in smart home gateways. Procurement is shifting toward module-level suppliers in Shenzhen and Dongguan manufacturing clusters as OEMs seek pre-certified subsystems.
- Low-Frequency Chips:Sub-1 GHz designs serve LPWAN and legacy IoT endpoints with extended product lifecycles. These devices command lower ASPs but sustain volume through smart metering deployments in European utilities.
- Analog Chips:Discrete voltage-controlled oscillators and mixers persist in cost-optimized consumer electronics where digital overhead proves prohibitive. Foundry capacity for these mature nodes faces competition from power management ICs.
Digital chips are gaining share at the steepest rate while high-frequency chips anchor the revenue base through premium-tier cellular and automotive sockets.
Technology:
Cost tiers separate enterprise-grade Wi-Fi infrastructure from disposable Bluetooth peripherals, with Zigbee and NFC occupying distinct volume-maturity positions in industrial and payment ecosystems.
- Wi-Fi:Tri-band Wi-Fi 6E/7 chipsets integrate 2.4 GHz, 5 GHz, and 6 GHz radios with MU-MIMO beamforming for enterprise access points. Healthcare imaging and manufacturing machine vision systems in Germany and Japan are absorbing premium-tier silicon with deterministic latency guarantees.
- Bluetooth:Low-energy variants dominate audio streaming and wearable tethering with annual design refresh cycles. Codec integration and LE Audio multicast are differentiating flagship smartphone platforms.
- Zigbee:Mesh networking protocols serve smart lighting and building automation with decade-long deployment horizons. Thread protocol convergence is collapsing standalone Zigbee procurement in North American residential markets.
- NFC:Contactless payment and access control modules operate at 13.56 MHz with stringent EMVCo certification requirements. Automotive digital key applications are expanding antenna-in-package integration.
Bluetooth sustains the volume base while Wi-Fi captures the steepest expansion trajectory through enterprise infrastructure upgrades.
End User:
Customer concentration varies from fragmented consumer electronics OEMs to consolidated automotive Tier 1s, with telecommunications operators exerting the heaviest procurement leverage through carrier certification mandates.
- Consumer Electronics:Smartphones, tablets, and peripheral devices drive annual chipset refresh cycles with aggressive cost-down targets. Flagship models absorb integrated modem-RF platforms while mid-tier devices prioritize discrete component flexibility.
- Automotive:V2X telematics modules and connected infotainment systems impose functional safety requirements under ISO 26262. OEMs in Germany and Japan are consolidating supplier lists around security-certified chipset vendors.
- Industrial Automation:Private 5G networks and wireless sensor networks demand extended temperature ranges and deterministic latency. Mining and port logistics operators in Australia and Chile are deploying software-defined radio architectures.
- Telecommunications:Base station OEMs procure sub-6 GHz and mmWave chipsets under multi-year supply agreements with volume commitments. China's domestic production targets are reshaping vendor qualification criteria.
Consumer electronics anchors shipment volumes while automotive applications are climbing the fastest on regulatory mandates for connected vehicle safety.
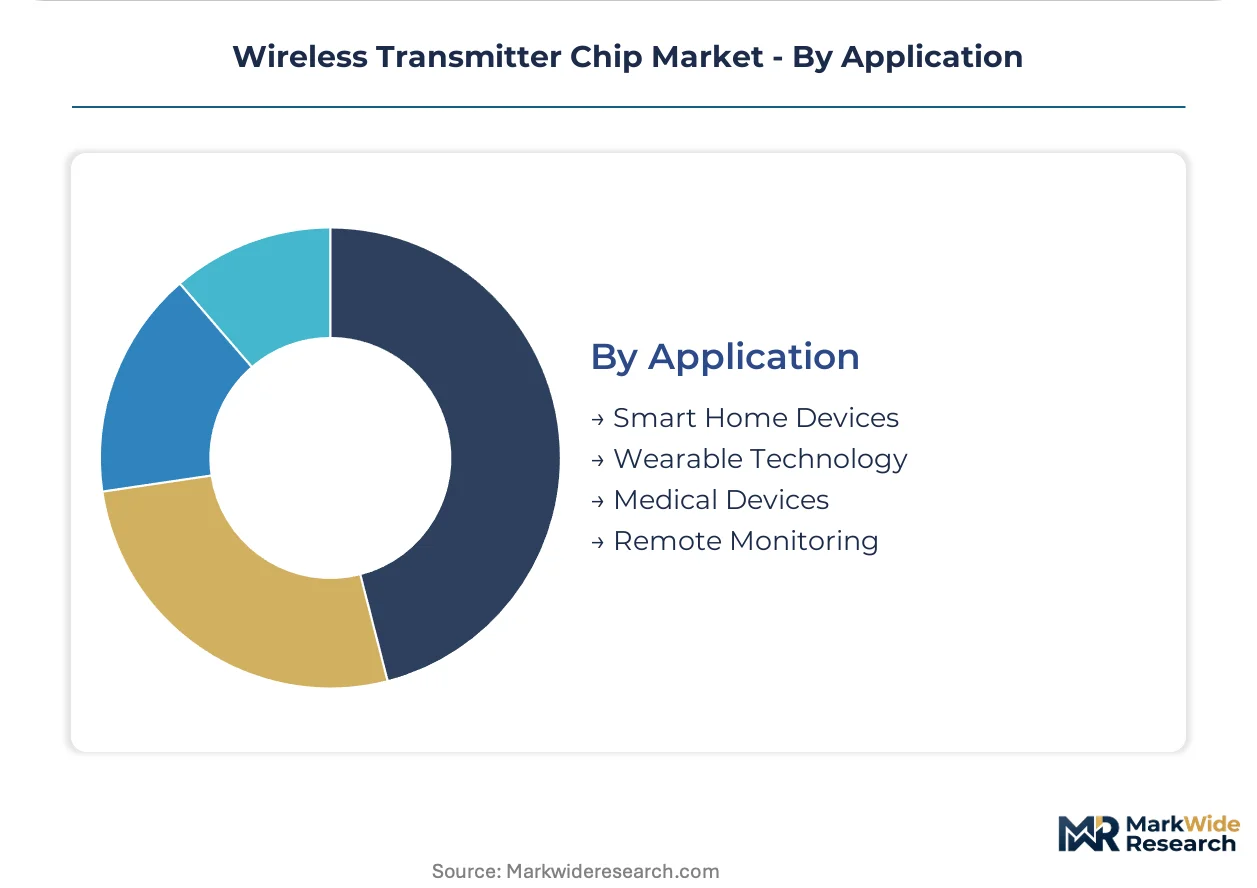
Application:
Supply concentration differs between module-integrated smart home devices and regulated medical equipment, with remote monitoring spanning both consumer wellness and clinical reimbursement pathways.
- Smart Home Devices:Converged multi-protocol chipsets combining Wi-Fi, Bluetooth, and Thread are displacing single-function RF components. Amazon and Google ecosystem certification requirements are filtering supplier participation.
- Wearable Technology:Ultra-low-power transmitters with integrated sensor hubs serve fitness trackers and smartwatches with sub-milliwatt sleep currents. Biometric authentication is driving UWB coexistence requirements.
- Medical Devices:Wireless patient monitors and implantable devices face FDA and EMA electromagnetic compatibility scrutiny. Bluetooth Medical Device Profile certification extends development timelines.
- Remote Monitoring:Industrial asset tracking and environmental sensors span licensed cellular and unlicensed LPWAN protocols. Solar-powered endpoints in agricultural and utility deployments prioritize receive sensitivity over transmit power.
Smart home devices anchor the volume base while medical devices gain share fastest on aging demographics and reimbursement expansion for remote patient monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors spectrum governance for the dominant geography, with SRRC certification timelines compressing supplier windows for domestic 5G infrastructure and IoT endpoints.
United States
FCC spectrum auctions for 6 GHz and mmWave bands are accelerating Wi-Fi 7 and 5G fixed wireless deployments. NIST cybersecurity frameworks for IoT devices are tightening procurement standards for federal smart city contracts. Austin and San Jose clusters concentrate fabless design houses developing software-defined radio architectures for private cellular networks.
Germany
Automotive OEMs in Stuttgart and Munich are mandating V2X modem integration for 2025 model year compliance with UNECE WP.29 regulations. The EU Cyber Resilience Act is forcing industrial automation vendors in Bavaria to embed over-the-air update capabilities. Dresden's silicon photonics foundry ecosystem is attracting RF-CMOS co-development partnerships for radar modules.
Japan
METI's Beyond 5G promotion strategy is channeling R&D subsidies into terahertz communication chipsets for 6G prototyping. Osaka-based electronics conglomerates are consolidating RF component procurement for automotive radar at 77-81 GHz. Yokohama's wireless test equipment cluster is expanding calibration capacity for mmWave base station chipsets.
South Korea
Ministry of Science and ICT funding for 6G R&D is driving pre-standard chipset development at Seoul-area research institutes. Samsung and LG procurement power is concentrating mmWave modem supply among security-certified vendors. Pangyo's semiconductor design valley is specializing in integrated modem-RF platforms for flagship smartphones.
India
TRAI's recommendations on 6 GHz unlicensed access are pending, with domestic OEMs preparing Wi-Fi 6E/7 roadmaps for enterprise markets. The PLI scheme for semiconductor assembly and testing is drawing wireless module manufacturers to Gujarat and Karnataka. Bangalore's design services ecosystem is expanding RF-analog talent pools for Bluetooth and LPWAN chipsets.
Wireless Transmitter Chip Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct tiers: integrated platform vendors commanding premium sockets, cost-optimized specialists capturing mid-range volume, and regional foundry-affiliated suppliers serving captive domestic demand. Strategic archetypes include modem-RF integrators, discrete RF component specialists, and software-defined radio platform vendors. Competitive moves center on M&A for mmWave talent acquisition and strategic partnerships with automotive Tier 1s for V2X certification.
Within the integrated platform tier, Qualcomm Incorporated and Broadcom Inc. exemplify divergent scale-capability positioning. Qualcomm anchors premium-tier smartphone and automotive telematics sockets through captive modem-RF integration. Broadcom occupies a position in enterprise Wi-Fi infrastructure with tri-band chipset supply. MediaTek Inc. represents the cost-engineered specialist archetype, competing on mid-range consumer electronics and emerging IoT verticals with aggressive foundry partnerships.
| Leading Market Players |
|---|
| Qualcomm Incorporated |
| Broadcom Inc. |
| Texas Instruments Incorporated |
| MediaTek Inc. |
| NXP Semiconductors |
| STMicroelectronics |
| Skyworks Solutions |
| Infineon Technologies |
| Intel Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in mature-node RF-CMOS foundries across China is compressing spot pricing for low-frequency Bluetooth and sub-GHz chipsets while tightening margins for analog specialists serving cost-optimized consumer electronics. This utilization asymmetry between legacy and advanced nodes shapes supplier behavior, with foundries prioritizing 5G mmWave and automotive radar wafer starts that command premium pricing and longer contract terms.
Pricing Analysis
Price spreads between Taiwan-sourced mmWave transceivers and mainland China-produced sub-6 GHz modules exceed three-to-one on a per-band basis, reflecting yield differentials and certification overhead. Three-tier pricing structure across premium, standard, and economy levels stratifies by protocol complexity and automotive qualification grade. Cost compression in mid-range Wi-Fi chipsets is intensifying because MediaTek and Realtek are absorbing foundry discounts to defend socket share against vertically integrated platform vendors. Consumer electronics OEMs in Shenzhen exhibit acute price sensitivity, while German automotive Tier 1s prioritize functional safety certification over unit cost.
Supply Chain Analysis
TSMC and Samsung Foundry anchor advanced-node capacity for integrated modem-RF platforms, while SMIC and Hua Hong dominate mature-node production for discrete Bluetooth and LPWAN transmitters. Gallium nitride substrates for high-power base station amplifiers draw from Chinese rare earth processing and Japanese epitaxial wafer suppliers. Single-source vulnerability concentrates in Taiwan-based 7 nm and below RF-CMOS fabrication, exposing Qualcomm and Apple supply chains to geopolitical disruption. Distribution runs through direct-to-module relationships with Shenzhen and Dongguan EMS clusters, bypassing traditional broadline electronics distributors for IoT device OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent wireless transmitter chip vendors face substitution pressure from software-defined radio platforms that collapse discrete component counts through reconfigurable RF front-ends, threatening traditional analog specialists with obsolescence.
For Market Incumbents: Pre-empt SDR platform encroachment by acquiring mmWave beamforming algorithm startups and embedding AI-driven calibration into modem-RF integration roadmaps. Secure automotive V2X certification through partnerships with German and Japanese Tier 1s before EU Cyber Resilience Act mandates harden compliance barriers. Vertical integration into gallium nitride substrate sourcing mitigates Chinese rare earth export volatility. For New Entrants and Emerging Players: Build out captive supply relationships with India's PLI-subsidized assembly and testing facilities in Gujarat and Karnataka to serve European industrial automation demand with cost-advantaged LPWAN modules. Target private 5G network deployments in Australian mining and Chilean port logistics where software-defined radio architectures displace legacy discrete RF procurement. Lead with pre-certified subsystems that compress customer time-to-revenue against incumbent component sales cycles. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because RF-analog design talent scarcity and multi-protocol certification complexity erect durable barriers against commoditization. Acquisition targets should display concentrated mmWave engineering teams with automotive radar or 5G base station track records. Monitor NXP and Infineon automotive telematics module design win announcements as inflection indicators for platform vendor market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Modem-RF Platform Integration | Qualcomm's integrated architectures collapse discrete PA vendor margins in 5G mmWave handsets. |
| Gallium Nitride Supply Security | Backward integration into substrate sourcing buffers Infineon and Wolfspeed against Chinese export licensing volatility. |
| Automotive V2X Certification | NXP's security-certified chipset partnerships with Stuttgart OEMs lock in decade-long design cycles. |
| Software-Defined Radio Convergence | AI-driven beamforming integration collapses hardware refresh cycles in private 5G mining networks. |
| India Manufacturing Footprint | PLI-subsidized Gujarat facilities attract MediaTek and Realtek module assembly for European smart metering demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with RF semiconductor engineering directors, automotive Tier 1 procurement leads, and Shenzhen EMS operations managers; and secondary validation through MIIT SRRC certification databases, FCC equipment authorization filings, and SEC 10-K disclosures from Qualcomm, Broadcom, and Skyworks. Bottom-up shipment modeling by frequency band and protocol triangulated against top-down foundry wafer allocation estimates from TSMC and SMIC investor materials.
Forecast inputs span product type segmentation across high-frequency, digital, low-frequency, and analog architectures; technology splits between Wi-Fi, Bluetooth, Zigbee, and NFC; and end-use verticals from automotive telematics to industrial automation. CAGRs were derived from regression analysis of historical foundry capacity expansion against MIIT 5G base station deployment targets and EU Cyber Resilience Act compliance timelines. Automotive V2X mandate schedules and Wi-Fi 7 enterprise upgrade cycles served as industry-specific demand drivers.
Stress conditions across Taiwan Strait logistics disruption, gallium nitride substrate price spikes, and divergent 6 GHz spectrum harmonization failure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding foundry yield progression and regulatory certification timeline stability. Quarterly review of MIIT base station procurement awards and automotive OEM V2X supplier announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Zigbee Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
4D Radar Chip Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market