
 Asia-Pacific Embedded Antenna Systems Market | 2026-2036
Asia-Pacific Embedded Antenna Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Embedded Antenna Systems Market Insights
Capability gaps in ceramic substrate processing and millimeter-wave tuning are reorganizing competitive tiers across the Asia-Pacific Embedded Antenna Systems Market. Murata Manufacturing leverages its monolithic integration expertise to dominate high-frequency ceramic antenna supply. Quectel Wireless Solutions Co Ltd anchors its position through module-level bundling that reduces customer RF engineering overhead. Huawei Technologies Co Ltd sustains captive demand via vertical control over baseband-to-antenna chains in domestic 5G infrastructure.
Embedded antenna systems integrate radiating elements, impedance-matching networks, and ground planes directly into device chassis or circuit boards, typically operating between 700 MHz and 6 GHz with dielectric constants of 3.5 to 10.2 for substrate materials. These assemblies eliminate external whip or blade protrusions while maintaining gain specifications of 2 to 5 dBi for cellular and short-range protocols. Patch antennas and integrated antennas command the widest deployment bases, though multifunction antennas that combine cellular, Wi-Fi, and GPS in single apertures are capturing the fastest design-in momentum as device makers prioritize internal volume reduction. Bluetooth and Wi-Fi technology segments remain mature volume channels, while 5G embedded antenna variants are absorbing disproportionate engineering investment due to beamforming complexity and carrier aggregation requirements.
China's MIIT enforces GB standards for radio transmission equipment that dictate spurious emission limits and SAR thresholds, forcing antenna redesigns for devices entering the Chinese market. Japan's TELEC certification and South Korea's RRA framework impose additional pattern efficiency and interoperability tests that filter out non-compliant suppliers. India's WPC licensing for imported radio gear creates procedural friction that favors local assembly partnerships. Stakeholders must monitor evolving spectrum auctions in Australia and Thailand, where mid-band 5G allocations will determine which antenna architectures achieve design wins in next-generation IoT and industrial automation deployments.
Market Dynamics
Carrier aggregation mandates for 5G-V2X automotive platforms are compressing antenna design cycles across the Asia-Pacific Embedded Antenna Systems Market, forcing module suppliers to pre-integrate impedance-matching networks before chassis allocation.
Growth Catalysts
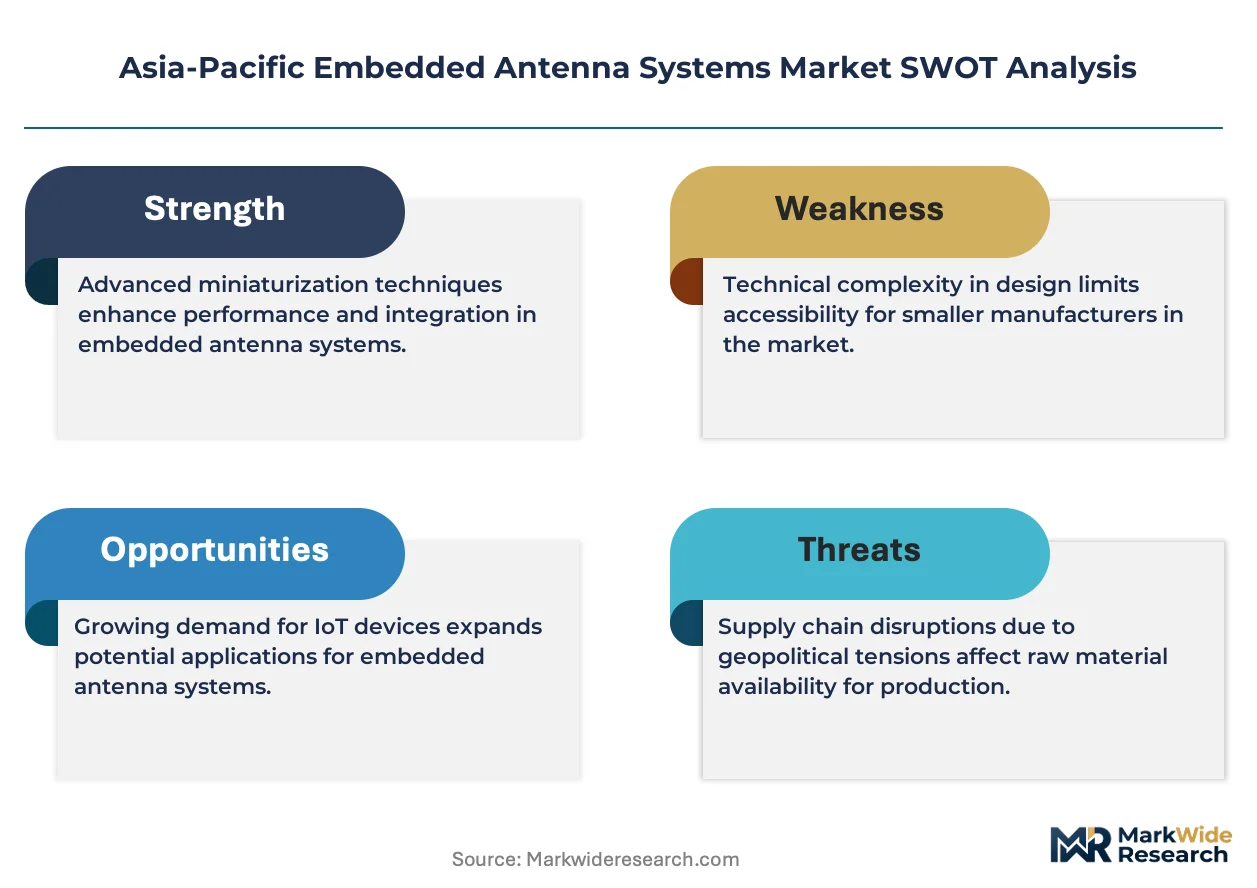
- MIIT spectrum allocation:China's 5G-V2X frequency assignments for connected vehicles are mandating embedded antenna architectures that eliminate external blade protrusions. Automotive OEMs in the Guangdong-Jiangsu corridor are accelerating module procurement.
- Smart manufacturing mandates:Japan's METI industrial digitization push requires millimeter-wave capable antennas for factory automation networks. Machine builders are specifying multifunction apertures combining cellular and Wi-Fi.
- Ceramic substrate demand:High-frequency operation above 3.5 GHz is driving dielectric constant specifications toward 10.2 materials. Electronics contract manufacturers are consolidating procurement around monolithic integration capabilities.
Market Restraints
- Millimeter-wave tuning complexity:Beamforming calibration for 28 GHz and 39 GHz bands requires specialized anechoic chamber infrastructure. Few Asia-Pacific testing facilities can certify pattern efficiency across full automotive temperature ranges.
- Raw material concentration:High-purity alumina and LTCC ceramic substrates concentrate among Japanese and Taiwanese suppliers. Inventory buffers for these materials extend supplier qualification timelines.
- TELEC certification friction:Japan's pattern efficiency and interoperability testing protocols filter out non-compliant antenna designs. Foreign module vendors face six-month certification queues that delay design wins.
Strategic Opportunities
- Thailand mid-band 5G auction:Upcoming spectrum allocations for industrial automation will determine antenna architecture standards for Southeast Asian IoT deployments. Early certification positioning captures design-in momentum.
- Module-level bundling:RF engineering overhead reduction through pre-integrated antenna-modem combinations is displacing discrete component procurement. Contract manufacturers value reduced validation cycles.
- India WPC localization:Import licensing friction for radio gear favors local assembly partnerships. Joint ventures with domestic electronics manufacturers bypass procedural delays.
Industry Challenges
- Millimeter-wave engineering talent:Scarcity of RF engineers capable of beamforming algorithm development and electromagnetic simulation is extending product development timelines. Universities in South Korea and Taiwan are expanding specialized curricula.
- Multi-protocol integration complexity:Combining cellular, Wi-Fi, GPS, and Bluetooth in single apertures requires trade-offs between gain specifications and internal volume constraints. Device makers demand iterative prototype cycles that strain supplier engineering resources.
- GB standard redesign cycles:China's spurious emission limits and SAR thresholds force antenna redesigns for each device variant entering the market. Validation costs accumulate across product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Embedded Antenna Systems Market |
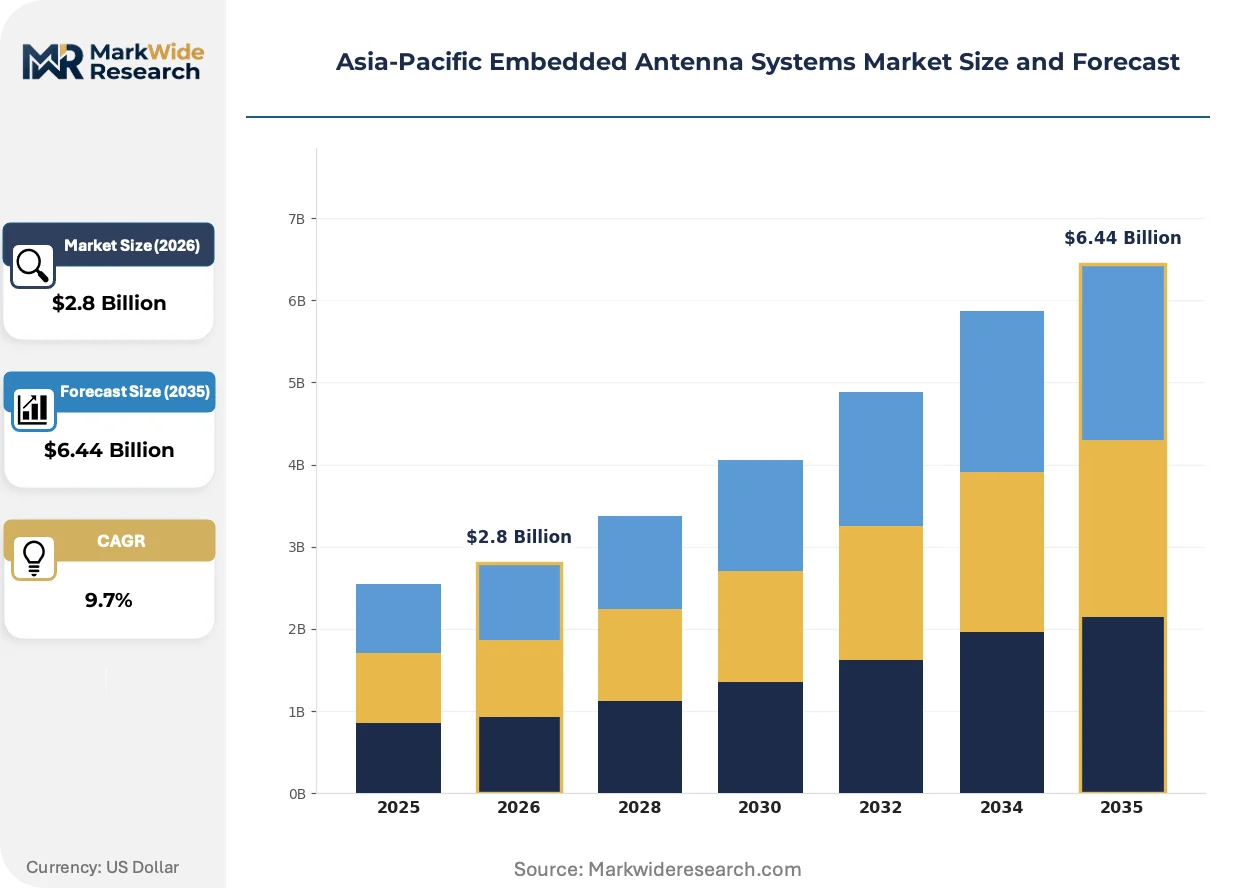
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microstrip Antennas, Patch Antennas, Integrated Antennas, Multifunction Antennas End User: Telecommunications, Consumer Electronics, Automotive, Medical Devices Technology: 4G, 5G, Wi-Fi, Bluetooth Application: IOT Devices, Wearable Technology, Smart Home Systems, Industrial Automation |
| Companies Covered | Comba Telecom Systems Holdings Ltd, Yageo Corporation, Quectel Wireless Solutions Co Ltd, Huawei Technologies Co Ltd, Murata Manufacturing, Molex, Taoglas, TE Connectivity, Kyocera AVX, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Embedded Antenna Systems Market Trends and Innovations
Antenna-in-package architectures are compressing the boundary between semiconductor and passive component supply chains, requiring new collaboration models between foundries and ceramic substrate processors.
Low-temperature co-fired ceramic (LTCC) multilayer substrates are supplanting traditional PCB-based antenna implementations in automotive radar and 5G millimeter-wave modules. Tier-1 automotive suppliers in Japan and South Korea are adopting LTCC for 77 GHz radar front-ends. This substrate transition is enabling three-dimensional antenna pattern routing that PCB etching cannot achieve, compressing module footprints by half.
China's GB standards for radio transmission equipment are tightening spurious emission limits for devices operating above 6 GHz. MIIT enforcement is forcing antenna redesigns that incorporate additional filtering stages before final impedance matching. Smartphone and automotive telematics manufacturers targeting the Chinese market are pre-qualifying architectures against draft standard revisions.
Electronics contract manufacturers are consolidating antenna procurement through module-level RF subsystem contracts rather than discrete component purchasing. Design validation responsibility is shifting upstream to antenna-module suppliers. This procurement compression is most visible in the Guangdong-Jiangsu manufacturing corridor, where volume scale determines supplier tier access.
Asia-Pacific Embedded Antenna Systems Market Segmentation
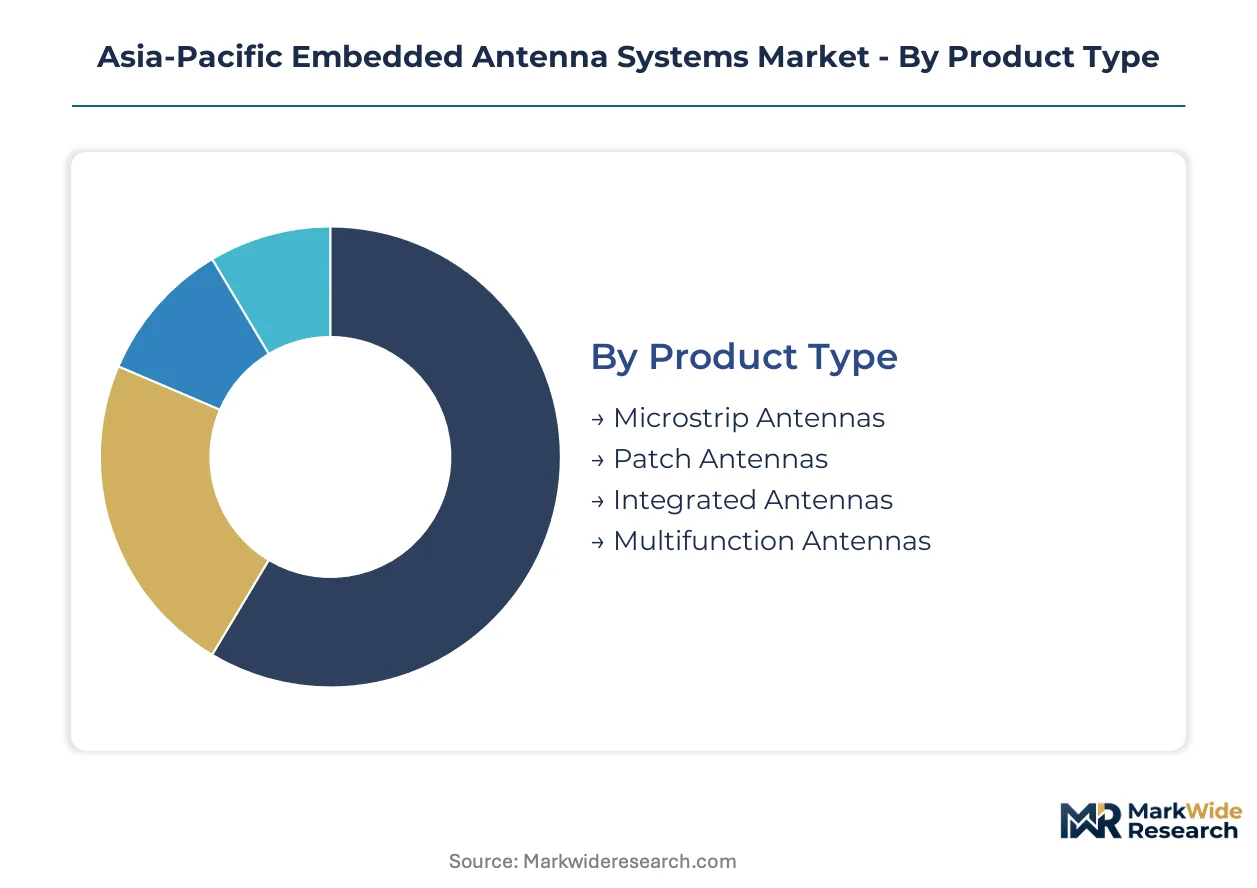
Embedded antenna architectures vary sharply by operating frequency, integration depth, and regulatory exposure across Asia-Pacific deployment contexts. Procurement patterns diverge between automotive OEMs seeking millimeter-wave certification and consumer electronics contract manufacturers prioritizing volume scale.
Product Type:
MIIT's GB standards for spurious emissions and SAR thresholds force distinct antenna redesigns for each substrate architecture entering the Chinese market.
- Patch Antennas:Planar radiating elements etched onto dielectric substrates with dielectric constants of 3.5 to 10.2 dominate telecommunications infrastructure and consumer electronics in the Guangdong-Jiangsu corridor. Contract manufacturers specify these for 700 MHz to 6 GHz cellular bands where gain requirements of 2 to 5 dBi must coexist with minimal vertical clearance.
- Multifunction Antennas:Single-aperture designs combining cellular, Wi-Fi, and GPS radiators are capturing design-in momentum as device makers prioritize internal volume reduction. Japanese automotive OEMs specify these for connected vehicle platforms where MIIT's 5G-V2X mandates eliminate external blade protrusions.
- Microstrip Antennas:Low-profile implementations on PCB substrates serve cost-sensitive IoT deployments across Southeast Asian manufacturing hubs.
- Integrated Antennas:Direct chassis-embedded implementations with impedance-matching networks pre-integrated suit high-volume smartphone and wearable production.
Established volume favors patch configurations; emerging adoption favors multifunction architectures.
End User:
Customer procurement scale determines supplier tier access, with automotive and telecommunications buyers commanding dedicated engineering resources.
- Automotive:Connected vehicle platforms require embedded antennas operating across 5G-V2X, Wi-Fi, and UWB protocols with full automotive temperature range certification. OEMs in Japan and South Korea specify LTCC substrate implementations for 77 GHz radar front-ends.
- Telecommunications:Base station and CPE manufacturers drive demand for high-gain arrays with beamforming calibration. China's MIIT spectrum allocations for mid-band 5G determine architecture selection for domestic infrastructure deployments.
- Consumer Electronics:Smartphone and tablet manufacturers in the Guangdong-Jiangsu corridor prioritize multifunction apertures that reduce RF engineering overhead through module-level bundling.
- Medical Devices:Wearable health monitors and implantable telemetry systems require SAR-compliant implementations with minimal power consumption.
Procurement concentration sits with automotive and telecommunications buyers; medical device demand remains fragmented across specialized applications.
Technology:
Carrier aggregation complexity and beamforming requirements create divergent engineering investment profiles across protocol generations.
- 5G:Millimeter-wave operation at 28 GHz and 39 GHz demands specialized anechoic chamber infrastructure for pattern efficiency certification. Japan's TELEC framework filters out non-compliant designs through six-month testing queues.
- Wi-Fi:Mature volume channel spanning 2.4 GHz and 5 GHz bands with established supply chains in Taiwan and South Korea. Smart home system manufacturers specify these for cost-optimized IoT deployments.
- 4G:Legacy cellular implementations retain volume in industrial automation networks where Thailand's pending mid-band spectrum auction will determine upgrade timelines.
- Bluetooth:Low-energy protocols dominate wearable technology and short-range sensor networks with minimal certification friction.
Engineering investment concentrates on 5G architectures; Bluetooth and Wi-Fi sustain mature procurement volumes.
Application:
Deployment environment determines substrate selection, with industrial settings demanding ceramic implementations that consumer wearables can forgo.
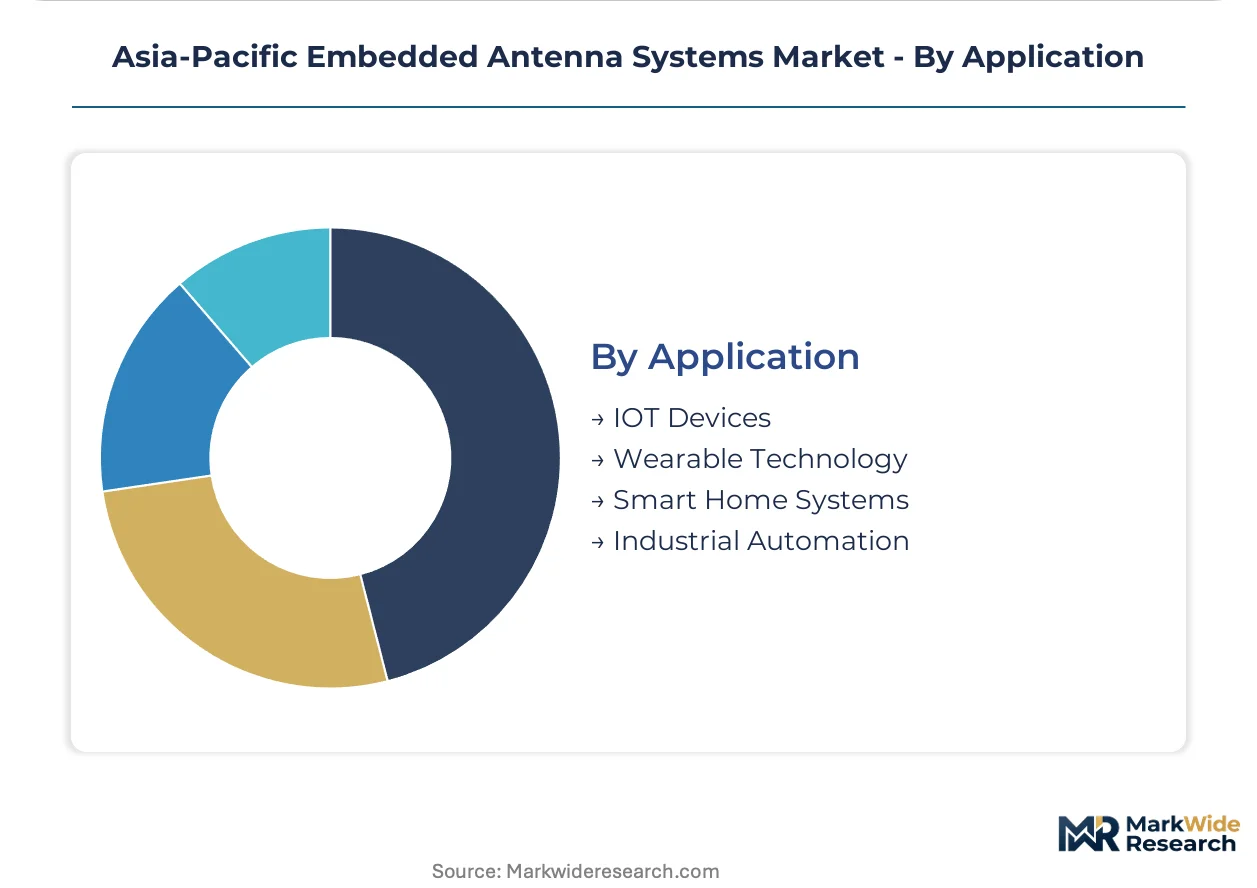
- Industrial Automation:Factory automation networks in Japan's METI-digitized manufacturing sector specify millimeter-wave capable antennas with LTCC substrates for 77 GHz radar and 5G private networks. Machine builders require multifunction apertures combining cellular and Wi-Fi in vibration-resistant packages.
- IoT Devices:Sensor networks and asset trackers across Southeast Asia prioritize cost-optimized PCB-based implementations where India's WPC licensing friction favors local assembly partnerships.
- Smart Home Systems:Voice assistants and security hubs integrate Wi-Fi and Bluetooth protocols with minimal gain requirements.
- Wearable Technology:Fitness bands and smartwatches demand SAR-compliant antennas with extreme volume constraints.
Industrial automation commands premium substrate specifications; IoT device procurement scales through cost-optimized implementations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Japan and South Korea accept premium pricing for millimeter-wave certified modules, while contract manufacturers in China's Guangdong-Jiangsu corridor drive aggressive cost compression for consumer electronics volumes.
China
MIIT's 5G-V2X spectrum allocations mandate embedded antenna architectures for connected vehicles, eliminating external blade protrusions. GB standards for spurious emissions and SAR thresholds force redesign cycles for each device variant entering the market. The Guangdong-Jiangsu manufacturing corridor concentrates electronics contract manufacturers who consolidate procurement through module-level RF subsystem contracts.
Japan
METI's industrial digitization push requires millimeter-wave capable antennas for factory automation networks. TELEC certification imposes pattern efficiency and interoperability testing protocols that filter out non-compliant designs through six-month queues. Tier-1 automotive suppliers specify LTCC substrate implementations for 77 GHz radar front-ends in the Chubu/Nagoya industrial belt.
South Korea
RRA framework testing requirements for radio equipment create regulatory friction that favors established domestic suppliers. Machine builders specify multifunction apertures combining cellular and Wi-Fi for smart manufacturing deployments. RF engineering talent scarcity extends product development timelines as universities expand specialized curricula.
India
WPC licensing for imported radio gear creates procedural friction that favors local assembly partnerships with domestic electronics manufacturers. Cost-optimized PCB-based antenna implementations serve sensor networks and asset trackers across manufacturing hubs. Joint ventures bypass import licensing delays while capturing government procurement preferences.
Thailand
Pending mid-band 5G spectrum allocations for industrial automation will determine antenna architecture standards for Southeast Asian IoT deployments. Electronics manufacturing investment from Japanese and Korean firms concentrates in the Eastern Economic Corridor. Early certification positioning captures design-in momentum for next-generation factory networks.
Asia-Pacific Embedded Antenna Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Embedded Antenna Systems Market. Ceramic substrate processors with monolithic integration capabilities command premium positioning in high-frequency applications, while module-level bundling specialists capture volume through RF engineering overhead reduction. The competitive structure separates into three archetypes: integrated component manufacturers, module subsystem suppliers, and telecommunications equipment vendors with captive demand. Dominant competitive moves include strategic partnerships for anechoic chamber certification access and capacity expansion for LTCC multilayer substrate processing.
Within the integrated component tier, Murata Manufacturing and Yageo Corporation occupy positions defined by materials science capabilities and dielectric substrate processing expertise. Among module subsystem suppliers, Quectel Wireless Solutions Co Ltd exemplifies the RF engineering overhead reduction archetype through pre-integrated antenna-modem combinations. Huawei Technologies Co Ltd represents telecommunications equipment vendors with vertical control over baseband-to-antenna supply chains in domestic 5G infrastructure deployments.
| Leading Market Players |
|---|
| Comba Telecom Systems Holdings Ltd |
| Yageo Corporation |
| Quectel Wireless Solutions Co Ltd |
| Huawei Technologies Co Ltd |
| Murata Manufacturing |
| Molex |
| Taoglas |
| TE Connectivity |
| Kyocera AVX |
| Others |
Pricing and Supply Chain Analysis
LTCC multilayer substrate capacity utilization above 85% across Japanese and Taiwanese suppliers compresses margin structures for automotive-grade antenna modules while elevating price floors for high-frequency ceramic implementations. Contract manufacturers in China's Guangdong-Jiangsu corridor leverage volume scale to extract per-unit concessions, forcing tier-2 suppliers to absorb yield-loss costs or exit certified supply pools.
Pricing Analysis
After-sales calibration services and extended TELEC certification support contracts capture lifetime value exceeding initial module sales by 40-60% for millimeter-wave implementations. Three-tier pricing structure across premium automotive-certified, standard industrial-grade, and economy IoT-consumer levels separates suppliers by anechoic chamber access and ceramic substrate purity grades. Cost compression in economy tiers intensifies because contract manufacturers consolidate procurement through module-level RF subsystem contracts. Automotive OEMs in Japan and South Korea exhibit lowest price sensitivity, prioritizing pattern efficiency guarantees over per-unit cost.
Supply Chain Analysis
Strait of Malacca transit routes and Shanghai-Nagoya shipping lanes underwrite just-in-time delivery schedules for high-purity alumina and LTCC green tape shipments from Japanese and Taiwanese substrate processors. Geographic supply concentration centers on Japan, Taiwan, and South Korea for ceramic substrates; China dominates PCB-based implementations and final module assembly. Raw material dependencies include high-purity alumina, silver-palladium metallization pastes, and low-loss dielectric ceramics. Single-source vulnerability concentrates in 77 GHz radar-qualified LTCC suppliers, with only three facilities regionally certified for automotive temperature range validation. Distribution runs through tier-1 automotive supplier hubs in Chubu/Nagoya and electronics manufacturing services clusters in Shenzhen-Dongguan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive OEMs and telecommunications equipment vendors who consolidate procurement through module-level RF subsystem contracts, squeezing discrete component suppliers into narrower margin bands.
For Market Incumbents: Compound defensive positioning through captive anechoic chamber certification infrastructure and backward integration into LTCC substrate processing to offset margin pressure from module-level bundling specialists. Lock in multi-year supply agreements with high-purity alumina processors before capacity constraints harden. Prioritize TELEC pre-certification investments to compress six-month validation queues that currently filter out foreign competitors. For New Entrants and Emerging Players: Anchor in India's WPC-licensed local assembly partnerships to bypass import friction for cost-optimized PCB-based IoT antenna implementations. Thailand's pending mid-band 5G spectrum auction creates the most penetrable white-space for industrial automation antenna certification. Pursue joint venture structures with established electronics manufacturing services providers to access Guangdong-Jiangsu corridor volume without direct customer qualification overhead. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors module-level bundling specialists with pre-integrated antenna-modem combinations over discrete component pure-plays. Long-term viability over the projection horizon hinges on millimeter-wave engineering talent pipelines and anechoic chamber certification access rather than manufacturing scale alone. Acquisition target archetype: ceramic substrate processors with monolithic integration capabilities serving automotive radar and 5G private network deployments. Signal to watch: MIIT draft standard revisions for spurious emission limits above 6 GHz, which will force redesign cycles favoring suppliers with rapid prototyping capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Anechoic Chamber Certification Partnership | TELEC and MIIT pattern efficiency validation access filters out non-compliant suppliers through six-month queues. |
| LTCC Substrate Capacity Expansion | Monolithic integration capabilities for 77 GHz radar front-ends command premium positioning in automotive supply chains. |
| Module-Level RF Subsystem Integration | Pre-integrated antenna-modem combinations reduce customer engineering overhead and displace discrete component procurement. |
| India Local Assembly Joint Venture | WPC licensing friction favors domestic partnerships that bypass import delays and capture government procurement preferences. |
| Thailand 5G Certification Pre-Positioning | Early mid-band spectrum auction positioning captures design-in momentum for Southeast Asian industrial automation deployments. |
Research Methodology
Cross-validation between primary interviews with RF engineering directors at automotive tier-1 suppliers and secondary analysis of MIIT GB standard filings, TELEC certification databases, and customs trade data anchors the qualitative findings. Stakeholder roles engaged include antenna module procurement managers at contract manufacturers, ceramic substrate processing engineers, telecommunications equipment vendor platform architects, and regulatory affairs specialists navigating WPC and RRA frameworks. Bottom-up triangulation across product-level bill-of-materials analysis and top-down validation against national spectrum allocation filings ensures consistency.
Sensitivity analysis around carrier aggregation complexity and beamforming calibration requirements informs the analytical framework across the analysis window. Segmentation dimensions modeled include substrate architecture type, end-user vertical, protocol generation, and regional regulatory cluster. CAGRs derive from installed base projections for connected vehicle platforms and factory automation networks, cross-referenced against MIIT and METI deployment targets. Industry-specific forecast inputs incorporate LTCC substrate capacity expansion timelines and anechoic chamber certification queue durations.
Material uncertainties — MIIT standard revision timing, Thailand spectrum auction outcomes, and alumina supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and automotive platform standardization trajectories that may shift with OEM consolidation decisions. Practitioners should keep alternative scenarios live as 5G-V2X deployment schedules and industrial digitization subsidy levels evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Ethernet Phys Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Automotive Transceivers Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Industrial Internet Chip Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Japan Digital Signal Processor Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
5G Chip Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market