
 Earphone Bluetooth Chip Market | 2026-2036
Earphone Bluetooth Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Earphone Bluetooth Chip Market Insights
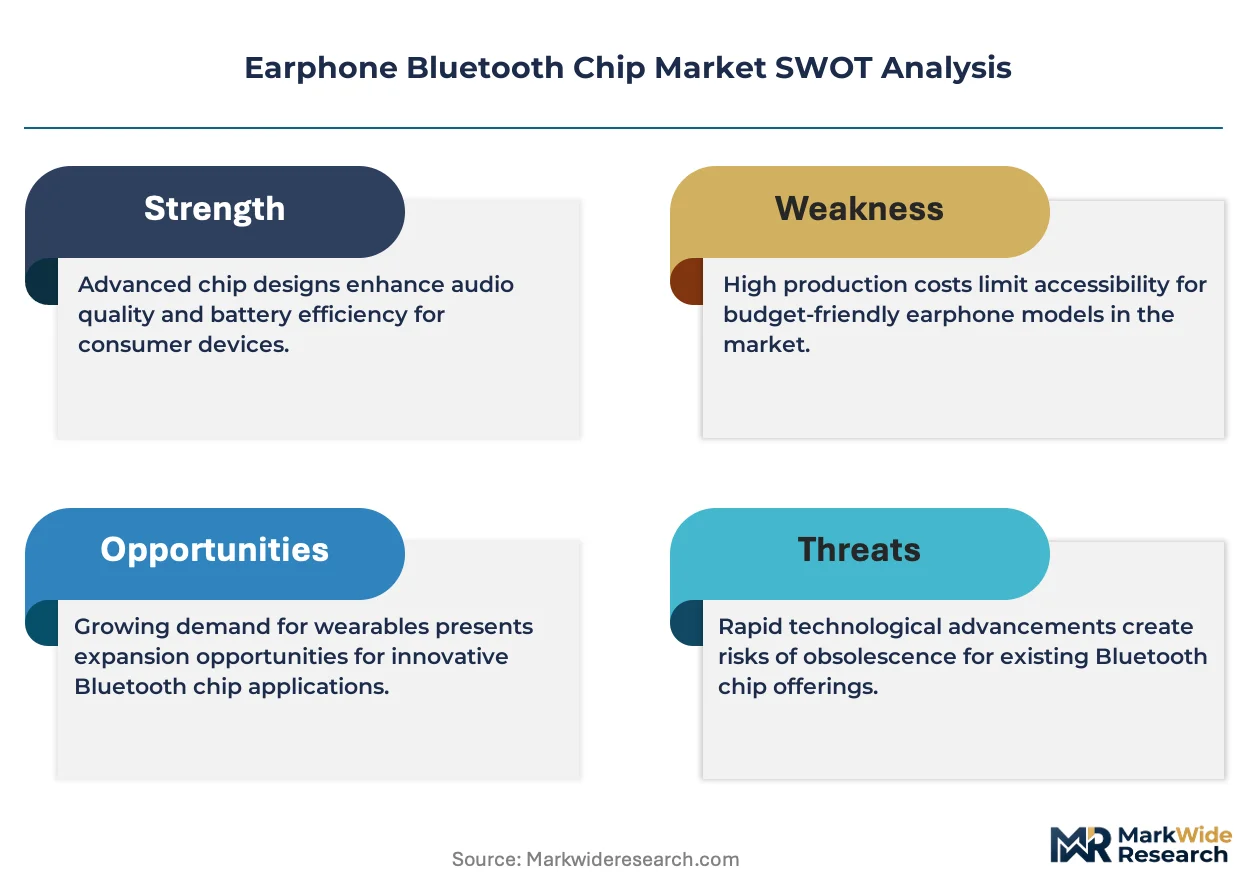
The gap between premium audio chipsets and commodity Bluetooth controllers is expanding in concrete terms. Qualcomm Incorporated leverages its aptX codec portfolio to dominate high-fidelity tiers, while MediaTek anchors volume production for mid-range true wireless platforms. Airoha Technology competes aggressively on cost-optimized solutions for white-label manufacturers across East Asian supply chains.
An earphone Bluetooth chip is a system-on-chip integrating radio frequency transceivers, baseband processors, and audio codecs within a single die, typically fabricated on 22nm or 40nm process nodes to balance power consumption with signal stability. Its primary commercial purpose is to enable wireless audio streaming between source devices and earphones while managing battery life, latency, and multipoint connectivity. True wireless configurations command the dominant share of silicon volume, though LDAC-enabled chips for audiophile-grade over-ear headphones capture disproportionate margin pools. SBC remains the baseline codec for economy-tier neckband products, where ASP compression limits R&D recovery.
FCC certification requirements in the United States mandate specific absorption rate thresholds and spectrum compliance for 2.4GHz transmission, directly influencing antenna design and power amplifier selection. The EU's Radio Equipment Directive and REACH substance restrictions constrain material choices for European-bound shipments, adding compliance layers to packaging and solder formulations. Stakeholders must monitor whether China's GB standards for wireless devices tighten interoperability testing, as this would reshape qualification timelines for new entrants.
Market Dynamics
True wireless stereo architectures are forcing chipmakers to consolidate RF transceivers, audio DSPs, and power management units into monolithic dies, compressing bill-of-materials costs while tightening latency tolerances below 40 milliseconds for gaming and video synchronization.
Growth Catalysts
- MIIT transmission standards:China's tightened wireless regulations are accelerating migration toward higher-efficiency 22nm process nodes among Shenzhen-based ODMs, creating captive demand for advanced Bluetooth controllers.
- Low-latency gaming segments:Mobile esports tournaments in South Korea and Japan are specifying sub-50ms audio response thresholds, pulling premium chipset procurement toward specialized aptX Adaptive and LC3plus implementations.
- LDAC codec proliferation:Sony's royalty-free licensing of high-resolution audio protocols is expanding addressable market for audiophile-grade over-ear headphones beyond Japan into European and North American specialty retailers.
Market Restraints
- 12-inch wafer allocation constraints:Foundry capacity bottlenecks at TSMC and Samsung are extending lead times for 22nm Bluetooth SoCs beyond 26 weeks, constraining volume ramp for mid-tier TWS platforms.
- REACH substance restrictions:ECHA limitations on lead-free solder formulations and halogenated flame retardants are forcing European-bound chip packaging redesigns, adding qualification costs without performance gains.
- Proprietary codec fragmentation:Qualcomm's aptX, Samsung's Scalable Codec, and Apple's AAC extensions are creating interoperability dead zones, forcing white-label manufacturers to license multiple IP stacks.
Strategic Opportunities
- India's PLI scheme for electronics:The government's production-linked incentive program for IT hardware is attracting contract manufacturers to Noida and Chennai, creating localized procurement nodes for entry-level neckband chips.
- Auracast broadcast audio:Bluetooth LE Audio's public address streaming capability is opening venue-scale deployments in airports, theaters, and houses of worship, requiring purpose-built transmitter-receiver silicon.
- Hearing aid convergence:FDA's 2022 over-the-counter hearing aid classification is pulling audio chip architectures toward medical-grade noise cancellation and prescription-tunable frequency response curves.
Industry Challenges
- RF analog design talent scarcity:Experienced engineers capable of optimizing 2.4GHz antenna matching networks and harmonic suppression are concentrated among a handful of fabless design houses in San Diego and Taipei.
- FCC Part 15 certification timelines:Unintentional radiator testing for new Bluetooth implementations averages 14-18 weeks, compressing product launch windows against seasonal consumer electronics cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earphone Bluetooth Chip Market |
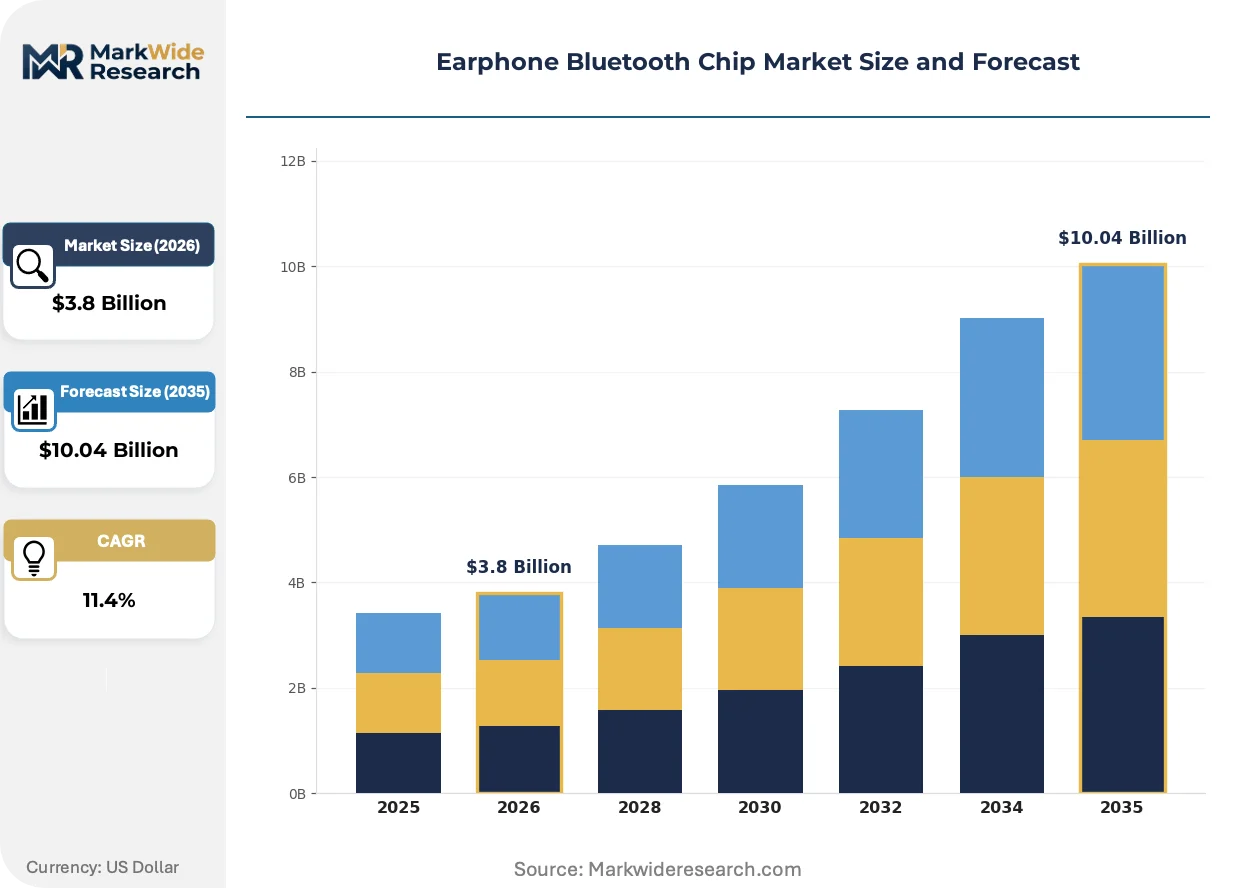
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: True Wireless, Neckband, Over-Ear, In-Ear Technology: AptX, AAC, SBC, LDAC End User: Consumers, Professionals, Sports Enthusiasts, Audiophiles Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Qualcomm Incorporated, STMicroelectronics, Texas Instruments Incorporated, Nordic Semiconductor, NXP Semiconductors, Silicon Laboratories, Dialog Semiconductor, MediaTek, Airoha Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earphone Bluetooth Chip Market Trends and Innovations
Silicon vendors are racing to integrate AI-driven adaptive noise cancellation directly onto Bluetooth SoCs, eliminating the need for separate DSP companion chips and reshaping power budgets for all-day wearables.
LE Audio with Auracast broadcast capabilities is absorbing market attention from legacy A2DP streaming protocols, particularly among enterprise AV integrators specifying conference room and hospitality deployments. Corporate IT procurement teams in Germany and the United States are piloting Auracast-enabled earbuds for hot-desking environments, compressing demand for proprietary DECT wireless headsets in open-plan offices.
REACH substance restrictions are forcing solder formulation changes across European-bound shipments, with ECHA's candidate list expansion for SVHCs compelling chip packaging suppliers to eliminate brominated epoxy mold compounds. Mid-tier ODMs in Dongguan are responding by dual-sourcing substrate materials from Japanese and Taiwanese suppliers, adding qualification overhead but preserving EU market access.
Direct-to-consumer audio brands are bypassing traditional retail distributors, compressing channel margins and accelerating product refresh cycles. Shenzhen-based OEMs are selling TWS platforms under private labels through TikTok Shop and Temu, fragmenting procurement authority away from Best Buy and MediaMarkt category managers. This disintermediation is most visible in North American and Western European markets where influencer-driven discovery is displacing shelf-space marketing.
Earphone Bluetooth Chip Market Segmentation
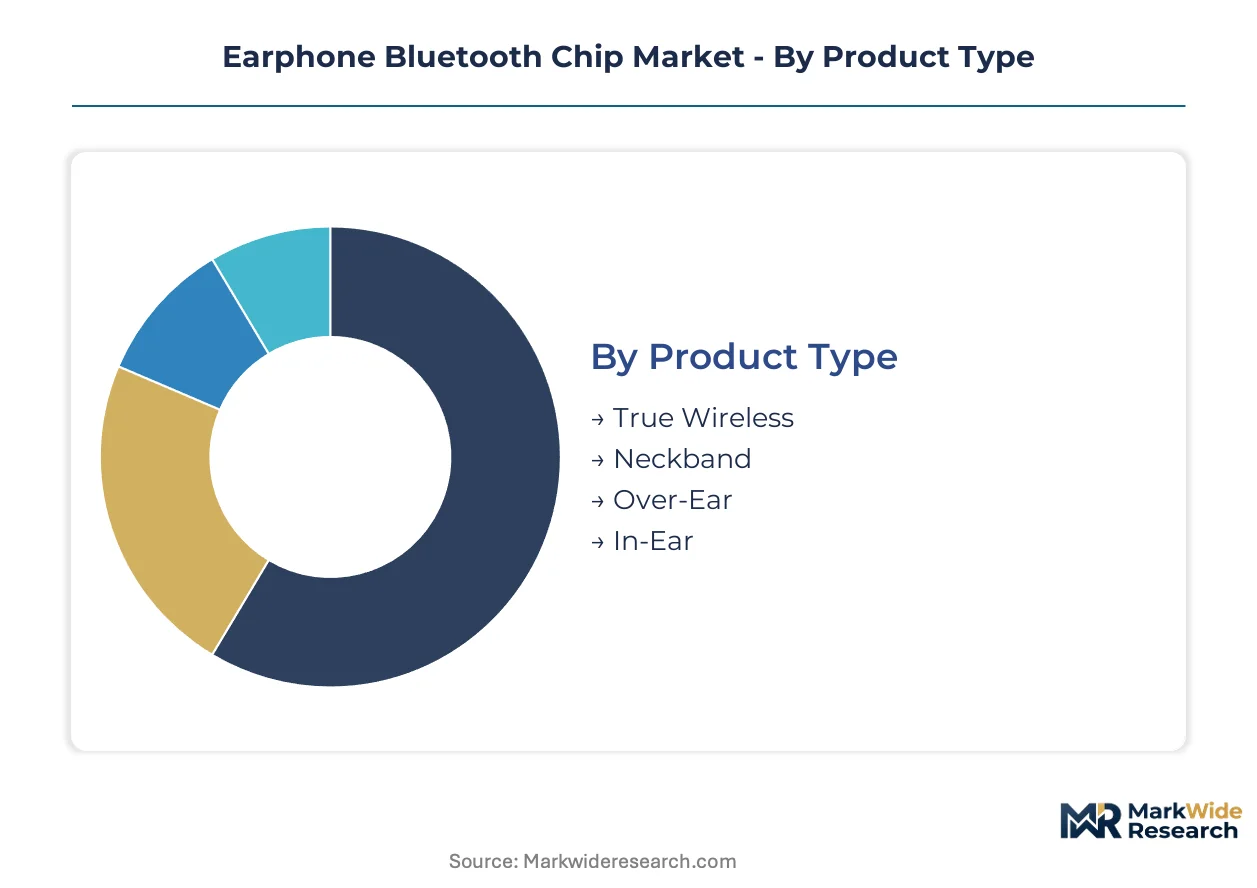
Bluetooth chip procurement patterns diverge sharply across earphone configurations, with form factor and codec technology dictating silicon specifications, power budgets, and ASP recovery timelines. Understanding these segment boundaries clarifies why foundry capacity allocates disproportionately to certain die configurations while others face margin compression.
Product Type:
Replacement cycles vary dramatically by wearable form factor, with true wireless platforms demanding annual refresh rates that outpace over-ear alternatives by a factor of two.
- True Wireless:Dual-chip or single-chip stereo solutions integrate RF transceivers, audio DSPs, and battery management for cord-free left-right synchronization. Shenzhen-based ODMs dominate procurement for Asia-Pacific assembly lines serving mobile-first consumers who prioritize pocketability over battery longevity.
- Over-Ear:Larger acoustic enclosures accommodate discrete amplifier stages and roomier antenna designs, enabling LDAC and aptX Adaptive implementations at lower thermal density. Demand clusters in Japanese and German specialty retail channels where stationary listening sessions justify premium codec licensing.
- Neckband:Collar-mounted battery packs permit simpler single-chip Bluetooth controllers with reduced power management complexity, anchoring volume production for Indian and Southeast Asian price-sensitive segments.
- In-Ear:Wired-to-wireless conversion kits and fitness-focused designs occupy a shrinking niche as true wireless costs compress, though hearing aid convergence applications are preserving medical-grade sub-segments.
Volume placements concentrate in True Wireless; the faster expansion belongs to Over-Ear.
Technology:
Codec selection directly determines royalty stacks, die area requirements, and interoperability certification burdens for chipmakers serving differentiated tiers.
- AptX:Qualcomm's proprietary codec family commands premium licensing fees and requires dedicated DSP blocks for adaptive bitrate streaming. Gaming peripheral manufacturers in South Korea specify sub-50ms latency variants, pulling silicon procurement toward San Diego-based fabless design houses.
- LDAC:Sony's royalty-free high-resolution protocol demands higher RF stability and expanded audio buffer memory, limiting viable suppliers to those with 22nm fabrication access. European audiophile retailers are expanding shelf space for LDAC-enabled over-ear configurations.
- AAC:Apple's preferred codec for iOS ecosystem integration requires optimized packet loss concealment algorithms, creating captive demand among MFi-certified accessory programs.
- SBC:The mandatory baseline codec for A2DP compliance occupies minimal silicon area and carries zero licensing overhead, preserving its lock on economy-tier neckband shipments to Indian contract manufacturers.
Shipment volumes skew toward SBC; steepest expansion trajectory belongs to LDAC.
End User:
User archetypes impose distinct performance thresholds that cascade through chip specification sheets and foundry queue priorities.
- Consumers:Mass-market buyers prioritize all-day battery life and multipoint connectivity over acoustic fidelity, driving procurement toward integrated single-chip solutions with aggressive power gating.
- Audiophiles:Resolution-maximizing users demand native DSD support and THD+N specifications below 0.001%, forcing discrete DAC companion chips and premium substrate materials that constrain gross margins.
- Professionals:Call center and hybrid workforce deployments specify beamforming microphone arrays and enterprise-grade security protocols, requiring dedicated neural processing units for voice isolation.
- Sports Enthusiasts:Sweat resistance and secure fit priorities translate to IPX-rated enclosures with accelerometer integration for fitness tracking, adding sensor hub requirements to baseline Bluetooth controllers.
Consumer segment anchors absolute volume; audiophile-tier procurement is climbing the fastest.
Distribution Channel:
Channel structure determines firmware customization needs, with direct-to-consumer models enabling over-the-air update capabilities that wholesale programs rarely justify.
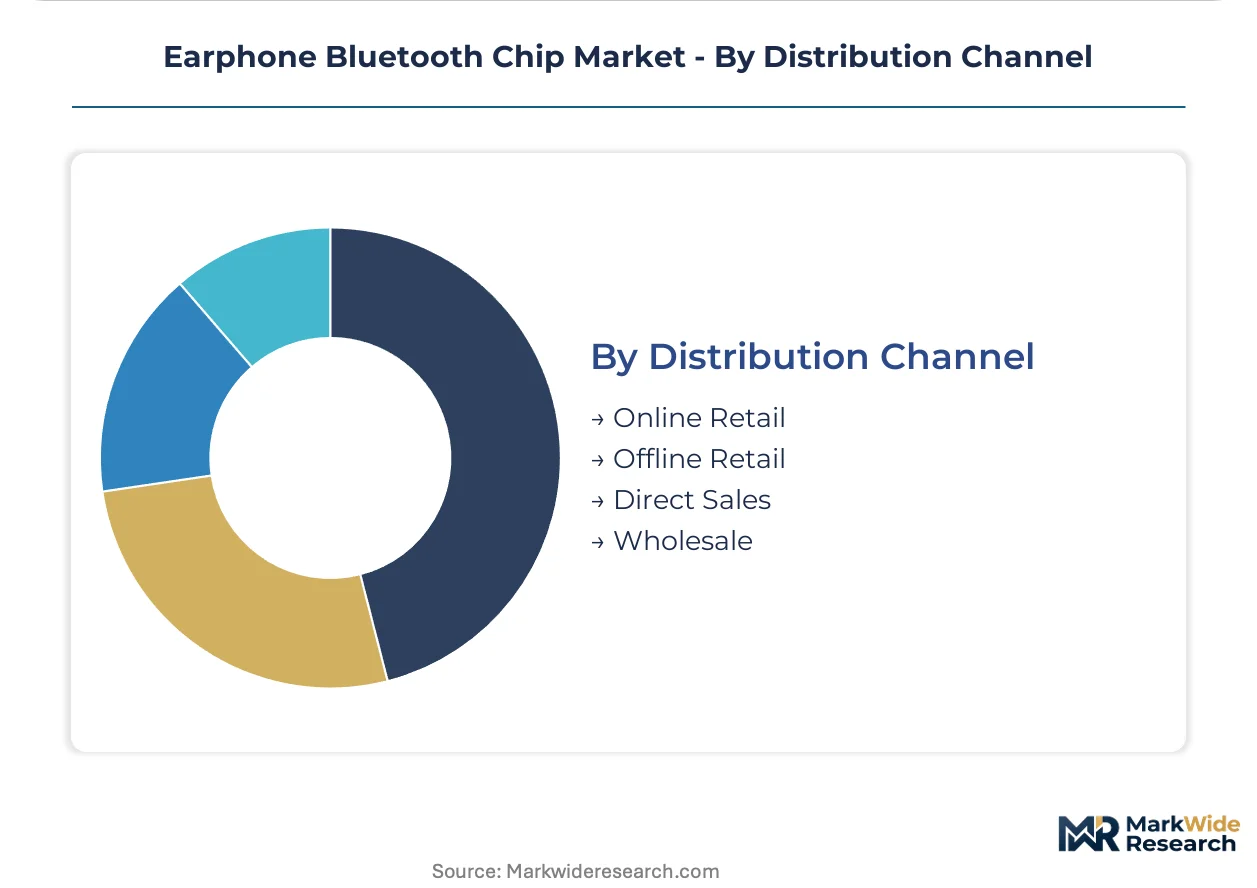
- Online Retail:Platform-native brands selling through TikTok Shop and Temu fragment procurement authority away from traditional electronics distributors, compressing qualification timelines and accelerating product refresh cycles.
- Offline Retail:Best Buy and MediaMarkt category managers still command volume for premium tier launches, though shelf-space fees are pushing chipmakers to subsidize co-marketing arrangements.
- Direct Sales:Audio-Technica and Sennheiser's owned e-commerce channels enable firmware personalization and extended warranty programs, requiring secure boot architectures and cloud connectivity stacks.
- Wholesale:B2B procurement for corporate gifting and airline amenity kits prioritizes cost minimization over feature depth, locking in multi-year supply agreements with limited silicon upgrade flexibility.
Online retail commands the dominant share of chip placements; direct sales channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics corridor concentrates Bluetooth chip procurement for Asia-Pacific assembly lines, while regulatory divergence across major economies fragments qualification requirements for new entrants.
China
MIIT transmission standards and SAMR wireless regulations are pushing Shenzhen-based ODMs toward 22nm process migrations. GB standards for wireless device interoperability are tightening testing protocols, extending certification timelines. Dongguan packaging suppliers are dual-sourcing substrate materials to preserve European market access under evolving substance restrictions.
United States
FCC Part 15 certification requirements mandate specific absorption rate thresholds for 2.4GHz transmission, directly influencing antenna design specifications. FDA's 2022 over-the-counter hearing aid classification is pulling chip architectures toward medical-grade noise cancellation. San Diego-based fabless design houses concentrate RF analog engineering talent for premium-tier implementations.
Germany
ECHA REACH substance restrictions on halogenated flame retardants are compelling solder formulation changes for European-bound chip shipments. Corporate IT procurement teams are piloting Auracast-enabled earbuds for hot-desking environments. Bavarian specialty retailers are expanding shelf space for LDAC-enabled over-ear configurations targeting audiophile segments.
South Korea
Mobile esports tournaments are specifying sub-50ms audio response thresholds, pulling premium chipset procurement toward specialized low-latency implementations. MFDS medical device regulations are creating compliance pathways for hearing aid convergence products. Seoul-based gaming peripheral manufacturers are driving aptX Adaptive specification adoption.
India
PLI scheme incentives for IT hardware are attracting contract manufacturers to Noida and Chennai assembly corridors. BIS certification requirements for wireless devices are standardizing import testing protocols. Price-sensitive consumer segments are anchoring volume demand for SBC-based neckband chip configurations.
Earphone Bluetooth Chip Market Competitive Landscape
Premium-margin players sit above commodity-margin players across codec licensing and process node sophistication, creating a tiered structure where IP portfolio depth separates recoverable R&D from margin compression. The vendor base concentrates among fabless design houses with captive foundry relationships and integrated device manufacturers with in-house fabrication. Three archetypes dominate: codec licensors commanding royalty stacks, foundry-affiliated volume producers, and cost-optimized specialists serving white-label channels. Competitive moves center on strategic IP licensing expansion and backward integration into packaging capabilities.
Among semiconductor specialists, Qualcomm Incorporated and MediaTek exemplify divergent positioning strategies, while Airoha Technology occupies a distinct tier serving cost-optimized procurement channels. Qualcomm's San Diego base and codec portfolio heritage situate it within the premium-licensor archetype, whereas MediaTek's Taiwanese origins and foundry scale align with volume-tier production. Airoha Technology represents the specialist fabricator model concentrated on white-label supply chains.
| Leading Market Players |
|---|
| Qualcomm Incorporated |
| STMicroelectronics |
| Texas Instruments Incorporated |
| Nordic Semiconductor |
| NXP Semiconductors |
| Silicon Laboratories |
| Dialog Semiconductor |
| MediaTek |
| Airoha Technology |
| Others |
Pricing and Supply Chain Analysis
22nm wafer fabrication costs cascade through three distinct pricing tiers, with TSMC and Samsung foundry rates compressing margins for mid-range true wireless platforms while Qualcomm's aptX licensing premiums sustain recoverable ASPs at the audiophile tier. Shenzhen-based ODMs absorb cost volatility through volume commitments to white-label channels, passing margin pressure downstream to entry-level neckband configurations.
Pricing Analysis
Value-based pricing anchors on codec performance throughput and latency guarantees rather than die area alone. Three-tier pricing structure across premium, standard, and economy levels separates LDAC-enabled audiophile chips from aptX Adaptive gaming variants and baseline SBC controllers. Cost compression in the economy tier is intensifying because white-label manufacturers are consolidating procurement around single-chip solutions. Corporate IT buyers in Germany and the United States show least price sensitivity for Auracast-enabled enterprise deployments, while Indian contract manufacturers driving neckband volume remain most sensitive to per-unit licensing stacks.
Supply Chain Analysis
Freight cost fluctuations between Taiwanese foundries and Dongguan packaging facilities are compressing landed costs for European-bound shipments already burdened by REACH compliance overhead. Silicon supply concentrates in Taiwan, South Korea, and the United States, with 22nm Bluetooth SoCs drawing from TSMC and Samsung wafer starts. Gallium arsenide substrates, gold wire bonding materials, and halogen-free epoxy mold compounds constitute critical input dependencies. Single-source vulnerability at TSMC's 12-inch fabs presents structural risk. Distribution runs through Shenzhen electronics corridors to Asia-Pacific assembly lines, with secondary nodes emerging at Noida and Chennai under India's PLI scheme.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with codec IP ownership and captive foundry allocation serving as the decisive levers separating recoverable R&D from commodity margin compression.
For Market Incumbents: Hedge against foundry allocation constraints by securing multi-year wafer commitments at 22nm nodes while accelerating backward integration into packaging capabilities at Dongguan facilities. Qualcomm and MediaTek must defend against emerging fabless entrants from South Korea by deepening MFi certification ecosystems that lock in Apple's AAC-optimized procurement channels.
For New Entrants and Emerging Players: Hearing aid convergence buyers represent the most penetrable white-space target, with FDA's over-the-counter classification creating procurement pathways for medical-grade noise cancellation chips. Auracast broadcast audio deployments in German corporate IT environments offer a second entry vector. Pursue direct-to-consumer channel partnerships with TikTok Shop-native brands to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: FDA 510(k) clearance timelines for OTC hearing aid chip submissions are the leading indicator that medical-grade audio architectures will command sustained premium multiples. Long-term viability favors vertically integrated specialists with captive RF analog design talent in San Diego or Taipei. Monitor ECHA SVHC list expansions as the signal for packaging material qualification costs that could reshape competitive economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Packaging | Dongguan substrate qualification preserves EU market access under REACH substance restrictions. |
| Codec IP Licensing Expansion | Sony's royalty-free LDAC proliferation expands addressable market for high-resolution audio silicon. |
| Medical-Grade Certification Pathway | FDA OTC hearing aid classification pulls chip architectures toward prescription-tunable frequency response. |
| Foundry Capacity Commitment | Multi-year 22nm wafer agreements at TSMC secure supply for low-latency gaming implementations. |
| Direct-to-Consumer Channel Partnership | TikTok Shop-native audio brands fragment procurement authority away from MediaMarkt category managers. |
Research Methodology
Document review covered SEC semiconductor filings, MIIT wireless transmission standards, and ECHA REACH substance restriction updates, complemented by interviews with Bluetooth chip design engineers, Shenzhen-based ODM procurement directors, and corporate IT audio equipment buyers. Secondary validation drew from FCC Part 15 certification databases, GB standards interoperability protocols, and foundry capacity utilization disclosures. Bottom-up die shipment estimates were triangulated against top-down OEM bill-of-materials analysis across the analysis window.
Historical volume trajectories were cross-referenced against panel input from fabless design house executives and foundry account managers. The analytical framework modeled product type segmentation, codec technology tiers, end-user archetypes, and regional regulatory clusters throughout the forecast period. CAGRs were derived from regression analysis of die area trends, process node migration rates, and licensing fee structures. Industry-specific forecast inputs included Auracast deployment timelines and hearing aid convergence regulatory pathways.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to foundry capacity allocation decisions, ECHA SVHC list expansions, and MIIT transmission standard revisions. Forecasts reflect documented assumptions about codec adoption curves and OEM platform refresh cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market