
 Semiconductors for Wireless Communications Market | 2026-2036
Semiconductors for Wireless Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductors for Wireless Communications Market Analytics
FCC spectrum reallocation is decoupling legacy RF designs from new certification pathways, forcing vendors to rebuild front-end modules around mmWave and CBRS bands. Qualcomm Technologies Inc. leverages its modem-RF integration to anchor premium smartphone sockets, while Broadcom sustains dominance in Wi-Fi 6E and 7 chipset platforms through vertical control over FBAR filter supply. Samsung Electronics Co., Ltd. competes by manufacturing both foundry capacity and end-device demand, creating captive pull for its RF solutions.
Semiconductors for wireless communications are integrated circuits engineered to transmit, receive, and process electromagnetic signals across licensed and unlicensed spectrum, typically fabricated on GaN, SiGe, CMOS, or SOI processes with operating frequencies spanning sub-1 GHz to 100 GHz. These devices enable cellular basebands, Wi-Fi connectivity, Bluetooth links, and satellite communications by converting digital data to analog waveforms and vice versa through mixer, amplifier, and filter stages. RF amplifiers built on GaN technology command premium positioning due to power efficiency advantages at millimeter-wave frequencies, while CMOS-based Bluetooth chips serve high-volume, cost-constrained IoT deployments where silicon economics dominate margin structures. Power management ICs for wireless infrastructure represent a maturing profit pool as 5G macro cell deployments slow, though demand from small cell densification and private networks offsets this deceleration.
The FCC governs spectrum access and device certification in the United States, directly constraining which frequency bands and power levels manufacturers can target. ETSI and national regulators across Europe enforce CE marking and RED compliance for wireless equipment, creating divergent testing burdens for multi-region product strategies. China's MIIT and GB standards mandate domestic encryption and spectrum protocols, fragmenting design requirements for vendors serving both export and local markets. Stakeholders must monitor spectrum auction schedules and localization mandates to time R&D bets and regional manufacturing commitments.
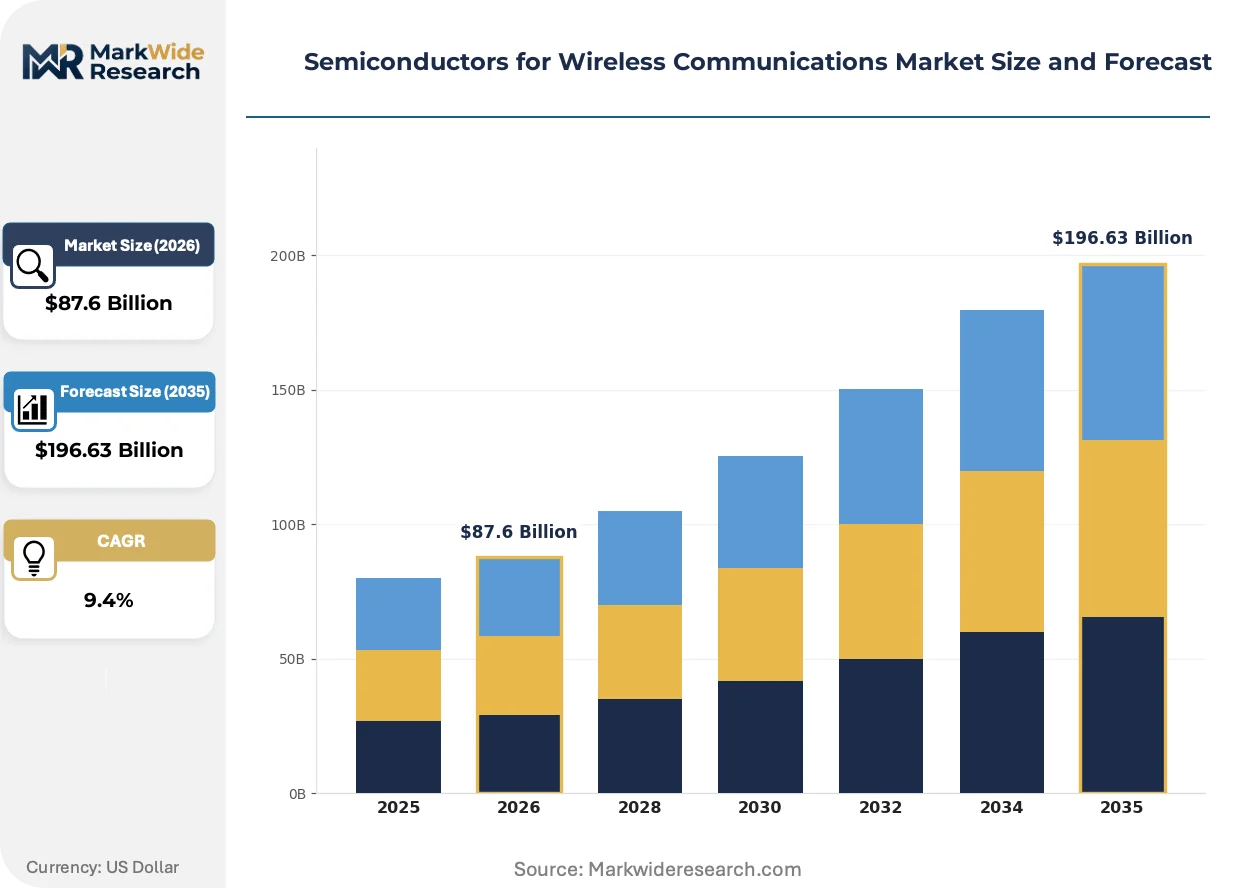
Market Dynamics
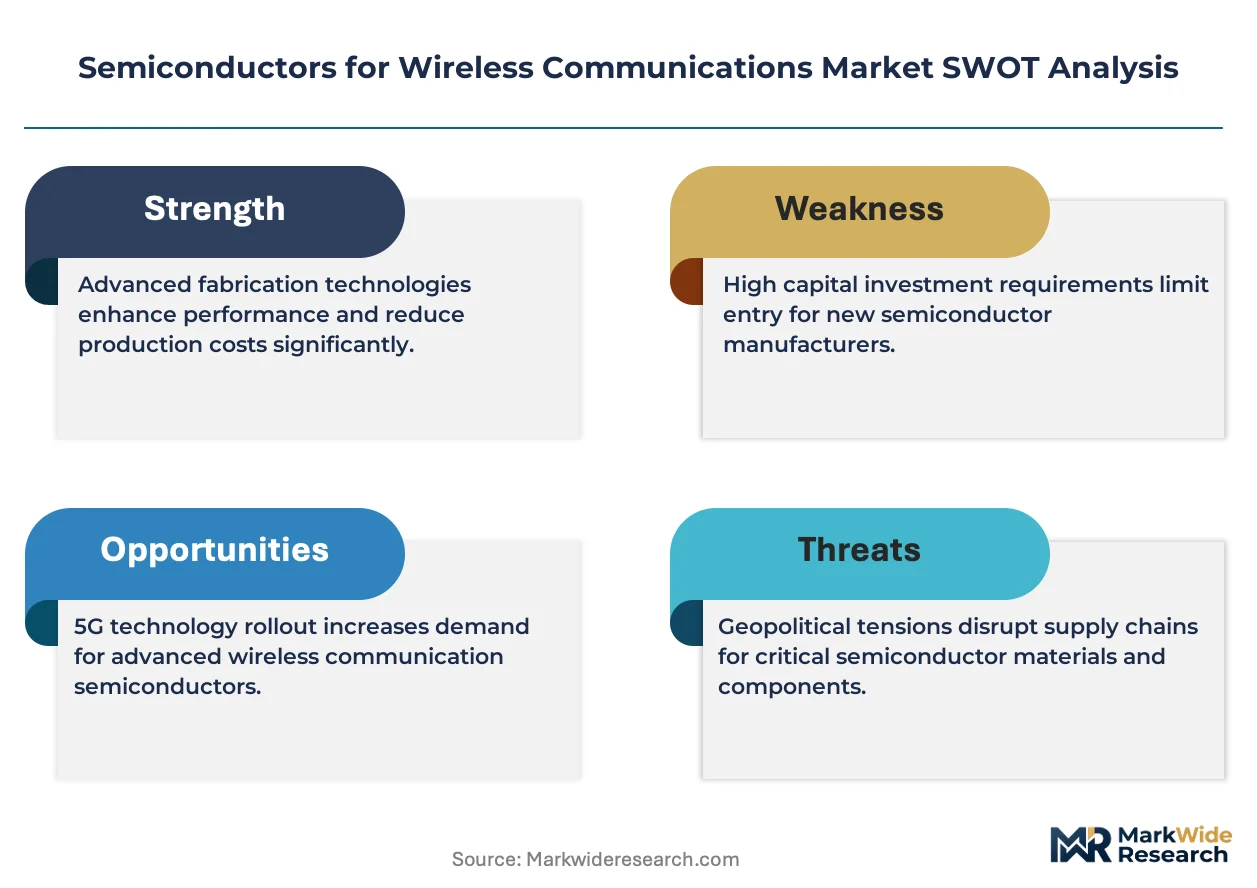
5G base station rollouts are compressing design cycles for RF front-end architectures as operators demand simultaneous coverage across sub-6 GHz and mmWave bands. This spectrum bifurcation is forcing semiconductor vendors to requalify processes and retool manufacturing lines at unprecedented velocity.
Growth Catalysts
- China's MIIT spectrum mandates:Domestic 5G infrastructure buildouts under GB standards are pulling GaN-on-SiC power amplifiers into macro cell deployments, creating captive demand for foundry capacity.
- Private 5G networks:Manufacturing campuses and logistics hubs are deploying dedicated small cells, expanding addressable silicon volumes beyond traditional carrier procurement.
- GaN process maturation:Epitaxial yield improvements are lowering cost trajectories for millimeter-wave power amplifiers, displacing legacy LDMOS in base station transmit chains.
Market Restraints
- Substrate supply concentration:Silicon carbide wafers for GaN epitaxy concentrate among Japanese and US suppliers, exposing RF device makers to allocation risk during demand surges.
- FCC certification timelines:mmWave device approvals face extended electromagnetic compatibility testing, delaying revenue recognition for new front-end module launches.
- Silicon germanium substitution:SiGe BiCMOS processes for sub-6 GHz beamforming are ceding socket share to CMOS SOI alternatives with superior integration density.
Strategic Opportunities
- India's PLI scheme for telecom equipment:Local assembly incentives are attracting RF module vendors to establish packaging and test operations near emerging 5G subscriber bases.
- Satellite-to-cell convergence:Direct-to-device satellite links are merging with terrestrial modem architectures, opening new silicon content per handset.
- Open RAN disaggregation:Interface standardization is decoupling RF hardware from baseband software, enabling merchant silicon penetration into previously integrated vendor stacks.
Industry Challenges
- Electromagnetic simulation talent scarcity:mmWave antenna-in-package design requires specialized computational electromagnetics expertise that outpaces university pipeline output.
- Multi-band coexistence certification:Simultaneous Wi-Fi 7 and 5G operation demands complex desense testing that stretches validation schedules and capitalizes test floor capacity.
- Legacy 4G inventory absorption:Carrier warehouse stockpiles of first-generation massive MIMO radios are depressing near-term procurement for next-generation silicon upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductors for Wireless Communications Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, RF Amplifiers, Power Management ICs, Bluetooth Chips Technology: GaN, SiGe, CMOS, SOI End User: Telecommunications, Consumer Electronics, Automotive, Industrial Automation Application: Mobile Devices, IoT Devices, Wireless Infrastructure, Smart Home Solutions |
| Companies Covered | Intel Corporation, Marvell Technology Group Ltd., Qualcomm Technologies Inc., STMicroelectronics NV, Texas Instruments Incorporated, Broadcom, NXP Semiconductors, Samsung Electronics Co., Ltd., MediaTek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductors for Wireless Communications Market Evolving Landscape
Antenna-in-package integration is collapsing the boundary between semiconductor and subsystem design, compelling foundries to offer co-design services alongside wafer fabrication. This convergence is redrawing competitive boundaries across the RF supply chain.
Gallium nitride-on-silicon carbide is rewriting power amplifier economics for 5G massive MIMO deployments. Base station OEMs are adopting GaN Doherty architectures for macro cells to meet efficiency targets. The technology is compressing thermal management overhead and enabling denser radio configurations per tower.
The FCC's 3.45 GHz auction and subsequent band reallocation are forcing front-end module redesigns for CBRS and C-band coexistence. Device manufacturers must retest spurious emissions profiles across expanded operating envelopes. Handset RF suppliers serving the US market are absorbing the highest compliance burden from these mid-band additions.
Carrier procurement consolidation is compressing supplier negotiation leverage as tier-one operators bundle RF, baseband, and antenna contracts into single-source awards. Tier-two module vendors are responding through design partnerships with captive foundry operations. This pattern is most pronounced in North American and Chinese carrier supply bases where procurement centralization has advanced furthest.
Semiconductors for Wireless Communications Market Segmentation
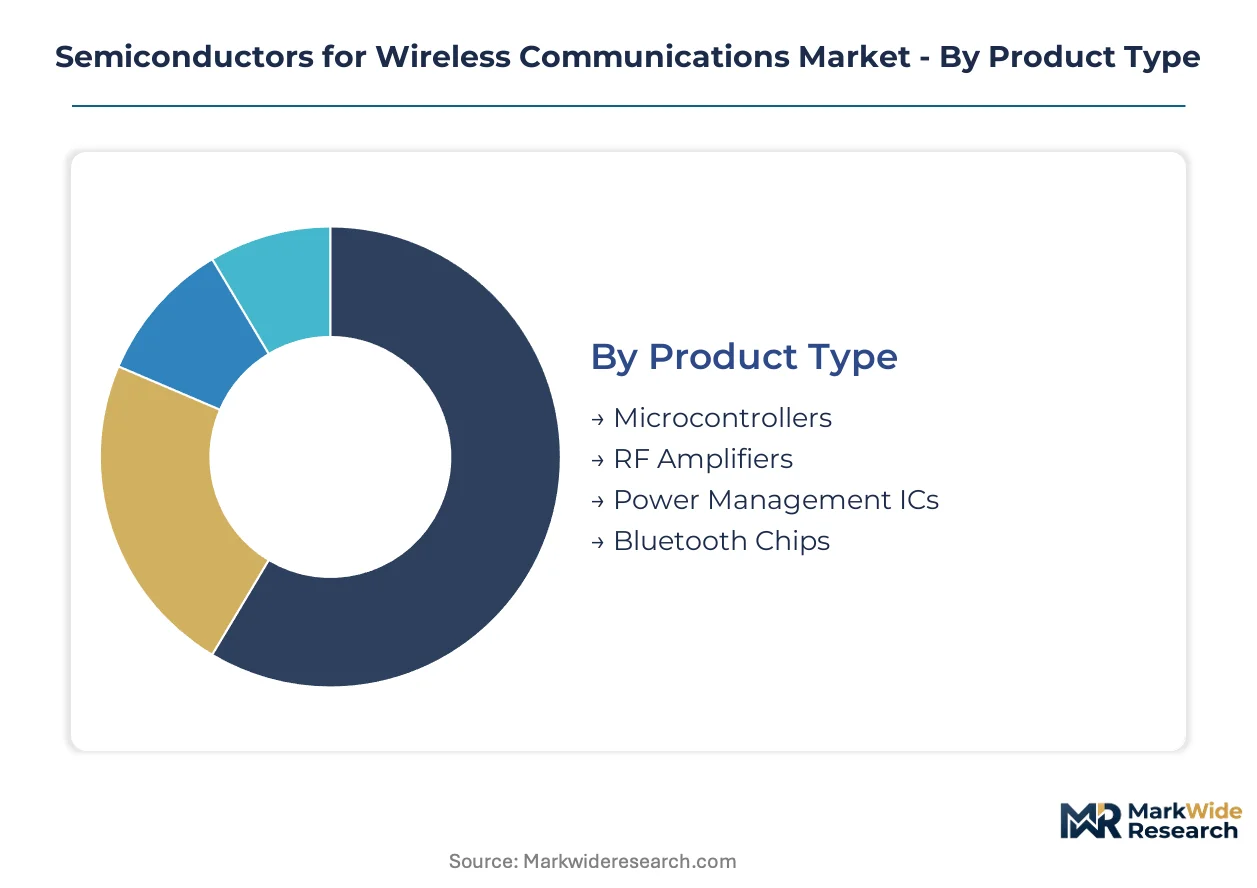
Semiconductor architectures for wireless communications fragment across four critical dimensions: product function, fabrication process, customer vertical, and deployment context. Each segmentation layer carries distinct margin profiles and capital requirements that reshape vendor positioning.
Product Type:
Capital intensity peaks with RF amplifiers requiring specialized epitaxial growth and thermal management infrastructure, while Bluetooth chips leverage depreciated CMOS lines.
- Microcontrollers:Integrated processing cores with embedded wireless protocol stacks manage signal modulation and packet processing at the edge. Automotive telematics modules in Germany and Japan are pulling automotive-grade MCUs with ASIL-D safety certifications, though foundry allocation for automotive variants stretches lead times.
- RF Amplifiers:Power amplification stages fabricated on GaN or LDMOS processes deliver watt-level output for base station transmit chains. China's MIIT-mandated 5G densification is absorbing GaN-on-SiC capacity for macro cell deployments, creating foundry bottlenecks during spectrum auction windows.
- Power Management ICs:Voltage regulation and battery charging circuits optimize energy delivery across wireless subsystems.
- Bluetooth Chips:Short-range radio transceivers on mature CMOS nodes enable low-cost connectivity for peripheral devices.
RF amplifiers absorb the bulk of installed capacity; Bluetooth chips are expanding most quickly.
Technology:
Process selection dictates which frequency bands and power levels a semiconductor can address, with GaN commanding premium positioning for infrastructure applications.
- GaN:Wide-bandgap compound semiconductors on silicon carbide substrates achieve breakthrough efficiency at millimeter-wave frequencies. US carrier C-band deployments are qualifying GaN Doherty amplifiers for massive MIMO radios, displacing legacy LDMOS in high-power transmit paths.
- SiGe:Silicon germanium BiCMOS processes merge bipolar performance with CMOS integration density for sub-6 GHz beamforming. South Korea's 5G base station OEMs are transitioning SiGe mmWave transceivers to CMOS SOI alternatives, eroding process share in handset applications.
- CMOS:Standard silicon logic processes enable cost-optimized radio integration for high-volume consumer markets.
- SOI:Silicon-on-insulator substrates reduce parasitic capacitance for switch and low-noise amplifier integration.
CMOS dominates wafer starts by volume; GaN claims the steepest expansion trajectory.
End User:
Customer concentration varies sharply, with telecommunications carriers consolidating procurement power while industrial automation spreads demand across fragmented equipment vendors.
- Telecommunications:Carrier and enterprise network operators specify RF front-end performance for macro cells, small cells, and private networks. India's TRAI spectrum auctions are accelerating 5G base station procurement, pulling GaN power amplifiers and massive MIMO digital beamforming chips into deployment pipelines.
- Consumer Electronics:Smartphone, tablet, and wearable OEMs integrate multi-band cellular, Wi-Fi, and Bluetooth connectivity. Japan's handset manufacturers are absorbing premium RF front-end modules with antenna-tuner integration to support sub-6 GHz and mmWave coexistence.
- Automotive:Connected vehicle platforms require V2X communication chipsets with functional safety certification.
- Industrial Automation:Factory wireless and asset tracking systems deploy private 5G and LPWAN connectivity.
Telecommunications commands the largest absolute silicon spend; industrial automation is climbing the fastest.
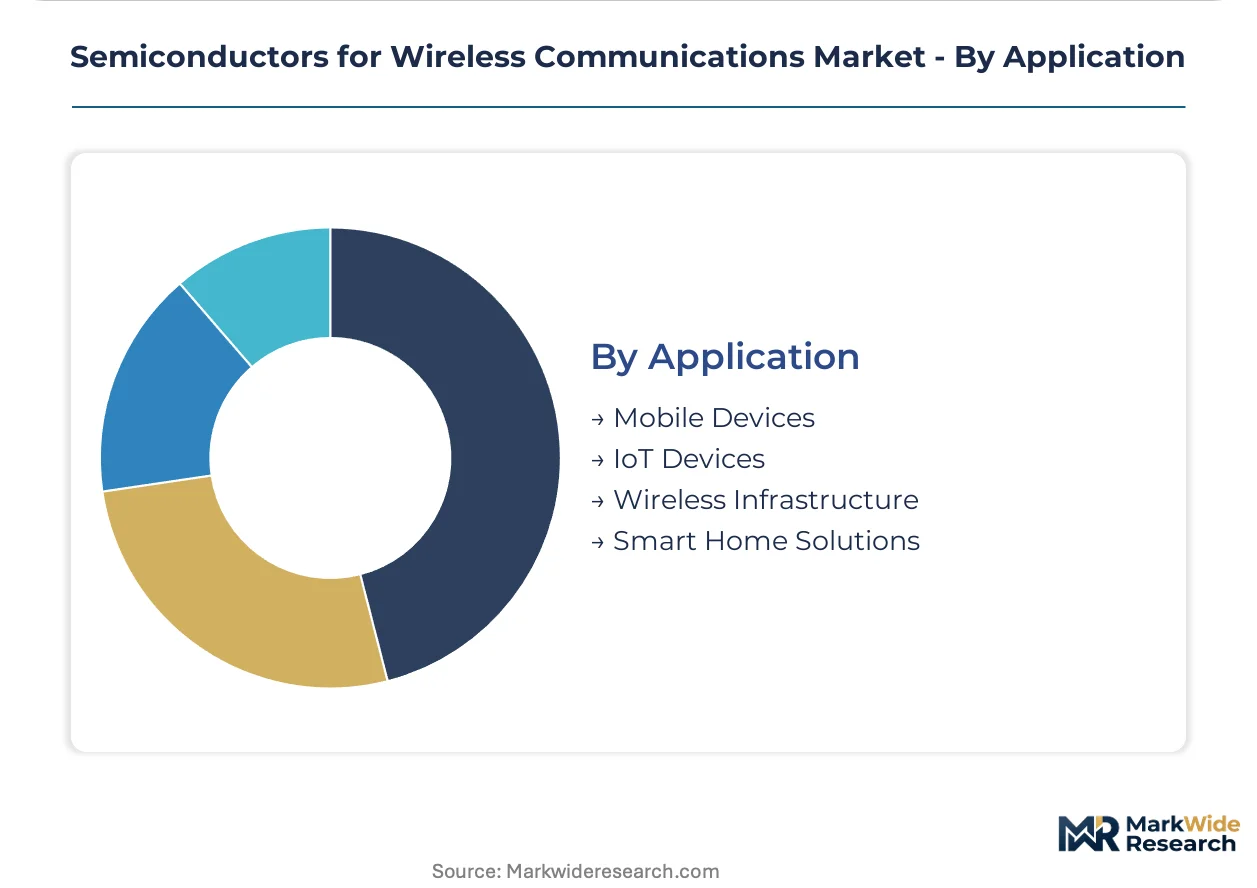
Application:
Deployment context determines thermal constraints, form factor limits, and regulatory certification pathways that cascade back to semiconductor specification.
- Mobile Devices:Handset and tablet platforms demand highly integrated modem-RF systems with aggressive power budgets. Qualcomm's modem-RF platforms anchor premium smartphone sockets in the United States and South Korea, while MediaTek competes on cost-optimized sub-6 GHz-only variants for emerging markets.
- IoT Devices:Sensor networks and asset trackers prioritize sub-gigahertz and 2.4 GHz connectivity with decade-long battery life. China's smart metering mandates are pulling LPWAN chipsets into utility deployments, creating volume anchors for domestic semiconductor vendors.
- Wireless Infrastructure:Base station and access point platforms require high-linearity amplification and massive MIMO digital processing.
- Smart Home Solutions:Residential gateways and connected appliances integrate Wi-Fi 6E/7 and Thread mesh protocols.
Wireless infrastructure captures the majority of RF amplifier demand; IoT devices are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates demand through its national 5G infrastructure buildout and domestic chip self-sufficiency programs, while the United States and South Korea anchor premium smartphone RF module consumption. Regulatory fragmentation across spectrum allocation and certification timelines shapes regional competitive positioning.
China
MIIT-mandated 5G densification and GB standards compliance pull GaN-on-SiC power amplifiers into macro cell deployments. The national semiconductor self-sufficiency program redirects procurement toward domestic foundry capacity. Yangtze River Delta clusters in Shanghai and Suzhou concentrate RF front-end packaging and test operations serving both export and captive demand.
United States
FCC spectrum reallocation mandates for mmWave and CBRS bands compel front-end module redesigns for C-band coexistence. Extended electromagnetic compatibility testing timelines delay revenue recognition for new device launches. Austin and Boston metropolitan areas host RF design centers specializing in antenna-in-package integration for sub-6 GHz and mmWave coexistence.
South Korea
Base station OEMs transition SiGe mmWave transceivers to CMOS SOI alternatives, eroding legacy process share in handset applications. National 5G spectrum auctions accelerate procurement cycles for massive MIMO digital beamforming chips. Seoul Capital Area fabs concentrate advanced SOI wafer production for switch and low-noise amplifier integration.
Japan
Handset manufacturers absorb premium RF front-end modules with antenna-tuner integration to support multi-band cellular and Wi-Fi 7 coexistence. METI industrial policy supports domestic GaN epitaxial capacity expansion for base station applications. Kyushu-based compound semiconductor clusters supply silicon carbide substrates for GaN RF device fabrication.
Germany
Automotive telematics modules pull automotive-grade MCUs with ASIL-D safety certifications, stretching foundry allocation for automotive variants. ETSI and national regulators enforce CE marking and RED compliance, creating testing burdens for multi-region product strategies. Bavaria's semiconductor corridor hosts RF design houses serving industrial automation and connected vehicle platforms.
Semiconductors for Wireless Communications Market Competitive Landscape
United States producers anchor the premium modem-RF integration tier; South Korean and Taiwanese specialists hold foundry and packaging capacity positions. The vendor base stratifies across three tiers: integrated platform vendors controlling modem-to-antenna stacks, discrete component specialists dominating filter and amplifier niches, and captive semiconductor divisions serving parent equipment manufacturers. Strategic moves concentrate on spectrum band expansion through process requalification and antenna-in-package co-design service offerings.
Within the integrated platform tier, Qualcomm Technologies Inc. and Broadcom exemplify the modem-RF convergence archetype, while Samsung Electronics Co., Ltd. occupies a position spanning captive foundry capacity and end-device demand pull. Texas Instruments Incorporated and STMicroelectronics NV sit within the broad-based analog and mixed-signal supplier category, serving industrial and automotive wireless connectivity sockets alongside consumer applications. These five entities collectively represent the competitive spectrum from premium smartphone RF front-ends to cost-optimized IoT Bluetooth implementations.
| Leading Market Players |
|---|
| Intel Corporation |
| Marvell Technology Group Ltd. |
| Qualcomm Technologies Inc. |
| STMicroelectronics NV |
| Texas Instruments Incorporated |
| Broadcom |
| NXP Semiconductors |
| Samsung Electronics Co., Ltd. |
| MediaTek Inc. |
| Others |
Value Network & Pricing Analysis
GaN-on-SiC process maturation is compressing cost curves for millimeter-wave power amplifiers while simultaneously concentrating foundry ownership among Japanese and US substrate suppliers. This dual compression of manufacturing economics and raw material access is reshaping how RF device vendors negotiate long-term supply agreements and price their front-end modules.
Pricing Analysis
Volume-margin splits separate commodity Bluetooth chips on depreciated CMOS nodes from premium GaN power amplifiers commanding foundry premiums. Pricing stratifies across certification tiers, with FCC Part 30 mmWave modules absorbing extended electromagnetic compatibility testing costs that sub-6 GHz alternatives avoid. Cost compression in the Bluetooth tier is intensifying as MediaTek and domestic Chinese vendors drive silicon economics toward marginal cost. Telecommunications carriers exhibit the lowest price sensitivity due to procurement consolidation, while IoT device makers face acute margin pressure from decade-long battery life requirements.
Supply Chain Analysis
Qualification gating through MIIT GB standards and FCC Part 30 certification fragments supplier pools and extends design-in cycles for new entrants. Silicon carbide substrate supply concentrates among Japanese and US vendors, while GaN epitaxial growth and RF front-end module assembly cluster in China and Taiwan. The supply chain draws from silicon carbide wafers, gallium nitride epitaxial layers, and advanced organic substrates for antenna-in-package integration. Single-source vulnerability in silicon carbide substrate allocation exposes RF device makers to allocation risk during spectrum auction windows. Distribution runs through direct carrier procurement contracts and tier-one handset OEM supplier programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where GaN-on-SiC power amplifiers are displacing legacy LDMOS in 5G massive MIMO transmit chains, rewriting procurement specifications and foundry capacity allocation.
For Market Incumbents: Deepen backward integration into silicon carbide substrate supply through long-term offtake agreements with Japanese suppliers, insulating against allocation risk during China's MIIT-mandated 5G densification waves. Anchor certification investment in FCC Part 30 and CE marking RED compliance to defend socket position against emerging CMOS SOI substitutes in sub-6 GHz beamforming. For New Entrants and Emerging Players: Launch via private 5G network system integrator channels, bypassing carrier procurement consolidation that favors incumbent platform vendors. Target India's PLI scheme for telecom equipment assembly, where local packaging and test operations attract RF module vendors near emerging 5G subscriber bases. Position on Open RAN disaggregation interfaces that decouple RF hardware from baseband software. For Investors and Strategic Acquirers: Re-rating potential sits with antenna-in-package co-design specialists given carrier procurement bundling of RF, baseband, and antenna contracts into single-source awards. Long-term viability over the next decade hinges on spectrum band expansion capabilities and foundry partnership depth. Watch FCC spectrum auction schedules as the inflection signal for demand surge timing and qualification gating intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Antenna-in-Package Co-Design Service Launch | Foundries offering co-design services alongside wafer fabrication capture RF front-end module redesign cycles triggered by FCC spectrum reallocation. |
| GaN-on-SiC Foundry Capacity Expansion | Capacity additions in Taiwan and China address MIIT-mandated 5G densification demand while compressing cost trajectories for millimeter-wave power amplifiers. |
| Open RAN Interface Certification Investment | Interface standardization enables merchant silicon penetration into previously integrated vendor stacks at tier-one carriers. |
| Satellite-to-Cell Modem Architecture Integration | Direct-to-device satellite links merging with terrestrial modem architectures open new silicon content per handset for premium smartphone sockets. |
| India PLI Scheme Manufacturing Footprint | Local assembly incentives attract RF module packaging and test operations near emerging 5G subscriber bases in the world's fastest-growing telecommunications market. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with RF design engineers, carrier procurement directors, foundry operations managers, and base station OEM platform architects. FCC equipment authorization databases, MIIT GB standard publications, ETSI RED compliance registries, and semiconductor trade flow records provided demand-side validation. Bottom-up unit economics for GaN power amplifiers and CMOS Bluetooth chips were triangulated against top-down carrier capex and handset bill-of-materials estimates.
Data-stream reconciliation across foundry utilization reports, spectrum auction timelines, and carrier procurement contract awards informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product function, fabrication process, customer vertical, and deployment context, with additional granularity on spectrum band certification tiers. CAGRs were derived from fitted adoption curves for 5G base station deployment phases and GaN process yield improvement trajectories. Forecast inputs incorporated MIIT infrastructure buildout schedules and FCC reallocation mandates.
Spectrum auction delays, GaN epitaxial yield shortfalls, and silicon carbide substrate supply disruptions are the dominant revision risks that could compress or extend the projected expansion trajectory. Forecasts reflect assumptions regarding carrier procurement consolidation patterns and foundry capacity allocation priorities. A model refresh is warranted upon material change in FCC or MIIT spectrum policy timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
Wi-Fi Semiconductor Chipset Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Chip Antenna Market