
 Wireless Mesh Networking Market | 2026-2036
Wireless Mesh Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Mesh Networking Market Analytics
China's manufacturing corridor for wireless infrastructure is fragmenting as domestic capacity expands beyond state-contracted volumes. Cisco Systems leverages its enterprise routing heritage to anchor premium indoor deployments across North American campuses. Rajant Corporation specializes in kinetic mesh protocols for military and mining applications where mobility tolerance exceeds conventional standards. Qualcomm Technologies dominates baseband silicon supply for mesh radio modules, extending its position into Wi-Fi 7 chipsets.
Wireless mesh networking deploys self-healing radio nodes that automatically reroute traffic across multiple hops using protocols such as IEEE 802.11s or proprietary extensions, eliminating single points of failure in distributed environments. The architecture serves critical functions in industrial automation, public safety communications, and large-scale sensor grids where cabled backhaul proves impractical or cost-prohibitive. Outdoor deployments command structural priority due to utility smart grid mandates and municipal broadband obligations, while hybrid models gain traction in campus environments blending fixed and mobile node requirements. IoT connectivity applications absorb the fastest expansion as agricultural, logistics, and environmental monitoring networks proliferate, though surveillance retains margin concentration through encrypted, low-latency specification tiers.
FCC Part 15 rules govern unlicensed spectrum allocation for mesh deployments in the United States, directly shaping product certification timelines and radio power constraints. The EU Radio Equipment Directive and ETSI EN 300 328 standards enforce coexistence protocols and spectrum efficiency thresholds for European market entry. Stakeholders must monitor evolving national spectrum auctions and cybersecurity labeling mandates that will determine which hardware architectures achieve regulatory clearance without costly redesign cycles.
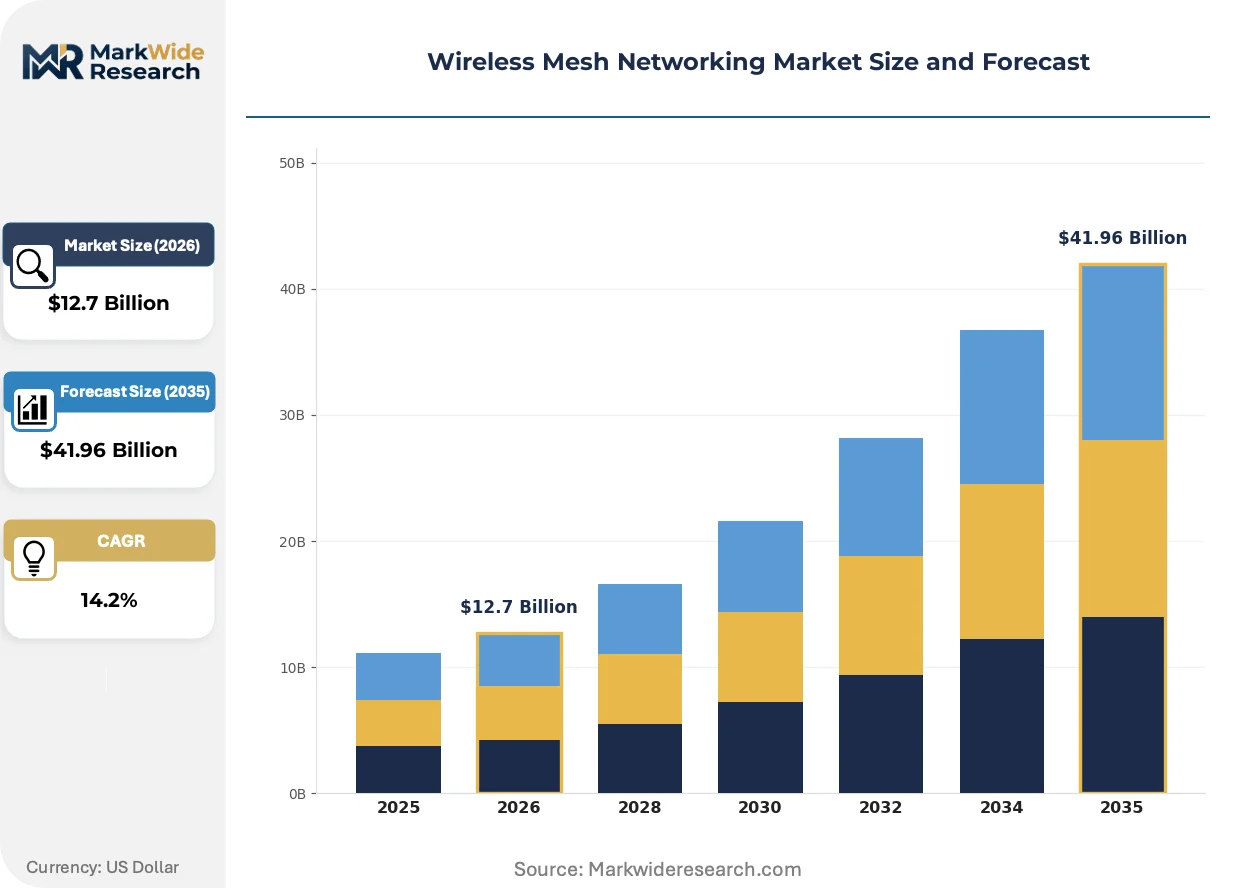
Market Dynamics
Utility smart grid mandates across Germany, Japan, and Australia are forcing infrastructure capital toward outdoor mesh architectures, while IEEE 802.11ax certification requirements compress product development cycles for equipment vendors.
Growth Catalysts
- FCC Part 15 unlicensed spectrum rules:The United States regulatory framework enables rapid deployment without auction costs, accelerating municipal broadband and industrial IoT networks.
- Wi-SUN Alliance interoperability certifications:Standardized protocol stacks reduce integration friction for utility-scale smart metering and distribution automation systems.
- Smart city infrastructure clusters:Barcelona and Singapore demonstrate operational models for sensor-dense urban environments, creating reference architectures for replication.
Market Restraints
- Baseband silicon supply concentration:Qualcomm's dominance in mesh radio module chipsets creates single-source dependency risks for tier-two equipment vendors.
- ETSI EN 300 328 coexistence thresholds:European spectrum efficiency requirements extend certification timelines and raise engineering costs for multi-band products.
- Licensed cellular alternatives:Private 5G networks and NB-IoT carrier offerings compete for the same utility and industrial connectivity budgets.
Strategic Opportunities
- Agricultural sensor networks:Brazil and Australia's farming corridors remain underpenetrated for precision irrigation and livestock monitoring applications.
- EU cybersecurity labeling mandates:Early compliance with emerging hardware security certification requirements opens preferential procurement channels for European utilities.
- Wi-Fi 7 and kinetic mesh convergence:Integration of high-throughput indoor standards with mobility-tolerant outdoor protocols enables unified campus-industrial deployments.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in multi-hop routing optimization and antenna design concentrates at legacy military contractors and select semiconductor firms.
- Legacy SCADA integration complexity:Brownfield industrial sites require protocol translation layers that degrade latency performance and expand system vulnerability surfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Mesh Networking Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $41.96 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Indoor, Outdoor, Hybrid, Remote Application Type: Smart Cities, IoT Connectivity, Disaster Management, Surveillance End User: Telecom, Utilities, BFSI, Education Technology: Wi-Fi, LoRa, Zigbee, Bluetooth |
| Companies Covered | Motorola Solutions, Rajant Corporation, Cisco Systems, Fluidmesh Networks, Ruckus Networks, Hewlett Packard Enterprise, Cambium Networks, Qualcomm Technologies, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Mesh Networking Market Evolving Landscape
Mesh networking architectures are bifurcating between static infrastructure-grade deployments and mobility-optimized kinetic configurations, with protocol choices increasingly determined by end-use latency tolerance rather than hardware cost.
Wi-Fi 7 chipsets with 320 MHz channel bonding and 4K-QAM modulation are rendering obsolete prior-generation equipment in campus and stadium environments. North American universities and corporate headquarters are piloting these deployments to support augmented reality maintenance applications. The technology is compressing refresh cycles from seven-year infrastructure norms toward four-year consumer-electronics pacing.
EU Radio Equipment Directive enforcement is tightening electromagnetic compatibility documentation requirements for mesh nodes operating in shared 2.4 GHz and 5 GHz bands. Manufacturers must now submit comprehensive coexistence testing protocols before CE marking approval. German industrial automation buyers are prioritizing vendors with pre-certified module portfolios to avoid deployment delays.
Buying committees at municipal utilities are consolidating vendor relationships from multi-source best-of-breed approaches toward single-source system integrators with cybersecurity liability coverage. Channel partners with embedded security operations capabilities are displacing pure hardware distributors. This pattern is most pronounced in Australia's critical infrastructure sectors following federal guidance on supply chain risk management.
Wireless Mesh Networking Market Segmentation
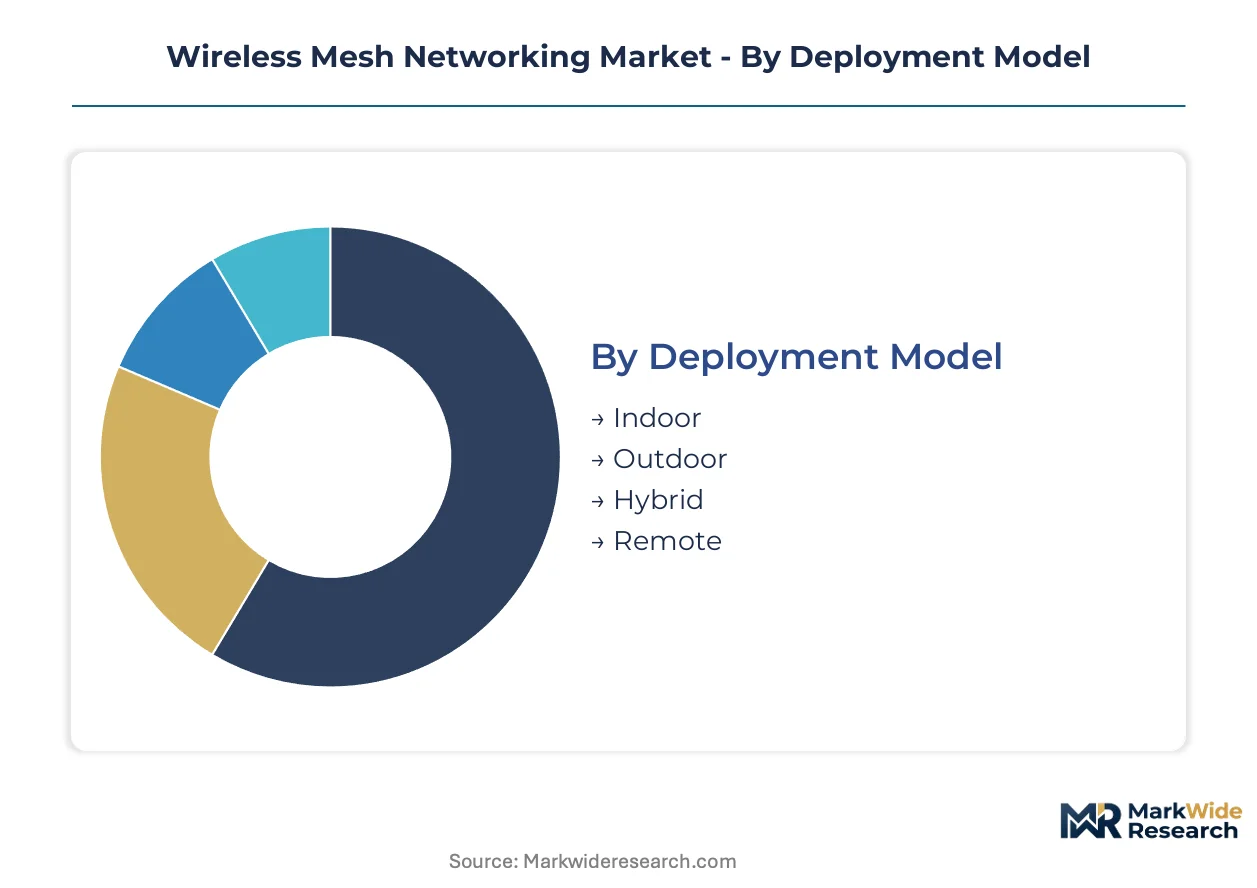
Wireless mesh networking deployments demand differentiated support architectures across deployment models, with outdoor infrastructure requiring predictive maintenance contracts and indoor campus networks prioritizing rapid swap-out logistics. Segmentation reveals how hardware specifications, spectrum licensing costs, and integration complexity fragment procurement patterns across end-use verticals.
Deployment Model:
After-sales service intensity varies dramatically by deployment environment, with outdoor nodes demanding multi-year field maintenance contracts and remote installations requiring satellite-linked diagnostic capabilities.
- Outdoor:Weather-hardened enclosures with IP67 ratings and extended temperature tolerances serve utility smart grid mandates across Germany and Australia. German distribution network operators specify 15-year operational lifespans with on-site technician dispatch guarantees.
- Indoor:Enterprise-grade access points with centralized cloud management dominate North American university and corporate campus rollouts. Cisco Systems anchors premium deployments leveraging existing routing infrastructure for seamless handoff.
- Hybrid:Blends fixed infrastructure with mobile node support for logistics yards and mining operations.
- Remote:Solar-powered nodes with satellite backhaul serve agricultural monitoring in Australia's pastoral zones.
By volume, Indoor leads. By growth pace, Outdoor is ahead.
Application Type:
Application segmentation tracks budget authority shifts from municipal IT departments toward operational technology teams with distinct procurement cycles and cybersecurity requirements.
- Smart Cities:Sensor-dense urban architectures in Barcelona and Singapore demonstrate operational models for traffic management, air quality monitoring, and public lighting control. Barcelona's deployment spans 22,000 nodes with unified citywide management platforms.
- IoT Connectivity:Agricultural sensor grids and livestock tracking networks absorb the fastest expansion as Brazil's farming corridors adopt precision irrigation. These deployments prioritize ultra-low power consumption over throughput.
- Disaster Management:Rapid-deploy kits for emergency responder communications in earthquake-prone Japanese prefectures.
- Surveillance:Encrypted, low-latency specification tiers for critical infrastructure perimeter monitoring retain margin concentration despite smaller volumes.
Smart Cities commands the largest installed base. IoT Connectivity shows the steepest expansion trajectory.
End User:
End user segmentation reflects divergent regulatory compliance burdens, with utilities facing critical infrastructure cybersecurity mandates and BFSI sectors prioritizing encrypted, audit-ready network logs.
- Utilities:Smart metering and distribution automation drive standardization around Wi-SUN Alliance protocols. Australia's federal supply chain risk management guidance is consolidating vendor relationships toward single-source integrators with liability coverage.
- Telecom:Municipal broadband obligations and rural coverage mandates in the United States leverage FCC Part 15 unlicensed spectrum rules for rapid deployment without auction costs.
- BFSI:Branch connectivity with failover resilience requirements and transaction-level encryption standards.
- Education:Campus-wide coverage for hybrid learning models with high-density classroom support.
Utilities dominates capital deployment. Telecom shows the most rapid contract acceleration.
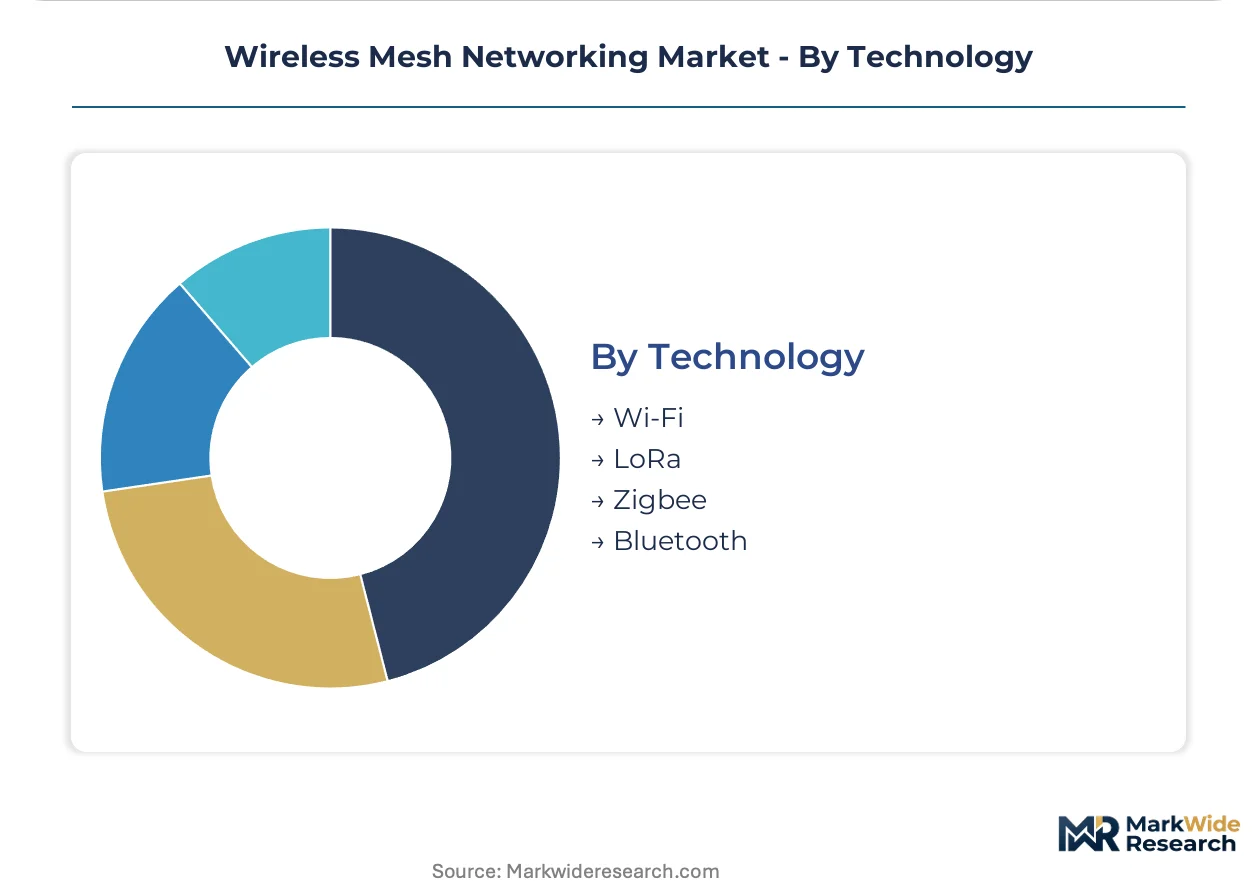
Technology:
Technology choice increasingly correlates with latency tolerance and mobility requirements rather than hardware cost, with protocol fragmentation creating integration complexity for multi-vendor environments.
- Wi-Fi:IEEE 802.11ax certification requirements compress product development cycles, while Wi-Fi 7 chipsets with 320 MHz channel bonding are rendering prior-generation equipment obsolete in stadium and campus environments. Qualcomm Technologies dominates baseband silicon supply.
- LoRa:Unlicensed sub-GHz spectrum enables long-range, low-power sensor networks for agricultural and environmental monitoring with minimal infrastructure.
- Zigbee:Mesh-native protocol stacks for residential and light commercial automation with proven interoperability.
- Bluetooth:Short-range personal area networks with mesh extensions for asset tracking and indoor positioning.
Wi-Fi holds the broadest addressable market. LoRa is expanding most quickly in greenfield sensor deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes unlicensed spectrum agility for municipal broadband, while Germany mandates decade-plus operational lifespans for utility infrastructure. Japan and Australia emphasize disaster resilience and remote agricultural coverage respectively.
United States
FCC Part 15 rules enable rapid municipal broadband deployment without spectrum auction costs. Chicago and Austin are expanding citywide mesh networks for public safety and digital equity programs. Utility cooperatives in Texas and California are piloting kinetic mesh protocols for wildfire-prone distribution grids.
Germany
Distribution network operators specify 15-year hardware lifespans with on-site technician guarantees under federal smart grid mandates. The EU Radio Equipment Directive enforces stringent electromagnetic compatibility documentation for CE marking. Industrial automation clusters in Bavaria and North Rhine-Westphalia prioritize pre-certified module portfolios to avoid deployment delays.
Japan
Earthquake-prone prefectures deploy rapid-deploy mesh kits for emergency responder communications. METI guidance accelerates utility modernization with interoperability requirements for distribution automation. Tokyo and Osaka metropolitan areas serve as testbeds for sensor-dense smart city architectures with unified management platforms.
Australia
Federal supply chain risk management guidance consolidates vendor relationships toward single-source integrators with cybersecurity liability coverage. Solar-powered remote nodes with satellite backhaul serve agricultural monitoring in Queensland and Western Australia pastoral zones. Melbourne and Sydney utilities lead smart metering standardization around Wi-SUN Alliance protocols.
Singapore
City-state sensor density targets drive unified management platforms spanning traffic, air quality, and public lighting. National broadband mandates prioritize encrypted, low-latency specification tiers for critical infrastructure. The dense urban environment demonstrates operational models replicated across Southeast Asian municipal planning offices.
Wireless Mesh Networking Market Competitive Landscape
Capability concentration sits with semiconductor and protocol specialists; scale advantage sits with enterprise networking incumbents. The market structures around three tiers: premium indoor infrastructure providers, kinetic mobility specialists, and utility-scale system integrators. Dominant competitive moves include strategic partnerships for cybersecurity liability coverage and vertical integration into baseband silicon supply.
Within the kinetic mobility tier, Rajant Corporation exemplifies protocol specialization for mining and defense applications. Cisco Systems occupies a position among enterprise-grade indoor deployment anchors leveraging routing heritage. Qualcomm Technologies represents semiconductor supply concentration extending into next-generation chipset standards.
| Leading Market Players |
|---|
| Motorola Solutions |
| Rajant Corporation |
| Cisco Systems |
| Fluidmesh Networks |
| Ruckus Networks |
| Hewlett Packard Enterprise |
| Cambium Networks |
| Qualcomm Technologies |
| ABB |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's wireless infrastructure manufacturing corridor is compressing module pricing and forcing suppliers toward extended payment terms to preserve offtake volumes. This utilization imbalance simultaneously erodes margins for tier-two vendors and creates procurement leverage for systems integrators bundling cybersecurity liability coverage.
Pricing Analysis
Long-term offtake contracts dominate utility-scale deployments in Germany and Australia, while spot-market module purchases prevail in North American campus rollouts. Three-tier pricing structure across premium, standard, and economy levels separates Wi-Fi 7 chipset-enabled equipment from IEEE 802.11ax certified hardware and legacy 802.11s configurations. Cost compression in the standard tier is intensifying because Qualcomm's baseband silicon concentration limits second-source alternatives. Municipal utilities exhibit the highest price sensitivity due to procurement oversight requirements, whereas mining operators prioritize mobility tolerance over unit cost.
Supply Chain Analysis
Extended payment terms from Taiwanese and South Korean foundry partners are becoming standard for mesh radio module vendors seeking wafer allocation commitments. Baseband silicon fabrication draws from Taiwan Semiconductor Manufacturing Company capacity, with assembly and test operations concentrated in Malaysia and Vietnam. Single-source vulnerability in Qualcomm's chipset supply creates exposure for equipment vendors lacking alternative baseband architectures. Distribution runs through channel partners with embedded security operations capabilities rather than pure hardware distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through Wi-SUN Alliance certification and FCC Part 15 compliance creates sticky vendor relationships resistant to substitution.
For Market Incumbents: Entrench position through captive supply of Wi-Fi 7 baseband silicon and backward integration into RF engineering talent pools concentrated at legacy military contractors. Private 5G network encroachment on utility budgets demands preemptive certification investment in EU cybersecurity labeling mandates to lock out unqualified competitors. Channel control through single-source integrator relationships with liability coverage anchors procurement decisions in Australia's critical infrastructure sectors.
For New Entrants and Emerging Players: Pursue agricultural sensor network deployments in Brazil's farming corridors and Queensland pastoral zones where precision irrigation demand outpaces established vendor presence. Kinetic mesh protocols for logistics yards represent the most penetrable mobility-tolerant segment given Rajant Corporation's mining-defense concentration leaves adjacent verticals exposed. Go-to-market execution should emphasize satellite-backhaul integration for remote deployment models underserved by terrestrial infrastructure specialists.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among utility-scale system integrators with multi-year field maintenance contracts and predictive maintenance service tiers. Long-term viability across the analysis window favors semiconductor suppliers with protocol-agnostic baseband architectures adaptable to Wi-SUN, IEEE 802.11ax, and kinetic mesh standards. Acquisition targets should demonstrate pre-certified module portfolios under EU Radio Equipment Directive and ETSI EN 300 328 coexistence protocols. The signal to monitor is consolidation velocity among municipal utility buying committees shifting from multi-source to single-source procurement frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Wi-SUN Alliance Certification Investment | Preemptive compliance with utility interoperability mandates locks out uncertified competitors in German and Australian smart grid deployments. |
| Backward Integration into Baseband Silicon | Captive supply of mesh radio chipsets insulates margin compression from Qualcomm's dominant pricing power in Wi-Fi 7 modules. |
| Cybersecurity Liability Coverage Expansion | Embedded security operations capabilities displace pure hardware distributors in Australia's federally guided supply chain risk management framework. |
| Kinetic Mesh Protocol Development | Mobility-tolerant outdoor configurations capture logistics and mining applications where conventional static mesh architectures fail. |
| Agricultural Sensor Network Partnership | Precision irrigation and livestock monitoring corridors in Brazil and Western Australia offer greenfield expansion beyond saturated urban smart city markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, Wi-SUN Alliance certification registries, and utility procurement disclosure filings. Primary engagement encompassed RF engineering directors at semiconductor firms, smart grid procurement officers at German distribution network operators, channel partners with security operations capabilities, and municipal IT directors overseeing Barcelona and Singapore deployments. Secondary validation incorporated IEEE standards documentation, ETSI technical specifications, and customs trade data for mesh radio module imports. Bottom-up unit economics from individual deployment models were triangulated against top-down market sizing from infrastructure capital expenditure tracking.
Forecast inputs include utility smart grid mandate compliance timelines, IEEE 802.11ax and Wi-Fi 7 chipset availability curves, and municipal broadband obligation schedules across the projection horizon. Segmentation dimensions modeled encompass deployment model, application type, end user vertical, and technology protocol choice. CAGRs derive from infrastructure refresh cycle compression and IoT connectivity penetration rates in agricultural and environmental monitoring. Industry-specific forecast inputs include spectrum auction outcomes and cybersecurity labeling mandate enforcement schedules.
Sensitivities concentrate around regulatory revision to FCC Part 15 power constraints, EU Radio Equipment Directive electromagnetic compatibility documentation requirements, and Wi-SUN Alliance protocol stack updates. Forecasts reflect assumptions regarding semiconductor foundry capacity allocation and utility capital expenditure continuity. Macroeconomic contraction, spectrum reallocation, or breakthrough in private 5G cost-efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
Global Mobile and Wireless Backhaul Market
Wireless Technologies
Wimax Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
APAC Small Cell Tower Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
LTE and 5G Market