
 APAC Small Cell Tower Market | 2026-2036
APAC Small Cell Tower Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Small Cell Tower Market Outlook
Carrier-grade outdoor specifications is collapsing the gap between macro infrastructure and enterprise-grade small cell deployments across dense urban corridors. Huawei Technologies Co., Ltd. leverages its integrated baseband-to-antenna portfolio to anchor large-scale 5G NR rollouts across Chinese municipalities. Telefonaktiebolaget LM Ericsson competes through its intelligent site solutions that sustain energy efficiency targets for tropical climates. Nokia Corporation specializes in cloud-native small cell architectures that differentiate its offering for enterprise private networks.
A small cell tower comprises low-powered radio access nodes operating below 250 milliwatts to 2 watts, designed for licensed spectrum bands from 600 MHz to 6 GHz with backhaul via fiber, millimeter wave, or sub-6 GHz relay links. These installations extend macro network coverage and capacity into urban canyons, indoor venues, and suburban edges where signal attenuation degrades quality of service. Picocells and microcells dominate current deployment volumes across the APAC footprint, though 5G NR-enabled metered cells represent the fastest-growing product tier as operators pursue network densification targets. Indoor installation types command premium positioning in Japan and South Korea where enterprise verticals demand guaranteed latency thresholds for manufacturing automation.
China's MIIT enforces GB standards for electromagnetic emissions and spectrum efficiency that constrain foreign vendor participation, while India's TRAI mandates infrastructure-sharing frameworks to accelerate rural coverage obligations. Japan's METI coordinates municipal spectrum pilots that shape procurement specifications for disaster-resilient small cell grids. Stakeholders must weigh regulatory fragmentation against the scale advantages of unified product platforms as country-specific certification timelines extend deployment cycles.
Market Dynamics
5G NR network densification mandates from APAC telecommunications regulators are compressing deployment timelines and forcing infrastructure-sharing frameworks that reshape vendor procurement patterns across the region.
Growth Catalysts
- Japan METI disaster-resilient grid targets:Municipal spectrum pilots accelerate procurement of hardened outdoor small cell installations for earthquake-prone urban corridors.
- India TRAI infrastructure-sharing mandates:Rural coverage obligations compel operators to pool tower assets, reducing per-site capital barriers for microcell deployment.
- Millimeter-wave backhaul integration:Sub-6 GHz relay link congestion drives adoption of fiber-alternative transmission for dense urban picocell networks.
Market Restraints
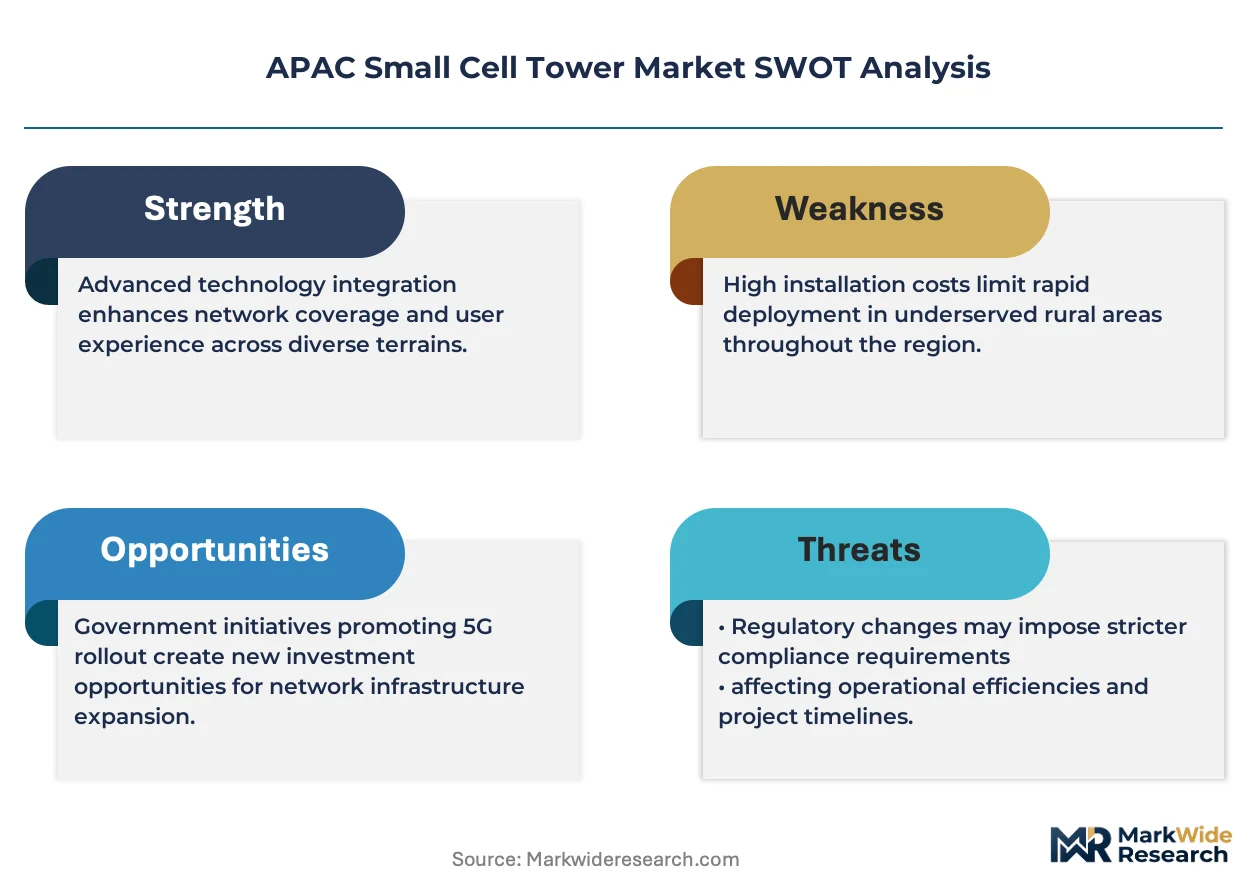
- China MIIT GB certification timelines:Electromagnetic emissions testing protocols extend foreign vendor product approval cycles by 8-14 months.
- Licensed spectrum fragmentation:Divergent national band allocations between 3.5 GHz and 4.9 GHz force hardware customization per jurisdiction.
- Site acquisition cost escalation:Municipal right-of-way fees in Seoul, Tokyo, and Singapore municipal districts consume 35-50% of total deployment budgets.
Strategic Opportunities
- Indonesia's underserved secondary cities:Bandung, Surabaya, and Medan corridors lack sufficient macro density, creating first-mover advantage for neutral-host small cell providers.
- Private 5G for manufacturing automation:Thailand's Eastern Economic Corridor industrial zones seek guaranteed latency thresholds for robotics integration.
- Cloud-native RAN architecture convergence:Virtualized baseband processing enables multi-tenant enterprise networks that split infrastructure costs across facility owners.
Industry Challenges
- RF engineering talent scarcity:Specialized millimeter-wave propagation modeling expertise concentrates in Shenzhen and Tokyo, constraining deployment velocity elsewhere.
- Legacy 4G small cell integration:Co-siting requirements with existing LTE infrastructure complicate power supply and antenna positioning in space-constrained street furniture.
- Multi-operator interoperability certification:Proprietary SON algorithms from incumbent vendors block seamless multi-carrier aggregation on shared hardware platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Small Cell Tower Market |
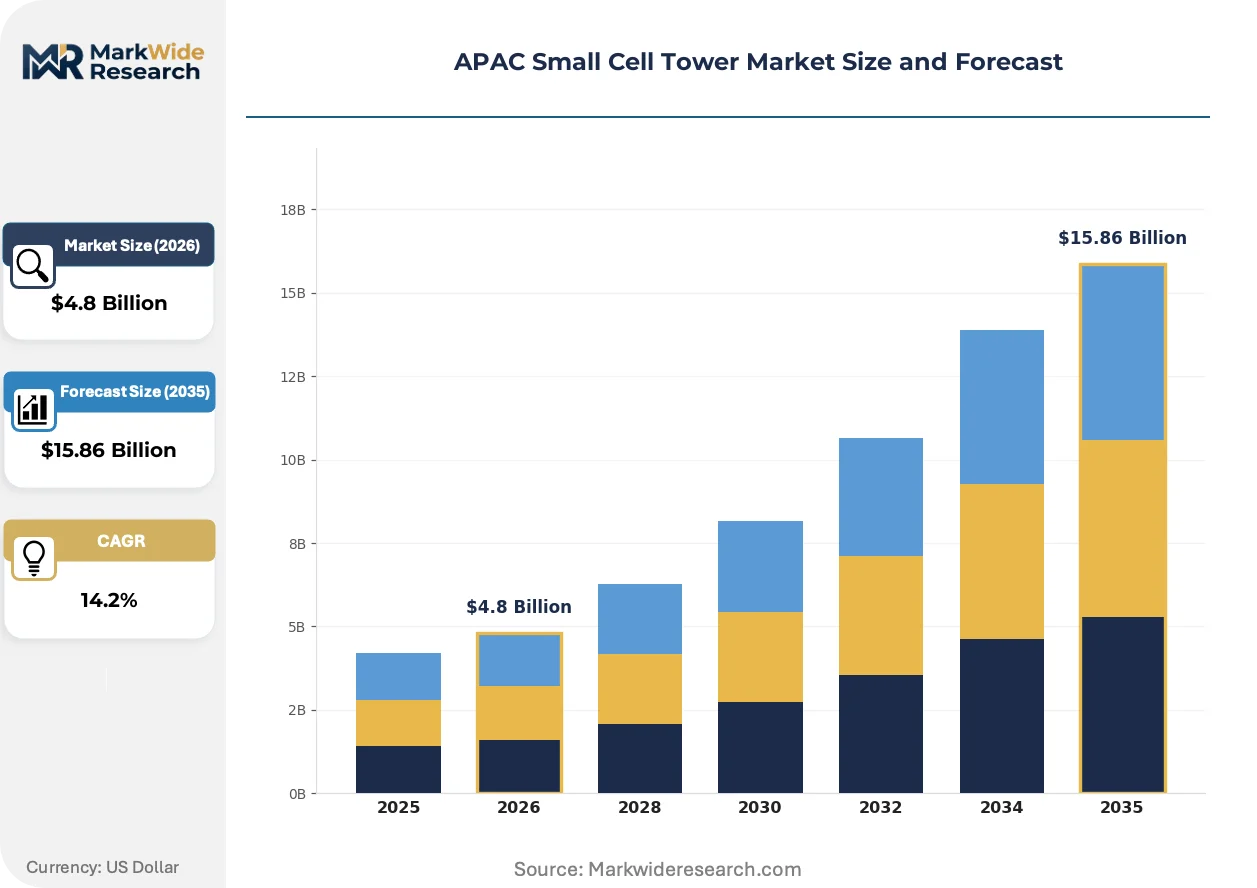
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Femtocells, Picocells, Microcells, Metered Cells Technology: 4G LTE, 5G NR, Wi-Fi, Hybrid End User: Telecommunication Operators, Enterprises, Municipalities, Residential Installation Type: Indoor, Outdoor, In-Macro, On-Street |
| Companies Covered | Huawei Technologies Co., Ltd., Telefonaktiebolaget LM Ericsson, Nokia Corporation, ZTE Corporation, Samsung Electronics Co., Ltd., Parallel Wireless Inc., Airspan Networks Inc., NEC Corporation, Baicells Technologies Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Small Cell Tower Market Strategic Shifts
Open RAN interface specifications are fragmenting traditional integrated baseband-to-antenna supply relationships, enabling new vendor combinations that challenge incumbent procurement patterns across Southeast Asian operator groups.
Massive MIMO antenna arrays are decomposing into distributed radio units and centralized baseband pools. Japanese mobile network operators deploy these disaggregated architectures in Tokyo and Osaka stadium venues to manage 10,000+ concurrent spectator connections. The separation of radio and compute functions is compressing equipment refresh cycles from seven years toward four-year replacement horizons.
China's MIIT spectrum efficiency mandates now require dynamic spectrum sharing capabilities in all new 5G small cell certifications. Equipment vendors must demonstrate 4G/5G carrier aggregation within unified 100 MHz blocks. Korean operators in Seoul metropolitan districts face the steepest compliance deadlines, driving accelerated retirement of single-mode hardware.
Neutral-host business models are displacing operator-captive deployment strategies. Australian tower companies now contract directly with property developers in Sydney and Melbourne commercial districts, pre-installing multi-tenant small cell infrastructure before tenant occupancy. This shifts capital risk from mobile operators to infrastructure specialists while accelerating indoor coverage availability.
APAC Small Cell Tower Market Segmentation
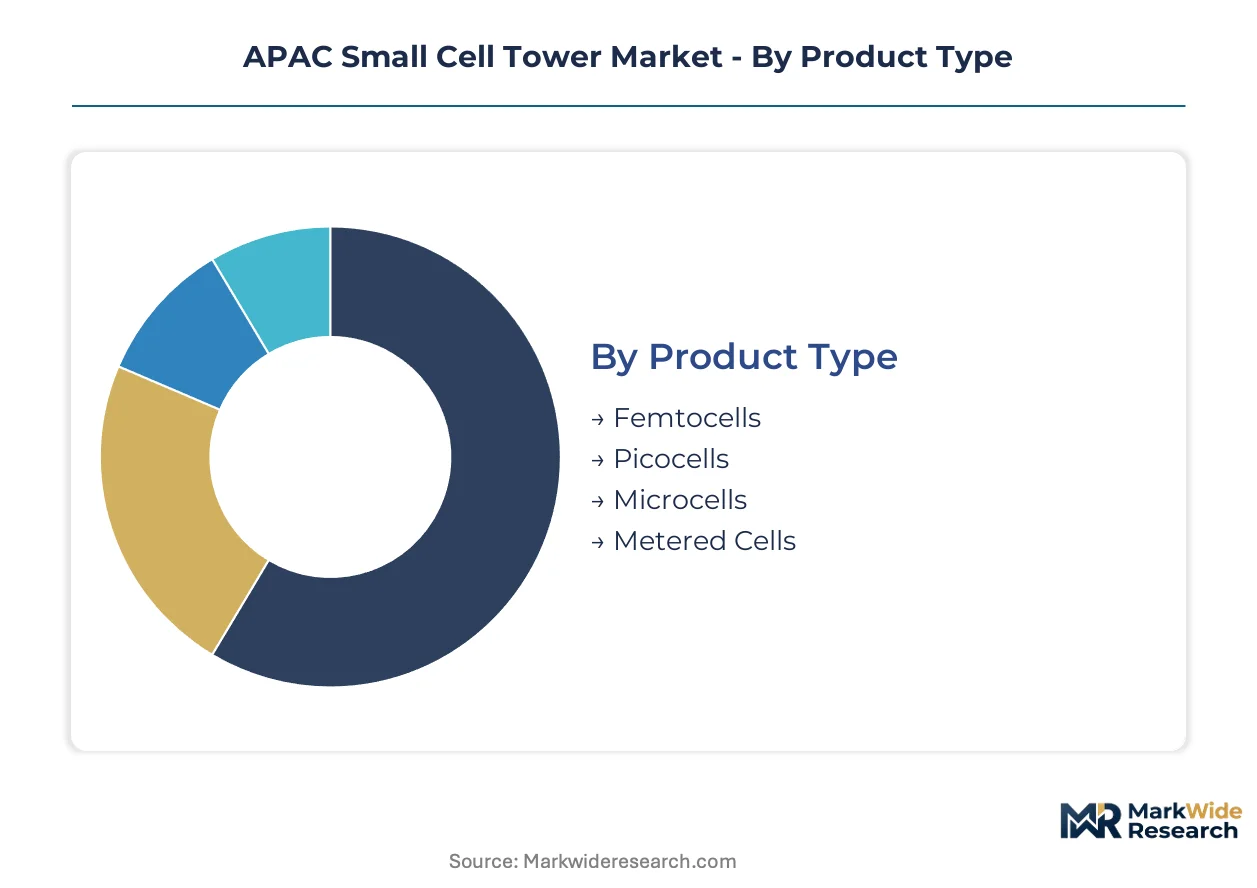
Segmentation reveals how deployment economics vary sharply across product tiers and installation contexts. Each dimension exposes distinct procurement patterns shaped by regulatory mandates, spectrum allocation, and site access constraints across the region.
Product Type:
Domestic demand concentrates in picocells and microcells across Chinese and Indian municipalities, while metered cells draw export-led procurement from Southeast Asian operators seeking 5G densification.
- Femtocells:Ultra-low-power units below 100 milliwatts designed for residential coverage gaps. Demand clusters in Japan's suburban prefectures where NTT Docomo and KDDI deploy consumer-purchased units for basement and interior dead zones.
- Picocells:Mid-range nodes operating at 100-250 milliwatts with integrated backhaul. Indoor venue deployments dominate in Seoul's COEX Convention Center and Singapore's Marina Bay Sands, driven by enterprise guaranteed-latency contracts for event connectivity.
- Microcells:Higher-power outdoor installations serving 200+ concurrent users. Street-level deployments concentrate in Mumbai's Bandra-Kurla Complex and Jakarta's Sudirman Central Business District where macro site acquisition costs prove prohibitive.
- Metered Cells:Software-defined 5G NR nodes with dynamic power adjustment. Expanding most quickly across Thailand's Eastern Economic Corridor as industrial automation requirements drive private network specifications.
Picocells hold the largest share; momentum sits with metered cells.
Technology:
Cost tiering separates legacy 4G refresh cycles from premium 5G NR deployments, with hybrid architectures occupying a mid-tier position for operators managing transition risk.
- 4G LTE:Mature small cell platforms with established supply chains and compressed pricing. Rural coverage obligations in India's tier-2 cities sustain residual procurement despite spectrum refarming pressures.
- 5G NR:Next-generation nodes supporting millimeter-wave and sub-6 GHz carrier aggregation. China's MIIT mandates dynamic spectrum sharing capabilities, accelerating retirement of single-mode hardware in Beijing and Shanghai metropolitan networks.
- Wi-Fi:Unlicensed spectrum offload solutions for high-density indoor environments. Enterprise demand concentrates in Australian commercial districts where neutral-host providers bundle Wi-Fi with licensed small cell infrastructure.
- Hybrid:Converged platforms supporting simultaneous 4G, 5G, and Wi-Fi operation. Procurement is climbing the fastest among Southeast Asian operators seeking to minimize street furniture footprint in space-constrained Singapore and Hong Kong.
4G LTE dominates installed base; hybrid configurations are gaining share fastest.
End User:
Volume concentration follows infrastructure ownership patterns, with telecommunication operators accounting for bulk procurement while enterprises drive premium specification tiers.
- Telecommunication Operators:Mobile network operators procuring carrier-grade outdoor specifications. Reliance Jio and Bharti Airtel in India anchor regional volume through TRAI-mandated rural coverage obligations.
- Enterprises:Private network deployments for manufacturing, logistics, and venue management. Toyota and Honda facilities in Japan's Aichi Prefecture specify hardened outdoor units with guaranteed 99.999% availability.
- Municipalities:Smart-city infrastructure programs integrating small cells with street lighting and traffic management. Seoul Metropolitan Government bundles small cell deployment with LED streetlight conversion contracts.
- Residential:Consumer-purchased indoor units for coverage extension. Limited to developed markets where operator subsidy programs exist, primarily Japan and South Korea.
Telecommunication operators command volume leadership; enterprises show the steepest specification escalation.
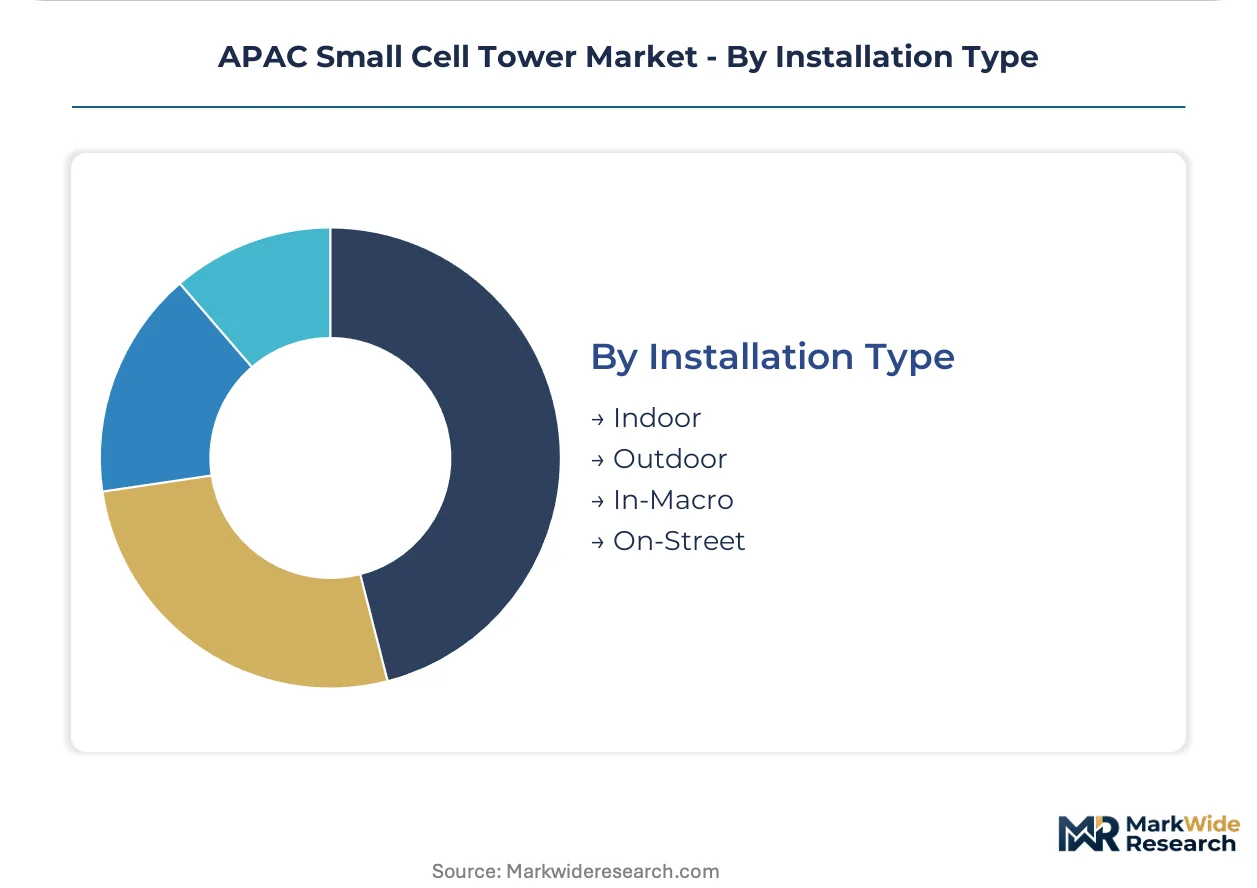
Installation Type:
Margin structures diverge between indoor premium deployments with guaranteed service levels and outdoor commodity installations competing on capital efficiency.
- Indoor:Enterprise and venue deployments with controlled environmental conditions. Japan's manufacturing automation sector commands premium positioning through METI-coordinated latency threshold requirements.
- Outdoor:Street-level and rooftop installations exposed to tropical climates. Ericsson and Nokia compete on energy efficiency specifications for Jakarta and Bangkok deployment where cooling costs dominate operational expenditure.
- In-Macro:Co-sited small cells integrated with existing macro tower infrastructure. India's infrastructure-sharing mandates accelerate this configuration for rural coverage extension.
- On-Street:Pole-mounted and street furniture deployments in dense urban corridors. Singapore's municipal right-of-way fee structure consumes disproportionate budget share, favoring multi-tenant neutral-host models.
Outdoor installations anchor deployment volume; indoor specifications capture margin premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese equipment exports supply Southeast Asian 5G rollouts while Japanese and Korean operators import specialized outdoor hardened units for tropical deployment corridors.
China
MIIT spectrum efficiency mandates and GB certification standards accelerate domestic procurement of dynamic spectrum-sharing small cells. Beijing and Shanghai metropolitan networks drive retirement of single-mode hardware ahead of 2026 deadlines. Shenzhen anchors millimeter-wave propagation modeling expertise that constrains regional deployment velocity elsewhere.
India
TRAI infrastructure-sharing mandates and rural coverage obligations compel Reliance Jio and Bharti Airtel to pool tower assets. Mumbai's Bandra-Kurla Complex and Delhi-NCR urban corridors concentrate street-level microcell deployment where macro site acquisition costs prove prohibitive. Municipal smart-city programs in tier-2 cities sustain residual 4G refresh procurement.
Japan
METI disaster-resilient grid targets and municipal spectrum pilots accelerate hardened outdoor small cell procurement for earthquake-prone corridors. Toyota and Honda facilities in Aichi Prefecture specify carrier-grade units with guaranteed availability thresholds. Tokyo and Osaka stadium venues deploy disaggregated Massive MIMO architectures for high-density spectator connectivity.
South Korea
Seoul metropolitan districts face the steepest MIIT-aligned compliance deadlines for dynamic spectrum sharing capabilities. COEX Convention Center and Gangnam commercial districts command premium indoor picocell specifications with enterprise guaranteed-latency contracts. Korean operators drive accelerated retirement of legacy single-mode hardware ahead of regional peers.
Indonesia
Underserved secondary cities including Bandung, Surabaya, and Medan lack sufficient macro density for quality service delivery. Jakarta's Sudirman Central Business District anchors outdoor microcell deployment competing with neutral-host providers for street furniture access. Tropical climate energy efficiency specifications from Ericsson and Nokia dominate procurement evaluation criteria.
APAC Small Cell Tower Market Competitive Environment
Listed leaders compete with private specialists across certification timelines and spectrum customization requirements. The vendor base consolidates around integrated baseband-to-antenna portfolios and cloud-native disaggregated architectures. Three archetypes dominate: state-linked equipment champions with domestic market anchoring, Nordic engineering specialists with tropical climate optimization, and neutral-host infrastructure platforms with multi-tenant deployment models. Competitive moves concentrate on vertical integration into semiconductor components and strategic partnerships with municipal right-of-way holders.
Within the state-linked champion tier, Huawei Technologies Co., Ltd. and ZTE Corporation exemplify integrated portfolio strategies that align with MIIT procurement specifications. Among Nordic specialists, Telefonaktiebolaget LM Ericsson and Nokia Corporation occupy positions emphasizing energy efficiency and cloud-native architectures respectively. Samsung Electronics Co., Ltd. represents the diversified conglomerate archetype with captive semiconductor supply advantages. These anchors illustrate how geographic origin and corporate structure shape competitive positioning across certification-intensive procurement cycles.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| ZTE Corporation |
| Samsung Electronics Co., Ltd. |
| Parallel Wireless Inc. |
| Airspan Networks Inc. |
| NEC Corporation |
| Baicells Technologies Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Shenzhen and Shanghai radio frequency component foundries lock in both millimeter-wave semiconductor supply access and eighteen-month price visibility for 5G NR small cell vendors serving MIIT-mandated deployment timelines across Chinese municipalities.
Pricing Analysis
5G NR metered cells command substantial premiums over legacy 4G LTE picocell platforms, while hybrid 4G/5G configurations occupy a mid-tier position for operators managing transition risk. Three-tier pricing structure across carrier-grade, enterprise-grade, and municipal-economy levels separates procurement specifications, with MIIT GB certification tiers and tropical climate hardening driving differentiation. Cost compression in the 4G refresh tier is intensifying because Indian TRAI rural coverage obligations force volume procurement of mature platforms. Telecommunication operators exhibit highest price sensitivity, while Japanese manufacturing automation enterprises accept premium positioning for guaranteed latency thresholds.
Supply Chain Analysis
Strategic stockpiling of millimeter-wave radio frequency integrated circuits and baseband processors dominates vendor inventory strategies, buffering against MIIT certification timeline volatility. Manufacturing concentrates in China, South Korea, and Taiwan, with Shenzhen anchoring millimeter-wave propagation modeling expertise and Seoul foundries supplying specialized semiconductors. Component dependencies include gallium nitride power amplifiers, FPGA programmable logic devices, and fiber-optic transceivers. Single-source vulnerability around advanced node semiconductor fabrication poses structural risk. Distribution runs through direct operator procurement channels and neutral-host infrastructure platforms contracting with municipal right-of-way holders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized RF engineering talent for millimeter-wave propagation modeling concentrates in Shenzhen and Tokyo, constraining deployment velocity across Southeast Asian corridors where network densification timelines compress.
For Market Incumbents: Consolidate semiconductor component sourcing through backward integration into gallium nitride foundry partnerships or captive supply agreements with Shanghai radio frequency specialists. Deepen certification engineering capacity in Beijing to compress MIIT GB approval cycles that currently extend foreign vendor product timelines. Prioritize tropical climate energy efficiency specifications to defend positioning against Ericsson and Nokia in Jakarta and Bangkok deployment corridors. For New Entrants and Emerging Players: MIIT fast-track certification partnerships with domestic Chinese testing laboratories offer accelerated market entry for metered cell platforms targeting private 5G industrial automation. Indonesia's underserved secondary cities including Bandung and Surabaya present white-space opportunities where macro density gaps exceed quality-of-service thresholds. Neutral-host business models contracting directly with Australian property developers provide a proven go-to-market angle that shifts capital risk from mobile operators to infrastructure specialists. For Investors and Strategic Acquirers: Cloud-native RAN software specialists with virtualized baseband processing capabilities represent the priority acquisition archetype as Open RAN interface specifications fragment traditional integrated supply relationships. Long-term viability hinges on multi-tenant enterprise network architectures that split infrastructure costs across facility owners. Watch for MIIT dynamic spectrum sharing mandate acceleration as the inflection indicator that would warrant portfolio rebalancing toward software-defined platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Engineering Expansion | Beijing-based testing capacity compresses MIIT GB approval timelines for foreign vendors. |
| Neutral-Host Infrastructure Partnership | Sydney property developer contracts accelerate indoor coverage availability before tenant occupancy. |
| Semiconductor Backward Integration | Captive gallium nitride foundry supply buffers against advanced node single-source vulnerability. |
| Cloud-Native RAN Development | Virtualized baseband processing enables multi-tenant cost splitting across Japanese manufacturing facilities. |
| Tropical Climate Optimization | Jakarta energy efficiency specifications from Nordic vendors reduce cooling-dominated operational expenditure. |
Study Parameters
Operator-level perspectives from network planning executives, RF engineering directors, municipal procurement officers, and neutral-host infrastructure managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against MIIT spectrum allocation filings, TRAI infrastructure-sharing directives, METI disaster-resilience procurement specifications, and customs trade data for radio access node equipment. Bottom-up deployment volume modeling triangulated against top-down telecommunications capital expenditure disclosures from Reliance Jio, Bharti Airtel, NTT Docomo, and Korean mobile network operators.
Sensitivity analysis across spectrum allocation timelines, certification duration scenarios, and municipal right-of-way fee structures shaped the analytical framework. Segmentation dimensions modeled include product type tier, technology generation, end-user ownership pattern, and installation context across the projection horizon. CAGRs derived from deployment volume trajectories weighted by unit economics for each specification tier. Industry-specific forecast inputs incorporated MIIT dynamic spectrum sharing mandate compliance deadlines and TRAI rural coverage obligation enforcement intensity.
Decision-makers should treat outputs as directional under assumptions of sustained 5G NR densification mandates and stable semiconductor supply availability; material deviation would warrant model refresh. Specific risk factors include MIIT certification timeline extensions, licensed spectrum band fragmentation between national jurisdictions, and RF engineering talent scarcity constraining deployment velocity. Revision becomes warranted when neutral-host business model adoption crosses threshold penetration in Australian and Southeast Asian commercial districts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Wimax Market
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
5G Spectrum Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Wireless Microphone Market