
 North America Wireless Microphone Market | 2026-2036
North America Wireless Microphone Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wireless Microphone Market Analytics
Market Context
Professional-grade digital wireless audio is rotating toward higher RF stability and extended dynamic range as the defining purchase criterion. Shure Incorporated leverages its domestic manufacturing footprint to sustain channel dominance across broadcast and touring verticals. Sennheiser electronic GmbH & Co. KG anchors its North American position through specialized frequency-agile systems engineered for congested RF environments. Audio-Technica Corporation competes on value-engineered digital platforms targeting mid-tier live sound contractors.
Technical Definition and Structural Segments
A wireless microphone is a transducer-cum-radio transmitter assembly that converts acoustic pressure waves into modulated RF signals, typically operating between 470–608 MHz or in the 1.9 GHz DECT band, for cable-free audio capture in performance and production environments. Handheld configurations retain the largest installed base, though lavalier and headset variants capture disproportionate margin pools in broadcast and corporate applications where concealment and mobility command pricing premiums. Digital technology segments displace legacy UHF architectures as spectrum scarcity intensifies, while live events and podcasting end-user categories outpace education in replacement velocity.
Regulatory Framework
The FCC governs frequency allocation and equipment authorization, directly constraining available spectrum and compelling hardware refresh cycles across the United States. Industry Canada coordinates parallel spectrum policy, while Mexico's IFT manages border-adjacent RF coordination; together these three regulators enforce interoperability standards that shape cross-border touring logistics and inventory decisions. Stakeholders must monitor pending spectrum auction outcomes and adaptive frequency-hopping certification requirements to time capital deployment and avoid stranded inventory.
Market Dynamics
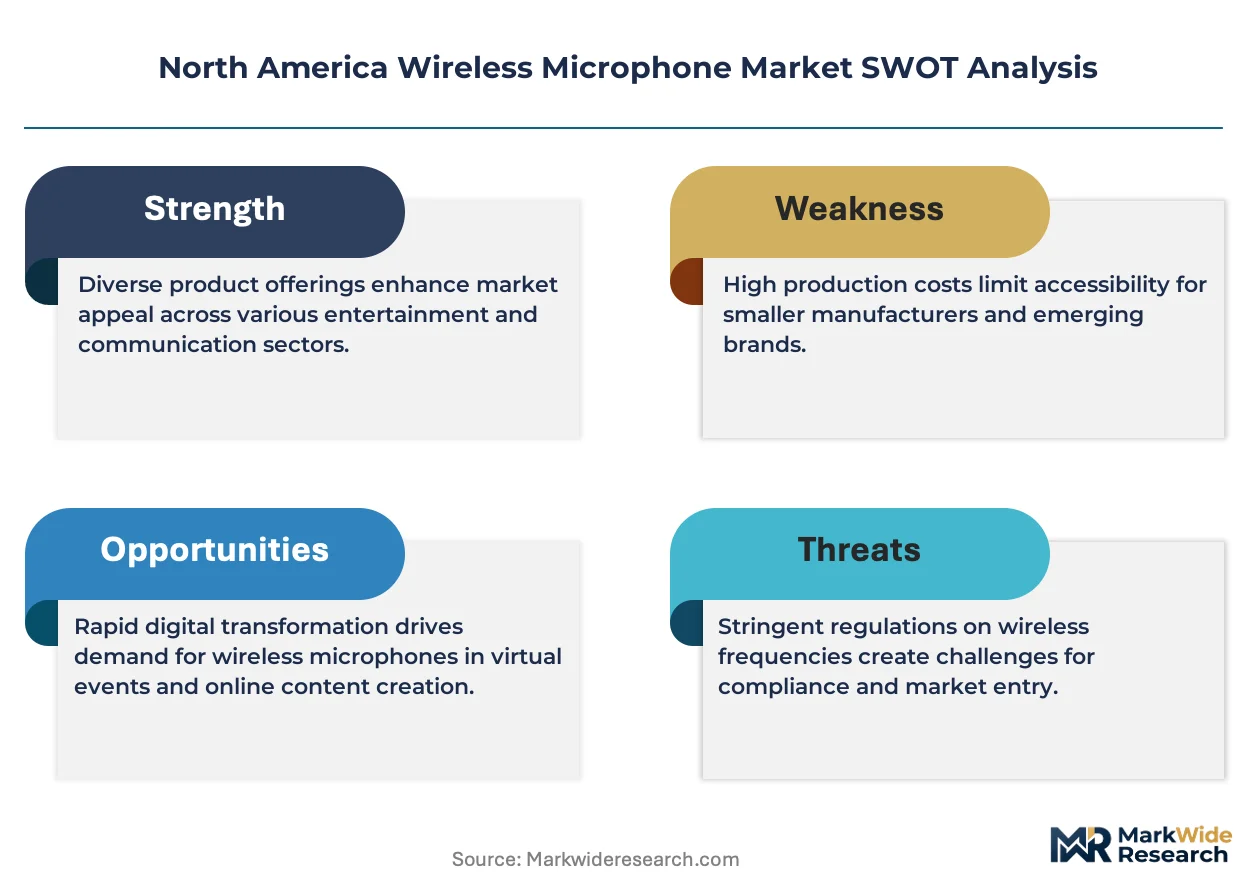
Spectrum scarcity from the FCC's 600 MHz incentive auction has forced wholesale hardware replacement across the United States live production sector, compressing procurement cycles and elevating RF stability to the top purchase criterion.
Growth Catalysts
- Live Event Production:Touring houses and festival operators across California, Texas, and Tennessee are replacing analog UHF inventories with digital wireless systems to meet RF coordination demands in dense metropolitan venues.
- FCC Spectrum Reallocation:The commission's post-auction clearing mandates have triggered mandatory equipment refresh cycles, pulling forward replacement demand that would otherwise have extended across multiple years.
- Podcasting Infrastructure:Independent content studios in Brooklyn, Austin, and Los Angeles are outfitting multi-channel digital wireless rigs as standard production kit, expanding addressable market beyond traditional broadcast.
Market Restraints
- Semiconductor Supply Concentration:RF transceiver chip fabrication concentrates in East Asian foundries, exposing North American manufacturers to lead-time volatility and allocation constraints.
- Frequency Coordination Costs:Dense urban RF environments in Manhattan, Chicago, and Toronto require paid spectrum coordination services that inflate total cost of ownership for mid-tier operators.
- Legacy Analog Stranding:Equipment operating in repurposed 616-698 MHz bands faces functional obsolescence without trade-in pathways, depressing residual value recovery.
Strategic Opportunities
- Mexico Touring Corridor:Border-adjacent production logistics between Tijuana and San Diego create demand for cross-certified frequency-agile systems that operate under both FCC and IFT frameworks.
- DECT Band Migration:1.9 GHz digital platforms bypass UHF congestion entirely, opening white space in corporate AV installations where range requirements are modest and interference immunity is paramount.
- Rental Channel Expansion:Specialized audio-visual rental houses in Las Vegas, Nashville, and Atlanta are building managed wireless inventories as subscription services, reducing upfront capital barriers for occasional users.
Industry Challenges
- RF Engineering Talent Scarcity:Frequency coordination and antenna distribution design require specialized expertise that outpaces vocational training pipeline output in the United States and Canada.
- Adaptive Frequency Certification Delays:FCC equipment authorization timelines for proprietary frequency-hopping algorithms extend product launch windows, compressing revenue realization against development investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wireless Microphone Market |
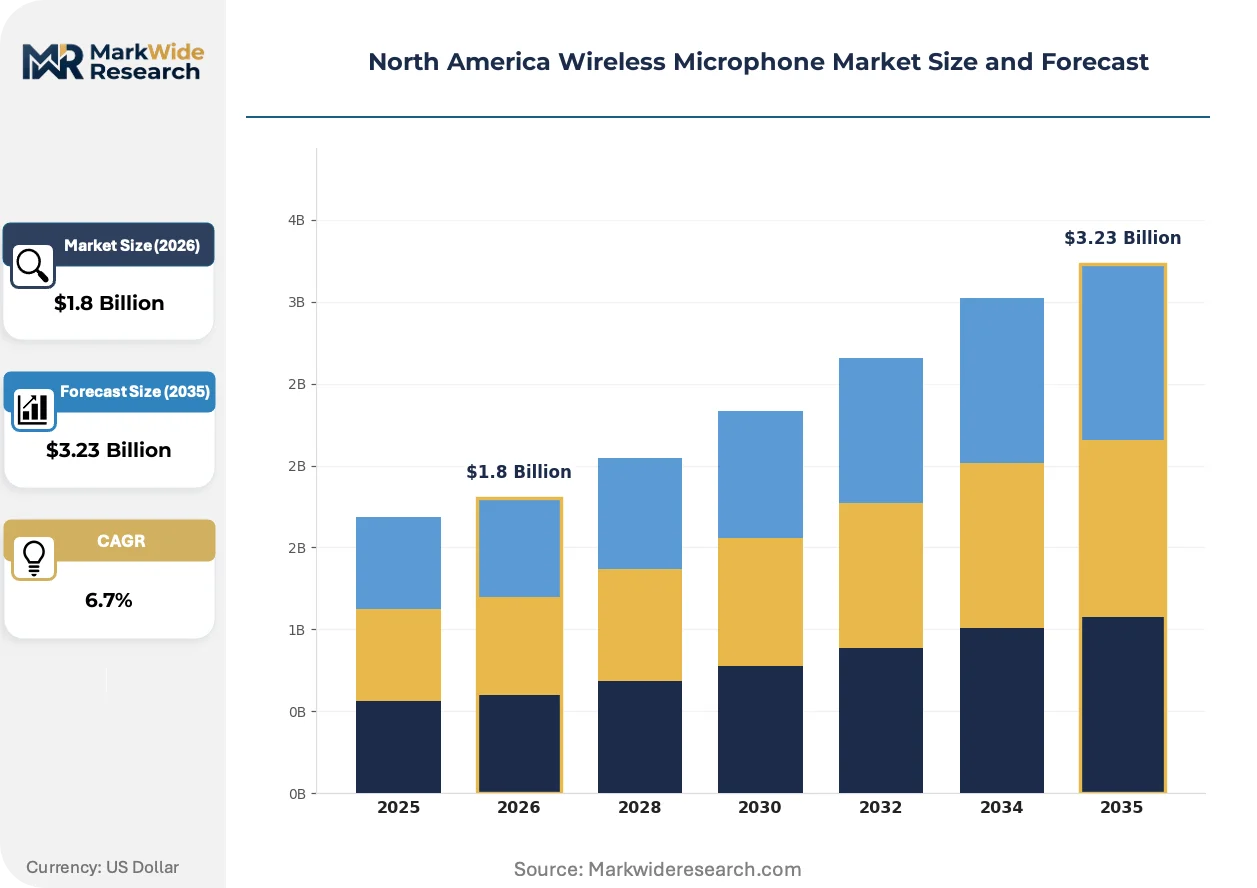
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Lavalier, Headset, Instrument Technology: UHF, VHF, Digital, Infrared Application: Live Events, Broadcasting, Public Speaking, Education End User: Musicians, Corporates, Educators, Podcasters |
| Companies Covered | Shure Incorporated, Sennheiser electronic GmbH & Co. KG, Audio-Technica Corporation, Sony Corporation, Lectrosonics, Inc., Yamaha Corporation, Røde Microphones, Samson Technologies Corp., Electro-Voice, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wireless Microphone Market Evolving Landscape
Digital modulation architectures are actively fragmenting the installed base between proprietary ecosystems, while regulatory pressure and procurement model evolution reshape how buyers evaluate total cost of ownership across the hardware lifecycle.
Digital wireless transmission is fragmenting competitive positioning across the North American market. Shure's Axient Digital, Sennheiser's Digital 6000, and Lectrosonics' DBSM platforms each employ incompatible modulation schemes and control protocols. Broadcast networks in New York and Los Angeles are standardizing on single-vendor ecosystems to simplify fleet management. This fragmentation is compressing interoperability and locking rental houses into captive inventory commitments.
FCC enforcement of unlicensed device rules in the 470-608 MHz core band is reshaping equipment authorization priorities. The commission's 2020 white space database requirements now constrain where professional wireless can operate in secondary markets. Live production companies in secondary cities like Phoenix, Denver, and Portland face steeper coordination burdens. Manufacturers are responding with automated frequency scanning and database-query capabilities embedded in receiver firmware.
Capital expenditure avoidance is driving procurement toward managed service models. Regional AV integrators in the Southeast and Midwest are offering wireless microphone systems as operational expenses rather than capital purchases. Corporate end-users in healthcare and legal sectors favor this structure for predictable budgeting. Canada shows similar momentum, with Toronto-based production services leading rental-subscription hybrid offerings.
North America Wireless Microphone Market Segmentation
Wireless microphone procurement patterns diverge sharply across use cases, with spectrum regulations and RF coordination requirements driving category-specific purchasing criteria. Buyers evaluate total cost of ownership differently depending on whether deployments serve touring productions, fixed installations, or content creation workflows.
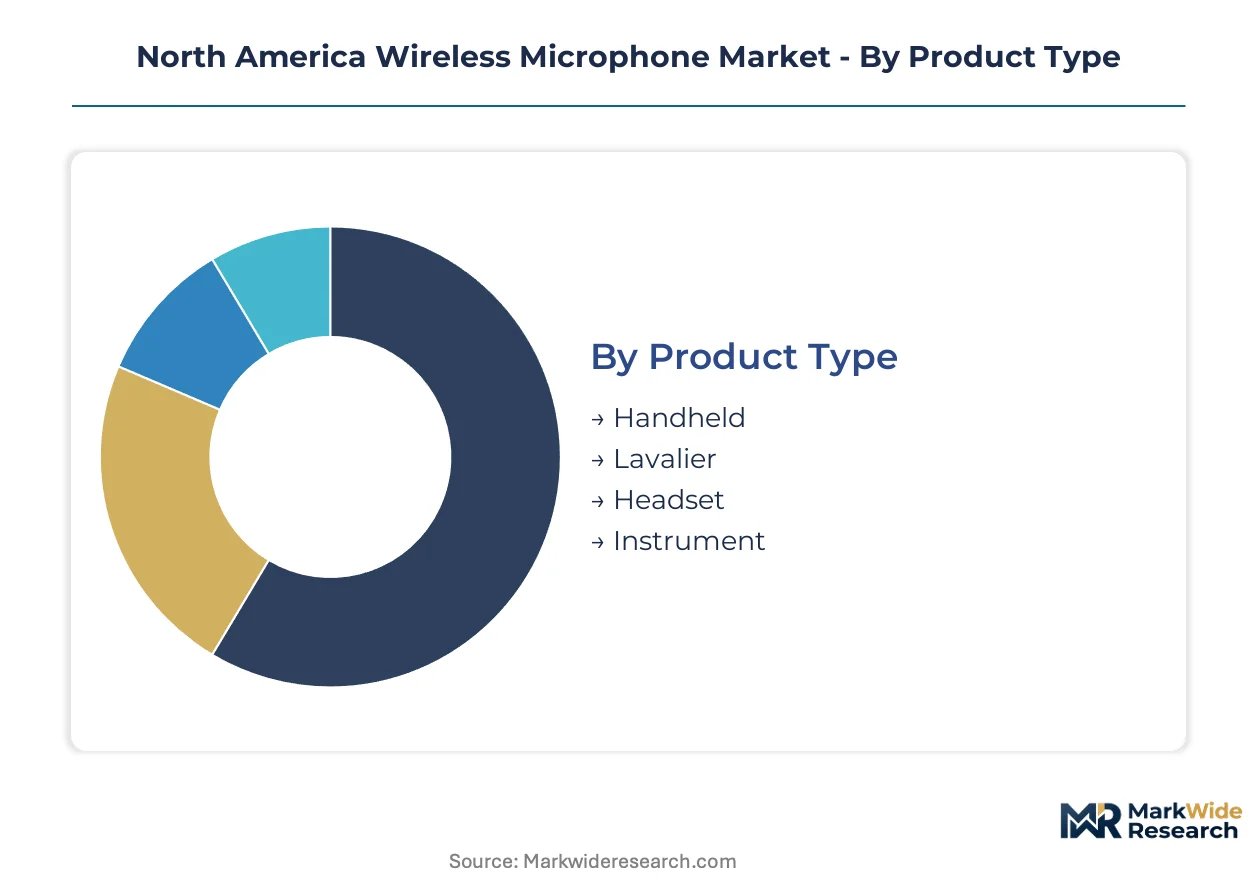
Product Type:
FCC equipment authorization rules differentiate professional-grade transmitters by form factor, with handheld and lavalier variants facing distinct RF exposure testing protocols that shape manufacturer certification timelines.
- Handheld:Integrates the microphone capsule and transmitter into a single housing, typically employing interchangeable capsules for polar pattern flexibility. Touring productions across California, Texas, and Tennessee favor these for vocal performance reliability in high-RF-density festival environments where antenna distribution complexity must be minimized.
- Lavalier:Miniature condenser elements paired with bodypack transmitters, engineered for concealment under wardrobe. Broadcast networks in New York and Los Angeles command pricing premiums here, as omnidirectional pickup patterns and moisture resistance specifications dominate technical evaluation for on-camera talent applications.
- Headset:Boom-positioned capsules mounted on ear-hook or headband assemblies for hands-free mobility. Theater productions and fitness instructors in Chicago and Toronto drive replacement demand where sweat resistance and secure fit override absolute audio fidelity.
- Instrument:Specialized transmitters adapted for guitar, brass, and percussion integration. Nashville session musicians and Austin live music venues prioritize these for stage mobility without signal degradation across extended transmission distances.
Established volume favors Handheld; emerging adoption favors Lavalier.
Technology:
Cost tier stratification separates legacy analog architectures from digital platforms, with semiconductor content and firmware development investment determining price positioning across procurement budgets.
- Digital:Proprietary modulation schemes convert audio to encrypted RF packets with extended dynamic range and frequency-agile channel selection. FCC spectrum reallocation mandates have compressed replacement cycles, pulling forward demand from analog UHF estates in major metropolitan production corridors.
- UHF:Traditional analog FM transmission occupying 470–608 MHz core bands, now contracting as auction-clearing deadlines strand inventory in repurposed spectrum blocks. Secondary market operators in Phoenix and Denver face steeper coordination burdens as white space database requirements constrain operational flexibility.
- VHF:Lower-frequency analog systems in 174–216 MHz range, retained primarily by budget-constrained educational institutions and houses of worship where multi-channel density requirements remain modest.
- Infrared:Line-of-sight optical transmission immune to RF congestion, confined to courtroom and secure government installations in Washington D.C. and Ottawa where electromagnetic eavesdropping concerns override range limitations.
Procurement velocity concentrates in Digital; residual utility persists in UHF.
Application:
Customer type determines whether buyers prioritize rental fleet interoperability, fixed installation reliability, or portable content creation flexibility.
- Live Events:Multi-channel touring rigs requiring RF coordination across dense metropolitan venues. Festival operators in Las Vegas and Atlanta favor frequency-agile systems with automated interference detection.
- Broadcasting:Network-affiliated studios demanding redundant transmission paths and remote monitoring capabilities. Major market facilities in Los Angeles and New York standardize on single-vendor ecosystems to simplify fleet management.
- Public Speaking:Corporate AV and government installations where predictable operation outweighs audio performance extremes. Healthcare and legal sector buyers in the Midwest favor managed service procurement models.
- Education:K-12 and university systems with constrained capital budgets and minimal technical support infrastructure. Texas and Florida school districts stretch replacement cycles despite spectrum compliance deadlines.
Revenue margin concentrates in Broadcasting; volume expansion favors Live Events.
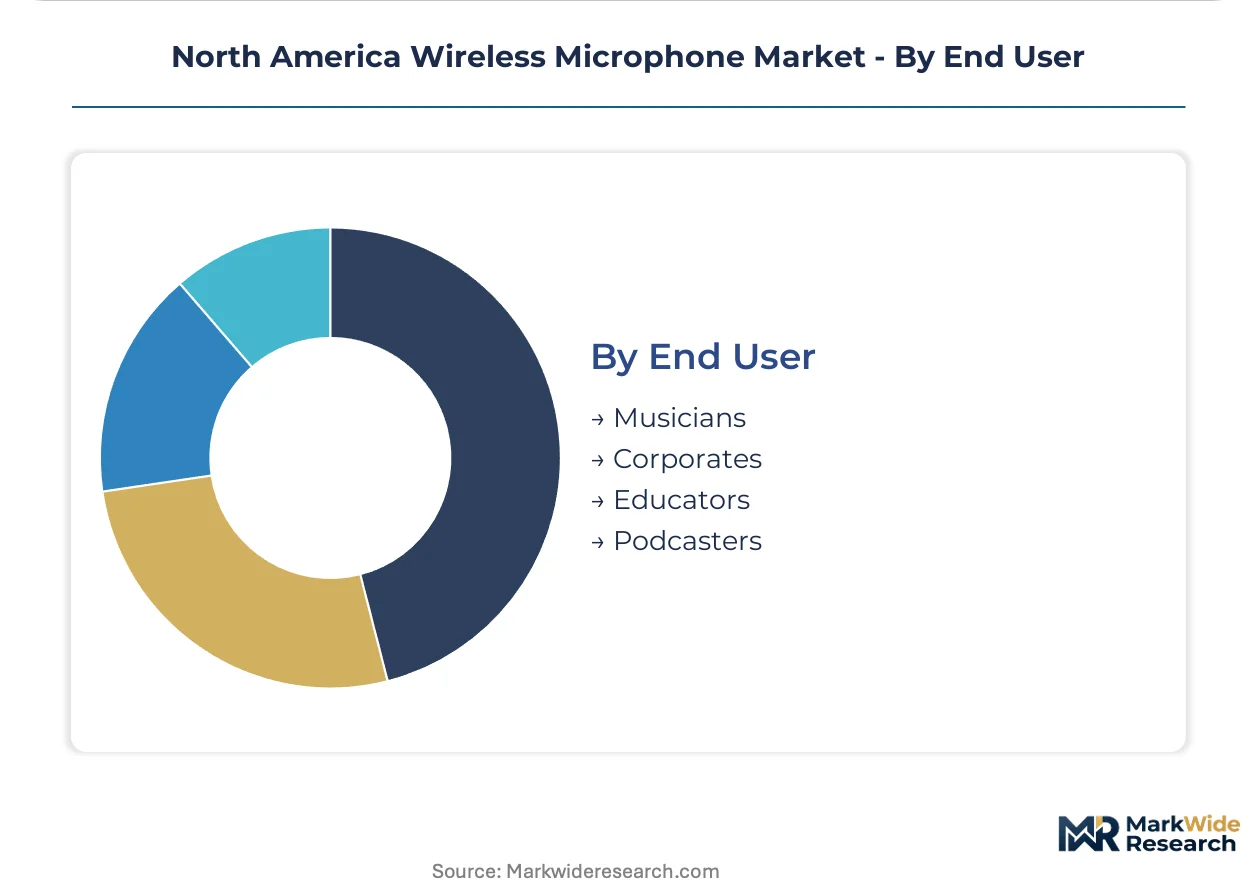
End User:
Geography and production maturity shape whether users purchase outright, rent episodically, or subscribe to managed wireless services.
- Musicians:Touring artists and session players requiring road-hardened transmitter durability. Nashville, Austin, and Memphis artists prioritize frequency-agile systems for cross-border touring into Mexico under dual FCC-IFT certification.
- Corporates:Enterprise AV departments and event marketing teams. Toronto and Chicago headquarters favor DECT-band 1.9 GHz platforms to bypass UHF coordination entirely in dense urban environments.
- Educators:University media departments and K-12 technology coordinators. California community colleges lag replacement cycles due to budget approval timelines extending beyond FCC compliance deadlines.
- Podcasters:Independent content studios and creator economy participants. Brooklyn, Austin, and Los Angeles micro-studios outfit multi-channel digital rigs as standard production kit, expanding addressable market beyond traditional broadcast.
Capital deployment concentrates among Corporates; steepest expansion trajectory sits with Podcasters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America wireless microphone market exhibits a pronounced import dependency for RF semiconductor components, while finished equipment assembly and brand headquarters concentrate domestically. Cross-border production logistics between the three member countries shape inventory deployment and certification strategies.
United States
Live event production houses in California, Texas, and Tennessee are replacing analog UHF inventories with digital wireless systems. The FCC's post-600 MHz auction clearing mandates have triggered mandatory equipment refresh cycles across the broadcast and touring sectors. Los Angeles and New York anchor network-affiliated studio demand, where redundant transmission paths and remote monitoring capabilities dominate technical specifications.
Canada
Toronto-based production services are leading rental-subscription hybrid offerings for corporate AV departments. Industry Canada coordinates parallel spectrum policy to FCC frameworks, enforcing interoperability standards that shape cross-border touring logistics. Broadcast facilities in Vancouver and Montreal prioritize frequency-agile systems for dense metropolitan RF coordination.
Mexico
Border-adjacent production logistics between Tijuana and San Diego create demand for cross-certified frequency-agile systems. The IFT manages RF coordination under frameworks that require dual FCC-IFT certification for touring equipment. Mexico City Metro and Nuevo León host expanding live event infrastructure where interference immunity commands pricing premiums.
North America Wireless Microphone Market Competitive Landscape
Concentration sits with heritage audio equipment manufacturers that have extended into digital wireless platforms through proprietary modulation investments. The vendor base stratifies between integrated electronics conglomerates and specialized RF audio houses, with the latter commanding loyalty in professional touring and broadcast verticals. Two archetypes dominate: frequency-agile system specialists and diversified professional audio portfolios. Competitive moves center on ecosystem lock-in through incompatible digital protocols and geographic expansion via regional certification acquisition.
Among heritage American RF audio houses, Shure Incorporated and Lectrosonics, Inc. exemplify the frequency-agile specialist archetype, while Sennheiser electronic GmbH & Co. KG represents the European-engineered alternative occupying a parallel premium position. These three entities anchor the professional-tier competitive structure, with their proprietary digital ecosystems fragmenting interoperability and compressing rental house inventory flexibility across the North American production corridor.
| Leading Market Players |
|---|
| Shure Incorporated |
| Sennheiser electronic GmbH & Co. KG |
| Audio-Technica Corporation |
| Sony Corporation |
| Lectrosonics, Inc. |
| Yamaha Corporation |
| Røde Microphones |
| Samson Technologies Corp. |
| Electro-Voice |
| Others |
Value Network & Pricing Analysis
FCC equipment authorization timelines gate both supplier qualification and price tiering across the North American wireless microphone market, compressing margins for uncertified entrants while rewarding heritage manufacturers with pricing power in broadcast and touring verticals.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FCC certification grade and RF channel density commanding the steepest premiums. Price differentiation stems from proprietary digital modulation ecosystems and after-sales spectrum coordination services bundled with enterprise contracts. Cost compression in mid-tier live sound channels is intensifying because rental houses consolidate around single-vendor fleets. Educational institutions exhibit highest price sensitivity, while broadcast networks in Los Angeles and New York demonstrate lowest sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
Port congestion along the Trans-Pacific trade lane elevates inbound logistics costs for RF semiconductor components, compressing working capital cycles for North American assembly operations. Fabrication concentrates in Taiwan, South Korea, and Japan, drawing from gallium arsenide substrates, precision crystal oscillators, and proprietary DSP firmware. Single-source vulnerability in RF transceiver chip supply creates exposure to allocation constraints during foundry capacity crunches. Distribution runs through authorized dealer networks and specialized AV rental houses, with direct-to-touring-house procurement gaining share in California and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proprietary digital ecosystem lock-in is fragmenting interoperability and creating platform-economics inflection, rewarding vendors who standardize rental house and broadcast network fleets around captive protocols.
For Market Incumbents: Secure spectrum coordination service revenue by bundling automated frequency management with hardware leases, defending against emerging DECT-band entrants. Deepen backward integration into RF transceiver design to reduce foundry allocation exposure. Prioritize dual FCC-IFT certification acquisition for cross-border touring corridor dominance. For New Entrants and Emerging Players: Differentiate on 1.9 GHz DECT platforms targeting corporate AV installations in Chicago and Toronto where UHF coordination costs burden incumbent pricing. Target podcasting micro-studios in Brooklyn and Austin with subscription-priced multi-channel rigs. Pursue rental-subscription hybrid go-to-market models to bypass upfront capital barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital wireless platform development, favoring scaled R&D amortization over niche analog specialization. Acquire frequency-agile firmware specialists with FCC certification pipelines rather than hardware-assemblers. Monitor FCC adaptive frequency-hopping authorization timelines as inflection signal for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Ecosystem Standardization | Broadcast networks in New York standardize on single-vendor fleets to simplify RF coordination. |
| Dual Certification Acquisition | Touring houses demand FCC-IFT cross-certified systems for Tijuana-San Diego logistics. |
| Rental-Subscription Hybrid Launch | Toronto production services reduce upfront capital barriers for corporate AV departments. |
| DECT Band Platform Development | Corporate buyers in dense urban environments bypass UHF congestion entirely. |
| Automated Frequency Management Integration | Secondary market operators in Phoenix face steeper white space database burdens. |
Research Methodology
Desk research of FCC equipment authorization databases, Industry Canada spectrum allocation records, and IFT regulatory filings preceded structured interviews with RF engineering directors at touring production houses, broadcast network technical managers, AV rental house inventory planners, and corporate AV procurement leads. Secondary validation drew from SEC 10-K disclosures of heritage audio manufacturers, customs import records for RF semiconductor components, and trade association membership directories. Bottom-up channel checks triangulated against top-down market sizing across frequency band, form factor, and end-use category.
Variance decomposition across product type, technology architecture, application vertical, and end-user archetype shaped the analytical framework over the projection horizon. CAGRs derived from replacement cycle modeling tied to FCC spectrum reallocation deadlines and digital platform adoption S-curves. Industry-specific inputs included RF coordination cost inflation indices and foundry capacity utilization rates for gallium arsenide fabrication.
Forecasts assume regulatory continuity in FCC, Industry Canada, and IFT spectrum management regimes; material policy shifts would require re-modeling. Semiconductor supply concentration and adaptive frequency-hopping certification delays constitute specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Wireless Charger Market
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Public Wi-Fi Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Li-Fi Market
Wireless Technologies
Wimax Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Wireless Communication Equipment Market
Wireless Technologies
Mobile WLAN Access Points Market