
 Wi-Fi Hotspot (Dongle) Market | 2026-2036
Wi-Fi Hotspot (Dongle) Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi Hotspot (Dongle) Market Analytics
The capital-intensity divergence between integrated semiconductor manufacturers and assembly-only OEMs is unwinding competitive stability in the Wi-Fi hotspot dongle sector. Huawei Technologies leverages captive chip design capabilities to sustain margin control across 5G-enabled product lines. NETGEAR competes through channel dominance in North American retail and enterprise distribution. TP-Link anchors its position via manufacturing scale across Shenzhen and Dongguan production clusters.
A Wi-Fi hotspot dongle is a compact, bus-powered peripheral that converts cellular or wired broadband signals into local wireless access, typically operating on 2.4 GHz and 5 GHz bands with throughput ratings up to 1.2 Gbps in Wi-Fi 5 configurations and 2.4 Gbps in Wi-Fi 6 variants. These devices serve mobile professionals, field service teams, and IoT deployments requiring untethered internet access beyond fixed infrastructure reach. The 5G product type segment leads absolute revenue contribution as carriers expand mid-band coverage, while USB dongles retain volume dominance in emerging markets where cost sensitivity shapes procurement. Enterprise end users represent the fastest-expanding demand pool as hybrid work policies institutionalize backup connectivity budgets.
The FCC equipment authorization framework and ETSI harmonized standards in Europe govern radio frequency emissions and interoperability certification, directly determining market access timelines and regional product variant requirements. India's WPC approval process and BIS compulsory registration scheme add compliance layers that favor established players with dedicated regulatory affairs teams. Stakeholders must monitor spectrum reallocation decisions and emerging Wi-Fi 7 certification standards to anticipate chipset sourcing requirements and product refresh cycles.
Market Dynamics
The mid-band 5G spectrum rollout by carriers is compressing product refresh cycles while simultaneously fragmenting chipset sourcing strategies across integrated and fabless suppliers.
Growth Catalysts
- Remote workforce institutionalization:Enterprise IT departments are formalizing backup connectivity budgets as hybrid policies stabilize, creating durable procurement pipelines for portable hardware.
- India's Digital India program:Government digital inclusion mandates are channeling subsidized connectivity hardware into rural educational institutions and small business clusters.
- Wi-Fi 6/6E protocol maturation:The 2.4 Gbps throughput standard is unlocking enterprise IoT deployments requiring high-density device support in field service environments.
Market Restraints
- Silicon supply concentration:Advanced 5G modem fabrication depends on Taiwan-based foundry capacity, exposing procurement timelines to geopolitical disruption risk.
- FCC certification friction:Updated broadband equipment authorization protocols in the United States are extending product launch timelines by 4-6 months for non-vertically integrated vendors.
- Smartphone tethering substitution:Native 5G handset capabilities are displacing USB dongle demand among cost-sensitive consumer segments in emerging markets.
Strategic Opportunities
- Rural India penetration gap:Telecom infrastructure investments in tier-3 cities and agricultural districts remain underserved by fixed broadband, creating white space for solar-powered outdoor hotspot units.
- EU CSRD compliance hardware:Corporate sustainability reporting mandates are creating preference for modular, repairable dongle designs with documented carbon footprints.
- Edge AI convergence:On-device inference chips combined with cellular backhaul are enabling new field analytics applications in construction and logistics verticals.
Industry Challenges
- RF engineering talent scarcity:mmWave antenna design and thermal management expertise concentrates among a narrow pool of semiconductor specialists, inflating compensation costs.
- Multi-band certification complexity:Simultaneous FCC, ETSI, and BIS compliance requires dedicated regulatory affairs teams that strain mid-tier vendor operating budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi Hotspot (Dongle) Market |
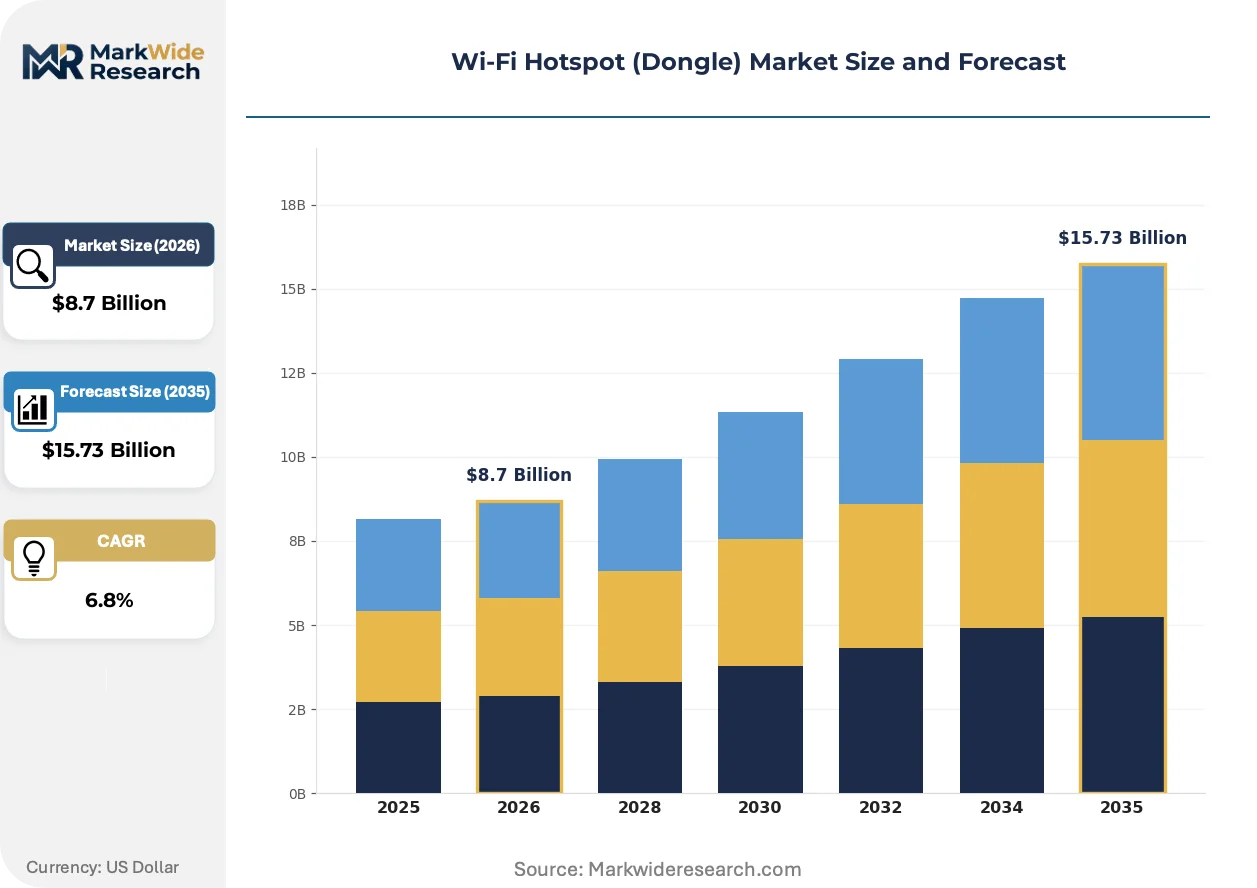
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4G LTE, 5G, Wi-Fi 6, USB Dongles End User: Individuals, Enterprises, Educational Institutions, Government Connection Type: Mobile Network, Satellite, Fixed Wireless, Ethernet Device Compatibility: Laptops, Tablets, Smartphones, IoT Devices |
| Companies Covered | Samsung Electronics, Huawei Technologies, NETGEAR, TCL, Inseego, GlocalMe, TP-Link, GL.iNet, Franklin Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi Hotspot (Dongle) Market Evolving Landscape
Connectivity hardware is pivoting from generic peripherals toward vertical-specific solutions as spectrum allocation and enterprise security requirements diverge across deployment contexts.
Wi-Fi 7 chipset integration is fragmenting the premium product tier as early adopters in financial services and healthcare verticals demand 320 MHz channel bonding and multi-link operation for low-latency applications. Enterprise procurement teams are piloting these units in trading floors and telemedicine command centers despite incomplete carrier certification. The technology is fragmenting vendor tiering by enabling specialist suppliers to compete on raw throughput metrics against established brands with superior distribution.
India's WPC approval process is tightening electromagnetic compatibility testing requirements for imported radio equipment, forcing OEMs to establish local testing partnerships or face 90-day clearance delays. The BIS compulsory registration scheme adds a parallel compliance layer that favors manufacturers with existing Indian subsidiary infrastructure. Small business and education sector tenders now explicitly require dual certification, reshaping competitive entry barriers.
Enterprise buyers are consolidating vendor relationships through managed connectivity contracts that bundle hardware, data plans, and remote diagnostics into per-seat subscriptions. Systems integrators and telecom resellers are displacing direct retail procurement in North American and European accounts. This pattern concentrates most visibly in field service organizations deploying 500+ unit fleets across distributed technician networks.
Wi-Fi Hotspot (Dongle) Market Segmentation
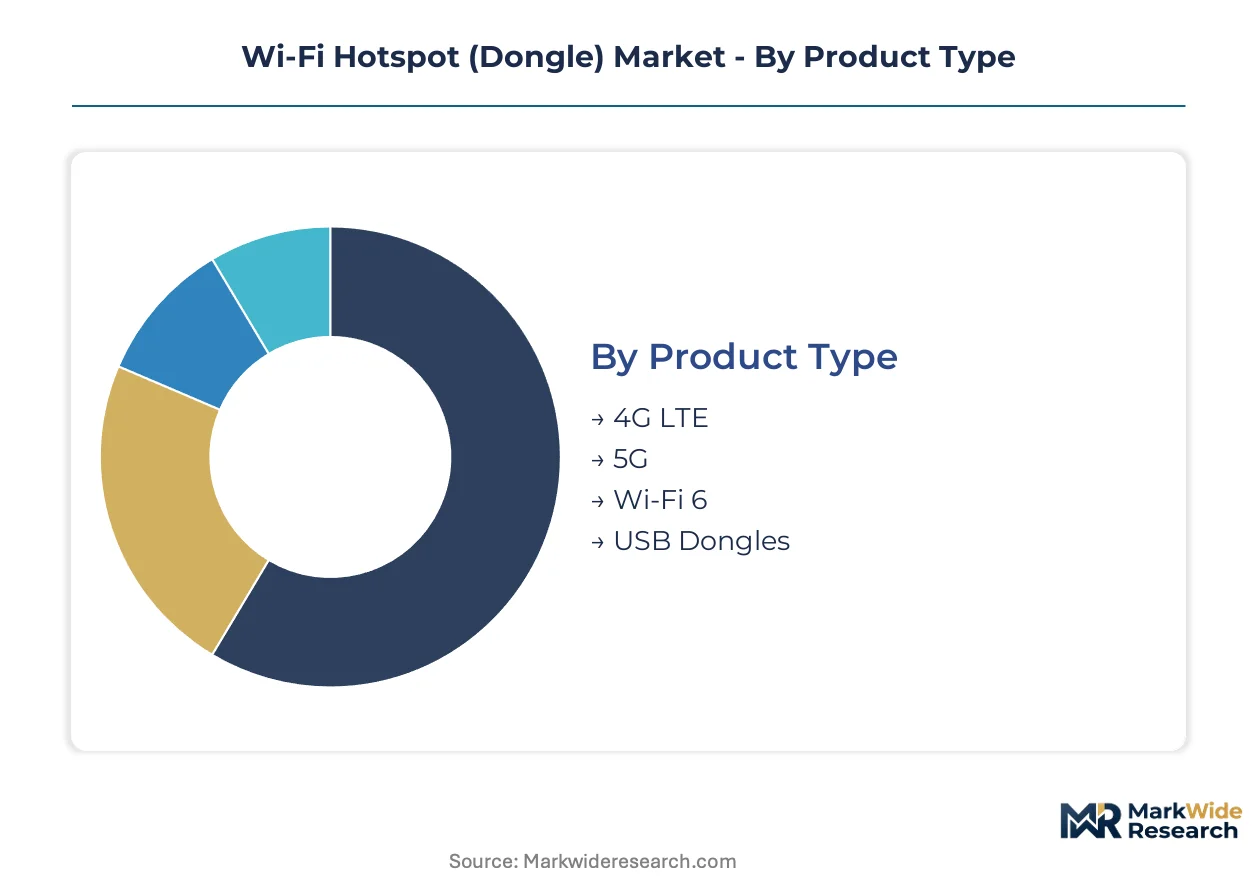
Product differentiation in Wi-Fi hotspot dongles tracks closely with spectrum licensing and certification requirements across target markets. Regulatory fragmentation forces OEMs to maintain parallel SKUs optimized for specific carrier band allocations and national type-approval protocols.
Product Type:
FCC equipment authorization timelines diverge sharply between legacy 4G architectures and emerging 5G mmWave designs, compressing refresh cycles for premium tiers while extending certification windows for budget segments.
- 5G:Mid-band and mmWave modem configurations deliver peak throughputs exceeding 2 Gbps in sub-6 GHz deployments. Enterprise field service fleets in Germany and Japan are standardizing these units as primary connectivity backbones for distributed technician networks.
- Wi-Fi 6:OFDMA and 1024-QAM modulation enable 2.4 Gbps aggregate throughput with support for 100+ concurrent client associations. Healthcare command centers in the United States are piloting these for telemedicine infrastructure requiring deterministic latency.
- 4G LTE:Cat-12 and Cat-16 modem variants dominate emerging market volume where carrier 5G coverage remains sparse.
- USB Dongles:Bus-powered single-band devices retain cost-sensitive consumer penetration in India and Southeast Asia.
Established volume favors USB Dongles; emerging adoption favors 5G.
End User:
Procurement scale and contract structure vary dramatically across customer archetypes, from individual retail purchases to thousand-unit managed service agreements.
- Enterprises:Hybrid work policies have institutionalized backup connectivity budgets across Fortune 500 IT departments. These buyers negotiate multi-year managed service contracts bundling hardware, data plans, and remote diagnostics into per-seat subscriptions.
- Educational Institutions:India's Digital India program channels subsidized hardware into rural schools and vocational training centers. BIS compulsory registration and WPC dual certification requirements now appear explicitly in government tender specifications.
- Individuals:Mobile professionals and digital nomads drive seasonal demand spikes aligned with travel recovery patterns.
- Government:Defense and civilian agencies require FIPS 140-2 encryption compliance and domestic assembly mandates for sensitive deployments.
Enterprise contracts concentrate revenue value; educational tenders concentrate unit volume expansion.
Connection Type:
Backhaul architecture determines thermal design, antenna complexity, and ultimately bill-of-materials cost structure.
- Mobile Network:Cellular-based dongles integrate baseband processors from Qualcomm, MediaTek, or UNISOC depending on target carrier band support. These units dominate portable use cases requiring seamless handoff across macro cell boundaries.
- Satellite:LEO constellation terminals from Starlink and OneWeb partners are emerging for maritime and remote mining applications beyond terrestrial coverage.
- Fixed Wireless:CPE-style devices bridge fiber backhaul to local Wi-Fi distribution for small office deployments.
- Ethernet:Tethered configurations serve stationary IoT gateways in industrial automation settings.
Mobile Network commands installed base; Satellite claims steepest expansion trajectory.
Device Compatibility:
Client ecosystem breadth shapes firmware development investment and antenna tuning requirements.
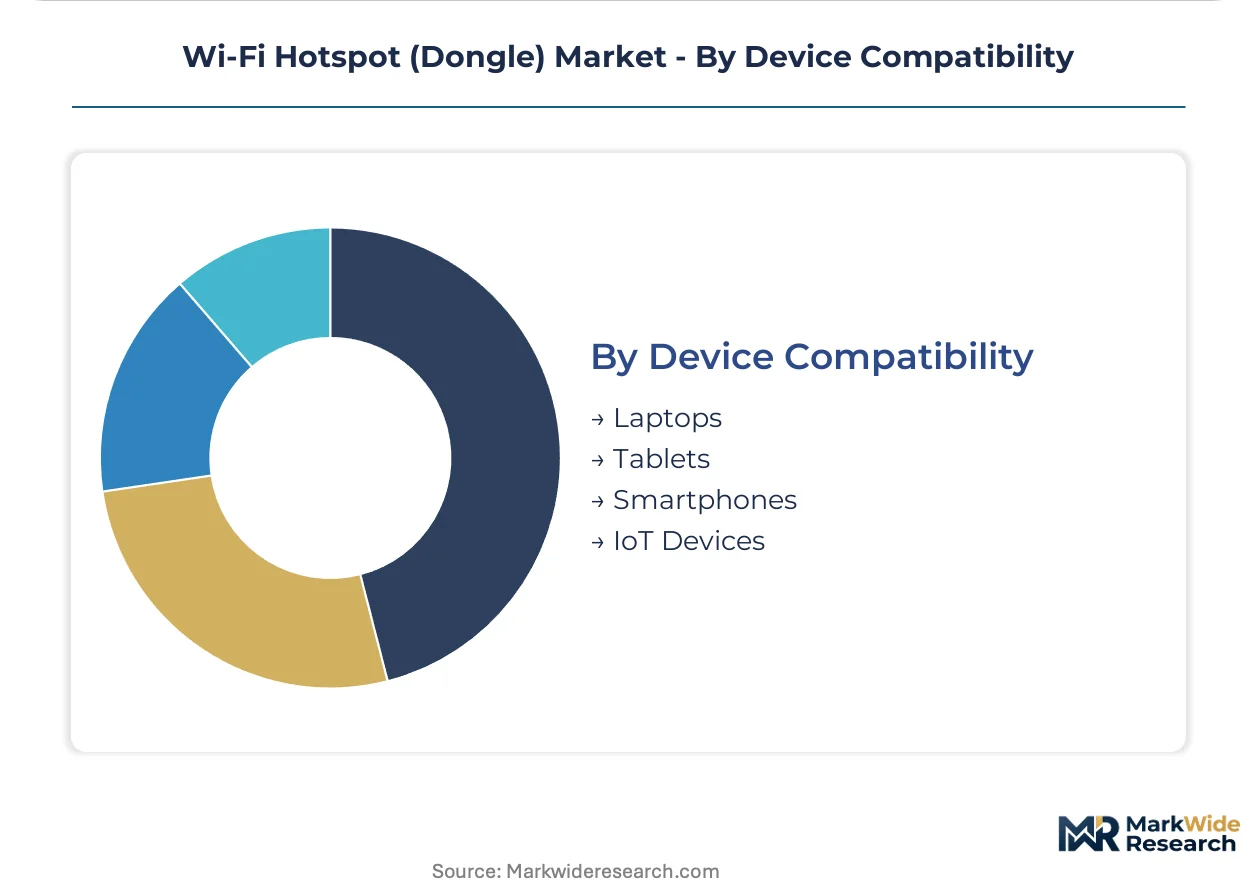
- Laptops:USB-C and Thunderbolt interface standards dominate enterprise procurement specifications. These deployments prioritize driverless plug-and-play compatibility across Windows, macOS, and ChromeOS environments.
- IoT Devices:Machine-to-machine deployments in logistics and construction require extended temperature ranges and hardened enclosures for field durability.
- Tablets:iPad and Android slate compatibility drives consumer retail channel placement.
- Smartphones:Tethering substitution effects compress dedicated dongle demand among handset-native 5G users.
Laptop compatibility anchors enterprise attach rates; IoT Device support unlocks vertical application pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Japan where enterprise buyers absorb premium 5G hardware, while cost-sensitive procurement in India and Indonesia compresses margins for standard-tier suppliers.
United States
Enterprise field service fleets and hybrid work policies drive procurement of managed connectivity bundles. FCC equipment authorization protocols extend product launch timelines for non-vertically integrated vendors. Dallas-Fort Worth hosts distribution centers serving North American enterprise accounts with same-day fulfillment capabilities.
Germany
Industrial IoT deployments in automotive and logistics sectors demand deterministic latency from Wi-Fi 6 and emerging Wi-Fi 7 hardware. ETSI harmonized standards govern radio frequency emissions certification across European market access. Munich anchors enterprise sales operations for Central European manufacturing accounts.
India
Digital India program subsidies channel hardware into rural schools and small business clusters across tier-3 cities. BIS compulsory registration and WPC dual certification requirements now appear explicitly in government tender specifications. Bengaluru hosts testing partnerships helping OEMs navigate 90-day clearance timelines.
Japan
Telemedicine command centers and financial trading floors pilot Wi-Fi 7 units requiring 320 MHz channel bonding. METI standards coordination shapes domestic type-approval protocols for enterprise security requirements. Tokyo-Osaka corridor concentrates demand from precision manufacturing and healthcare verticals.
China
Shenzhen and Dongguan production clusters supply global volume for USB dongle and 4G LTE segments. MIIT radio transmission equipment certification governs domestic market access for cellular-enabled devices. Pearl River Delta integration enables rapid turnaround from chipset sourcing to finished goods export.
Wi-Fi Hotspot (Dongle) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where captive semiconductor design separates premium positioning from assembly-dependent competition. The vendor base spans vertically integrated conglomerates, specialized connectivity hardware firms, and contract manufacturing specialists serving private-label programs. Three archetypes dominate: integrated technology conglomerates with captive chip capabilities, dedicated networking equipment vendors with channel depth, and scale manufacturers optimizing Shenzhen- and Dongguan-based production clusters. M&A activity concentrates on 5G modem IP acquisitions, while strategic partnerships with carrier certification laboratories accelerate regulatory clearance timelines.
Among integrated technology conglomerates, Samsung Electronics and Huawei Technologies exemplify archetypes combining captive semiconductor design with end-product manufacturing, occupying positions where baseband processor ownership insulates margin structures from foundry pricing volatility. NETGEAR anchors the dedicated networking equipment tier with established North American retail and enterprise distribution relationships. TP-Link represents the scale-manufacturing archetype, leveraging Shenzhen and Dongguan production cluster density to serve cost-sensitive segments across emerging markets.
| Leading Market Players |
|---|
| Samsung Electronics |
| Huawei Technologies |
| NETGEAR |
| TCL |
| Inseego |
| GlocalMe |
| TP-Link |
| GL.iNet |
| Franklin Wireless |
| Others |
Value Network & Pricing Analysis
FCC equipment authorization protocols gate both supplier qualification timelines and price differentiation between vertically integrated and assembly-dependent vendors simultaneously. Certification friction compresses margins for non-captive manufacturers while enabling integrated players to command configured-to-order premiums.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise bundles from standard retail SKUs by 40-60% at list. Subscription-based managed connectivity contracts dominate enterprise procurement, with per-seat pricing bundling hardware, data plans, and remote diagnostics. Price differentiation rests on certification grade and volume scale, with FCC and ETSI dual-certified units commanding tier-one positioning. Pricing pressure stems from smartphone tethering substitution in emerging markets, compressing USB dongle margins. Educational institutions in India exhibit highest price sensitivity, while German industrial IoT buyers absorb premium Wi-Fi 6/7 hardware with minimal negotiation.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for 5G baseband processors, while Shenzhen and Dongguan production clusters handle final assembly and antenna integration. Raw material dependencies center on GaAs and GaN substrates for mmWave front-ends, plus high-frequency laminates for PCB stack-ups. Single-source vulnerability concentrates in Taiwan-based foundry capacity for advanced modem silicon. Distribution runs through carrier-certified systems integrators and telecom resellers in North American and European enterprise accounts, displacing direct retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where managed connectivity subscriptions and remote diagnostics layers expand faster than hardware replacement cycles. Recurring revenue per installed unit now exceeds upfront hardware margin for enterprise fleet deployments.
For Market Incumbents: Compound channel control through exclusive distribution agreements with carrier-certified systems integrators. Deepen captive semiconductor design capabilities to insulate margin structures from foundry pricing volatility. Defend against smartphone tethering substitution by embedding edge AI inference chips that enable field analytics applications unavailable on handsets. For New Entrants and Emerging Players: India's WPC certification fast-track partnerships with Bengaluru testing laboratories reduce clearance timelines from 90 days to 45 days for qualified applicants. Target rural educational institutions and tier-3 small business clusters underserved by established vendor direct sales operations. Pursue white-label manufacturing contracts for private-label programs serving European sustainability-mandated procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed networking equipment specialists lacking 5G modem IP portfolios. Long-term viability hinges on backward integration into baseband processor design or exclusive carrier certification relationships. Watch for spectrum reallocation decisions and Wi-Fi 7 certification standard finalization as inflection indicators requiring portfolio recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Certification Partnership | FCC and ETSI dual-certification accelerates enterprise procurement cycles by 4-6 months. |
| Managed Connectivity Bundle Launch | Per-seat subscriptions bundling hardware and data plans lock in multi-year enterprise revenue. |
| Edge AI Chip Integration | On-device inference enables construction and logistics analytics beyond smartphone tethering capabilities. |
| India Testing Infrastructure Investment | Bengaluru laboratory partnerships navigate WPC and BIS dual certification for government tenders. |
| Modular Repairable Design Program | EU CSRD compliance documentation captures sustainability-mandated procurement preference. |
Research Methodology
Operator-level perspectives from enterprise IT procurement officers, carrier certification engineers, OEM regulatory affairs leads, and systems integrator account managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FCC equipment authorization databases, ETSI harmonized standards filings, and carrier capex disclosure documents. Bottom-up unit shipment estimates triangulated against top-down service revenue projections across the analysis window.
Sensitivity analysis tested forecast robustness across spectrum allocation scenarios and foundry capacity utilization assumptions. The modeling framework segmented volume and value by product type, end user archetype, connection architecture, and regional certification cluster. CAGRs derived from regression analysis of historical procurement patterns and projected carrier infrastructure deployment schedules. Inputs included BIS compulsory registration timelines, WPC clearance velocity, and enterprise hybrid work policy institutionalization rates.
Underlying assumptions cover stable geopolitical conditions for Taiwan-based foundry access, with deviation risk concentrated in spectrum reallocation decisions and emerging Wi-Fi 7 certification standard delays. Forecasts reflect these conditions with explicit scenario boundaries. Recalibration cycles align with material shifts in carrier 5G mid-band rollout velocity and regulatory approval protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
France Fixed Wireless Access (FWA) Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Wireless Access Point Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Mobile WLAN Access Points Market
Wireless Technologies
Wireless Telecommunication Services Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Global Bluetooth Audio Codec Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Global Mobile and Wireless Backhaul Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Asia-Pacific Distributed Antenna System Market
Wireless Technologies
Asia-Pacific Wi-Fi 6 Market
Wireless Technologies
Li-Fi Market