
 Mobile Signal Booster Market | 2026-2036
Mobile Signal Booster Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Signal Booster Market Intelligence
FCC Part 20 certification rules is recalibrating the cost-of-entry calculus for signal booster manufacturers seeking US market access. SureCall leverages in-house amplifier design to sustain premium positioning across North American distribution channels. weBoost anchors its competitive stance through deep retail partnerships with major carriers and big-box electronics chains. Wilson specializes in consumer-grade installation simplicity, occupying a distinct niche between professional integrators and DIY residential buyers.
A mobile signal booster is an RF amplification system comprising a donor antenna, bi-directional amplifier, and indoor rebroadcast antenna, typically operating across 700 MHz to 2.7 GHz cellular bands to overcome path loss and building penetration attenuation. The device captures weak outdoor cellular signals, amplifies them by 50–70 dB, and redistributes enhanced coverage to eliminate dead zones in structures or vehicles. Commercial boosters dominate current revenue contribution due to enterprise-scale deployments in hospitals, warehouses, and high-rise offices where carrier-grade DAS alternatives prove cost-prohibitive. 5G-enabled booster architectures represent the fastest-growing technology segment as sub-6 GHz and C-band compatibility requirements reshape R&D roadmaps across the supplier base.
The FCC enforces strict emission limits and carrier-notification protocols under Part 20, while the EU Radio Equipment Directive mandates CE marking and harmonized spectrum compliance for booster sales across member states. India's WPC (Wireless Planning and Coordination Wing) imposes import licensing and frequency authorization requirements that delay product launches by six to twelve months for unprepared vendors. Stakeholders must monitor evolving 5G mid-band spectrum allocations and corresponding national type-approval timelines to avoid stranded inventory in key demand markets.
Market Dynamics
5G mid-band spectrum expansion is compressing product lifecycles as legacy 700 MHz amplifiers face technical obsolescence before depreciation schedules complete. Equipment vendors must now engineer simultaneous sub-6 GHz and C-band compatibility into single hardware platforms to avoid stranded inventory.
Growth Catalysts
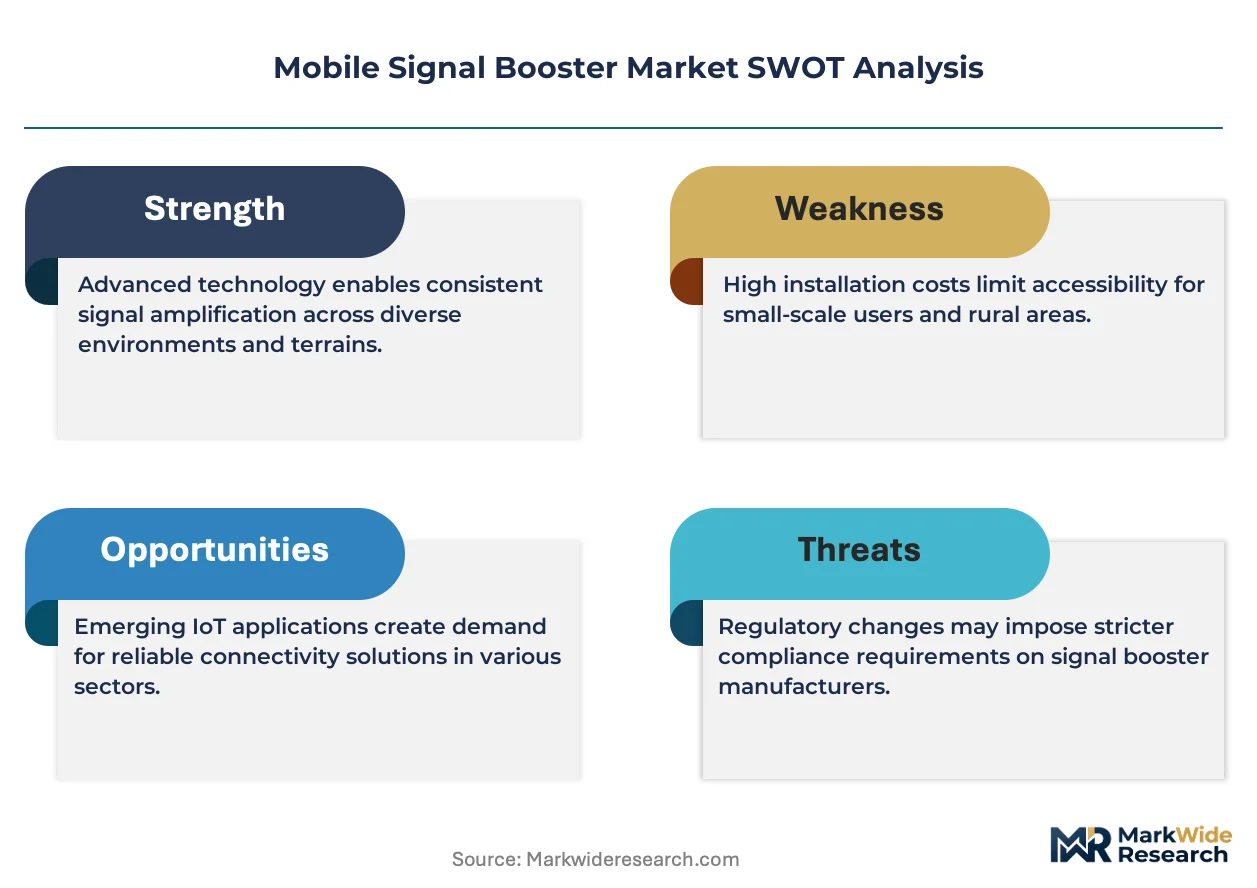
- FCC Part 20 carrier-notification protocols:Streamlined certification pathways accelerate US market entry for compliant manufacturers. Rural healthcare clinics deploy boosters to meet telemedicine connectivity mandates.
- India's tier-2 and tier-3 urban corridors:5G rollout lags behind metropolitan centers, creating coverage gaps that consumer-grade amplification addresses affordably.
- Sub-6 GHz antenna integration:New RF architectures reduce component count while supporting wider frequency ranges, lowering per-unit production costs.
Market Restraints
- India WPC import licensing:Frequency authorization requirements delay product launches by six to twelve months for unprepared vendors, freezing working capital.
- GaN and GaAs semiconductor supply:RF power amplifier chip fabrication concentrates among a handful of foundries, exposing lead times to geopolitical disruption.
- Carrier-grade DAS substitution:Enterprise buyers in dense urban cores increasingly prefer distributed antenna systems for multi-tenant buildings despite higher upfront costs.
Strategic Opportunities
- EU Radio Equipment Directive harmonization:CE marking mutual recognition opens 27-member-state addressable market with single certification investment.
- Vehicle fleet cellular connectivity:Commercial trucking and rail operators seek mobile booster integration for cabin and cargo-area coverage.
- Machine learning interference cancellation:AI-driven spectral analysis enables booster operation in noisier RF environments previously requiring manual tuning.
Industry Challenges
- RF engineering talent scarcity:Specialized microwave design expertise concentrates among legacy defense contractors, constraining vendor R&D scaling.
- Legacy 3G amplifier retrofit complexity:Existing installed base requires costly hardware swaps rather than firmware updates to achieve 5G compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Signal Booster Market |
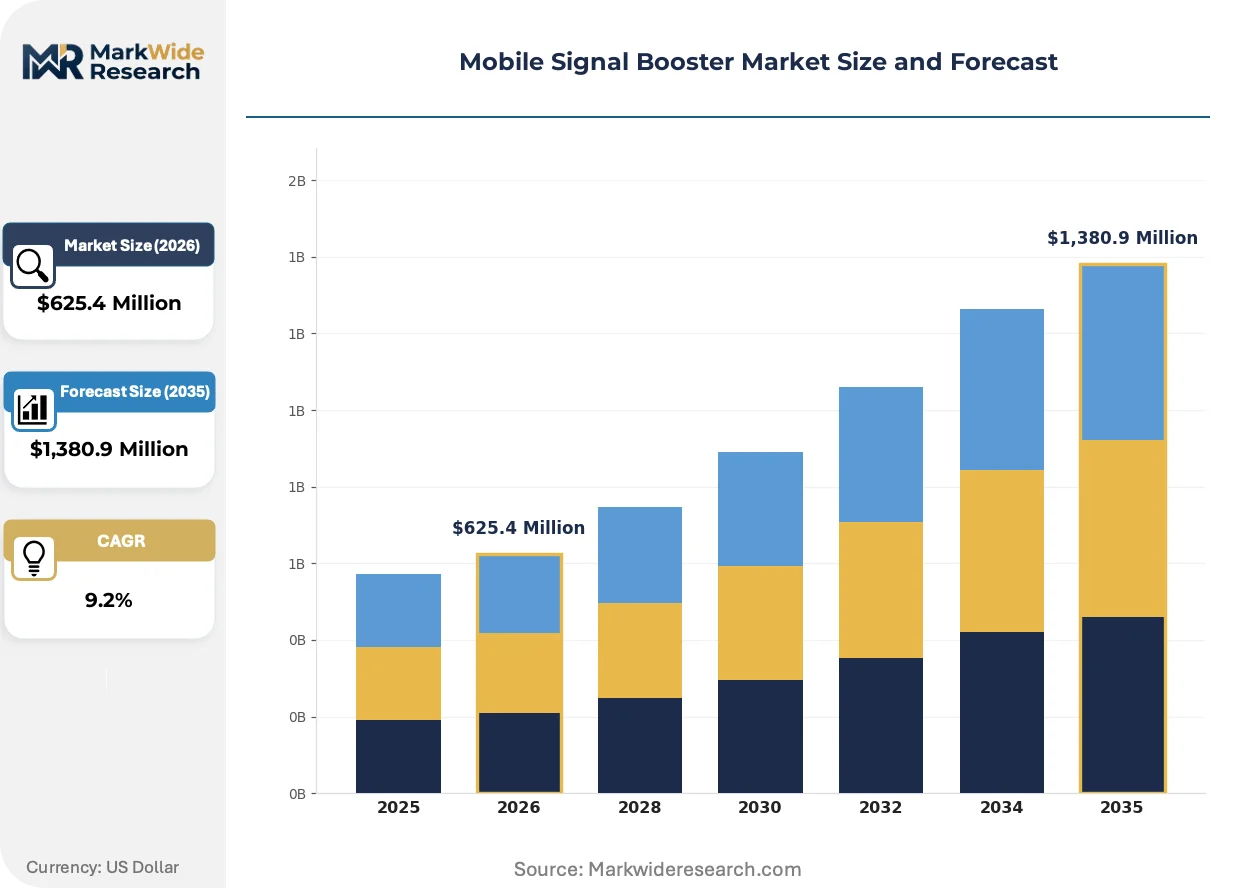
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,380.9 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Boosters, Commercial Boosters, In-Vehicle Boosters, Industrial Boosters, Marine Boosters Technology: 4G LTE, 3G, 5G, CDMA, GSM, DCS Application: Indoor Coverage, Outdoor Coverage, Emergency Communication, Public Venues, Transportation Networks End User: Telecom Operators, Enterprises, Residential Consumers, Government Agencies |
| Companies Covered | SureCall, weBoost, CommScope, Nextivity, HiBoost, Corning, Wilson, CEL-FI, Airspan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Signal Booster Market Strategic Shifts & Innovations
Software-defined amplification architectures are displacing fixed-gain hardware, enabling remote configuration and over-the-air parameter adjustment. This shift compresses installation timelines while expanding addressable use cases beyond static building deployments.
Multi-band digital signal processors are unifying previously separate amplification chains into single hardware units. Warehouse operators and hospital systems adopt these consolidated platforms to reduce rack space and simplify maintenance contracts. The technology is unifying what were three distinct product categories—consumer, commercial, and industrial boosters—into scalable modular architectures.
The EU Radio Equipment Directive's 2024 enforcement amendments tighten electromagnetic compatibility testing for booster emissions. Manufacturers serving European distribution channels now embed pre-certification testing into design cycles rather than treating compliance as a final-stage gate. Medical device integrators face the steepest adaptation burden as their dual CE-MDR obligations compound documentation requirements.
Enterprise buyers increasingly specify outcome-based connectivity service contracts rather than capital equipment purchases. System integrators respond by bundling booster hardware with performance-guaranteed maintenance subscriptions. This model penetrates fastest among US hospital networks where operating lease accounting aligns with capital constraint pressures.
Mobile Signal Booster Market Segmentation
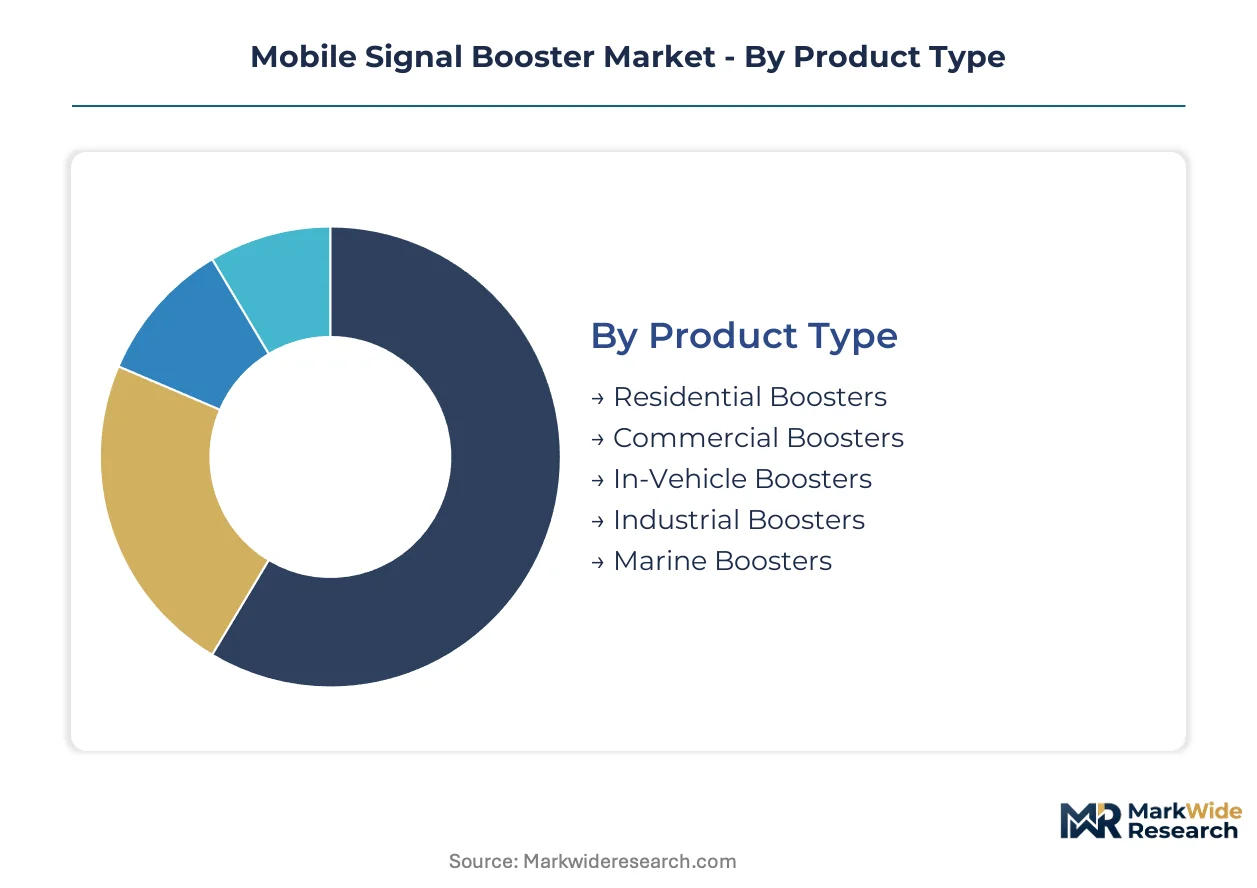
Signal booster procurement hinges on distinct buyer priorities across product tiers, frequency compatibility, and deployment environments. Each segmentation dimension reveals divergent margin structures and regulatory exposure that reshape vendor portfolio strategy.
Product Type:
Buyers select amplification hardware based on coverage footprint requirements and installation complexity tolerance.
- Residential Boosters:Compact plug-and-play units deliver 50–70 dB gain for single-family homes and small apartments. Demand clusters in India's tier-2 and tier-3 urban corridors where 5G rollout lags metropolitan centers and consumers seek affordable coverage solutions.
- Commercial Boosters:Rack-mounted systems with multi-carrier support serve hospitals, warehouses, and high-rise offices where carrier-grade DAS alternatives prove cost-prohibitive. FCC Part 20 certification requirements elevate compliance costs for new market entrants targeting US healthcare networks.
- In-Vehicle Boosters:DC-powered mobile units maintain connectivity for commercial trucking fleets and passenger rail operators traversing cellular dead zones.
- Industrial Boosters:Hardened enclosures withstand temperature extremes and vibration in manufacturing plants and mining operations.
- Marine Boosters:Saltwater-resistant antenna systems support offshore vessels and coastal shipping routes requiring continuous communication links.
Volume sits with Commercial Boosters; growth tilts toward In-Vehicle Boosters.
Technology:
Frequency band compatibility determines hardware obsolescence risk and R&D amortization timelines.
- 5G:Sub-6 GHz and C-band architectures unify amplification chains into single hardware platforms. Equipment vendors engineer simultaneous mid-band compatibility to avoid stranded inventory as spectrum allocations evolve.
- 4G LTE:Mature 700 MHz–2.7 GHz amplifiers retain installed base relevance in emerging markets where network modernization proceeds gradually.
- 3G:Legacy platforms face technical obsolescence before depreciation schedules complete, forcing costly hardware swaps rather than firmware updates.
- CDMA:Specialized units address residual North American carrier networks transitioning to VoLTE.
- GSM:900/1800 MHz systems sustain demand across African and South Asian markets with slower 4G migration.
- DCS:1800 MHz-specific amplification serves European and Middle Eastern corridors with concentrated GSM infrastructure.
Revenue concentrates in 4G LTE; expansion accelerates most steeply in 5G.
Application:
Deployment environment dictates antenna configuration, weatherproofing specifications, and regulatory notification protocols.
- Indoor Coverage:Bi-directional amplifier systems with distributed rebroadcast antennas eliminate building penetration attenuation in concrete and steel structures. Enterprise buyers increasingly specify outcome-based connectivity service contracts rather than capital equipment purchases.
- Outdoor Coverage:High-gain donor antennas and ruggedized enclosures withstand environmental exposure for remote infrastructure and agricultural operations.
- Emergency Communication:Priority-access amplifiers ensure first responder connectivity during network congestion events.
- Public Venues:Stadium and convention center deployments require carrier coordination under FCC Part 20 notification rules.
- Transportation Networks:Tunnel and railway systems integrate mobile boosters with leaky feeder cable architectures for continuous coverage.
Deployment value pools in Indoor Coverage; Public Venues climb the fastest.
End User:
Procurement authority and technical sophistication separate enterprise-scale buyers from consumer self-installation.
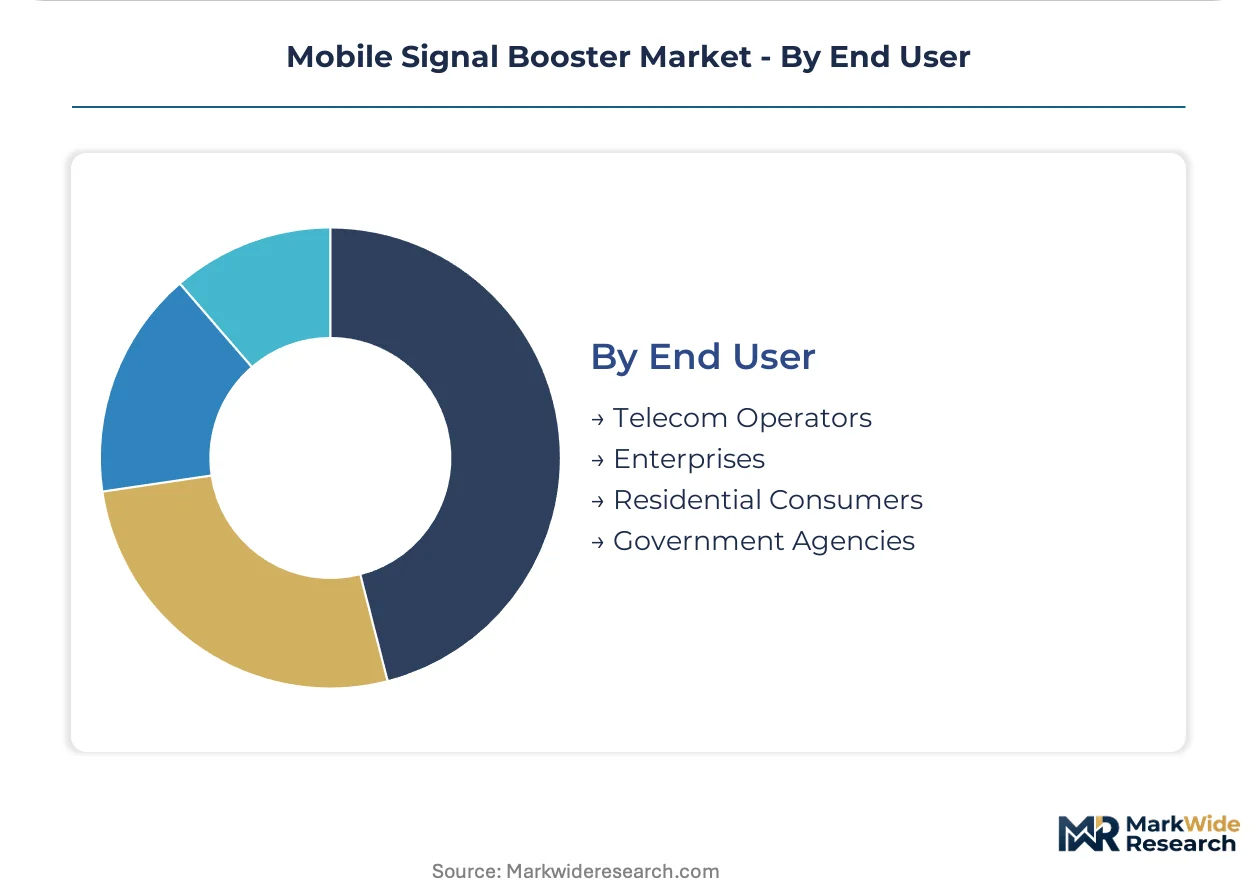
- Telecom Operators:Carrier-direct deployments leverage wholesale hardware partnerships and centralized network management platforms. India's WPC import licensing delays product launches by six to twelve months for unprepared vendors supplying operator channels.
- Enterprises:Hospital networks and warehouse operators adopt consolidated multi-band digital signal processors to reduce rack space and simplify maintenance contracts.
- Residential Consumers:DIY installation preference drives demand for consumer-grade simplicity occupying the niche between professional integrators and complex commercial systems.
- Government Agencies:Defense and public safety procurement mandates domestic content requirements and classified facility clearance protocols.
Spend concentrates among Enterprises; Government Agencies gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Dongguan concentrate RF component manufacturing, while India's Software Technology Parks of India scheme drives assembly operations in Bengaluru and Hyderabad. These zones attract mobile signal booster producers through tax holidays and duty exemptions on imported semiconductor substrates.
United States
Rural healthcare clinics in Montana and Alaska deploy boosters to meet telemedicine connectivity mandates from CMS reimbursement rules. FCC Part 20 carrier-notification protocols streamline certification for compliant manufacturers. Dallas-Fort Worth anchors distribution networks serving hospital systems across the Southwest.
India
Tier-2 and tier-3 urban corridors in Uttar Pradesh and Madhya Pradesh generate consumer-grade demand where 5G rollout lags metropolitan centers. WPC import licensing and frequency authorization requirements delay product launches by six to twelve months for unprepared vendors. Hyderabad's electronics manufacturing clusters absorb working capital from certification backlogs.
Germany
Industrial automation corridors in Bavaria and Baden-Württemberg specify hardened booster enclosures for manufacturing plant connectivity. EU Radio Equipment Directive harmonization enables CE marking mutual recognition across 27 member states. Munich's Mittelstand engineering firms integrate boosters into Industry 4.0 retrofit contracts.
China
Sub-6 GHz infrastructure buildouts in the Yangtze River Delta and Pearl River Delta compress product lifecycles for legacy amplifier vendors. MIIT spectrum allocation timelines for C-band reshape R&D roadmaps among domestic suppliers. Shenzhen's RF foundries supply GaN power amplifier chips to regional booster assemblers.
United Kingdom
Transportation network operators in the Midlands and Scotland integrate mobile boosters with leaky feeder architectures for tunnel coverage. Ofcom's shared spectrum framework governs booster emissions in rail corridors. Birmingham's systems integrators bundle hardware with performance-guaranteed maintenance subscriptions for NHS trusts.
Mobile Signal Booster Market Key Industry Players
North American producers anchor one tier; Asia-Pacific specialists hold component supply leverage. The vendor base stratifies across three tiers: integrated RF design houses, retail-brand distributors, and contract assemblers serving operator channels. Strategic archetypes include in-house amplifier designers, carrier-partnered brands, and installation-simplicity specialists. Competitive moves concentrate on FCC Part 20 pre-certification investments and multi-band hardware consolidation to avoid stranded inventory.
Within the integrated design tier, SureCall and weBoost exemplify divergent positioning strategies. SureCall occupies a premium position through captive amplifier engineering capabilities. weBoost anchors retail distribution through carrier partnerships and big-box electronics channel access. Wilson sits between professional integrators and DIY residential buyers, representing the installation-simplicity archetype. These three entities collectively illustrate how vendor positioning maps to buyer sophistication and procurement authority across enterprise, consumer, and operator segments.
| Leading Market Players |
|---|
| SureCall |
| weBoost |
| CommScope |
| Nextivity |
| HiBoost |
| Corning |
| Wilson |
| CEL-FI |
| Airspan |
| Others |
Cost & Logistics Intelligence
Enterprise hospital networks and warehouse operators concentrate procurement authority, anchoring contract-based long-term offtake agreements that bundle hardware with performance-guaranteed maintenance subscriptions. This buyer concentration tilts pricing power toward vendors with captive amplifier engineering capabilities and multi-band certification portfolios.
Pricing Analysis
Premium pricing attaches to sub-6 GHz and C-band compatible units with sub-twelve-week lead times, while spot inventory of legacy 700 MHz amplifiers trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates FCC Part 20 pre-certified systems from CE-marked-only variants and uncertified gray-market units. Cost compression in consumer-grade residential boosters intensifies because India's tier-2 and tier-3 demand pulls volume toward price-sensitive DIY installers rather than enterprise integrators.
Supply Chain Analysis
Freight costs from Shenzhen and Dongguan Special Economic Zones to North American distribution hubs consume margin on low-density amplifier enclosures. GaN power amplifier chip fabrication concentrates in Taiwan, South Korea, and domestic China foundries. RF component sourcing rests on gallium nitride substrates and ceramic antenna substrates vulnerable to single-source vulnerability in semiconductor foundry capacity. Distribution runs through Dallas-Fort Worth logistics clusters serving US hospital networks and Bengaluru electronics corridors supplying Indian operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile signal booster market functions as a vertical-integration race where captive GaN amplifier design and in-house RF engineering determine margin sustainability. Players pursuing backward integration into semiconductor foundry partnerships or forward integration into outcome-based service contracts capture structural advantage.
For Market Incumbents: Cement multi-band hardware consolidation to avoid stranded inventory as 5G mid-band spectrum allocations evolve across the US, EU, and India. Lock in exclusive distribution partnerships with major carrier retail channels before emerging entrants achieve FCC Part 20 certification. Carrier-grade DAS substitution in dense urban cores threatens enterprise booster margins; respond with outcome-based connectivity service contracts that align hospital network procurement with operating lease accounting preferences. For New Entrants and Emerging Players: Direct-to-installer digital channels bypass incumbent retail shelf dominance and compress customer acquisition costs for unprepared vendors facing WPC import licensing delays. Target India's tier-2 and tier-3 urban corridors where 5G rollout lags metropolitan centers and consumer-grade amplification addresses affordable coverage gaps. Lead with software-defined amplification architectures enabling remote configuration to differentiate from fixed-gain legacy hardware. For Investors and Strategic Acquirers: Distressed-cycle entries favor RF engineering talent-scarce mid-cap specialists with captive amplifier design capabilities in North American and European geographies. Long-term viability over the next decade hinges on 5G sub-6 GHz and C-band certification breadth rather than legacy 4G LTE installed base maintenance. Monitor FCC Part 20 carrier-notification protocol amendments as the inflection signal for regulatory compliance cost recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Band Hardware Consolidation | Unifies sub-6 GHz and C-band amplification into single platforms for US hospital networks. |
| FCC Part 20 Pre-Certification Investment | Accelerates US market entry before WPC import licensing delays freeze Indian competitor working capital. |
| Outcome-Based Service Contract Bundling | Aligns with NHS trust and US hospital network operating lease accounting constraints. |
| GaN Foundry Partnership | Secures RF power amplifier chip supply against Taiwan and South Korea foundry concentration risk. |
| Software-Defined Amplification Architecture | Enables remote parameter adjustment for warehouse operators and rail tunnel deployments. |
Research Approach
Independent corroboration across RF component suppliers, hospital network procurement managers, and carrier retail channel directors underwrites the qualitative findings. Primary interviews with booster system integrators, FCC certification consultants, and Indian WPC licensing specialists combined with secondary validation from FCC equipment authorization databases, EU Radio Equipment Directive harmonized standards filings, and Indian DGFT import-export records. Bottom-up triangulation across product tier shipment estimates and top-down validation against enterprise connectivity expenditure surveys anchored market sizing.
Comparable historical reference periods spanning legacy 3G amplifier replacement cycles and 4G LTE deployment waves anchored the projection horizon. The analytical framework modeled segmentation across product type, frequency band compatibility, deployment environment, and end-user procurement authority. CAGRs derived from equipment vendor revenue disclosures and carrier infrastructure capex patterns across the analysis window. Sub-6 GHz spectrum allocation timelines and national type-approval certification backlogs served as industry-specific forecast inputs.
The model holds under stable FCC Part 20 and EU Radio Equipment Directive enforcement regimes; deviation in 5G mid-band spectrum auction timing or WPC import licensing processing duration would shift vendor inventory positioning and working capital requirements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
Wireless Intercoms Market
Wireless Technologies
France Fixed Wireless Access (FWA) Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Wimax Market
Wireless Technologies
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
5G Wireless Ecosystem Market