
 LTE and 5G Market | 2026-2036
LTE and 5G Market Size, Share, and Industry Trends Forecast 2026-2036
LTE and 5G Market Foresight
The FCC's spectrum reallocation framework is recalibrating infrastructure economics for mid-band 5G rollouts. Huawei Technologies Co., Ltd. leverages its integrated baseband-to-antenna portfolio to dominate turnkey deployments across emerging markets. Samsung Electronics Co., Ltd. anchors its position through captive semiconductor supply and vRAN specialization. Qualcomm Incorporated differentiates via modem-RF system integration that sustains premium licensing across Android ecosystems.
LTE and 5G encompass cellular radio access technologies operating from sub-1 GHz through millimeter-wave frequencies, with 5G NR specifying subcarrier spacings of 15-240 kHz and latency targets below one millisecond for ultra-reliable low-latency communication. These technologies enable broadband connectivity, industrial automation, and mission-critical communications across consumer, enterprise, and public safety domains. Public network deployments retain the largest revenue pool but face margin compression from infrastructure commoditization, while private network installations command premium pricing due to site-specific spectrum licensing and customized quality-of-service guarantees. Massive MIMO arrays represent the fastest-expanding technology segment as 64T64R and 128T128R configurations become standard for dense urban capacity.
The European Telecommunications Standards Institute, 3GPP, and national regulators including the FCC and Ofcom govern spectrum allocation, equipment certification, and cross-border roaming frameworks that determine vendor market access and operator deployment timelines. Open RAN security requirements from NIST and EU cybersecurity certification schemes are reshaping procurement criteria and supplier qualification processes. Stakeholders must monitor spectrum auction calendars and O-RAN conformance testing milestones to align capital deployment with regulatory windows.
Market Dynamics
Open RAN interoperability mandates are fragmenting vendor ecosystems and forcing infrastructure operators to diversify supply chains away from single-source radio access network dependencies.
Growth Catalysts
- Private 5G spectrum frameworks:Regulators in Germany and South Korea have released localized licensing regimes that enable factory operators to deploy captive networks for industrial automation without competing for public spectrum.
- Massive MIMO densification:64T64R and 128T128R antenna configurations are becoming standard equipment for urban capacity expansion, pulling demand for baseband processing hardware and RF front-end components.
- Industrial corridor state backing:China's infrastructure spending prioritizes 5G-enabled automation zones, concentrating equipment procurement in manufacturing belts around Shenzhen, Suzhou, and Chongqing.
Market Restraints
- Semiconductor supply concentration:Advanced node chip fabrication for baseband processors remains concentrated among Taiwan-based foundries, exposing equipment vendors to geopolitical supply disruption.
- Millimeter-wave propagation limits:Sub-6 GHz spectrum saturation forces operators toward 28 GHz and 39 GHz bands where signal attenuation through building materials requires dense small-cell deployment.
- EU cybersecurity certification delays:The EU Cybersecurity Act's pending EN 303 645 harmonized standards for radio equipment are stretching procurement timelines for Open RAN deployments.
Strategic Opportunities
- Smart manufacturing captive networks:Automotive and semiconductor fabs in Bavaria and Gyeonggi Province are commissioning private 5G installations with guaranteed quality-of-service SLAs for robotic control systems.
- Mid-band spectrum reallocation:The FCC's 3.45-3.55 GHz auction framework is opening fresh capacity for rural broadband expansion, creating equipment refresh cycles among regional carriers.
- AI-driven network optimization convergence:Machine learning inference at the network edge is merging with radio resource management, enabling predictive handoff and dynamic spectrum allocation.
Industry Challenges
- Multi-vendor integration complexity:Open RAN disaggregation requires operators to certify interoperability across radio units, distributed units, and centralized units from different suppliers, extending deployment timelines.
- RF engineering talent scarcity:The shift from hardware-centric to software-defined radio architectures demands expertise in both antenna physics and cloud-native orchestration that crosses traditional telecom skill boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LTE and 5G Market |
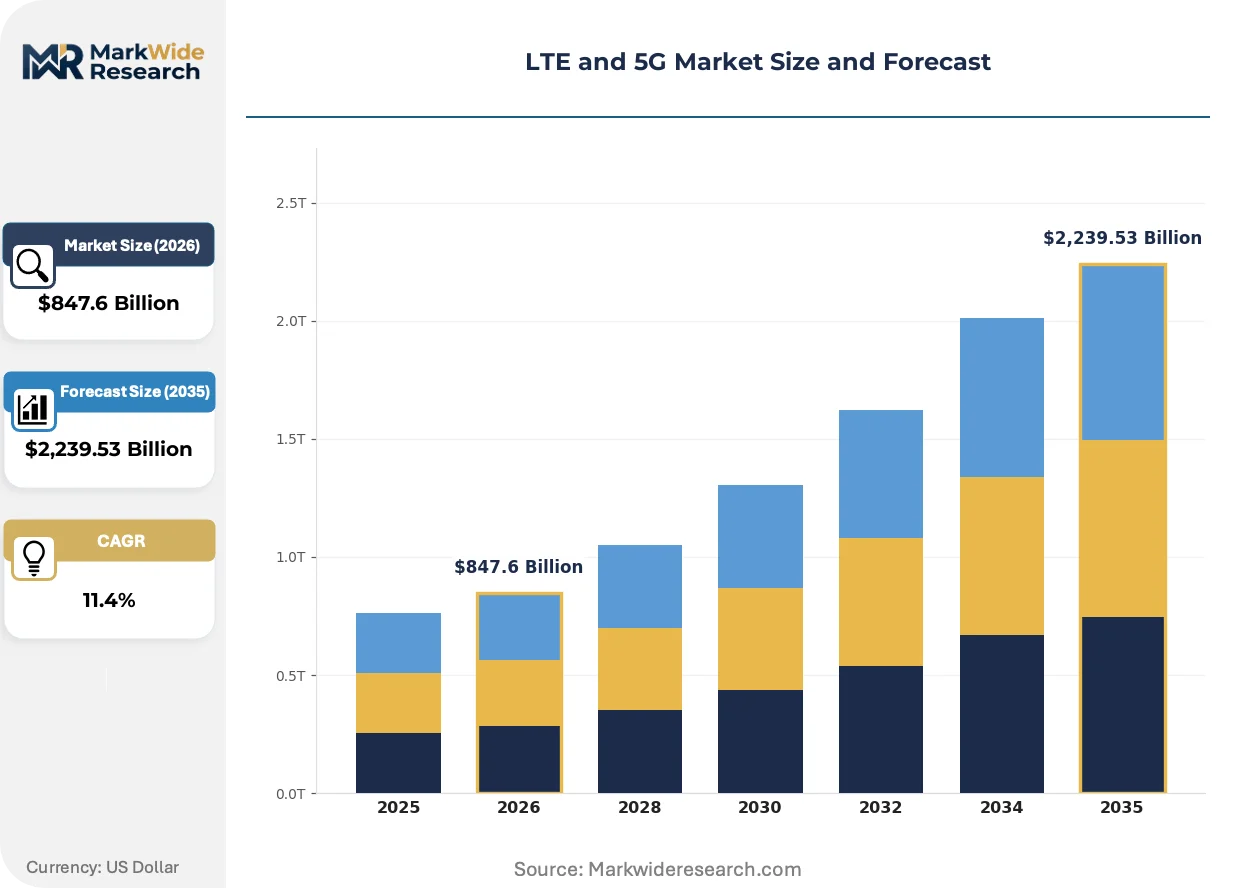
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $2,239.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Network, Private Network, Hybrid Network, Dedicated Network Technology: NR, LTE Advanced, LTE, Massive MIMO End User: Telecom Operators, Enterprises, Government, IoT Providers Service Type: Data Services, Voice Services, Video Services, Messaging Services |
| Companies Covered | Huawei Technologies Co., Ltd., Telefonaktiebolaget LM Ericsson, Nokia, Samsung Electronics Co., Ltd., ZTE Corporation, Qualcomm Incorporated, AT&T Inc., NEC Corporation, KT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LTE and 5G Market Shifts & Advancements
Radio access technology is bifurcating between high-performance public networks and specialized private installations, with software-defined architectures displacing purpose-built hardware across both paths.
Virtualized RAN (vRAN) is expanding into containerized baseband functions running on commercial off-the-shelf servers. Tier-one operators in Japan and the United States are deploying centralized RAN pools that consolidate signal processing for hundreds of cell sites. This compression of hardware diversity is expanding into new procurement models where operators lease compute capacity rather than owning dedicated network equipment.
The FCC's spectrum reallocation framework for mid-band 5G is compressing infrastructure economics for rural carriers. The 2.5 GHz and 3.45 GHz band openings are forcing equipment vendors to support wider channel bandwidths and new carrier aggregation combinations. Regional operators in the Midwest and Mountain West are responding by accelerating base station upgrades to capture coverage gaps left by national carriers.
Enterprise procurement of network equipment is consolidating through systems integrators rather than direct vendor relationships. Manufacturing and logistics buyers in Germany's Ruhr industrial cluster are contracting turnkey private 5G deployments that bundle spectrum licensing, equipment installation, and managed services into single agreements. This bundling is most visible in automotive supply chain facilities where production downtime costs justify premium pricing for guaranteed latency performance.
LTE and 5G Market Segmentation
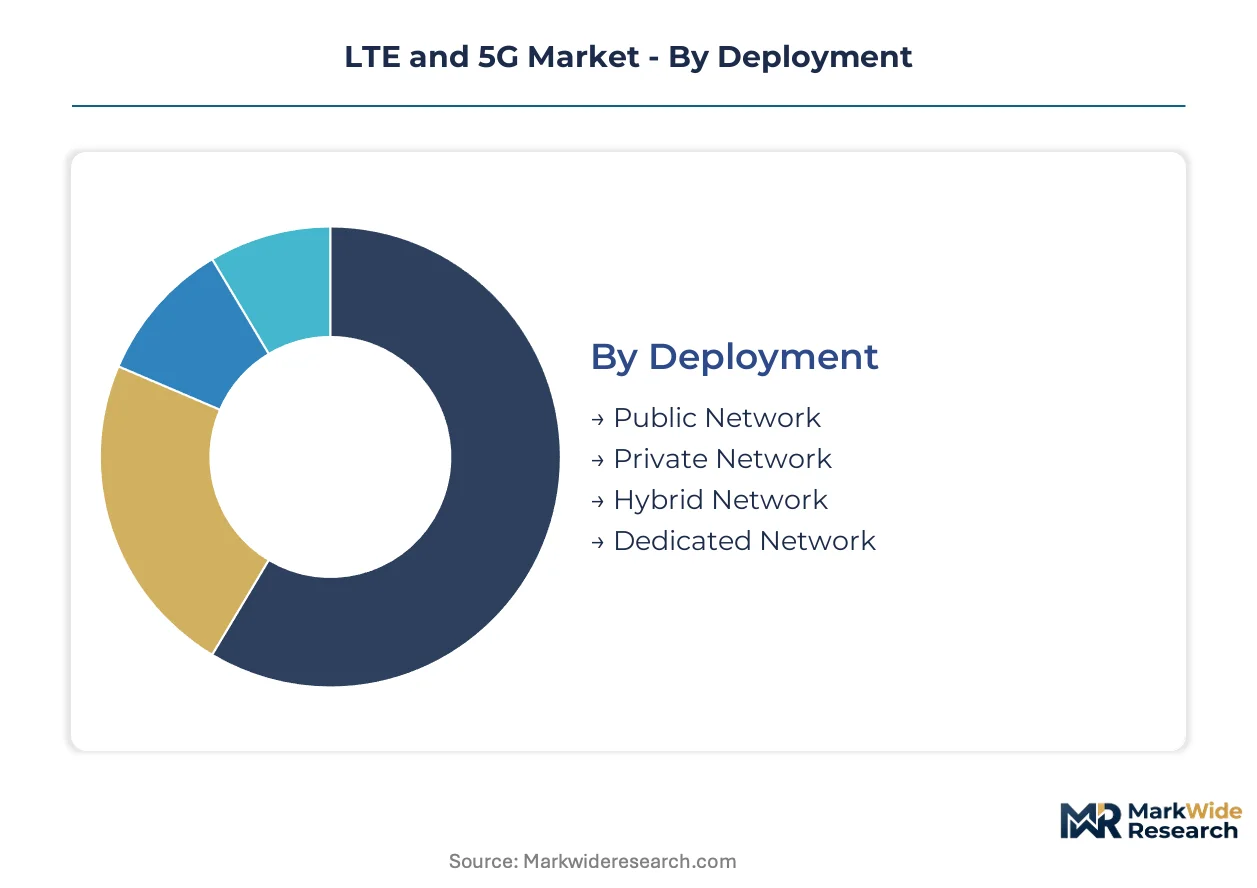
Segmentation in the LTE and 5G market reveals distinct procurement patterns between scale-driven public infrastructure and premium-priced private installations. Understanding these divides enables equipment vendors to align R&D investment with margin profiles and deployment timelines.
Deployment:
Volume concentration sits with public network rollouts while premium pricing attaches to site-specific captive installations.
- Public Network:Wide-area coverage infrastructure serving consumer and enterprise subscribers through licensed spectrum blocks. Mobile network operators in Germany, South Korea, and China are densifying urban macro sites with 64T64R configurations to manage traffic loads from video streaming and cloud applications.
- Private Network:Captive spectrum deployments offering guaranteed quality-of-service for industrial automation and mission-critical control. Automotive fabs in Bavaria and semiconductor facilities in Gyeonggi Province are commissioning these installations to support robotic control systems with sub-millisecond latency requirements.
- Hybrid Network:Architectures combining public infrastructure with dedicated capacity slices for enterprise priority traffic. Mining operations in Western Australia and port logistics hubs in Rotterdam are adopting this model to balance coverage breadth with performance isolation.
- Dedicated Network:Fully isolated infrastructure for public safety and defense applications with hardened security requirements. First responder agencies and critical infrastructure operators are procuring these deployments under specialized spectrum allocations that bypass commercial operator dependencies.
Mature deployment sits with Public Network. Newer deployment is concentrated in Private Network.
Technology:
Technology selection tracks the transition from established LTE capacity layers to 5G NR greenfield construction with Massive MIMO anchoring urban densification.
- NR:5G New Radio specifying subcarrier spacings from 15 kHz to 240 kHz across sub-6 GHz and millimeter-wave bands. Equipment vendors are prioritizing NR development for mid-band spectrum auctions in the United States and industrial corridor deployments in China's manufacturing belts.
- LTE Advanced:Carrier aggregation and enhanced MIMO extensions of fourth-generation standards sustaining subscriber connectivity during 5G migration. Rural carriers in the Midwest and Mountain West are extending LTE Advanced equipment life cycles through software upgrades rather than full hardware replacement.
- LTE:Legacy fourth-generation infrastructure providing baseline broadband coverage in emerging markets and remote geographies. Operators in Southeast Asia and sub-Saharan Africa are continuing LTE deployments where 5G spectrum remains unallocated or device ecosystems are immature.
- Massive MIMO:Antenna arrays with 64 or more transceiver elements enabling spatial multiplexing and beamforming gains. Urban centers in Tokyo, New York, and London are standardizing on 128T128R configurations for stadium and transit hub capacity.
Massive MIMO is climbing the fastest as operators confront sub-6 GHz saturation in dense metropolitan markets.
End User:
Procurement authority is fragmenting from traditional telecom operators toward enterprise buyers with captive spectrum rights and specialized performance requirements.
- Telecom Operators:Licensed mobile network providers deploying wide-area infrastructure under national spectrum allocations. Tier-one operators in Japan and the United States are consolidating baseband processing through centralized RAN pools spanning hundreds of cell sites.
- Enterprises:Manufacturing, logistics, and energy sector buyers procuring private installations with guaranteed service levels. Germany's Ruhr industrial cluster is seeing manufacturing buyers contract turnkey deployments bundling spectrum licensing, equipment, and managed services.
- Government:Public sector agencies requiring secure, resilient communications for emergency response and defense applications. National regulators are reserving spectrum blocks for government priority access during network congestion events.
- IoT Providers:Specialized connectivity aggregators serving distributed sensor networks and machine-to-machine applications. Smart grid operators and agricultural monitoring services are driving demand for low-power wide-area configurations within LTE and 5G standards.
Telecom Operators retain the largest procurement volume. Enterprises are gaining share fastest as localized spectrum frameworks proliferate.
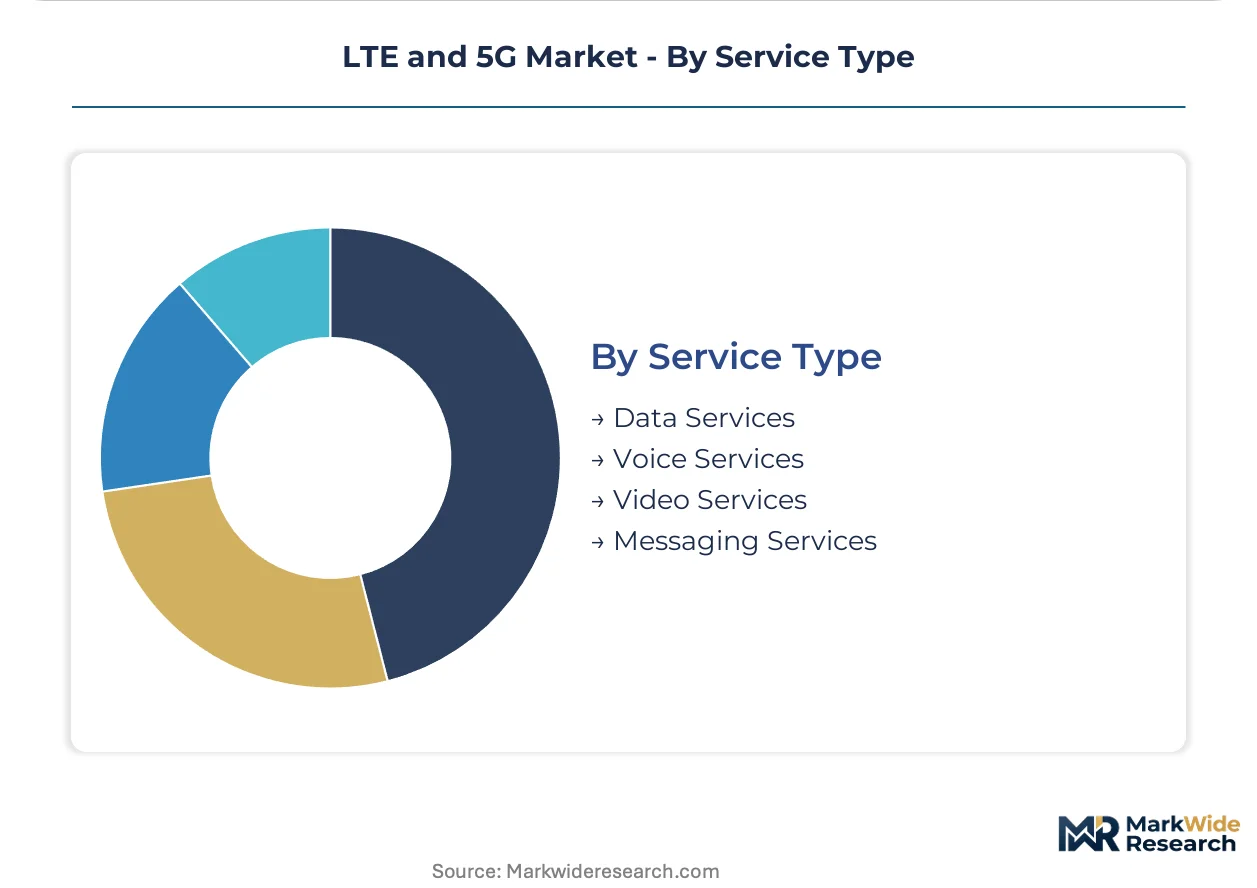
Service Type:
Revenue composition is shifting from voice-centric legacy bundles toward data-intensive applications with video commanding disproportionate bandwidth consumption.
- Data Services:Broadband internet access and cloud connectivity representing the dominant traffic category. Streaming platforms, enterprise SaaS migration, and connected vehicle telemetry are expanding per-subscriber data consumption in urban corridors.
- Voice Services:Circuit-switched and VoLTE voice connectivity with declining revenue per user but persistent quality requirements. Public safety networks and rural subscriber bases maintain voice service priority despite industry-wide data transition.
- Video Services:Live streaming, video conferencing, and surveillance applications driving peak capacity engineering. Stadium venues and transit hubs in Seoul and Singapore are dimensioning Massive MIMO deployments specifically for concurrent 4K video uploads.
- Messaging Services:SMS, RCS, and machine-to-machine signaling traffic with stable volume but compressed pricing. IoT authentication and critical alert systems are sustaining messaging service relevance in enterprise and government segments.
Voice Services represent the most mature revenue category. Video Services are expanding most quickly as immersive and real-time formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's special economic zone status concentrates 5G equipment manufacturing, drawing component suppliers and systems integrators into clustered production corridors. State-backed infrastructure bonds in China's industrial belt accelerate automation deployments. Germany's Industrie 4.0 tax incentives pull private network investment toward Bavarian manufacturing zones.
United States
Regional carriers in the Midwest and Mountain West accelerate base station upgrades to capture coverage gaps left by national operators. The FCC's 3.45-3.55 GHz auction framework opens fresh mid-band capacity for rural broadband expansion. Stadium venues and transit hubs in New York standardize on 128T128R Massive MIMO configurations for concurrent 4K video uploads.
China
Manufacturing belts around Shenzhen, Suzhou, and Chongqing concentrate equipment procurement for 5G-enabled automation zones. MIIT spectrum allocation prioritizes industrial corridor deployments over consumer coverage expansion. State-backed infrastructure spending in the Yangtze River Delta pulls demand for integrated baseband-to-antenna systems.
Germany
Automotive and semiconductor fabs in Bavaria commission private 5G installations with guaranteed quality-of-service SLAs for robotic control systems. Localized licensing regimes enable factory operators to deploy captive networks without competing for public spectrum. The Ruhr industrial cluster sees manufacturing buyers contract turnkey deployments bundling spectrum licensing, equipment, and managed services.
South Korea
Semiconductor facilities in Gyeonggi Province drive demand for sub-millisecond latency networks supporting precision manufacturing. Regulators have released localized spectrum frameworks that accelerate private network deployment timelines. Smart manufacturing facilities anchor private 5G installations with site-specific performance guarantees.
Japan
Tier-one operators consolidate baseband processing through centralized RAN pools spanning hundreds of cell sites in the Tokyo metropolitan area. METI industrial policy supports vRAN deployment for manufacturing automation. Urban centers standardize on dense Massive MIMO configurations for stadium and transit hub capacity expansion.
LTE and 5G Market Competitive Landscape
Chinese producers anchor one tier; European and Korean specialists hold differentiated positions in integrated systems and semiconductor supply. The vendor ecosystem fragments across radio access network disaggregation, with Open RAN interoperability mandates forcing supply chain diversification. Three archetypes dominate: integrated equipment vendors with captive silicon, specialized radio frequency component suppliers, and cloud-native software stack providers. Competitive moves concentrate on strategic partnerships for multi-vendor certification and vertical integration into baseband processor fabrication.
Within the integrated systems tier, Huawei Technologies Co., Ltd. and Samsung Electronics Co., Ltd. occupy positions shaped by geographic market access constraints and captive semiconductor supply chains. ZTE Corporation represents the state-linked equipment vendor archetype serving infrastructure markets with turnkey deployment capabilities. Qualcomm Incorporated exemplifies the modem-RF system integration specialist licensing across Android ecosystems. Nokia and Telefonaktiebolaget LM Ericsson anchor the European vendor segment with vRAN specialization and Open RAN conformance portfolios. These five entities collectively span the competitive spectrum from silicon-to-systems integration to disaggregated software-defined architectures.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Telefonaktiebolaget LM Ericsson |
| Nokia |
| Samsung Electronics Co., Ltd. |
| ZTE Corporation |
| Qualcomm Incorporated |
| AT&T Inc. |
| NEC Corporation |
| KT Corporation |
| Others |
Supply & Pricing Matrix
Base station component spot prices on the Shanghai Metals Market cascade through equipment vendor quotations, compressing margins for 64T64R Massive MIMO arrays while elevating premiums for millimeter-wave small-cell configurations with guaranteed delivery windows.
Pricing Analysis
Lead-time-driven pricing separates urgent-deployment premiums from inventory-clearance discounts in the RF front-end segment. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FCC Part 27 compliance commanding substantial uplifts over uncertified alternatives. Pricing pressure stems from Open RAN disaggregation forcing multi-vendor integration costs onto systems integrators. Enterprise buyers in Germany's automotive belt exhibit lowest price sensitivity due to production downtime costs, while emerging-market operators face acute budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mobile network operator demand for integrated baseband units, while systems integrators aggregate private 5G procurement for manufacturing buyers. Geographic concentration centers on Taiwan for advanced-node baseband processors, South Korea for RF front-end components, and China for antenna assembly and passive infrastructure. Raw material dependencies include gallium nitride substrates, high-purity copper for RF cabling, and rare-earth elements for power amplifiers. Single-source vulnerability in Taiwan-based foundry capacity exposes equipment vendors to geopolitical disruption. Distribution runs through carrier procurement consortia in developed markets and turnkey systems integrators in industrial automation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where 5G New Radio displaces LTE Advanced equipment, with Massive MIMO configurations and vRAN architectures rendering purpose-built hardware obsolete across public and private deployments.
For Market Incumbents: Lock in captive semiconductor supply through long-term foundry agreements with Taiwan-based producers to insulate against geopolitical disruption. Deepen backward integration into RF front-end component fabrication to defend margin position against Open RAN disaggregation. Prioritize certification investment for FCC mid-band and EU cybersecurity frameworks to maintain operator procurement eligibility. For New Entrants and Emerging Players: Capture private 5G installations in South Korea's Gyeonggi Province and Germany's Bavarian manufacturing zones where localized spectrum frameworks reduce incumbent lock-in. Target industrial corridor deployments in China's Yangtze River Delta through partnerships with state-backed systems integrators. Pursue cloud-native vRAN software stacks as the most penetrable entry vector against integrated hardware vendors. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized RF component suppliers with millimeter-wave design capabilities in South Korea and Japan. Long-term viability hinges on 5G-Advanced and 6G standardization participation across the next decade. Monitor 3GPP Release timelines and national spectrum auction calendars as inflection indicators for equipment refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Multi-Vendor Certification | FCC and NIST security mandates force interoperability testing across radio unit, distributed unit, and centralized unit combinations. |
| Captive Semiconductor Supply Agreement | Long-term foundry contracts with Taiwan-based producers reduce exposure to geopolitical supply disruption in baseband processor fabrication. |
| Private 5G Turnkey Systems Integration | Germany's Ruhr industrial cluster buyers bundle spectrum licensing, equipment installation, and managed services into single procurement agreements. |
| Mid-Band Spectrum Equipment Refresh | FCC 3.45-3.55 GHz auction framework drives regional carrier upgrade cycles in the Midwest and Mountain West coverage gaps. |
| AI-Driven Network Optimization Development | Machine learning inference at the network edge merges with radio resource management for predictive handoff in Tokyo metropolitan deployments. |
Research Methodology
Multi-period observation of spectrum auction calendars, base station deployment permits, and operator capital expenditure disclosures anchored the trend analysis, supplemented by interviews with network planning executives at tier-one mobile operators, procurement directors at automotive and semiconductor manufacturers, regulatory affairs specialists at equipment vendors, and RF engineering leads at systems integrators. Secondary validation drew from FCC licensing databases, 3GPP technical specifications, MIIT infrastructure spending disclosures, and SEC filings of publicly traded equipment vendors. Bottom-up equipment shipment tracking triangulated against top-down operator capex analysis.
Input-output matrices modeled subscriber growth trajectories, spectrum efficiency improvements, and equipment replacement cycles across the projection horizon. Segmentation dimensions included deployment type, radio access technology generation, end-user procurement authority, and service type revenue composition. CAGRs were derived from regression analysis of historical equipment pricing and volume trends. Industry-specific forecast inputs incorporated Massive MIMO densification rates and private spectrum licensing framework adoption.
The model holds under stable regulatory timelines for spectrum allocation and equipment certification; deviation in trade policy restrictions or cybersecurity mandate acceleration would shift deployment trajectories. Forecasts reflect documented assumptions regarding sub-6 GHz saturation timing and millimeter-wave propagation engineering solutions. Periodic stress-testing of base assumptions against 3GPP standardization milestones and national auction outcomes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Global Mobile and Wireless Backhaul Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Wireless Mesh Networking Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Global Bluetooth Audio Codec Market