
 Underwater Wireless Communication Market | 2026-2036
Underwater Wireless Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Wireless Communication Market Outlook
Norway is fragmenting as new acoustic modem foundries and sensor integration labs compete for North Sea defense and energy contracts. Kongsberg Gruppen ASA anchors Norwegian supply through its Kongsberg Maritime division, which dominates subsea navigation and communication systems for autonomous underwater vehicles. Teledyne Technologies Incorporated extends its position across the Atlantic through Teledyne Marine's portfolio of acoustic modems and imaging sonars. Saab AB competes in the Baltic and North Sea corridors with underwater communication systems tailored for naval mine countermeasures and surveillance.
Underwater wireless communication encompasses data transmission between submerged platforms using acoustic pressure waves, optical pulses, or electromagnetic fields, typically operating below 100 kHz for acoustic links to overcome seawater absorption. These systems enable real-time command of remotely operated vehicles, seabed sensor networks, and submarine tactical coordination in environments where radio frequency propagation fails. Acoustic technology occupies the largest share of deployed links due to its range resilience in turbid and deep-water conditions. Optical communication is gaining traction for high-bandwidth, short-range applications such as underwater robotics docking and seabed data harvesting. Hybrid architectures that fuse acoustic positioning with optical data bursts are emerging where operators need both range and throughput in dynamic marine environments.
The International Telecommunication Union's radiocommunication sector sets spectrum coordination rules for submerged acoustic channels, while the International Maritime Organization's safety codes influence equipment certification for vessel-tethered systems. The United States Navy's Unmanned Undersea Vehicle Master Plan shapes procurement standards that cascade through NATO-aligned defense ministries and their commercial suppliers. Stakeholders must monitor how national submarine cable protection statutes and exclusive economic zone data sovereignty claims reshape deployment permissions and cross-border network architectures.
Market Dynamics
Defense procurement cycles in Norway and the United States are compressing development timelines for acoustic modem networks, forcing suppliers to accelerate certification while maintaining reliability standards for submarine and autonomous underwater vehicle operations.
Growth Catalysts
- EU Marine Strategy Framework Directive:Tightened environmental monitoring mandates in offshore zones are accelerating sensor network deployments across the North Sea corridor.
- Acoustic modem networks:Naval mine countermeasures and surveillance applications in the Baltic corridor are pulling demand for extended-range underwater communication infrastructure.
- Autonomous underwater vehicle fleets:Expanded procurement by NATO-aligned defense ministries is creating sustained demand for real-time seabed coordination systems.
Market Restraints
- Seawater absorption physics:Electromagnetic field propagation remains technically unviable beyond shallow depths, locking acoustic technology into bandwidth-constrained architectures.
- Transducer material concentration:Specialized piezoelectric ceramic supply concentrates among a limited set of precision foundries, creating input vulnerability.
- Exclusive economic zone data sovereignty claims:Cross-border network permissions are fragmenting as coastal states assert seabed infrastructure control rights.
Strategic Opportunities
- Hybrid acoustic-optical architectures:Fusing acoustic positioning with optical data bursts is opening high-throughput niches in dynamic marine environments where range and bandwidth must coexist.
- Seabed data harvesting:Offshore energy operators in the United Kingdom are piloting optical communication for subsea robotics docking and sensor data retrieval.
- Norwegian subsea cluster expansion:New acoustic modem foundries and sensor integration labs are fragmenting supply and creating partnership entry points for specialized component vendors.
Industry Challenges
- Acoustic channel modeling expertise:The talent pool for predicting multipath propagation in turbid water columns remains shallow, extending system calibration cycles.
- NATO STANAG certification timelines:Interoperability standards for submarine tactical coordination are extending product validation phases by 18-24 months.
- Legacy vessel integration:Retrofitting acoustic modem networks onto existing remotely operated vehicle fleets requires custom mechanical and software interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Wireless Communication Market |
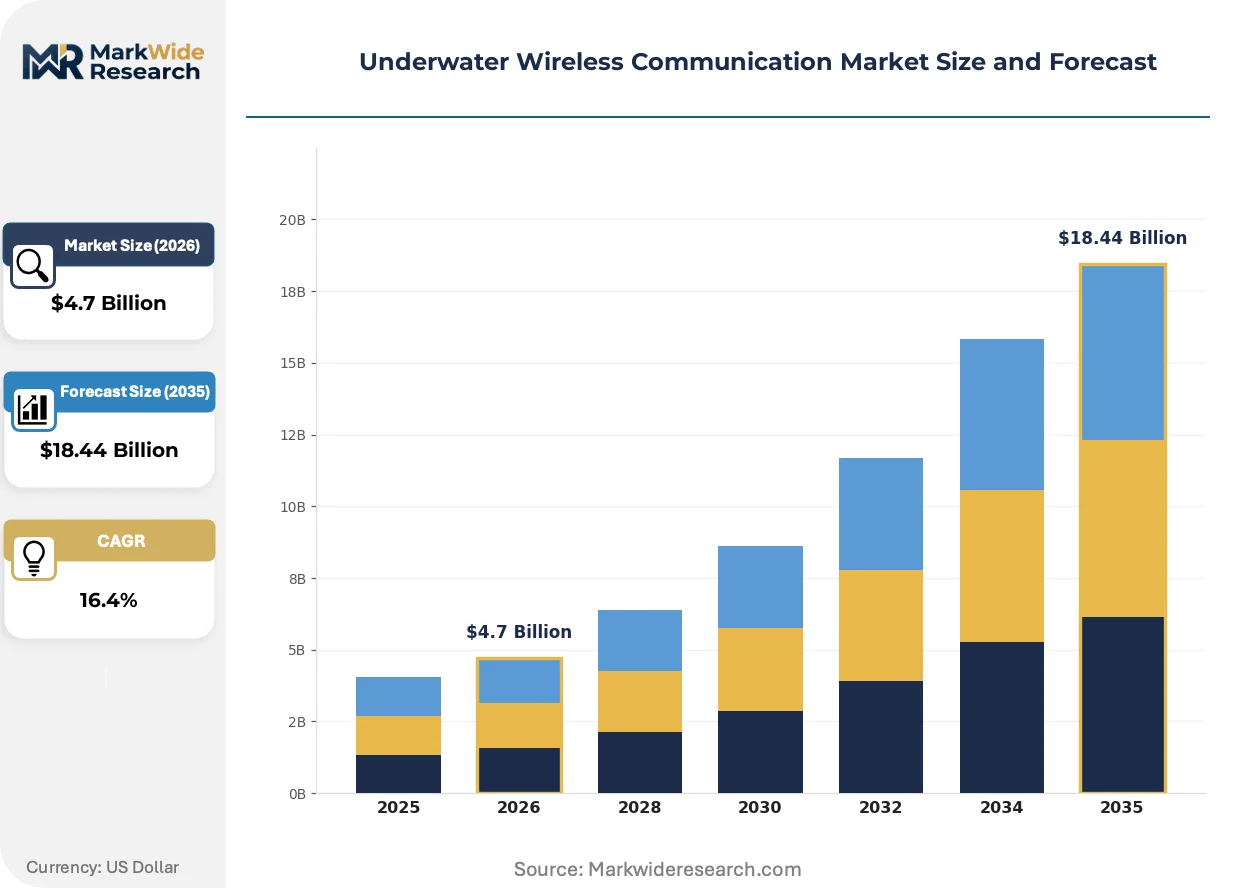
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $18.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Acoustic, Optical, Radio Frequency, Hybrid Application: Marine Exploration, Oil & Gas, Environmental Monitoring, Underwater Robotics End User: Defense, Commercial, Research Institutions, Fisheries Form Factor: Modems, Transducers, Sensors, Networks |
| Companies Covered | EvoLogics GmbH, Water Linked AS, Teledyne Technologies Incorporated, Saab AB, Nortek AS, Kongsberg Gruppen ASA, Subnero Ltd, L3Harris Technologies, Inc., Sonardyne International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Wireless Communication Market Strategic Shifts
Underwater wireless communication is experiencing a technology inflection as optical pulses and acoustic pressure waves converge into unified system architectures, while regulatory pressure on seabed environmental monitoring intensifies procurement specifications.
Optical communication systems are hybridizing across the market. These platforms transmit high-bandwidth data bursts through seawater using blue-green laser pulses for short-range applications. Offshore energy operators in Denmark are adopting hybrid acoustic-optical nodes for subsea robotics docking and seabed sensor data retrieval. The technology is hybridizing positioning accuracy with throughput capacity, compressing the trade-off between range resilience and data speed that has historically constrained acoustic-only deployments.
REACH substance restrictions are reshaping transducer material sourcing. The European Chemicals Agency's phased limitations on lead-based piezoelectric ceramics are forcing acoustic modem manufacturers to qualify alternative compositions. Norwegian and United Kingdom suppliers are accelerating barium titanate and potassium sodium niobate validation programs. Defense procurement channels are most affected, with NATO-aligned ministries requiring RoHS-compliant alternatives for new autonomous underwater vehicle programs.
Buyers are consolidating vendor relationships around integrated system capabilities. Defense end users in the United States Navy are shifting from component procurement to full acoustic modem network packages that include positioning, communication, and imaging sonar functions. Teledyne Marine and Kongsberg Maritime are capturing larger contract shares by bundling previously separate product lines. This consolidation is most visible in the North Sea corridor, where Norwegian and United Kingdom operators prefer single-source accountability for subsea infrastructure projects.
Underwater Wireless Communication Market Segmentation
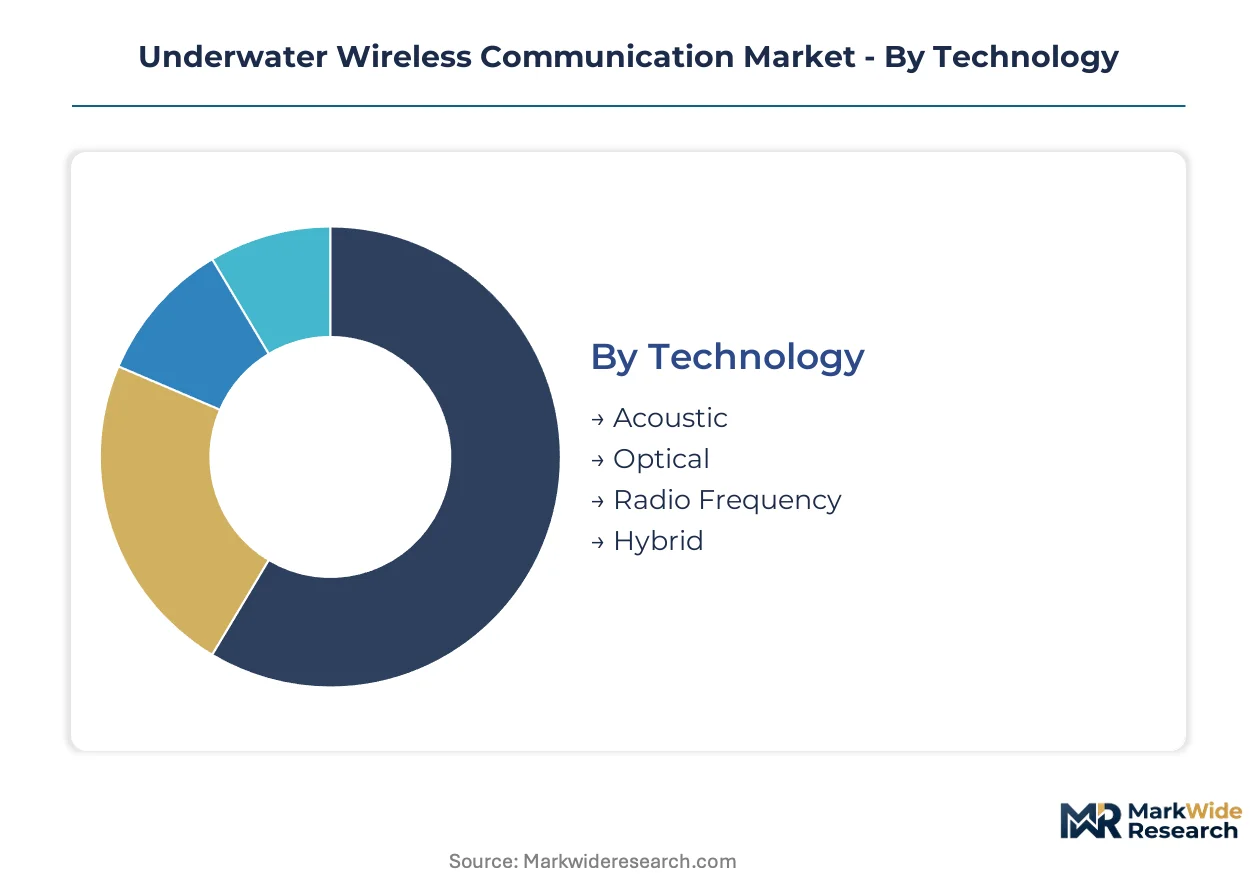
Technology choice in underwater wireless communication determines range, bandwidth, and deployment depth, creating distinct procurement patterns across defense, energy, and scientific verticals. Each segment exhibits unique supply chain configurations and certification requirements that shape vendor positioning and end-user selection criteria.
Technology:
Mature acoustic systems dominate deployed infrastructure while optical and hybrid architectures emerge for bandwidth-intensive applications.
- Acoustic:Pressure wave transmission below 100 kHz overcomes seawater absorption to enable kilometer-range links in turbid conditions. Norwegian defense procurement and North Sea energy operators anchor demand for proven modem networks with established NATO STANAG interoperability.
- Optical:Blue-green laser pulses transmit high-bandwidth data bursts through seawater for short-range, high-throughput scenarios. United Kingdom offshore operators pilot optical nodes for subsea robotics docking where clarity permits.
- Radio Frequency:Electromagnetic field propagation remains confined to shallow depths due to conductive seawater attenuation, limiting deployment to surface-near sensor networks.
- Hybrid:Fused acoustic positioning with optical data bursts addresses dynamic marine environments requiring both range resilience and throughput capacity.
Acoustic technology handles the majority of deployed links; hybrid architectures are expanding most quickly on share as operators seek unified range-bandwidth solutions.
Application:
Cost tier differentiation separates mission-critical defense deployments from price-sensitive commercial monitoring networks.
- Marine Exploration:Scientific seabed mapping and geological survey operations require extended-range acoustic coordination for autonomous vehicle fleets operating at abyssal depths.
- Oil & Gas:Subsea production systems demand real-time communication for remotely operated vehicle intervention and pipeline inspection in the North Sea corridor.
- Environmental Monitoring:EU Marine Strategy Framework Directive mandates are accelerating sensor network deployments across Norwegian, United Kingdom, and Danish offshore zones for compliance data collection.
- Underwater Robotics:Autonomous underwater vehicle fleet expansion by NATO-aligned ministries creates sustained demand for real-time seabed coordination and docking systems.
Oil & Gas commands the highest per-link expenditure; environmental monitoring is gaining share fastest as regulatory enforcement tightens.
End User:
Customer type determines procurement channel, certification burden, and technology specification rigor.
- Defense:Submarine tactical coordination and mine countermeasures require NATO STANAG-certified acoustic modem networks with hardened encryption and anti-jam resilience. Norway and United States procurement cycles are compressing supplier development timelines.
- Commercial:Offshore energy operators prioritize integrated positioning-communication-imaging bundles from single-source vendors to reduce subsea project accountability fragmentation.
- Research Institutions:Scientific programs favor modular, reprogrammable systems for experimental acoustic channel characterization and optical propagation studies.
- Fisheries:Aquaculture monitoring and net pen communication systems represent emerging demand for cost-optimized, short-range acoustic links.
Defense absorbs the premium tier volume; commercial buyers are climbing the fastest as integrated system procurement consolidates vendor relationships.
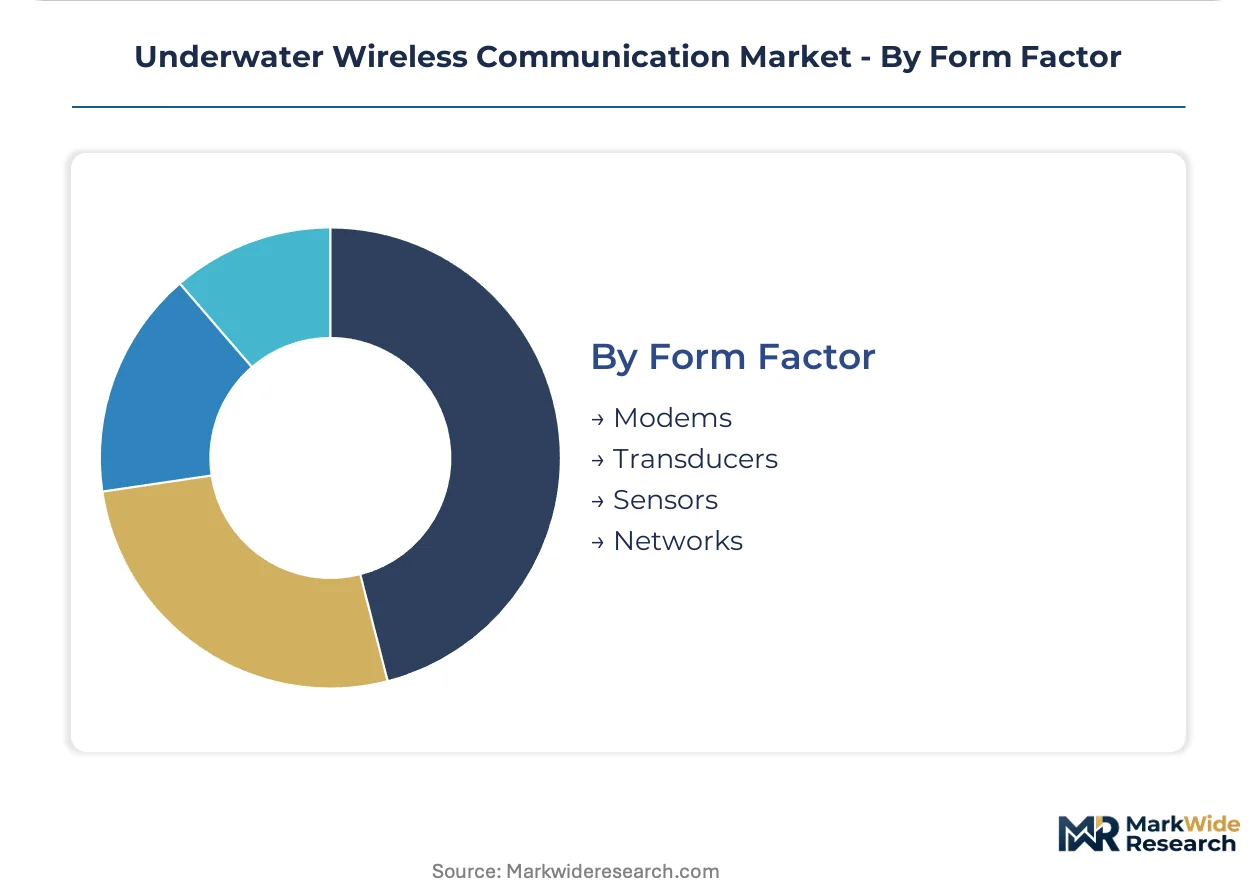
Form Factor:
Supply concentration varies sharply between commoditized transducer elements and complex integrated network systems.
- Modems:Signal processing units encoding data onto acoustic or optical carriers form the core revenue concentration point, with Kongsberg Maritime and Teledyne Marine capturing integrated contract shares.
- Transducers:Piezoelectric ceramic elements face REACH substance restrictions forcing barium titanate and potassium sodium niobate qualification programs among Norwegian and United Kingdom suppliers.
- Sensors:Environmental parameter acquisition nodes for temperature, pressure, and chemical detection integrate communication capability for seabed observatory networks.
- Networks:Multi-node mesh architectures with synchronized positioning and data routing enable coordinated autonomous underwater vehicle fleet operations.
Modems generate the dominant revenue stream; networks are expanding most rapidly as operators shift from component procurement to full system packages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea subsea cable corridor and Norwegian fjord infrastructure anchor European underwater wireless communication deployment, while Pacific seabed observatory networks and Atlantic defense routes shape procurement patterns across other concentrated markets.
Norway
Defense procurement for submarine and autonomous underwater vehicle operations drives acoustic modem network demand along the Norwegian coast. The country's implementation of EU Marine Strategy Framework Directive monitoring mandates accelerates sensor deployment in offshore zones. Kongsberg Maritime's headquarters region near Horten anchors subsea navigation and communication system development.
United States
The United States Navy's Unmanned Undersea Vehicle Master Plan compresses supplier development timelines for tactical coordination systems. FCC spectrum coordination rules and Department of Defense procurement standards cascade through NATO-aligned channels. Teledyne Marine's California and Massachusetts operations exemplify integrated positioning-communication-imaging bundling for defense contracts.
United Kingdom
Offshore energy operators in the North Sea corridor pilot optical communication nodes for subsea robotics docking and seabed data harvesting. REACH substance restrictions on lead-based piezoelectric ceramics force barium titanate qualification programs among domestic suppliers. Sonardyne International's presence in Yate concentrates underwater positioning and communication engineering.
Denmark
Hybrid acoustic-optical node adoption accelerates among offshore energy operators seeking unified range-bandwidth solutions for subsea infrastructure. ECHA RoHS compliance requirements shape transducer material sourcing decisions for Baltic and North Sea deployments. Copenhagen-based sensor integration labs compete for environmental monitoring contracts under tightened EU directives.
Germany
EvoLogics GmbH's Berlin operations anchor acoustic modem development for scientific and defense applications across European seabed observatory networks. Germany's Federal Maritime and Hydrographic Agency enforces equipment certification standards that influence NATO STANAG interoperability timelines. The country's precision foundry concentration in southern industrial zones supplies specialized piezoelectric ceramic elements.
Underwater Wireless Communication Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in transducer materials and signal processing modules. The vendor base concentrates around bundled positioning-communication-imaging offerings rather than discrete product lines. Two strategic archetypes dominate: integrated maritime technology conglomerates with defense certification pathways, and specialized acoustic modem foundries serving research and environmental monitoring verticals. Competitive moves center on strategic partnerships for hybrid technology development and geographic expansion into North Sea corridor energy contracts.
Among Nordic integrated system providers, Kongsberg Gruppen ASA and Saab AB exemplify the defense-certified platform tier with established NATO procurement channels. Teledyne Technologies Incorporated occupies a position bridging Atlantic defense and commercial energy markets through its marine division's bundled offerings. Specialized component developers including EvoLogics GmbH and Water Linked AS represent the agile foundry archetype, focusing on modular acoustic modem architectures for research and autonomous vehicle integration.
| Leading Market Players |
|---|
| EvoLogics GmbH |
| Water Linked AS |
| Teledyne Technologies Incorporated |
| Saab AB |
| Nortek AS |
| Kongsberg Gruppen ASA |
| Subnero Ltd |
| L3Harris Technologies, Inc. |
| Sonardyne International Ltd |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions on lead-based piezoelectric ceramics compress both margin structures and sourcing architectures across acoustic modem manufacturing tiers. Norwegian and United Kingdom suppliers face dual pressure from ECHA compliance timelines and defense procurement cost ceilings, forcing tiered pricing spreads that separate NATO STANAG-certified systems from commercial monitoring alternatives.
Pricing Analysis
Volume-discount tiering structures separate defense procurement bundles from discrete component sales across the underwater wireless communication market. Premium tiers capture integrated positioning-communication-imaging systems with NATO STANAG certification and hardened encryption, while standard tiers address commercial offshore energy operators seeking single-source accountability. Cost compression in the commercial tier intensifies as United Kingdom and Danish operators consolidate vendor relationships around bundled offerings. Research institutions exhibit highest price sensitivity due to modular, reprogrammable system requirements and grant-funded budget constraints.
Supply Chain Analysis
Upstream feedstock concentration in specialized piezoelectric ceramics centers on German precision foundries and Japanese ceramic manufacturers, with barium titanate and potassium sodium niobate alternatives qualifying under REACH timelines. Acoustic modem assembly draws from Norwegian sensor integration labs, United States defense contractors, and United Kingdom offshore energy equipment specialists. Single-source vulnerability concentrates in transducer material supply, where limited foundry capacity creates input bottlenecks. Distribution runs through direct defense procurement channels and integrated maritime technology conglomerates serving commercial energy contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Underwater wireless communication sits at an early-cycle expansion phase as hybrid acoustic-optical architectures displace legacy single-technology deployments across North Sea defense and energy corridors.
For Market Incumbents: Build certification moats around NATO STANAG interoperability standards to lock out modular competitors. Accelerate barium titanate and potassium sodium niobate qualification programs ahead of REACH enforcement timelines. Capture sensor integration lab partnerships in Norway to defend against acoustic modem foundry fragmentation threatening integrated contract shares.
For New Entrants and Emerging Players: Build out environmental monitoring sensor network capabilities targeting EU Marine Strategy Framework Directive compliance mandates across Danish and United Kingdom offshore zones. Fisheries aquaculture monitoring represents the most penetrable segment, with cost-optimized short-range acoustic links replacing legacy tethered systems. Partner with Copenhagen-based integration labs for rapid Baltic corridor market access.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors specialized acoustic modem foundries with optical hybridization roadmaps. Long-term viability hinges on positioning-communication convergence rather than discrete component supply. Watch NATO Unmanned Undersea Vehicle Master Plan procurement acceleration as the inflection signal for defense contract flow-through.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Acoustic-Optical Platform Development | Fuses Kongsberg Maritime's positioning heritage with optical throughput for subsea robotics docking. |
| REACH-Compliant Transducer Material Qualification | Positions Norwegian suppliers ahead of ECHA phased limitations on lead-based ceramics. |
| NATO STANAG Certification Investment | Creates 18-24 month validation barriers protecting Teledyne Marine's defense contract share. |
| Sensor Integration Lab Partnership Network | Fragments supply concentration across Copenhagen, Horten, and Yate engineering clusters. |
| Seabed Data Harvesting Pilot Deployment | Validates optical node economics for United Kingdom offshore energy operators. |
Study Parameters
Operator-level perspectives from submarine systems engineers, autonomous underwater vehicle fleet managers, offshore energy project directors, and marine environmental compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through ECHA substance restriction filings, NATO STANAG documentation, United States Navy Unmanned Undersea Vehicle Master Plan procurement disclosures, and United Kingdom North Sea decommissioning project databases. Bottom-up acoustic modem unit deployment estimates triangulated against top-down defense budget allocation analysis across Norway, United States, and United Kingdom channels.
Scenario-bracketing framed volume and value outputs across the analysis window, with technology segmentation modeling acoustic, optical, radio frequency, and hybrid architectures. Application dimensions captured marine exploration, oil and gas, environmental monitoring, and underwater robotics end uses. End-user stratification separated defense procurement cycles, commercial integrated system bundles, research institution modular requirements, and emerging fisheries monitoring demand. CAGR derivation incorporated acoustic channel modeling expertise scarcity, transducer material substitution timelines, and exclusive economic zone data sovereignty claim proliferation as industry-specific forecast inputs.
Sensitivities concentrate around REACH enforcement acceleration, NATO procurement cycle compression, and hybrid technology validation success rates. Forecasts reflect documented assumptions regarding piezoelectric ceramic supply continuity and submarine cable protection statute harmonization. Cross-checking against United States Department of Defense unmanned systems budget justification materials is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Wireless Health Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Wigig Market
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Multefire Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market