
 Latin America Wireless Mesh Networking Market | 2026-2036
Latin America Wireless Mesh Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Wireless Mesh Networking Market Insights
The capital-intensity gap between integrated platform vendors and component specialists is bifurcating competitive dynamics across Latin America. Cisco Systems leverages its end-to-end hardware-software stack to anchor large-scale smart city deployments in São Paulo and Mexico City. Qualcomm Incorporated sustains chipset supply relationships that dominate the cellular and Bluetooth technology layers embedded in regional OEM devices. Rajant Corporation specializes in industrial-grade kinetic mesh configurations that occupy niche mining and energy extraction environments across Chile and Peru.
Wireless mesh networking deploys self-healing, multi-hop radio architectures operating across unlicensed and licensed spectrum bands to deliver resilient last-mile connectivity without wired backhaul dependency. These systems typically integrate IEEE 802.11s or proprietary routing protocols to enable node-to-node packet forwarding with sub-50 millisecond failover recovery, serving critical infrastructure where fiber deployment proves economically unfeasible. Hardware sales currently lead revenue composition as municipalities and utilities prioritize physical access point and gateway procurement over software licensing. Services segments surrounding network design and post-deployment maintenance represent the fastest-expanding margin pool as technical skill scarcity across Latin America pushes buyers toward managed outcome arrangements. Smart Cities and Industrial Automation end-user categories concentrate demand most intensely, reflecting divergent buyer profiles between public-sector resilience mandates and private operational-technology uptime requirements.
Brazil's ANATEL spectrum regulations and Mexico's IFT interoperability mandates shape product certification requirements and market access timelines for equipment vendors entering these jurisdictions. Chile's SUBTEL technical standards and Argentina's ENACOM type-approval processes add further compliance layering that advantages pre-certified multinational suppliers over emerging local competitors. Stakeholders must monitor pending spectrum reallocation proceedings and evolving cybersecurity attachment rules as these regulatory instruments increasingly determine which technology configurations achieve commercial viability across the region's fragmented national frameworks.
Market Dynamics
ANATEL's spectrum reallocation proceedings and Brazil's national broadband infrastructure mandates are compressing vendor certification timelines while accelerating municipal procurement cycles for resilient last-mile connectivity across metropolitan corridors.
Growth Catalysts
- Smart city infrastructure mandates:Brazilian and Mexican municipal governments prioritize mesh-based traffic management and environmental monitoring systems for public safety networks. Federal funding allocations for urban digitalization are channeling capital toward resilient connectivity architectures.
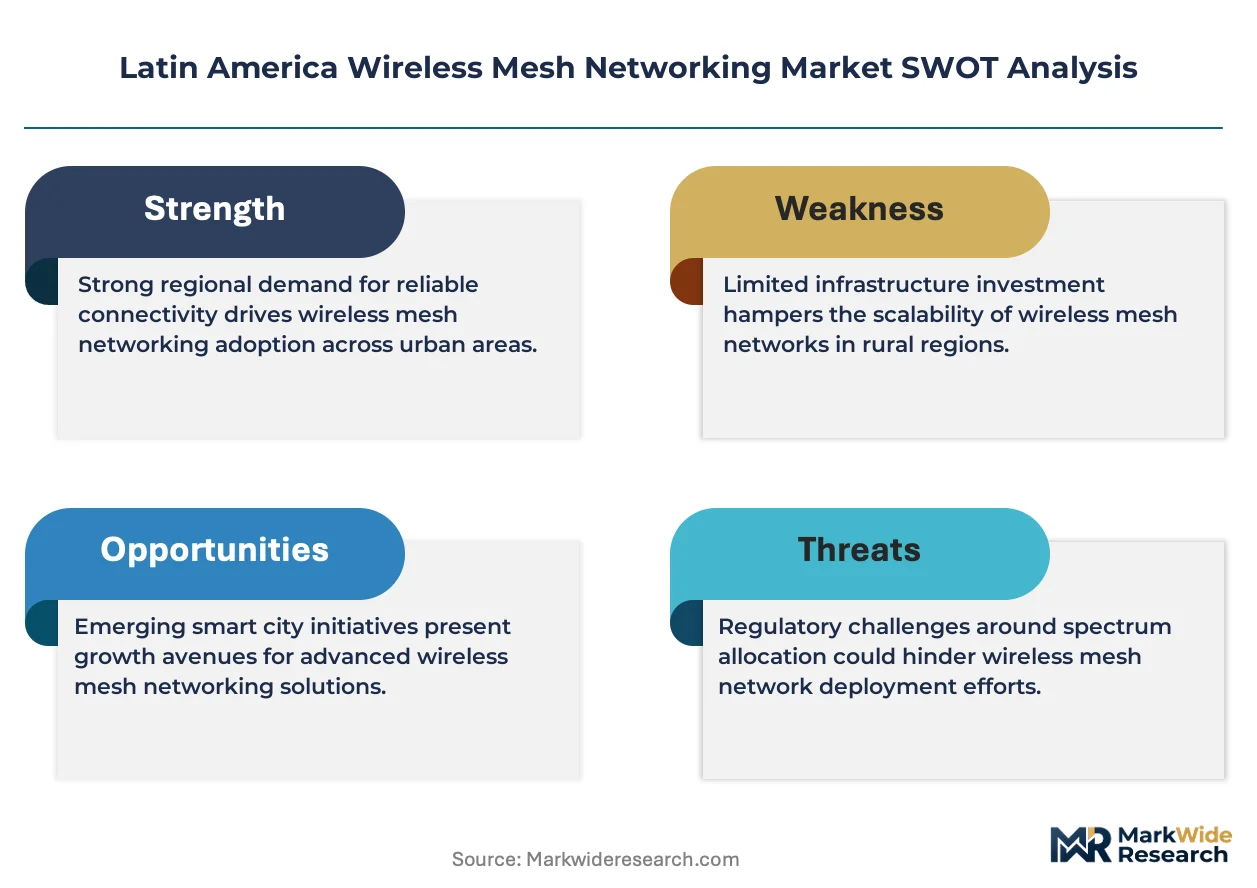
- Spectrum allocation reforms:ANATEL's unlicensed band expansions and Mexico's IFT interoperability frameworks reduce market access barriers for equipment vendors. Regulatory clarity accelerates product certification and commercial deployment timelines.
- Industrial automation uptake:Mining and energy extraction operations across Chile and Peru deploy kinetic mesh configurations for operational-technology uptime in remote environments. Private sector demand complements public-sector resilience investments.
Market Restraints
- Technical skill scarcity:Network design and post-deployment maintenance expertise concentrates in São Paulo and Mexico City, limiting execution capacity across secondary metropolitan markets.
- Compliance layering fragmentation:Chile's SUBTEL technical standards, Argentina's ENACOM type-approval processes, and divergent national cybersecurity attachment rules extend product launch timelines.
- Fiber backhaul economics:Dense urban corridors in Brazil and Mexico face competitive pressure from subsidized fiber deployments, compressing addressable market for wireless alternatives in core revenue zones.
Strategic Opportunities
- Utility grid modernization:Latin American electrical distributors seek resilient connectivity for distribution automation and smart metering in areas where fiber trenching proves economically unfeasible.
- Managed outcome arrangements:Technical skill scarcity across the region pushes buyers toward network-as-a-service models, expanding recurring revenue pools for vendors with regional service infrastructure.
- Cross-border spectrum harmonization:Pending MERCOSUR digital integration frameworks could streamline multi-country deployments for vendors with pre-certified equipment portfolios.
Industry Challenges
- Multi-protocol integration complexity:IEEE 802.11s standards coexist with proprietary routing implementations, forcing buyers to navigate interoperability testing and vendor lock-in risks.
- Cybersecurity certification velocity:Evolving national cybersecurity attachment rules in Brazil and Mexico require continuous product recertification, consuming engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Wireless Mesh Networking Market |
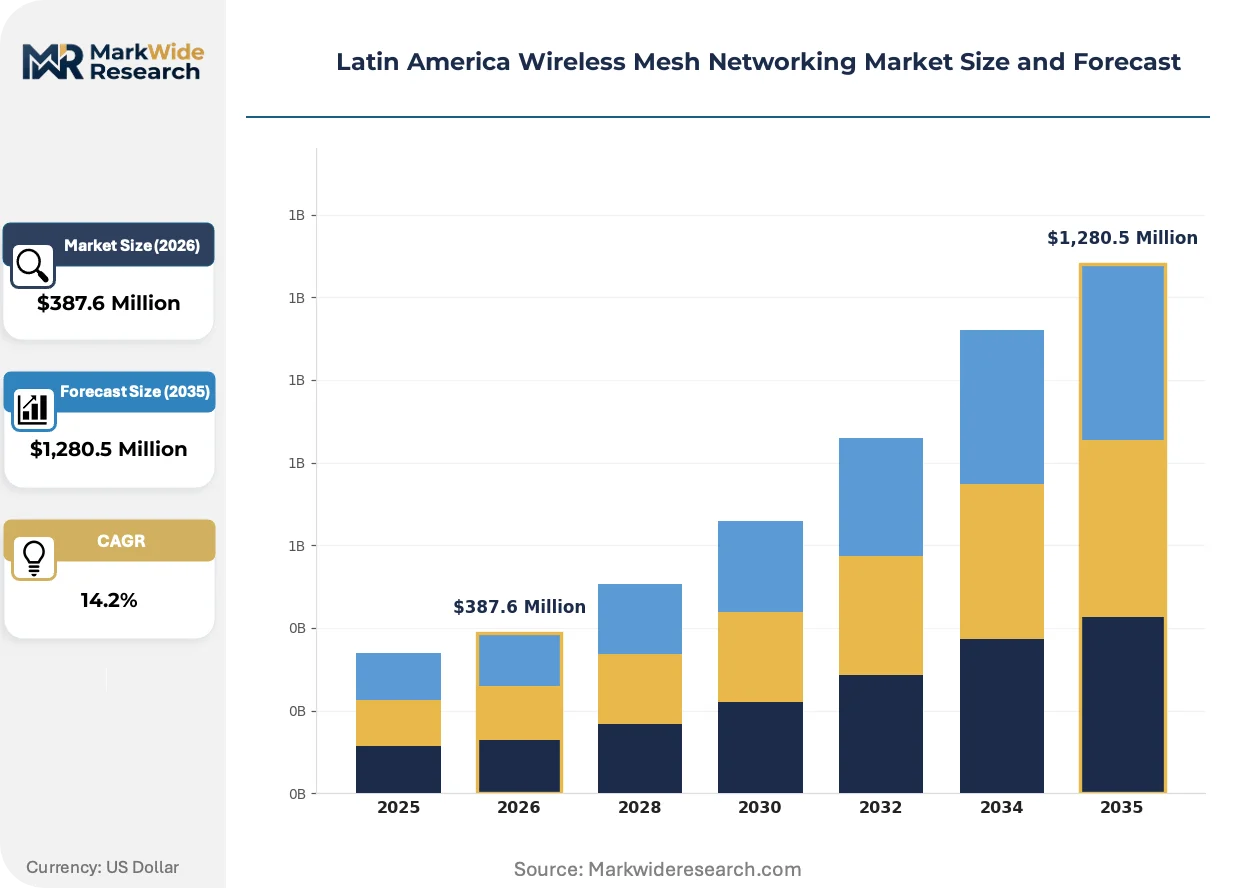
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Connectivity Solutions End User: Smart Cities, Industrial Automation, Healthcare Facilities, Educational Institutions Application: Traffic Management, Smart Grids, Building Automation, Environmental Monitoring Technology: IPv6, Cellular, Bluetooth, LoRaWAN |
| Companies Covered | Cisco Systems, Qualcomm Incorporated, ABB Ltd, Rajant Corporation, Aruba Networks, Cambium Networks, Motorola Solutions Inc, TP-Link Corporation Limited, CommScope Holding Company Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Wireless Mesh Networking Market Trends and Innovations
Proprietary kinetic mesh protocols and spectrum-efficient radio architectures are reshaping competitive differentiation as buyers prioritize sub-50 millisecond failover recovery over legacy hardware-centric procurement.
Multi-hop self-healing radio architectures operating across unlicensed and licensed spectrum bands are supplanting single-hop point-to-point wireless backhaul in municipal traffic management deployments. Brazilian metropolitan governments now specify mesh resilience as a mandatory procurement criterion. This technology shift compresses vendor qualification timelines while elevating software-defined routing capabilities over hardware access point density.
ANATEL's pending spectrum reallocation proceedings and Mexico's IFT interoperability mandates are tightening certification requirements for network equipment entering these jurisdictions. Industrial consequence includes accelerated consolidation around pre-certified multinational suppliers with dedicated regulatory affairs teams. Mining and energy extraction segments across Chile and Peru face compressed product launch windows as cybersecurity attachment rules layer onto existing technical standards.
Buyer preference is migrating from hardware-centric procurement toward managed service contracts bundling network design, deployment, and post-installation maintenance. Municipal governments and utility operators across São Paulo, Mexico City, and Santiago increasingly reject capital expenditure ownership in favor of outcome-based arrangements. This behavioral shift concentrates contract awards with vendors maintaining regional technical service infrastructure rather than pure equipment manufacturers.
Latin America Wireless Mesh Networking Market Segmentation
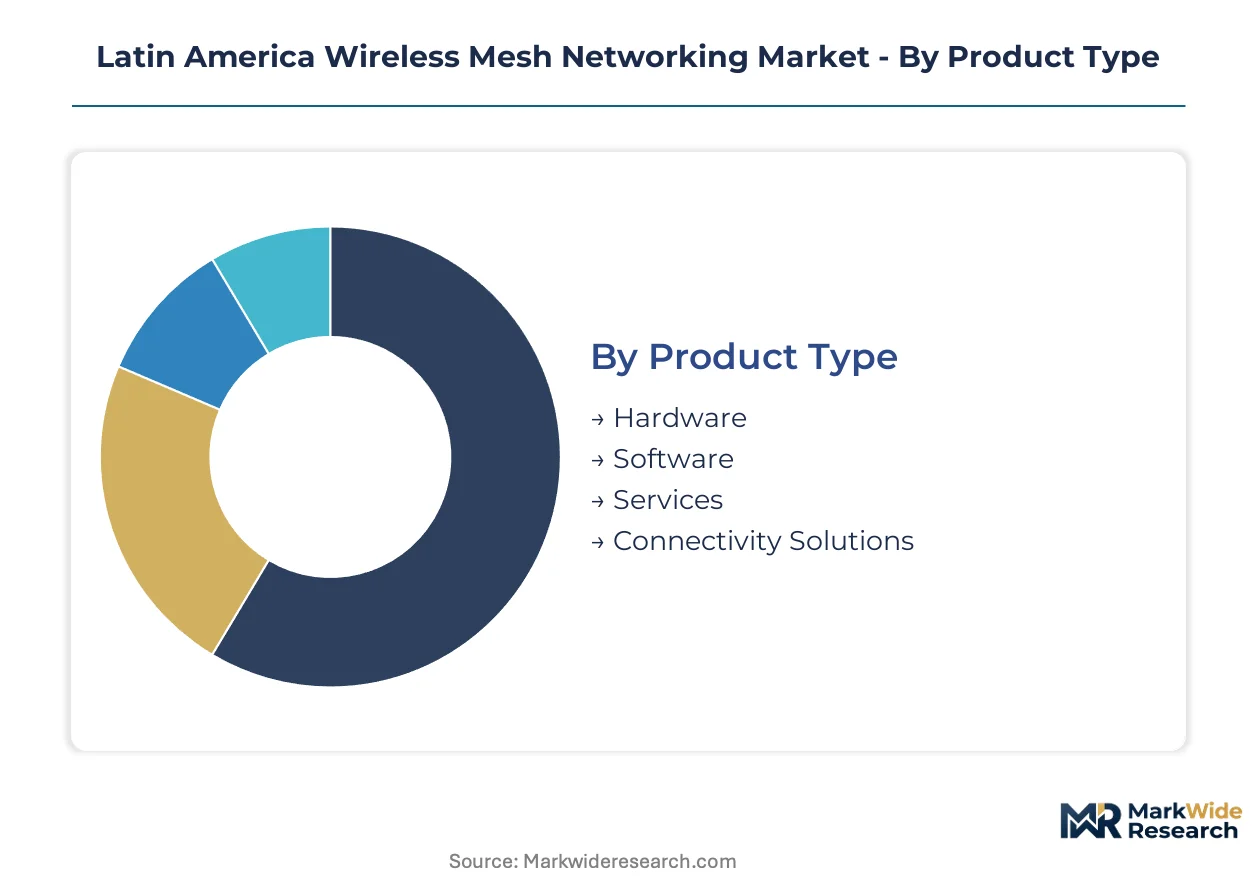
Segmentation in wireless mesh networking reveals divergent margin structures across the technology stack. Hardware procurement dominates municipal budgets, while services contracts capture expanding recurring revenue as technical skill scarcity intensifies across Latin America.
Product Type:
Margin pools concentrate most heavily in recurring service arrangements rather than one-time equipment sales.
- Hardware:Physical access points, gateways, and radio modules constitute the foundational infrastructure layer. Brazilian metropolitan corridors and Mexican smart city deployments drive procurement volume, though price compression from subsidized fiber alternatives limits margin expansion in dense urban cores.
- Services:Network design, deployment engineering, and post-installation maintenance contracts generate the highest recurring margin profiles. Technical skill scarcity across secondary Latin American markets pushes municipal buyers toward managed outcome arrangements with vendors maintaining regional service infrastructure.
- Software:Routing protocol licenses and network management platforms enable centralized configuration of distributed mesh nodes.
- Connectivity Solutions:Bundled offerings combining hardware, spectrum access, and managed network operations address utility grid modernization requirements.
The dominant share belongs to Hardware, while Services is closing the gap fastest.
End User:
Application intensity varies sharply between public-sector resilience mandates and private operational-technology uptime requirements.
- Smart Cities:Municipal governments across São Paulo, Mexico City, and Santiago specify mesh resilience as mandatory procurement criteria for traffic management and public safety networks. Federal urban digitalization funding channels capital toward architectures with sub-50 millisecond failover recovery.
- Industrial Automation:Mining and energy extraction operations in Chile and Peru deploy kinetic mesh configurations for operational-technology continuity in remote environments where fiber trenching proves economically unfeasible.
- Healthcare Facilities:Hospital networks require resilient connectivity for medical device integration and telemedicine infrastructure.
- Educational Institutions:Campus networks leverage mesh architectures to extend coverage across distributed facilities without wired backhaul dependency.
Smart Cities commands the largest addressable base, with Industrial Automation expanding most quickly.
Application:
Deployment complexity escalates with integration depth into legacy operational systems.
- Traffic Management:Brazilian metropolitan governments now mandate mesh-based architectures for signal coordination and congestion monitoring. ANATEL spectrum regulations and interoperability frameworks shape certification requirements for equipment entering these deployments.
- Smart Grids:Electrical distributors across the region prioritize resilient connectivity for distribution automation and smart metering in areas where fiber economics fail. Chilean utility operators lead procurement volume for grid modernization applications.
- Building Automation:Commercial and institutional facilities deploy mesh for HVAC, lighting, and security system integration.
- Environmental Monitoring:Sensor networks for air quality, water management, and disaster early warning leverage mesh self-healing for coverage continuity.
Traffic Management holds the leading position, though Smart Grids is gaining share fastest.
Technology:
Protocol selection determines interoperability boundaries and vendor ecosystem lock-in risks.
- Cellular:Licensed spectrum deployments offer guaranteed quality-of-service for critical infrastructure applications. Mexico's IFT interoperability mandates and Brazil's ANATEL certification frameworks favor pre-certified cellular modules for municipal and utility procurement.
- LoRaWAN:Unlicensed spectrum operation enables low-power, wide-area sensor networks for environmental monitoring and smart metering. Chilean SUBTEL technical standards and Argentina's ENACOM type-approval processes shape regional deployment feasibility.
- IPv6:Next-generation addressing protocols support scalable node density in dense urban mesh configurations.
- Bluetooth:Short-range radio technology enables device-to-device mesh in building automation and healthcare facility applications.
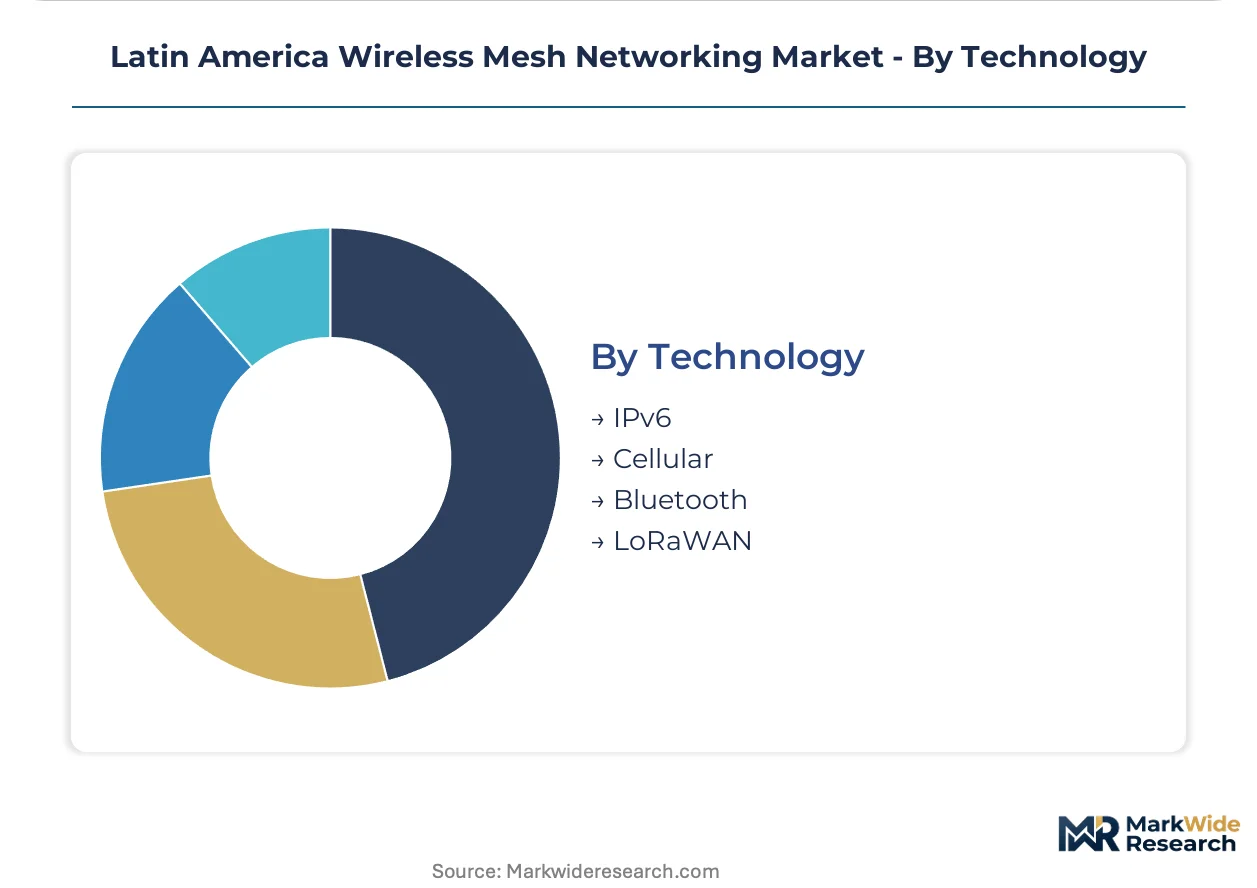
Cellular maintains the dominant technology position, while LoRaWAN is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement elasticity varies sharply across Latin America. Brazilian metropolitan buyers demonstrate lowest price sensitivity due to federal smart city subsidies, while Peruvian mining operators face compressed deployment budgets amid volatile copper prices.
Brazil
São Paulo and Rio de Janeiro municipal governments drive mesh infrastructure procurement for traffic signal coordination and public safety networks. ANATEL's spectrum reallocation proceedings and national broadband plan mandates compress vendor certification timelines while accelerating metropolitan deployment cycles. The São Paulo metropolitan corridor concentrates demand most intensely, where utility distributors prioritize resilient connectivity for smart grid automation.
Mexico
Mexico City and Nuevo León state governments specify mesh resilience as mandatory procurement criteria for urban digitalization projects. IFT interoperability frameworks reduce market access barriers for equipment vendors while tightening certification requirements for network hardware. The Bajío Region automotive manufacturing cluster deploys industrial mesh configurations for factory automation and operational-technology continuity.
Chile
SUBTEL technical standards shape deployment feasibility for mining and energy extraction operations across the Atacama Desert and copper belt regions. Santiago municipal authorities channel federal urban digitalization funding toward traffic management and environmental monitoring sensor networks. Antofagasta mining operators lead procurement volume for kinetic mesh configurations in remote extraction environments.
Argentina
ENACOM type-approval processes extend product launch timelines for equipment vendors entering Buenos Aires and Córdoba metropolitan markets. Federal infrastructure modernization programs prioritize resilient last-mile connectivity for utility grid distribution automation. The Buenos Aires metropolitan corridor concentrates public-sector demand, though procurement cycles lag regional peers due to currency volatility and import financing constraints.
Peru
Ministry of Transport and Communications spectrum regulations govern mesh deployment for Andean mining operations and Lima metropolitan traffic management. Cerro de Pasco and Ancash mining districts deploy kinetic mesh for operational-technology uptime in remote high-altitude extraction sites. Lima municipal government procurement concentrates on environmental monitoring and disaster early warning sensor networks.
Latin America Wireless Mesh Networking Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Latin American wireless mesh networking. Tier-one vendors leverage end-to-end hardware-software stacks to anchor large-scale smart city deployments, while component specialists dominate chipset supply relationships and industrial-grade kinetic configurations. Three archetypes define competitive positioning: integrated platform providers, semiconductor layer suppliers, and industrial-environment specialists. Consolidation pressures favor vendors with dedicated regulatory affairs teams and pre-certified equipment portfolios spanning multiple national jurisdictions.
Among integrated platform providers, Cisco Systems and Aruba Networks exemplify the full-stack archetype with municipal and enterprise deployment capabilities. Rajant Corporation occupies a position within the industrial-specialist tier, representing kinetic mesh configurations for mining and energy extraction environments. These three companies illustrate how competitive positioning stratifies across public-sector resilience mandates versus private operational-technology requirements.
| Leading Market Players |
|---|
| Cisco Systems |
| Qualcomm Incorporated |
| ABB Ltd |
| Rajant Corporation |
| Aruba Networks |
| Cambium Networks |
| Motorola Solutions Inc |
| TP-Link Corporation Limited |
| CommScope Holding Company Inc |
| Others |
Pricing and Supply Chain Analysis
Long-term managed service contracts lock in both supply access and price visibility across Brazilian and Mexican metropolitan corridors, where municipal buyers favor outcome-based arrangements over capital expenditure ownership. ANATEL certification timelines and IFT interoperability mandates compress vendor qualification windows while anchoring multi-year pricing commitments.
Pricing Analysis
Post-deployment maintenance and network-as-a-service tiers drive lifetime value for vendors with regional technical infrastructure. Pricing stratifies across certified-premium, standard-compliance, and economy-hardware tiers, with ANATEL pre-certification commanding measurable premiums. Cost compression in hardware procurement intensifies as subsidized fiber alternatives penetrate dense urban cores. Municipal governments in São Paulo demonstrate lowest price sensitivity due to federal smart city subsidies, while Peruvian mining operators face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of radio modules and gateway inventory dominates vendor preferences given ANATEL and IFT certification delays. Component sourcing draws from Taiwan, China, and USA for semiconductor layers, with Mexico and Brazil hosting final assembly operations. Single-source vulnerability concentrates in proprietary routing protocol chipsets. Distribution runs through certified systems integrators and municipal procurement frameworks rather than open channel sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among São Paulo and Mexico City municipal governments, which now specify mesh resilience as mandatory procurement criteria and bundle multi-year service contracts into single awards.
For Market Incumbents: Secure ANATEL and IFT pre-certification portfolios across multiple product generations to compress competitor entry timelines. Anchor large-scale smart city deployments through vertical integration into regional service infrastructure, as emerging pure-hardware vendors lack maintenance execution capacity. Defend against kinetic mesh specialists by embedding sub-50 millisecond failover specifications into municipal tender requirements. For New Entrants and Emerging Players: Lead with utility grid modernization applications in Chilean and Peruvian markets where fiber economics fail and incumbent service coverage remains thin. Target secondary Brazilian metropolitan corridors outside São Paulo and Rio de Janeiro, where technical skill scarcity has delayed incumbent deployment. Establish go-to-market partnerships with regional systems integrators holding existing municipal relationships rather than direct sales investment. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap vendors with pre-certified equipment portfolios spanning Brazil, Mexico, and Chile regulatory regimes. Long-term viability hinges on recurring services revenue share exceeding hardware transactional exposure. Watch for ANATEL spectrum reallocation proceedings as inflection indicator—accelerated unlicensed band expansion would favor agile entrants over legacy licensed-spectrum incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Pre-Certification Investment | Compresses product launch timelines and anchors premium pricing in Brazilian municipal procurement. |
| Regional Service Infrastructure Buildout | Captures recurring maintenance margins as technical skill scarcity intensifies across secondary markets. |
| Kinetic Mesh Protocol Development | Addresses mining and energy extraction uptime requirements in Chilean and Peruvian remote environments. |
| Managed Outcome Contract Packaging | Aligns vendor revenue streams with municipal buyer preference for operational expenditure models. |
| Cross-Border Spectrum Harmonization Lobbying | Positions vendors for streamlined multi-country deployments under pending MERCOSUR digital frameworks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANATEL regulatory filings, IFT interoperability standards, municipal procurement databases, and utility grid modernization disclosures across the analysis window. Interviews with network equipment procurement officers, smart city project directors, mining operational-technology leads, and regional systems integrators informed demand-side validation. Secondary sources include SUBTEL technical standards, ENACOM type-approval records, and customs trade data for radio module imports. Bottom-up equipment shipment estimates triangulate against top-down infrastructure spending allocations.
Segmentation dimensions modeled span hardware, software, services, and connectivity solutions by product type; smart cities, industrial automation, healthcare, and education by end user; traffic management, smart grids, building automation, and environmental monitoring by application; and cellular, LoRaWAN, IPv6, and Bluetooth by technology. CAGRs derive from regression analysis against broadband infrastructure investment trajectories and spectrum allocation timelines. Industry-specific forecast inputs include ANATEL certification velocity and municipal digitalization funding disbursement patterns.
Forecasts assume regulatory continuity in Brazilian ANATEL, Mexican IFT, Chilean SUBTEL, and Argentine ENACOM regimes; material policy shifts would require re-modeling. Cybersecurity attachment rule evolution and copper price volatility in Peruvian mining represent primary revision triggers. Revision becomes warranted when spectrum reallocation proceedings accelerate or federal smart city funding disbursements stall.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Asia-Pacific Distributed Antenna System Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
APAC Small Cell Tower Market