
 Industrial 5G Market | 2026-2036
Industrial 5G Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial 5G Market Analysis
Market Context
Project finance and spectrum-leasing arrangements for private 5G networks is tilting competitive access toward mid-sized industrial operators that previously lacked capital for licensed infrastructure. Nokia Corporation leverages its end-to-end private wireless portfolio to anchor large manufacturing deployments across Europe. Samsung Electronics dominates equipment supply for South Korea's factory automation upgrades. Huawei Technologies Co., Ltd. extends its position through integrated baseband and radio unit offerings that reduce deployment complexity for enterprise customers.
Technical Definition and Segment Structure
Industrial 5G denotes cellular communication systems operating in licensed, shared, or unlicensed spectrum bands with ultra-reliable low-latency communication and massive machine-type connectivity specifications, purpose-built to replace or augment wired industrial Ethernet in mission-control environments. Private Networks command the dominant share of current deployment value as manufacturers seek deterministic performance isolated from public network congestion. Network Slicing represents the fastest-expanding technology dimension, enabling energy sector operators to partition bandwidth across critical grid monitoring and non-essential administrative traffic on shared infrastructure.
Regulatory Environment
The Federal Communications Commission in the United States, Germany's Federal Network Agency, and Japan's Ministry of Internal Affairs and Communications each govern local spectrum allocation for industrial 5G, with diverging approaches to localized licensing directly shaping vendor market access and enterprise deployment timelines. The European Union's Cybersecurity Act and its harmonized standards under the Radio Equipment Directive impose certification burdens that favor established infrastructure suppliers with dedicated compliance laboratories. Stakeholders must monitor pending spectrum reallocation proceedings and evolving cross-border data sovereignty requirements that will determine where edge computing nodes can legally process operational technology data.
Market Dynamics
Private spectrum licensing frameworks are compressing deployment timelines for factory automation, tilting capital allocation from public carrier contracts toward captive infrastructure that guarantees deterministic latency for robotic control systems.
Growth Catalysts
- EU AI Act:Germany's Federal Network Agency accelerates private 5G approvals when combined with AI-enabled predictive maintenance systems, reducing spectrum allocation review periods for industrial applicants.
- Smart Manufacturing:Automotive assembly plants in Stuttgart and Wolfsburg deploy end-to-end private networks to synchronize welding robots with sub-millisecond coordination.
- Network Slicing:Energy sector operators partition bandwidth across critical grid monitoring and administrative traffic, enabling shared infrastructure without performance compromise.
Market Restraints
- Radio Unit Supply Concentration:Baseband processor fabrication depends on advanced semiconductor foundries concentrated in Taiwan, creating vulnerability to geopolitical disruption.
- Localized Licensing Friction:Japan's Ministry of Internal Affairs and Communications imposes site-by-site inspection requirements that extend private network activation timelines by 8-14 months versus streamlined German procedures.
- Wired Ethernet Substitution Threshold:Existing industrial Ethernet installations in mature manufacturing facilities require complete cabling replacement to realize 5G mobility benefits, locking in hybrid architectures.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for electronics manufacturing create demand for private 5G in greenfield semiconductor fabrication facilities around Gujarat and Tamil Nadu.
- Edge-AI Convergence:Integration of on-premise inference engines with private radio access networks enables real-time quality inspection without cloud dependency.
- Neutral Host Infrastructure:Multi-tenant private networks serving adjacent industrial parks in South Korea's Ulsan corridor distribute capital burden across small and mid-sized component suppliers.
Industry Challenges
- OT-IT Integration Expertise:Operational technology engineers lack TCP/IP stack proficiency while information technology teams misunderstand deterministic industrial protocols, creating staffing bottlenecks for deployment projects.
- Cross-Border Data Sovereignty:Evolving requirements under GDPR and national cybersecurity frameworks restrict where edge computing nodes can process sensor telemetry, complicating multi-site deployments for multinational manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial 5G Market |
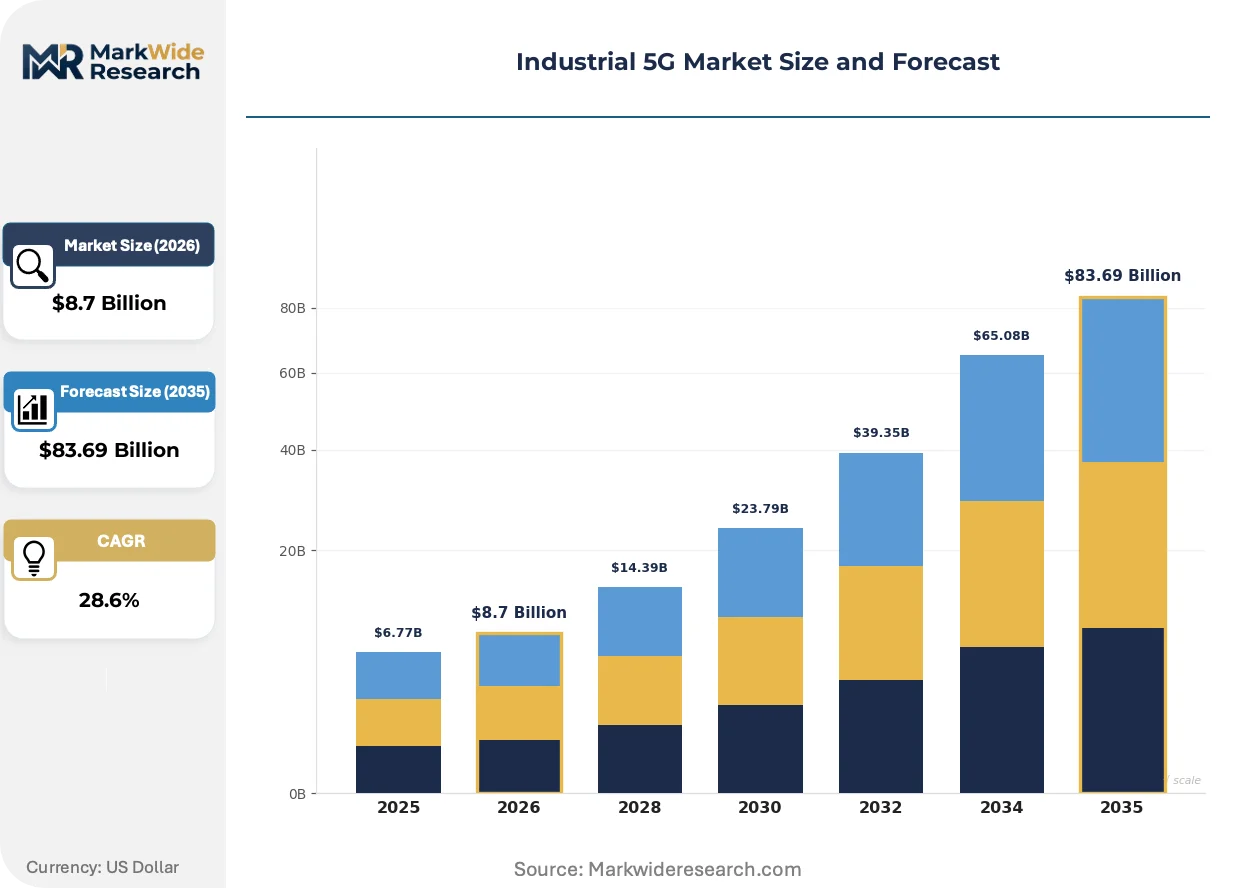
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $83.69 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing, Supply Chain, Asset Tracking, Remote Monitoring Technology: Private Networks, Public Networks, Hybrid Solutions, Network Slicing End User: Manufacturers, Energy Sector, Logistics Providers, Healthcare Facilities Solution: IoT Devices, Automation Systems, Data Analytics, Edge Computing |
| Companies Covered | Huawei Technologies Co., Ltd., Nokia Corporation, Telefonaktiebolaget LM Ericsson, Samsung Electronics, Qualcomm Technologies, Inc., ZTE Corporation, AT&T, Verizon Communications Inc., NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial 5G Market Emerging Trajectories
Time-sensitive networking overlays are merging with cellular radio layers, collapsing the historical separation between factory floor control systems and enterprise resource planning into unified connectivity fabrics.
Time-sensitive networking gateways are digitizing legacy fieldbus protocols into IP-native traffic streams that traverse private 5G bearers without protocol translation latency. Automotive powertrain manufacturers in Bavaria deploy these gateways at scale to connect programmable logic controllers directly to manufacturing execution systems. The technology is digitizing equipment monitoring that previously required dedicated wired drops, reducing cabling costs while preserving microsecond-level synchronization.
The EU Cybersecurity Act mandates Common Criteria certification for radio equipment deployed in critical infrastructure, imposing laboratory validation burdens that favor established infrastructure suppliers with dedicated compliance facilities. Industrial operators must now budget 12-18 months for certification cycles before network activation. Energy utilities in Scandinavia front-load these requirements into procurement specifications, pre-qualifying vendors based on existing certification portfolios rather than technical merit alone.
Buyer consortiums are aggregating demand across adjacent manufacturing facilities to negotiate shared private network infrastructure with neutral host operators. Germany's Industrie 4.0 clusters around Aachen and Munich pioneer this model, distributing spectrum leasing costs across machinery suppliers and final assemblers. The model concentrates procurement leverage for mid-sized operators that previously lacked capital for standalone licensed infrastructure, compressing vendor margins while expanding addressable deployment volume.
Industrial 5G Market Segmentation
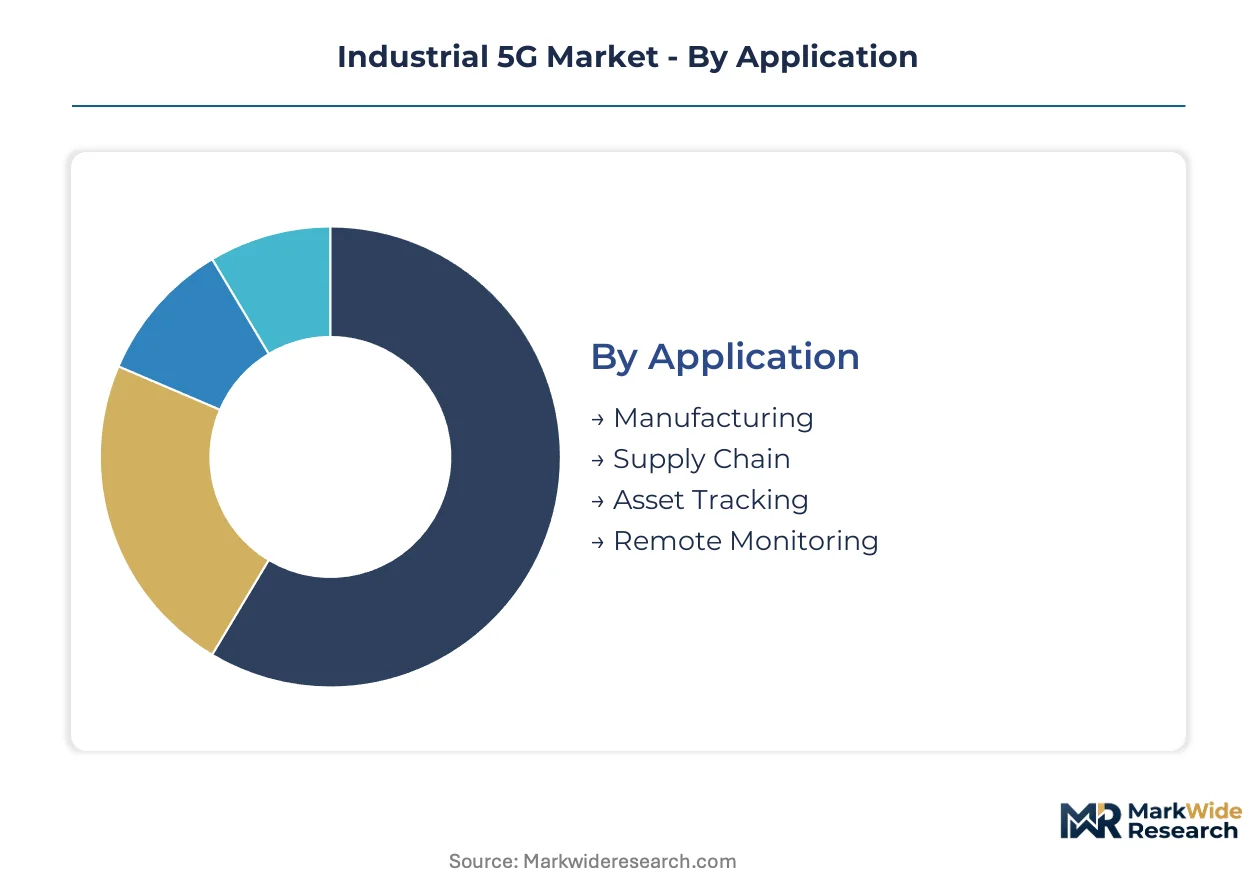
Segmentation in industrial 5G reveals how deployment complexity and service intensity vary sharply across use cases. Manufacturers prioritize deterministic latency for robotic control, while logistics operators emphasize mobility over precision, creating divergent vendor engagement models and support requirements.
Application:
After-sales service intensity escalates dramatically once private networks activate, with manufacturing deployments requiring 24/7 radio frequency optimization and supply chain implementations demanding continuous firmware patches for roaming handsets.
- Manufacturing:Welding robot synchronization and programmable logic controller integration demand sub-millisecond latency guarantees. Automotive assembly plants in Stuttgart and Wolfsburg anchor demand, driven by EU AI Act compliance requirements for predictive maintenance systems.
- Supply Chain:Warehouse automation and autonomous mobile robot coordination rely on seamless handover between radio cells. Logistics hubs in South Korea's Ulsan corridor concentrate investment, pressured by just-in-time delivery contracts that penalize connectivity downtime.
- Asset Tracking:Real-time location systems for high-value components use 5G positioning rather than Wi-Fi or UWB alternatives.
- Remote Monitoring:Offshore oil platforms and distributed solar farms transmit sensor telemetry over private bearers to reduce satellite dependency.
Manufacturing holds the largest share; momentum sits with Supply Chain as warehouse automation accelerates.
Technology:
Cost tier stratification separates turnkey private network bundles from sliced public infrastructure, with hybrid architectures occupying a middle band that trades capital efficiency against performance predictability.
- Private Networks:Licensed spectrum deployments deliver deterministic latency isolated from public congestion. Germany's Federal Network Agency streamlines approvals for industrial applicants, compressing activation timelines versus Japan's site-by-site inspection requirements.
- Network Slicing:Virtualized bandwidth partitions enable energy utilities to share infrastructure across critical grid monitoring and administrative traffic. Scandinavian operators lead deployment, front-loading EU Cybersecurity Act certification into procurement specifications.
- Public Networks:Carrier-managed services reduce capital burden for mid-sized operators with less stringent latency requirements.
- Hybrid Solutions:Combinations of private radio access networks with public core connectivity balance control against cost.
Private Networks dominate current deployment value; Network Slicing is climbing the fastest as shared infrastructure models mature.
End User:
Customer type dictates procurement sophistication, with energy sector buyers imposing rigorous certification requirements that extend sales cycles, while manufacturers prioritize speed-to-deployment over exhaustive vendor qualification.
- Manufacturers:Discrete and process industries deploy end-to-end connectivity to replace aging industrial Ethernet. Bavarian powertrain producers digitize legacy fieldbus protocols through time-sensitive networking gateways.
- Energy Sector:Grid operators and renewable asset managers partition bandwidth across operational and administrative traffic. EU Cybersecurity Act mandates impose 12-18 month certification cycles before network activation.
- Logistics Providers:Third-party warehouse operators and port authorities prioritize mobility for automated guided vehicles and yard management systems.
- Healthcare Facilities:Hospital systems deploy private networks for medical device connectivity and emergency communications.
Manufacturers command the largest installed base; energy sector procurement is gaining share fastest as grid modernization accelerates.
Solution:
Margin structure varies across the solution stack, with edge computing hardware capturing premium pricing against commoditized IoT sensors, while data analytics subscriptions generate recurring revenue that alters vendor cash flow profiles.
- Edge Computing:On-premise inference engines enable real-time quality inspection without cloud dependency. India's PLI scheme for electronics manufacturing stimulates demand in greenfield semiconductor fabrication facilities around Gujarat.
- Data Analytics:Predictive maintenance platforms process telemetry from 5G-connected sensors to forecast equipment failures. AI-enabled systems in Germany's Industrie 4.0 clusters reduce unplanned downtime for machinery suppliers.
- Automation Systems:Integrated control platforms synchronize robotic equipment over private radio bearers.
- IoT Devices:Ruggedized sensors and actuators transmit operational data over cellular rather than wired connections.
Edge Computing holds the largest share; Data Analytics is expanding most quickly as AI convergence deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Federal Network Agency accelerates private 5G approvals for industrial applicants, compressing spectrum allocation timelines and triggering competitive responses from regulators in South Korea and the United States.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg anchor demand for welding robot synchronization with sub-millisecond latency requirements. The EU AI Act combines with national spectrum licensing to reduce review periods for predictive maintenance deployments. Bavarian powertrain manufacturers digitize legacy fieldbus protocols through time-sensitive networking gateways at scale.
South Korea
Factory automation upgrades concentrate around the Ulsan and Gumi industrial corridor, driven by just-in-time delivery contracts that penalize connectivity downtime. The Ministry of Science and ICT governs local spectrum allocation with streamlined procedures that contrast with Japan's inspection-heavy approach. Busan port authorities prioritize mobility for automated guided vehicles and yard management systems.
United States
Mid-sized industrial operators gain competitive access through project finance and spectrum-leasing arrangements that previously required prohibitive capital for licensed infrastructure. The Federal Communications Commission governs local spectrum allocation with diverging approaches to localized licensing that shape vendor market access. Manufacturing clusters in the Midwest and Southeast deploy captive infrastructure to guarantee deterministic latency for robotic control systems.
Japan
Operational technology engineers face staffing bottlenecks as information technology teams misunderstand deterministic industrial protocols, complicating deployment projects. The Ministry of Internal Affairs and Communications imposes site-by-site inspection requirements that extend private network activation timelines by 8-14 months versus German procedures. Nagoya-area automotive suppliers hesitate on full 5G migration due to hybrid architecture lock-in from existing industrial Ethernet installations.
India
Greenfield semiconductor fabrication facilities around Gujarat and Tamil Nadu stimulate demand for private 5G under the Production-Linked Incentive scheme for electronics manufacturing. The Department of Telecommunications and TRAI govern spectrum allocation with frameworks still evolving for industrial applications. Maharashtra-based machinery suppliers explore neutral host models to distribute capital burden across adjacent manufacturing facilities.
Industrial 5G Market Vendor Landscape
On the supply side, the industry is consolidating around end-to-end infrastructure providers with dedicated compliance laboratories capable of navigating 12-18 month certification cycles under the EU Cybersecurity Act. Three strategic archetypes dominate: integrated baseband-radio unit suppliers that reduce deployment complexity, private wireless portfolio specialists anchoring large manufacturing deployments, and carrier-managed service providers targeting mid-sized operators with less stringent latency requirements. Competitive moves concentrate on strategic partnerships for spectrum access and portfolio diversification into edge computing hardware.
Among Asian-origin equipment suppliers, Huawei Technologies Co., Ltd. and ZTE Corporation exemplify the integrated infrastructure archetype, while Samsung Electronics occupies a position representing the premium-tier equipment supply segment for domestic factory automation. Nokia Corporation anchors the European vendor landscape as a private wireless portfolio specialist. These three companies collectively illustrate how geographic origin and corporate structure shape competitive positioning across divergent regulatory environments.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| Samsung Electronics |
| Qualcomm Technologies, Inc. |
| ZTE Corporation |
| AT&T |
| Verizon Communications Inc. |
| NEC Corporation |
| Others |
Supply Flow & Price Mechanics
Semiconductor foundry concentration in Taiwan creates single-source vulnerability that widens pricing spreads between EU Cybersecurity Act-certified equipment and uncertified alternatives while forcing buyers toward dual-sourcing strategies.
Pricing Analysis
Certification level under the EU Cybersecurity Act creates the primary spread between premium and standard tiers, with Common Criteria-validated radio units commanding substantial premiums over uncertified alternatives. Project-based pricing dominates turnkey private network deployments, while subscription models gain traction for managed slicing services. Price differentiation reflects after-sales bundling intensity, as manufacturing buyers demand 24/7 radio frequency optimization that logistics operators will not pay for. Cost compression in the standard tier intensifies because buyer consortiums aggregate procurement leverage across Germany's Industrie 4.0 clusters.
Supply Chain Analysis
Advanced baseband processor fabrication draws from semiconductor foundries concentrated in Taiwan, South Korea, and the United States, with mature radio unit assembly anchored in China and Vietnam. Gallium nitride power amplifiers, high-density substrate materials, and millimeter-wave beamforming chips constitute critical input dependencies. Single-source vulnerability in Taiwan-based advanced node production threatens equipment availability during geopolitical disruption. Distribution runs through direct vendor-to-enterprise channels for large manufacturing deployments, with systems integrators serving mid-sized operators in India's emerging industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbents: the EU Cybersecurity Act's 12-18 month certification cycles create switching costs that lock buyers into established supplier relationships.
For Market Incumbents: Harden compliance infrastructure by expanding dedicated certification laboratory capacity ahead of anticipated EU AI Act convergence with radio equipment standards. Deepen backward integration into edge computing hardware to capture premium pricing from AI-enabled predictive maintenance deployments. Counter emerging neutral host operators by anchoring exclusive spectrum partnerships with Germany's Federal Network Agency. For New Entrants and Emerging Players: Pursue white-space opportunities in India's greenfield semiconductor fabrication facilities around Gujarat and Tamil Nadu, where Production-Linked Incentive scheme subsidies reduce capital barriers for private 5G deployment. Target mid-sized machinery suppliers in Maharashtra exploring shared infrastructure models. Lead with edge-AI convergence propositions that bypass incumbent radio certification advantages through software-defined differentiation. For Investors and Strategic Acquirers: The market sits at a regulatory-consolidation phase that favors vertically integrated infrastructure suppliers with captive compliance capabilities. Long-term viability hinges on spectrum policy convergence across the European Union, United States, and East Asian industrial economies. Acquisition focus should center on edge computing hardware specialists with existing manufacturing customer relationships. Watch for inflection signals in India's Department of Telecommunications framework finalization for industrial spectrum allocation.| Strategic Initiative | Industry Significance |
|---|---|
| EU Cybersecurity Act Certification Investment | Common Criteria validation locks in procurement preference from Scandinavian energy utilities and German automotive clusters. |
| Edge-AI Hardware Integration | On-premise inference engines capture premium pricing from Bavarian powertrain manufacturers demanding real-time quality inspection. |
| Neutral Host Infrastructure Partnership | Multi-tenant models distribute capital burden across South Korea's Ulsan corridor component suppliers. |
| Spectrum Access Exclusive Arrangement | Direct licensing relationships with Germany's Federal Network Agency compress activation timelines versus Japanese procedures. |
| Time-Sensitive Networking Gateway Development | Protocol digitization capabilities reduce cabling costs for Stuttgart automotive assembly plants migrating from fieldbus systems. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, engaging private network deployment directors at automotive assembly plants, spectrum licensing officers at Germany's Federal Network Agency, procurement leads at South Korean logistics hubs, and edge computing hardware engineers. Secondary validation drew from FCC spectrum allocation proceedings, EU Cybersecurity Act certification registries, TRAI industrial framework consultations, and SEC filings from listed infrastructure suppliers. Bottom-up deployment volume estimates triangulated against top-down spectrum licensing data.
Calibration against historical private network activation timelines anchored growth projections across the analysis window. Segmentation dimensions modeled include application type, technology architecture, end-user industry, and solution component. CAGRs derived from equipment shipment trajectories, licensing fee structures, and service revenue attach rates. Forecast inputs incorporated EU AI Act implementation schedules and India's PLI scheme disbursement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers into private radio access networks would shift outcomes substantially. Cross-checking against FCC CBRS deployment databases and Germany's BNetzA licensing registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless Access Point Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
5G Small Cell Market
Wireless Technologies
Li-Fi Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
Fixed LTE Wireless Broadband Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Wimax Market
Wireless Technologies
Wireless Telecommunication Services Market
Wireless Technologies
Wireless Charger Market