
 Fixed Wireless Access (5G/Wttx/LTE) Market | 2026-2036
Fixed Wireless Access (5G/Wttx/LTE) Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Wireless Access (5G/Wttx/LTE) Market Foresight
Gigabit-tier throughput specifications is redrawing competitive benchmarks across the Fixed Wireless Access landscape. Nokia leverages its end-to-end portfolio spanning massive MIMO radios to cloud-native core platforms, sustaining R&D intensity in sub-6 GHz and mmWave integration. Samsung Electronics anchors its position through vertical manufacturing of 5G baseband chipsets and radio units, while Huawei Technologies competes on deployment scale across emerging markets with integrated WTTx solutions.
Fixed Wireless Access denotes a broadband delivery architecture where radio links substitute physical cable or fiber infrastructure between provider access points and customer premises equipment, typically operating at frequencies from 600 MHz to 39 GHz with throughput targets exceeding 100 Mbps downstream. The technology serves municipalities, enterprises, and residential clusters where trenching costs or geographic barriers impede wired deployment. 5G NR segments command premium positioning due to spectral efficiency gains and latency profiles suited to enterprise SLA requirements, while CPE-based deployment modes dominate volume economics through standardized indoor gateway form factors. WTTx legacy infrastructure retains material installed base across Central European and Southeast Asian markets, creating parallel upgrade revenue streams alongside greenfield 5G builds.
The FCC's Broadband DATA Act and spectrum auction frameworks in the United States shape infrastructure investment timelines by clarifying license tenure and build-out obligations, while the European Union's Gigabit Infrastructure Act establishes cross-border coordination standards for wireless backhaul frequencies. India's TRAI mandates on QoS benchmarks and the Department of Telecommunications' spectrum harmonization directives further constrain equipment certification pathways. Stakeholders must monitor mid-band refarming decisions and national security screening protocols for vendor eligibility, as these mechanisms determine addressable market scope and supply chain configuration across deployment cycles.
Market Dynamics
Spectrum reallocation mandates from the FCC in the United States and Ofcom in the United Kingdom are compressing deployment timelines for millimeter-wave infrastructure, forcing equipment vendors to accelerate sub-6 GHz and mmWave integration roadmaps.
Growth Catalysts
- BharatNet Program Extensions:India's rural broadband initiative is accelerating wireless last-mile penetration where fiber trenching costs remain prohibitive for village clusters.
- Massive MIMO Radio Deployment:Base station architecture upgrades are expanding cell edge throughput for residential subscribers in suburban zones.
- CEA Grid Modernization Directives:India's power sector mandates are creating co-location opportunities for FWA backhaul on utility transmission infrastructure.
Market Restraints
- Millimeter-Wave Propagation Limitations:Line-of-sight requirements and rain fade sensitivity constrain deployment economics in tropical and mountainous terrain.
- Semiconductor Supply Concentration:Advanced baseband chipset fabrication depends on a concentrated foundry base in East Asia, creating input volatility.
- Right-of-Way Regulatory Friction:Municipal permitting timelines for small cell siting extend deployment cycles in dense urban corridors.
Strategic Opportunities
- Enterprise SLA Convergence:5G NR latency specifications are opening manufacturing and logistics applications previously served by leased fiber.
- WTTx Upgrade Revenue Streams:Legacy CPE installed bases across Central Europe and Southeast Asia create parallel hardware refresh markets.
- TRAI QoS Benchmark Harmonization:India's service quality mandates are standardizing performance thresholds that favor integrated solution providers.
Industry Challenges
- RF Engineering Talent Scarcity:mmWave network design and propagation modeling expertise remains concentrated among a limited specialist pool.
- Multi-Band Certification Complexity:Equipment validation across 600 MHz to 39 GHz ranges extends regulatory approval timelines in multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Wireless Access (5G/Wttx/LTE) Market |
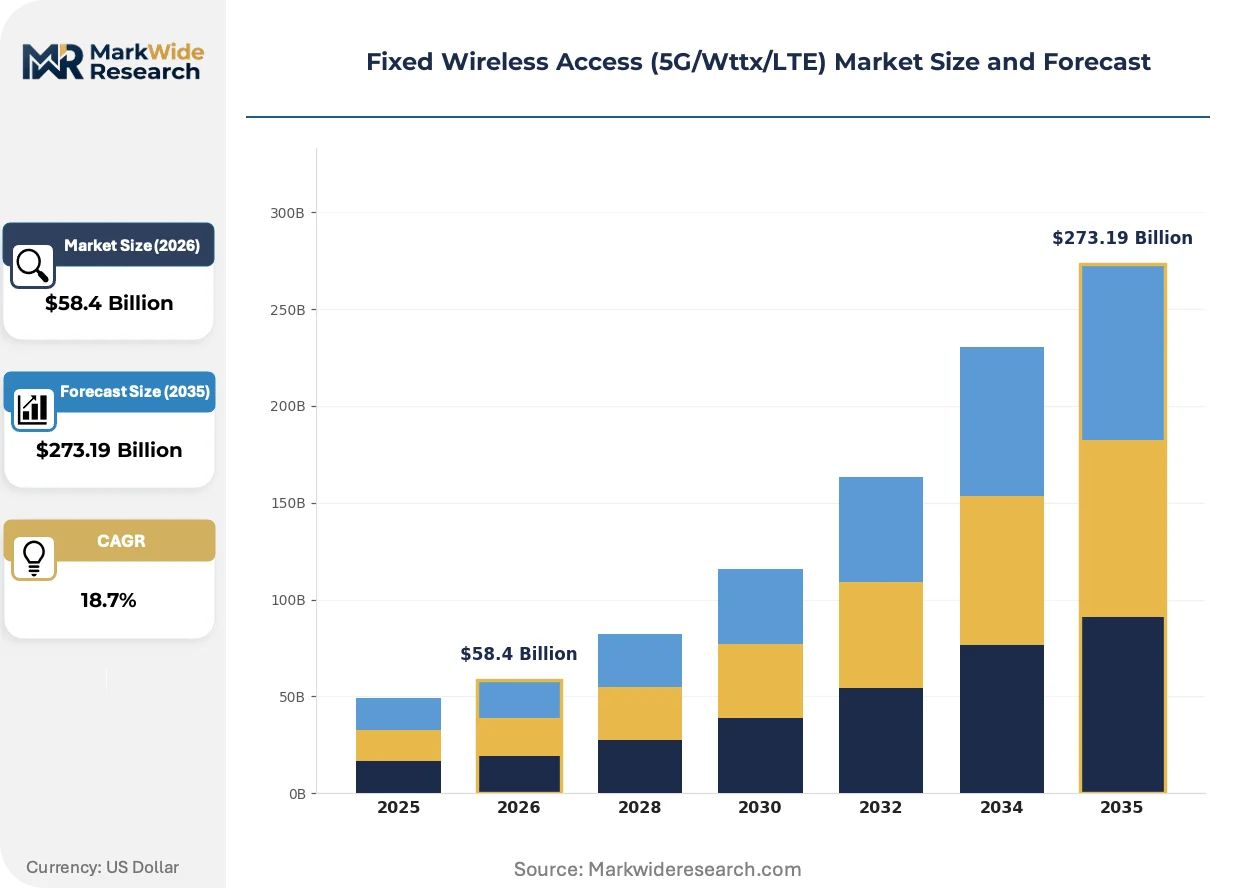
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $273.19 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 5G NR, LTE Advanced, Wi-Fi 6, WTTx, Massive MIMO, mmWave Deployment Mode: Outdoor Fixed, Indoor Fixed, CPE-based, Integrated Access, Satellite Augmented, Cloud-managed Application: Broadband Internet, Enterprise Connectivity, Smart Grid, Rural Access, Video Streaming, IoT Backhaul End User: Residential Subscribers, Small Offices, Municipal Networks, Public Safety Agencies, Educational Institutions, Hospitality Services |
| Companies Covered | Nokia, Samsung Electronics, Huawei Technologies, Telefonaktiebolaget LM Ericsson, ZTE Corporation, Qualcomm Technologies, NEC Corporation, CommScope, Airspan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Wireless Access (5G/Wttx/LTE) Market Shifts & Advancements
Radio frequency integration and policy harmonization are compressing equipment form factors while expanding addressable spectrum. Three developments are restructuring deployment economics and competitive positioning.
Active antenna systems with integrated transceivers are replacing discrete component architectures in customer premises equipment. Rural and suburban residential installers are specifying these units for simplified truck-roll deployments. The technology is miniaturizing outdoor unit dimensions while consolidating installation labor requirements.
REACH substance restrictions and EU Green Deal circularity mandates are altering base station material specifications for equipment marketed in Europe. Manufacturers are reformulating printed circuit board substrates and enclosure plastics to maintain market access. Outdoor radio units destined for European deployment face the most intensive compliance redesign cycles.
Service bundling unbundling is separating broadband connectivity from legacy voice and video packages among price-sensitive residential segments. Direct-to-consumer online channels and retail electronics partnerships are displacing traditional telecom distribution arrangements. This pattern is most visible in India's competitive metropolitan markets where Reliance Jio's digital-first acquisition model has reset subscriber onboarding expectations.
Fixed Wireless Access (5G/Wttx/LTE) Market Segmentation
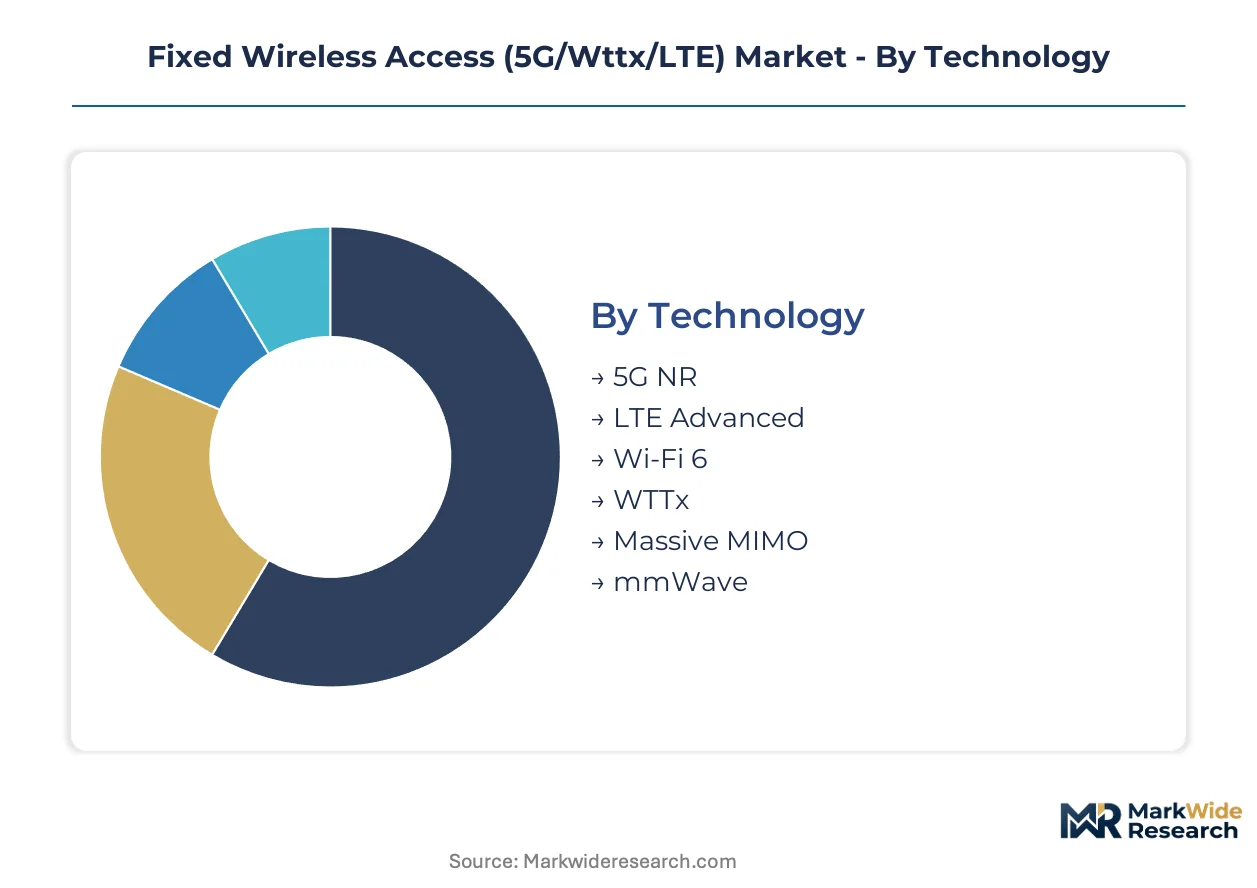
Technology choices determine spectrum licensing costs and equipment vendor selection. Deployment modes shape capital intensity per subscriber. Application mix influences service-level agreement structures. End-user categories dictate distribution channel configuration and customer acquisition economics.
Technology:
Channel distribution varies sharply by spectrum band—sub-6 GHz equipment flows through carrier procurement channels, while mmWave solutions concentrate in direct vendor relationships with tower companies.
- 5G NR:New Radio specifications deliver spectral efficiency gains through advanced modulation schemes and beamforming. Demand concentrates in Indian metropolitan circles where Reliance Jio's network densification creates volume procurement. TRAI's QoS mandates favor integrated 5G core solutions that simplify compliance certification.
- mmWave:Millimeter-wave systems operate above 24 GHz with gigabit throughput potential but require line-of-sight propagation. Deployment concentrates in suburban United States markets where FCC auction licenses for 28 GHz and 39 GHz bands have clarified build-out obligations. Rain fade sensitivity limits tropical geography penetration.
- LTE Advanced:Carrier aggregation and enhanced MIMO extend 4G infrastructure utility.
- Wi-Fi 6:OFDMA scheduling improves indoor spectrum efficiency for dense residential clusters.
- WTTx:Legacy TDD-LTE platforms retain installed base across Central European utilities.
- Massive MIMO:64T64R antenna arrays expand cell edge capacity for suburban residential zones.
By volume, LTE Advanced leads through legacy infrastructure reuse. By growth pace, 5G NR is gaining share fastest through greenfield spectrum allocations.
Deployment Mode:
Cost tier separation drives channel structure—outdoor fixed units command project-based sales through systems integrators, while cloud-managed offerings flow through software subscription channels.
- CPE-based:Customer premises equipment in standardized indoor gateway form factors enables retail electronics distribution and direct-to-consumer online channels. Volume concentrates in Indian metropolitan markets where Reliance Jio's digital-first acquisition model has reset subscriber onboarding expectations. Service bundling unbundling accelerates standalone broadband sales.
- Outdoor Fixed:Pole-mounted and rooftop radio units require professional installation and truck-roll deployment. Demand clusters in United States suburban zones where fiber-to-the-home trenching costs exceed wireless last-mile economics. FCC Broadband DATA Act mapping requirements clarify underserved addressable market scope.
- Indoor Fixed:Self-install window units reduce deployment labor for apartment dwellers.
- Integrated Access:Converged small cell and FWA platforms suit municipal network tenders.
- Satellite Augmented:Hybrid terrestrial-satellite backhaul extends coverage to remote terrain.
- Cloud-managed:Centralized orchestration platforms enable managed service provider resale channels.
By volume, CPE-based deployment leads through retail channel penetration. By margin structure, cloud-managed solutions show the steepest expansion trajectory.
Application:
Application type determines performance tier requirements—enterprise connectivity commands premium pricing through SLA guarantees, while rural access competes on coverage reach.
- Broadband Internet:Residential high-speed access represents the volume foundation of FWA economics. Demand concentrates in Indian village clusters where BharatNet program extensions subsidize wireless last-mile penetration. Fiber trenching cost barriers exceed wireless deployment by an order of magnitude in these geographies.
- Enterprise Connectivity:Dedicated bandwidth with latency guarantees serves manufacturing and logistics facilities. Adoption clusters in United States industrial corridors where 5G NR specifications displace leased fiber for private network deployment. FCC spectrum auction frameworks clarify license tenure for vertical industry use.
- Smart Grid:Utility telemetry backhaul creates co-location revenue on power transmission infrastructure.
- Rural Access:Universal service obligation fulfillment drives subsidized deployment in underserved geographies.
- Video Streaming:Sustained throughput requirements shape evening peak capacity planning.
- IoT Backhaul:Low-rate sensor aggregation suits narrowband-IoT overlay architectures.
By subscriber count, broadband internet leads. By revenue per connection, enterprise connectivity is climbing the fastest.
End User:
Customer type shapes procurement modality—municipal networks flow through public tender processes, while residential subscribers convert through retail and digital channels.
- Residential Subscribers:Individual households in suburban and rural zones constitute the demand base for mass-market FWA penetration. Volume concentrates in Indian metropolitan and peri-urban circles where price-sensitive segments respond to direct-to-consumer acquisition models. TRAI QoS benchmarks standardize performance thresholds that favor integrated solution providers.
- Municipal Networks:City-owned infrastructure serves public facilities and underserved neighborhoods. Procurement concentrates in United States markets where FCC Rural Digital Opportunity Fund subsidies offset capital deployment. Build-out obligations attach to spectrum license awards.
- Small Offices:SOHO segments blend residential pricing with business-grade reliability needs.
- Public Safety Agencies:First responder networks require hardened equipment and priority access mechanisms.
- Educational Institutions:Campus connectivity tenders favor multi-year service contracts with equipment refresh provisions.
- Hospitality Services:Hotel and venue operators seek converged guest and operational network platforms.
By connection volume, residential subscribers lead. By contract value expansion, municipal networks are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive residential subscribers in Indian village clusters drive volume procurement, while United States enterprises pay premiums for low-latency SLA guarantees. Regulatory frameworks in both markets compress deployment timelines through spectrum clarity and subsidy programs. Geographic barriers and trenching economics determine where wireless last-mile solutions displace fiber alternatives.
United States
Suburban residential zones constitute the core demand base where fiber-to-the-home deployment costs exceed wireless economics. The FCC's Broadband DATA Act mapping requirements and spectrum auction frameworks for 28 GHz and 39 GHz bands clarify build-out obligations and license tenure. Deployment concentrates in metropolitan peripheries where small cell siting permits and municipal network tenders create procurement volume for outdoor fixed radio units.
India
Rural village clusters and peri-urban circles generate mass-market subscriber acquisition through price-sensitive digital-first onboarding models. TRAI QoS mandates and BharatNet program extensions subsidize wireless last-mile penetration where fiber trenching costs remain prohibitive. Maharashtra and Gujarat industrial corridors see enterprise connectivity adoption, while Karnataka's technology hub drives 5G NR equipment certification and integration testing.
Germany
Central European WTTx legacy infrastructure creates parallel upgrade revenue streams alongside greenfield 5G builds. The EU Green Deal circularity mandates and REACH substance restrictions alter base station material specifications, forcing compliance redesign cycles for outdoor radio units. North Rhine-Westphalia's industrial belt and Bavaria's manufacturing clusters demand enterprise SLA convergence for private network deployment.
United Kingdom
Suburban residential markets and municipal network tenders drive CPE-based volume through retail electronics distribution channels. Ofcom spectrum reallocation policies unlock millimeter-wave bands for commercial FWA use, compressing equipment vendor integration roadmaps. Greater London's dense urban corridors face right-of-way regulatory friction for small cell siting, extending deployment cycles compared to regional town clusters.
South Korea
Metropolitan 5G densification and enterprise private network deployment anchor equipment procurement from semiconductor-integrated vendors. The national spectrum harmonization directives and MIIT-aligned certification pathways constrain vendor eligibility and supply chain configuration. Seoul Capital Area's manufacturing and logistics facilities displace leased fiber with 5G NR latency specifications, while Busan-Ulsan industrial zones drive massive MIMO radio deployment for cell edge throughput expansion.
Fixed Wireless Access (5G/Wttx/LTE) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Fixed Wireless Access landscape. The market structure consolidates around integrated telecommunications equipment vendors with end-to-end portfolios spanning radio access to core network platforms. Three archetypes dominate: spectrum-integrated semiconductor suppliers, vertically consolidated infrastructure vendors, and regional deployment specialists with emerging market scale. Competitive moves center on sub-6 GHz and mmWave integration roadmaps, alongside strategic partnerships for utility co-location backhaul infrastructure.
Within the integrated infrastructure tier, Nokia and Samsung Electronics exemplify divergent strategic positions. Nokia leverages its Finland-based corporate structure to anchor European regulatory compliance and cloud-native core platform development. Samsung Electronics occupies a position as a vertically consolidated Korean vendor with captive semiconductor fabrication and radio unit manufacturing. Huawei Technologies, despite supply chain constraints, represents the emerging market scale archetype through integrated WTTx solution deployment across Asia-Pacific and African markets where price-performance ratios dominate procurement criteria.
| Leading Market Players |
|---|
| Nokia |
| Samsung Electronics |
| Huawei Technologies |
| Telefonaktiebolaget LM Ericsson |
| ZTE Corporation |
| Qualcomm Technologies |
| NEC Corporation |
| CommScope |
| Airspan |
| Others |
Supply & Pricing Matrix
Massive MIMO radio manufacturing scale in South Korea and Taiwan establishes cost floors that cascade through sub-6 GHz and mmWave equipment tiers, concentrating margin leverage among vertically integrated semiconductor vendors while compressing pricing power for pure-play radio unit assemblers serving price-sensitive Indian carriers.
Pricing Analysis
FCC spectrum auction frameworks dictate the pricing tier structure across United States deployment markets, separating premium outdoor fixed units with professional installation from economy CPE-based offerings through retail electronics channels. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade—FCC Part 30 compliance for mmWave versus sub-6 GHz flex—and volume scale from BharatNet bulk procurement. Price erosion runs through the economy tier as Reliance Jio's digital-first acquisition model resets subscriber onboarding expectations. Municipal networks in United States suburban zones show least price sensitivity due to Rural Digital Opportunity Fund subsidy offsets, while Indian village clusters demand maximum cost compression.
Supply Chain Analysis
Baseband chipset inventory cycles stretching 26-32 weeks force equipment vendors to pre-position radio unit stockpiles ahead of TRAI-mandated deployment windows. Taiwan, South Korea, and China anchor advanced semiconductor fabrication for 5G NR modems and massive MIMO beamforming processors, drawing from gallium nitride substrates and high-frequency laminates. Single-source vulnerability concentrates in mmWave RF front-end modules where Qualcomm Technologies and Samsung Electronics maintain captive supply. Distribution runs through carrier procurement channels for sub-6 GHz equipment and direct vendor relationships with United States tower companies for mmWave small cell deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Indian national carriers and United States municipal aggregators, fragmenting equipment vendor pricing leverage as procurement volumes consolidate under Reliance Jio and FCC-subsidized rural electric cooperatives.
For Market Incumbents: Fortify sub-6 GHz and mmWave integration roadmaps through backward integration into RF semiconductor design, defending against emerging pure-play massive MIMO specialists from South Korea. Prioritize TRAI QoS certification maintenance as the priority lever, since India's harmonized performance thresholds favor integrated solution providers with cloud-native core platforms. Capacity addition in Tamil Nadu and Karnataka assembly facilities reduces exposure to East Asian logistics chokepoints. For New Entrants and Emerging Players: FCC Part 30 fast-track certification for 28 GHz and 39 GHz bands opens white-space entry for mmWave outdoor fixed units targeting United States suburban zones where fiber-to-the-home trenching costs exceed wireless economics. WTTx upgrade revenue streams across Central European utilities present the most penetrable legacy refresh segment. Go-to-market traction requires direct relationships with tower companies rather than carrier procurement channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional deployment specialists with emerging market scale and utility co-location backhaul infrastructure. Long-term viability hinges on 5G NR equipment certification breadth across FCC, Ofcom, and TRAI jurisdictions simultaneously. Acquisition target archetype: vertically consolidated vendors with captive semiconductor fabrication and radio unit manufacturing. Signal to watch: mid-band refarming decisions in India and spectrum harmonization directives constraining vendor eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Sub-6 GHz and mmWave Integration Roadmap | Nokia and Samsung Electronics sustain R&D intensity to meet FCC build-out obligations. |
| Utility Co-Location Backhaul Partnership | India's CEA grid modernization mandates create parallel revenue on power transmission infrastructure. |
| Cloud-Managed CPE Platform Launch | Reliance Jio's digital-first acquisition model resets subscriber onboarding expectations in metropolitan India. |
| REACH Compliance Redesign Cycle | EU Green Deal circularity mandates force base station material specification changes for European market access. |
| TRAI QoS Certification Investment | Harmonized performance thresholds favor integrated solution providers over pure-play radio vendors. |
Research Methodology
A standing panel of network planning executives at tier-1 carriers, RF engineering directors at infrastructure vendors, procurement leads at tower companies, and regulatory affairs specialists at semiconductor suppliers provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC spectrum auction filings, TRAI QoS benchmark publications, EU Green Deal implementation directives, and equipment vendor SEC disclosures. Bottom-up subscriber deployment models triangulated against top-down spectrum licensing revenue projections.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation dimensions spanning technology generation, deployment mode capital intensity, application performance tier, and end-user procurement modality. CAGRs derived from equipment shipment run-rates and average selling price trajectories, incorporating mmWave propagation constraints in tropical geographies and semiconductor supply concentration volatility as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained spectrum reallocation momentum and stable East Asian foundry capacity; material deviation in FCC mid-band auction timing or trade restriction expansion would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Global Bluetooth Audio Codec Market
Wireless Technologies
Light Fidelity Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Industrial Wireless Solution Market