
 Phoropters Market | 2026-2036
Phoropters Market Size, Share, and Industry Trends Forecast 2026-2036
Phoropters Market Intelligence
The customer base for phoropters is consolidating as large hospital networks and private equity-backed optometry chains centralize procurement. EssilorLuxottica leverages its extensive optical retail and wholesale channels to drive sales. Topcon specializes in integrated diagnostic systems that connect phoropters with other examination tools. Carl Zeiss competes on the basis of its premium brand reputation and advanced digital optics technology.
A phoropter is an ophthalmic instrument that contains a series of lenses used to measure an individual's refractive error. It allows an optometrist to present different lens powers and combinations to determine the optimal prescription for corrective eyewear. Automated phoropters are displacing traditional manual units, driven by workflow efficiency and data connectivity. Optometry clinics and ophthalmology centers remain the dominant end-user segments, with hospitals showing steady demand for integrated systems.
Product commercialization is governed by medical device regulations. In the United States, the FDA oversees market clearance, while in Europe, phoropters must comply with CE marking requirements under the Medical Device Regulation (MDR). These frameworks impose strict standards for manufacturing quality and clinical performance. The critical decision for instrument manufacturers is how to allocate R&D between high-end digital features and cost-effective models for emerging economies.
Market Dynamics
The integration of digital phoropters with Electronic Health Record (EHR) systems is the central force shaping the market. This shift prioritizes data connectivity and workflow efficiency over standalone instrument performance, altering competitive dynamics and R&D focus.
Growth Catalysts
- Automated Refraction:The adoption of automated phoropters accelerates refraction times in high-volume optometry clinics, improving patient throughput and operational efficiency. This technology reduces operator dependency and standardizes examination quality.
- Healthcare Infrastructure Expansion:Rapid development of ophthalmology centers and optical retail chains in emerging economies, particularly in China and India, creates substantial new demand for both manual and digital phoropter units.
- Telehealth Reimbursement Policies:Favorable reimbursement policies for tele-optometry services are encouraging investment in remotely operable digital phoropters, expanding access to eye care in underserved or rural areas across multiple geographies.
Market Restraints
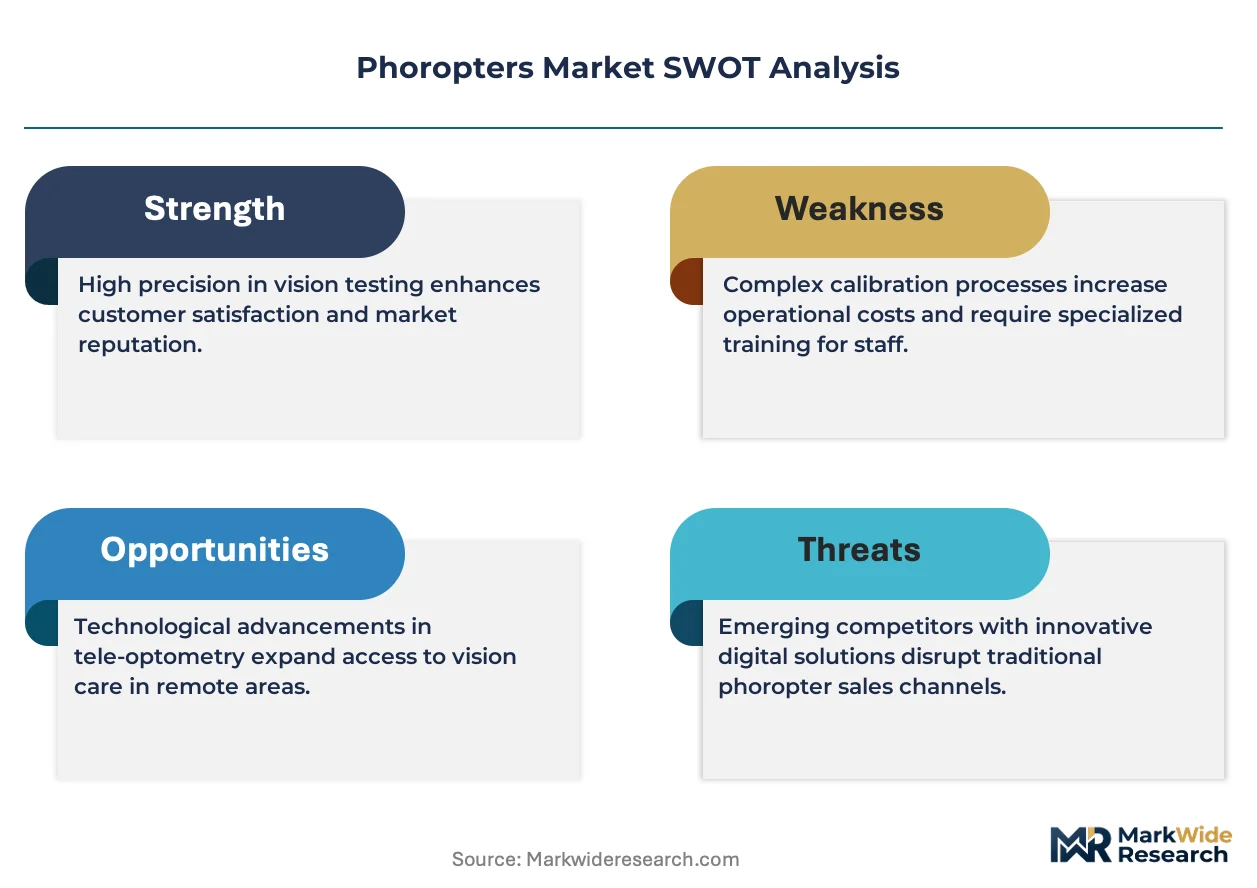
- High Capital Cost:The significant upfront investment required for advanced automated phoropters, especially those with integrated diagnostic modules, acts as a barrier for small, independent optometry practices and clinics in price-sensitive markets.
- Availability of Refurbished Units:A robust secondary market for refurbished manual and early-generation automated phoropters provides a lower-cost alternative, slowing the replacement cycle and capping new unit sales, particularly in developing regions.
- Stringent Regulatory Hurdles:Compliance with medical device regulations, such as the FDA's clearance process in the United States and the EU's MDR, imposes significant R&D costs and lengthy time-to-market for new instrument innovations.
Strategic Opportunities
- Integration with AI Diagnostics:Combining phoropter data with AI-powered diagnostic platforms for early disease detection offers a significant value-add, creating a new premium product tier for integrated eye care systems.
- Southeast Asian Markets:Markets like Vietnam and Indonesia, with their growing middle class and expanding private healthcare sector, represent underpenetrated regions for modern optometry equipment, offering new growth avenues beyond China.
- Subscription-Based Models:Shifting from outright capital sales to hardware-as-a-service (HaaS) or subscription models can lower the adoption barrier for smaller clinics, creating recurring revenue streams and locking in customers.
Industry Challenges
- Legacy System Interoperability:Ensuring seamless data exchange between new digital phoropters and diverse, often outdated, Electronic Health Record (EHR) and practice management systems remains a significant technical and implementation hurdle for vendors.
- Technician Training Gap:The transition to automated and digital phoropters requires retraining ophthalmic technicians and optometrists, creating a skills gap and implementation friction within clinical workflows, which can slow adoption rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phoropters Market |
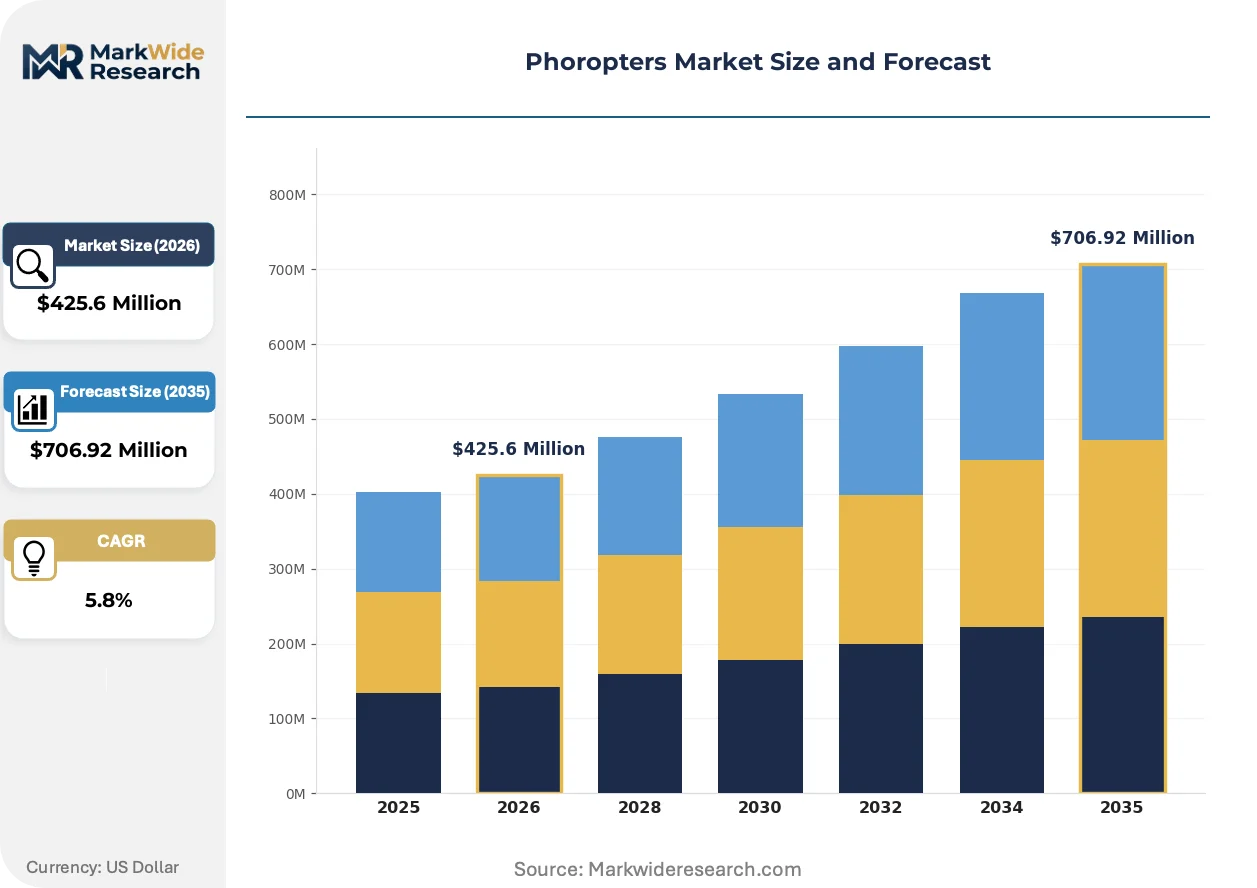
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $706.92 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automated, Digital, Portable Application: Eye Examination, Vision Screening, Refraction Testing, Optometry Research End User: Optometry Clinics, Ophthalmology Centers, Hospitals, Vision Care Labs Technology: Lens Dial, Digital Interface, Motorized Lens System, LCD Display |
| Companies Covered | EssilorLuxottica, Huvitz, Topcon, Rexxam, Marco Ophthalmic, Nidek, Reichert Technologies, Luneau Technology, Carl Zeiss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phoropters Market Strategic Shifts & Innovations
The evolution of phoropters is defined by their transformation from standalone mechanical tools into connected data-capture devices. This shift emphasizes software, interoperability, and the ability to support new models of remote and integrated patient care.
Advanced digital phoropters feature tablet-based interfaces and wireless connectivity, allowing optometrists to control the refraction process from a distance. Large optometry chains and hospital networks are rapidly adopting these systems to standardize examination protocols and improve workflow. This technology is unifying the previously separate acts of refraction, data entry, and diagnostic review into a single, cohesive digital workflow connected to the central patient record.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on all ophthalmic instruments, including phoropters. This regulation increases the compliance burden and cost for manufacturers, favoring larger companies with dedicated regulatory affairs departments. Phoropter manufacturers targeting the European market must now provide more extensive technical documentation and clinical performance data, impacting product development timelines.
Centralized purchasing departments of large hospital networks and private equity-backed clinic chains are increasingly buying integrated eye-care suites rather than standalone instruments. This disrupts the traditional sales model targeting individual practitioners, favoring vendors who offer a complete ecosystem of connected diagnostic tools. This trend is most prominent in the United States and Western Europe, where healthcare consolidation is advanced.
Phoropters Market Segmentation
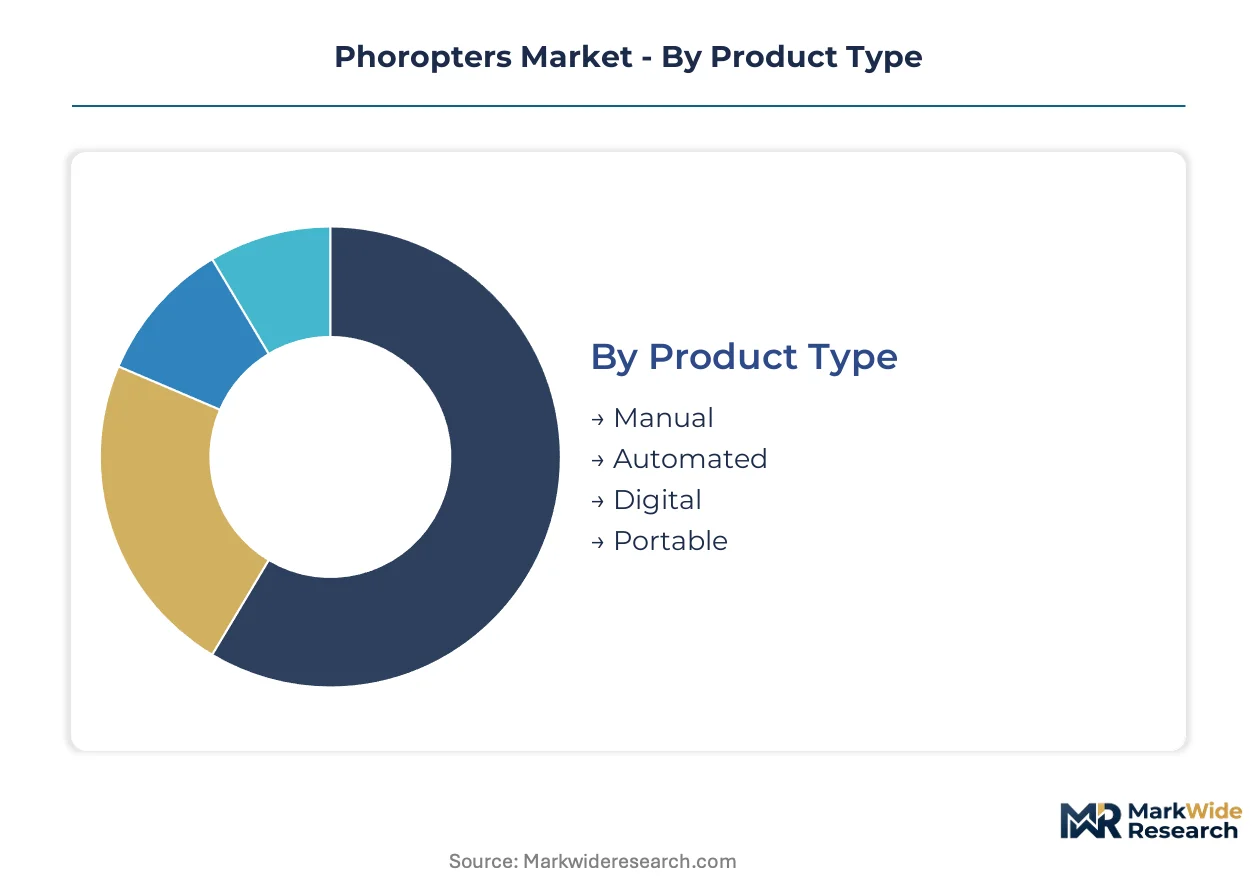
The phoropters market segmentation provides critical insights into the diverse needs of eye care professionals and the technological progression influencing instrument design. Understanding these distinct segments allows manufacturers to tailor product development and market strategies effectively. This granular view highlights where innovation and investment are most impactful across the ophthalmic sector.
Product Type:
Supply concentration in phoropters is shifting as manufacturers prioritize automated and digital units for enhanced workflow efficiency.
- Automated:These phoropters integrate motorized lens changes and often connect with other diagnostic equipment, reducing manual input and standardizing refraction procedures in high-volume clinics. Demand for automated units is concentrating in large optometry chains seeking operational consistency and faster patient throughput.
- Digital:Digital phoropters feature advanced software interfaces and often wireless connectivity, enabling remote control and seamless data transfer to electronic health records. These systems are highly valued in modern ophthalmology centers for their precision and ability to support tele-optometry services.
- Manual:Manual phoropters rely on physical lens rotation and adjustment by the operator, representing the traditional method for refractive error measurement.
- Portable:Portable phoropters offer compact, lightweight designs suitable for mobile clinics or outreach programs in remote areas, providing essential diagnostic capabilities.
Manual units absorb the bulk of installed capacity; digital phoropters are expanding most quickly.
Application:
The volume of examinations dictates phoropter application deployment across various clinical settings.
- Eye Examination:This primary application involves comprehensive assessment of a patient's visual acuity and refractive error, forming the core of routine ophthalmic care. Demand for general eye examination phoropters remains foundational across all end-user segments.
- Refraction Testing:Refraction testing specifically determines the precise lens power required to correct vision, a critical step in prescribing glasses or contact lenses. This application sees high utilization in optometry clinics and ophthalmology centers.
- Vision Screening:Vision screening applications focus on quick, preliminary assessments to identify potential visual problems, often used in schools or public health initiatives.
- Optometry Research:Phoropters are utilized in academic and clinical research settings to study visual perception, develop new diagnostic techniques, and evaluate novel corrective interventions.
Demand for eye examination remains foundational; optometry research is seeing increased investment.
End User:
Customer type significantly influences phoropter purchasing decisions and the feature sets prioritized by manufacturers.
- Optometry Clinics:These facilities specialize in primary eye care, including comprehensive eye exams, vision correction, and management of common eye conditions. Optometry clinics represent the largest customer base for both manual and automated phoropters.
- Ophthalmology Centers:Ophthalmology centers provide advanced medical and surgical eye care, often requiring sophisticated diagnostic equipment for complex cases. These centers prioritize high-precision digital phoropters with integration capabilities.
- Hospitals:Hospitals integrate phoropters within their broader diagnostic departments or specialized eye units, serving a diverse patient population with varied ophthalmic needs.
- Vision Care Labs:These specialized laboratories may use phoropters for calibration, quality control, or research and development of new optical devices and lenses.
Optometry clinics represent the largest user base; hospitals are integrating more advanced systems.
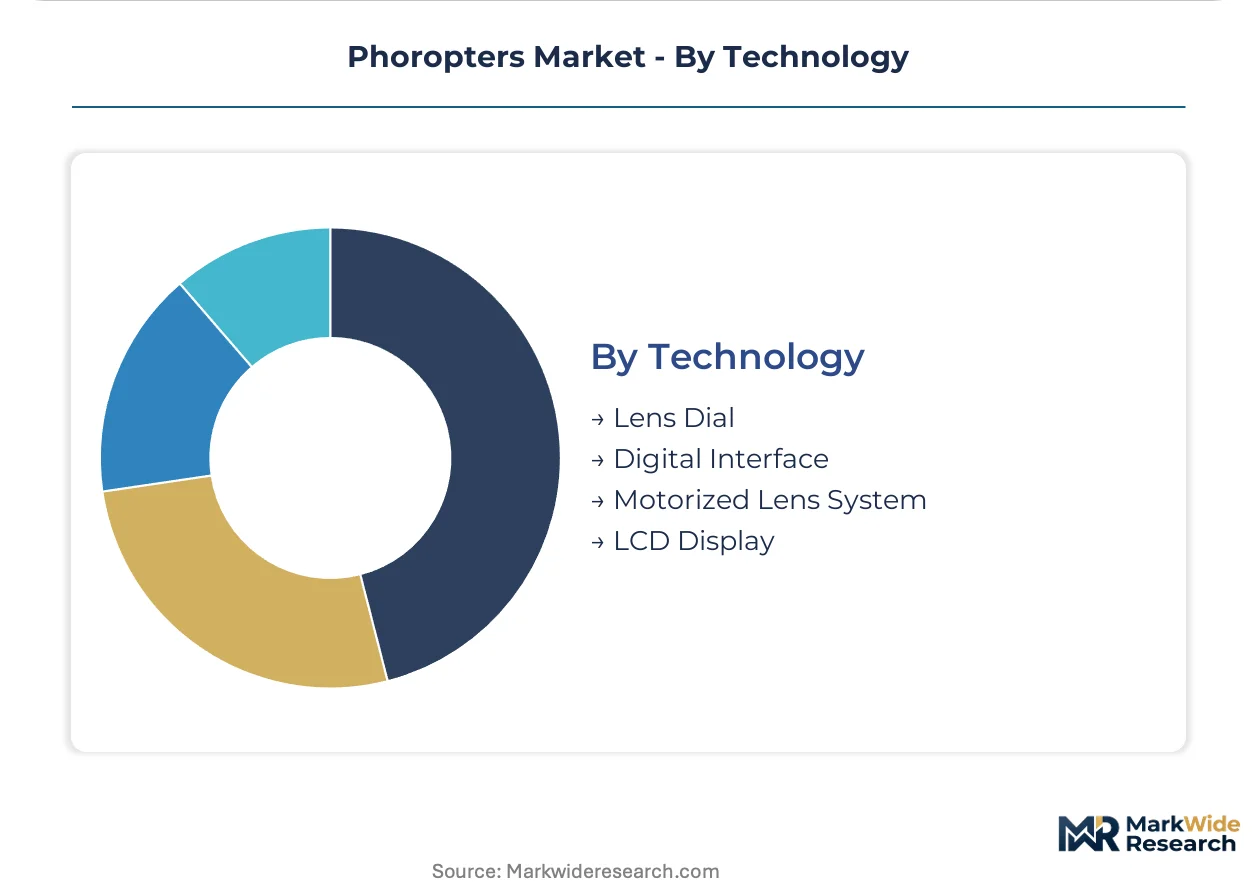
Technology:
Technology maturity drives distinct competitive dynamics within the phoropters market, influencing product lifecycles and R&D focus.
- Digital Interface:This technology provides a modern, intuitive user experience through touchscreens and software, enhancing control and data management for optometrists. Digital interfaces are critical for integration with EHR systems and remote operation.
- Motorized Lens System:Motorized lens systems allow for precise, automated changes in lens power and axis, reducing operator fatigue and improving examination speed and accuracy. This technology is a hallmark of advanced automated phoropters.
- Lens Dial:Lens dial technology involves manual rotation of physical dials to select different lenses, characteristic of traditional phoropter designs.
- LCD Display:LCD displays on phoropters provide clear, digital readouts of refractive values and other parameters, replacing older mechanical indicators.
Lens dial technology forms the historical base; digital interfaces define future development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for phoropters is consolidating as large hospital networks and private equity-backed optometry chains centralize procurement. This shift prioritizes integrated systems and workflow efficiency. Emerging economies like China are also witnessing significant demand due to expanding healthcare infrastructure.
China
China's market sees high demand from rapid healthcare infrastructure expansion and a large population needing eye care. The NMPA oversees medical device approval and market entry for phoropters. Major urban centers like Shanghai and Beijing are driving significant investment in new ophthalmology centers.
United States
The United States market experiences strong demand from consolidating optometry chains and the adoption of advanced digital phoropters. The FDA oversees market clearance processes for ophthalmic instruments. Healthcare networks in regions like California and New York centralize procurement for integrated eye care suites.
Germany
Germany's market for phoropters is driven by its premium brand reputation and advanced digital optics technology. CE marking requirements under the EU's MDR are critical for product compliance. Research and development hubs in Bavaria and Baden-Württemberg focus on innovative digital phoropter features.
India
India's market benefits from expanding optical retail chains and a growing middle class seeking eye care services. The CDSCO regulates medical devices and market authorization for phoropters. Metropolitan areas such as Mumbai and Delhi are experiencing rapid growth in private optometry clinics.
Vietnam
Vietnam presents demand from a growing middle class and an expanding private healthcare sector. The Ministry of Health regulates medical device imports and distribution. Ho Chi Minh City and Hanoi are seeing new investments in modern optometry clinics and diagnostic centers.
Phoropters Market Key Industry Players
European producers anchor one tier; Japanese specialists hold another, reflecting diverse market approaches. The phoropters market exhibits a tiered structure, with global conglomerates alongside specialized diagnostic system providers. Strategic archetypes include integrated optical solutions providers and premium digital optics manufacturers. Companies frequently engage in portfolio diversification, strategic partnerships, and geographic expansion to strengthen their market presence.
Within the integrated optical solutions segment, EssilorLuxottica represents a global player leveraging extensive optical retail and wholesale channels for market penetration. This strategy addresses the consolidating customer base of large hospital networks. Japanese-based Topcon exemplifies specialization in integrated diagnostic systems, connecting phoropters with other examination tools to offer comprehensive solutions. This approach caters to the demand for unified diagnostic workflows. German manufacturer Carl Zeiss occupies a position in premium digital optics technology, competing on its brand reputation and advanced features. This focus aligns with the increasing interest in high-end digital interfaces and precision.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Huvitz |
| Topcon |
| Rexxam |
| Marco Ophthalmic |
| Nidek |
| Reichert Technologies |
| Luneau Technology |
| Carl Zeiss |
| Others |
Cost & Logistics Intelligence
Digital phoropter certification ladders create a significant divergence in pricing and supply chain configurations. This bifurcation influences manufacturing complexity and market access across global regions.
Pricing Analysis
Volume-driven manual phoropters compete on price, while advanced digital units command higher margins. The dominant pricing structure is per-unit transactional, though subscription models are emerging. Price differentiation stems from brand premium, advanced digital features, and FDA/CE certification. Pricing softness in entry-level segments reflects the availability of refurbished units. Small independent optometry practices exhibit the highest price sensitivity.
Supply Chain Analysis
Skilled workforce availability in precision optics manufacturing centers like Japan and Germany influences phoropter production. Supply concentrates in these countries, alongside emerging manufacturing in China for cost-effective models. Key component dependencies include specialized optical lenses and sophisticated electronic interfaces. Stringent regulatory compliance, particularly with EU MDR, presents a structural supply chain risk. Distribution runs through direct sales to large hospital networks and specialized optical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phoropters market is entering a consolidation phase, driven by the significant capital investment required for advanced digital systems. This pressure is forcing smaller, less capitalized manufacturers to exit or be acquired.
For Market Incumbents: Acquire specialized software integration firms to overcome legacy system interoperability challenges. Consolidate market share by offering complete eye-care suites that bundle phoropters with other diagnostic tools. Invest heavily in R&D for AI diagnostics to differentiate premium offerings. This strategy addresses the threat from new entrants focusing on niche digital solutions.
For New Entrants and Emerging Players: AI-powered diagnostic integration offers a technology-first wedge into the premium segment. Target underpenetrated Southeast Asian markets like Vietnam with cost-effective, digital-ready portable phoropters. Develop subscription-based hardware-as-a-service models to lower adoption barriers for smaller clinics. This approach leverages the shift towards tele-optometry and remote care.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated eye care system providers or specialized software companies with strong data connectivity. Long-term viability, over the next five to ten years, hinges on firms that can unify diagnostic workflows and patient data. Prioritize acquisition targets with proven EHR interoperability or AI-driven diagnostic capabilities. A significant signal to watch is the accelerated adoption of hardware-as-a-service models.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate with AI Diagnostics | Creates a new premium product tier for integrated eye care systems. |
| Expand in Southeast Asian Markets | Captures new demand from a growing middle class and expanding private healthcare. |
| Develop Subscription Models | Lowers adoption barriers for smaller clinics, establishing recurring revenue streams. |
| Strengthen EHR Interoperability | Ensures seamless data exchange, improving workflow efficiency for large networks. |
| Secure CE Marking Compliance | Facilitates market entry and expansion within the highly regulated European Union. |
Research Approach
Document review covered regulatory filings from FDA and EMA, industry association reports, and academic research papers, complemented by interviews. Primary research involved discussions with optometrists, ophthalmologists, clinic procurement managers, and medical device engineers. This approach facilitated bottom-up data collection and top-down validation. Data triangulation ensured comprehensive market understanding and robust insights.
Historical market performance was cross-referenced with expert panel input to construct the forecast framework over the projection horizon. Segmentation dimensions modeled include product type, application, end user, technology, and regional healthcare infrastructure development. Compound Annual Growth Rates were derived from market dynamics and anticipated technology adoption. Key forecast inputs include global eye examination rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory changes or economic downturns. Forecasts reflect assumptions regarding technological adoption and healthcare infrastructure development. Material deviation in tele-optometry reimbursement policies warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Respiratory Devices Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Gastric Bands Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Public Access Automated External Defibrillators (Aeds) Market
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Sialendoscopes Market
Medical Devices
Colposcopes Market
Medical Devices
Smart Medical Loupes Market