
 Medical Germicidal Lamps Market | 2026-2036
Medical Germicidal Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Germicidal Lamps Market Foresight
Hospital-grade UV-C certification is unwinding legacy product lines across the medical germicidal lamps sector. American Ultraviolet leverages its American manufacturing base to sustain domestic supply commitments for healthcare procurement. Sankyo Denki anchors Asian production capacity with specialized low-pressure mercury vapor expertise. Philips Lighting competes through broad wavelength research investments spanning conventional and LED platforms.
Medical germicidal lamps are sealed ultraviolet radiation sources typically operating at 253.7 nanometers wavelength, constructed from fused quartz envelopes with mercury amalgam fills or solid-state semiconductor arrays, designed to destroy microbial DNA in clinical and water treatment environments. UV-C Lamps retain dominant installed volume across healthcare facilities while LED Germicidal Lamps capture accelerated replacement cycles due to mercury-phaseout directives. Pulsed Xenon technology differentiates within operating theater applications where rapid cycle turnover commands premium positioning.
FDA radiation safety standards and EPA mercury handling regulations constrain product entry while ISO 15858 UV exposure safety protocols shape international procurement specifications. The EU RoHS mercury exemption timeline pressures manufacturers toward solid-state platform transitions. Stakeholders must weigh wavelength efficacy against material compliance costs when configuring next-generation product portfolios.
Market Dynamics
The EU RoHS mercury exemption phaseout is compressing legacy low-pressure mercury lamp production timelines while accelerating solid-state LED platform transitions across hospital procurement channels.
Growth Catalysts
- Hospital Infrastructure Modernization:Germany's clinical infrastructure programs prioritize infection control upgrades, driving UV-C air disinfection system procurement across acute care facilities.
- Mercury-Phaseout Directives:The EU RoHS mercury exemption timeline creates replacement demand for solid-state germicidal platforms in water treatment and clinical environments.
- FDA Radiation Safety Standards:Updated medical device radiation benchmarks tighten performance requirements, filtering substandard products and elevating certified manufacturer market position.
Market Restraints
- Mercury Supply Chain Concentration:Specialized low-pressure mercury vapor expertise concentrates in Asian manufacturing clusters, creating single-source dependency risks for legacy lamp producers.
- Material Compliance Cost Escalation:Fused quartz envelope sourcing faces purity specification tightening from ISO 15858 UV exposure safety protocols, elevating input costs.
- LED Efficacy Limitations:Solid-state semiconductor arrays at 265-280 nanometer wavelengths achieve lower photon flux density than mercury amalgam fills in high-throughput water sterilization applications.
Strategic Opportunities
- Operating Theater Pulsed Systems:Rapid cycle turnover requirements in surgical suites create premium positioning for pulsed xenon technology differentiated by treatment speed.
- North American Hospital Procurement:American manufacturing base proximity offers supply commitment advantages for domestic healthcare system contracting.
- Broad Wavelength Research Convergence:Investments spanning conventional and LED platforms enable multi-spectrum disinfection protocols addressing resistant pathogen strains.
Industry Challenges
- Wavelength Efficacy Optimization:Manufacturers must balance 253.7 nanometer DNA destruction peak performance against solid-state material thermal management constraints.
- Certification Timeline Compression:EPA mercury handling regulations and FDA device approvals create extended validation periods for next-generation product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Germicidal Lamps Market |
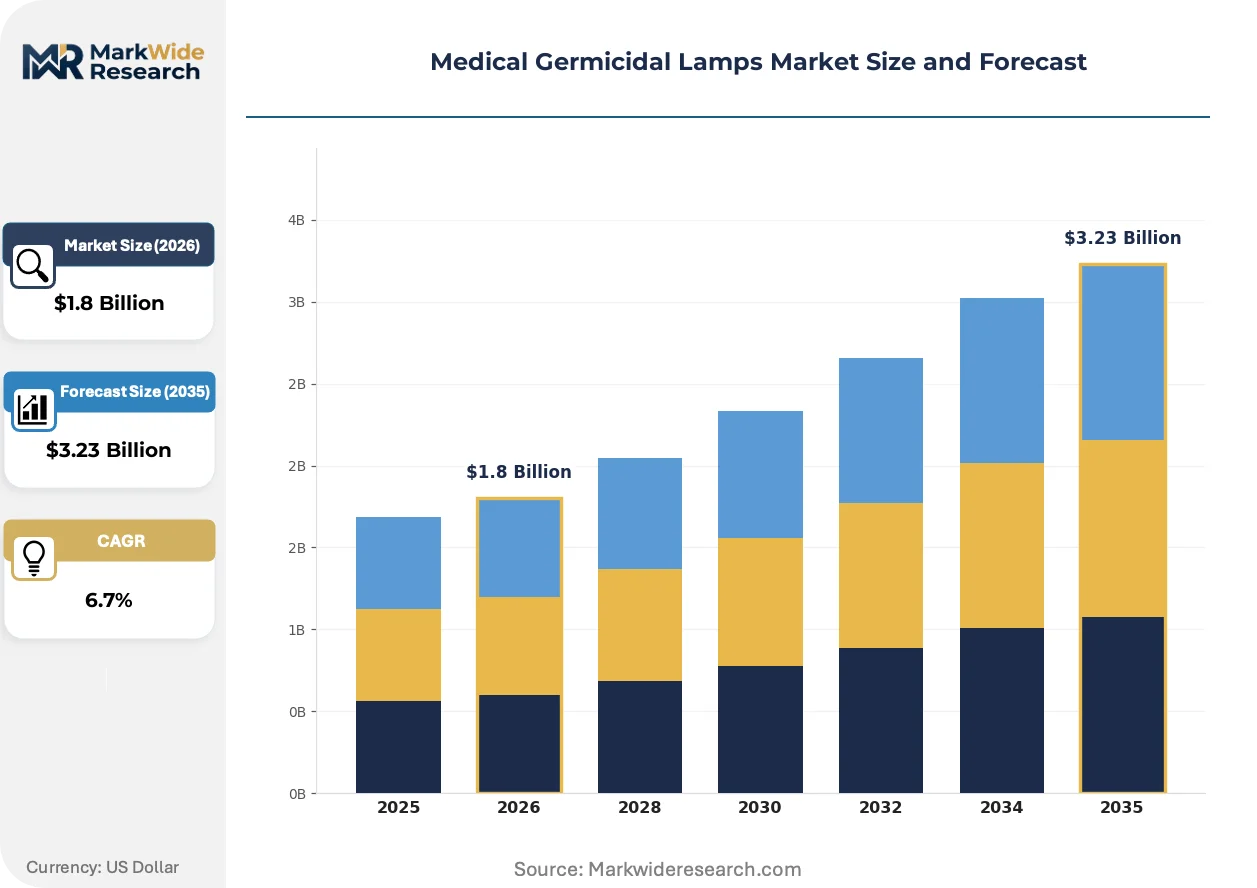
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV-C Lamps, Mercury Vapor Lamps, LED Germicidal Lamps, Disinfection Robots Application: Healthcare Facilities, Water Treatment, Air Purification, Surface Disinfection Technology: Conventional UV, Pulsed Xenon, Ozone-Free Technology, Hybrid Solutions End User: Hospitals, Laboratories, Commercial Buildings, Residential Users |
| Companies Covered | American Ultraviolet, Atlantic Ultraviolet, Steril-Aire, Light Sources, Spectronics Corporation, Herolab GmbH, UVP, Sankyo Denki, Philips Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Germicidal Lamps Market Shifts & Advancements
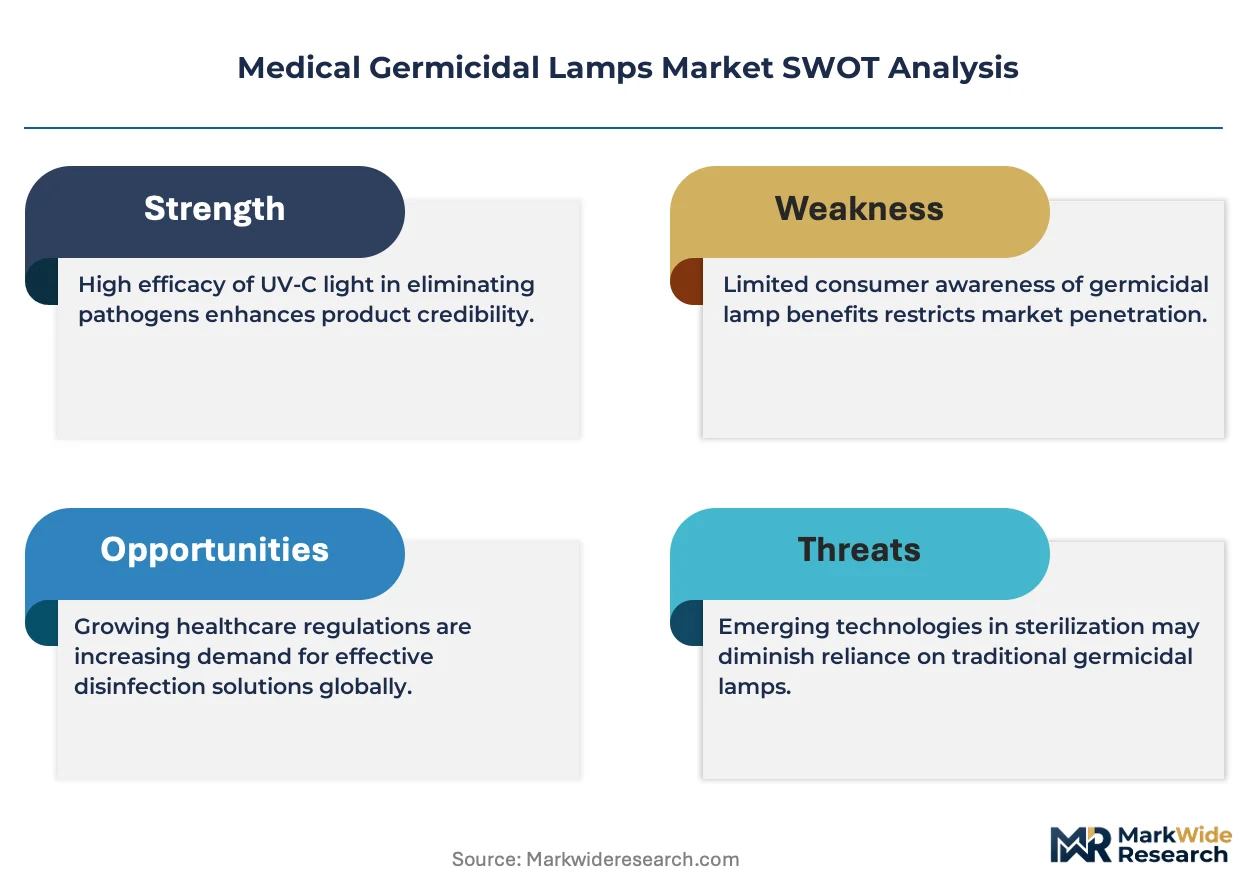
Technology transitions and regulatory compression are rewriting competitive positioning across germicidal lamp architectures. Platform convergence and procurement model evolution define the current innovation cycle.
LED germicidal arrays are supplanting conventional mercury vapor sources in healthcare facility retrofits. Hospital engineering departments accelerate replacement schedules to preempt RoHS compliance deadlines. The technology is supplanting legacy installed bases while compressing maintenance contract structures around solid-state reliability claims.
The EU RoHS mercury exemption timeline tightens allowable mercury content thresholds for medical lighting equipment. Manufacturers face forced platform migration toward semiconductor-based emission sources ahead of statutory deadlines. German clinical procurement specifications now prioritize mercury-free certification in tender evaluations, shifting supplier qualification criteria.
Acute care facilities consolidate UV-C system purchasing through group procurement organizations. Equipment specification authority centralizes at health system headquarters, displacing individual hospital engineering autonomy. This concentration pattern is most visible across integrated delivery networks in the United States, where standardization mandates override local vendor relationships.
Medical Germicidal Lamps Market Segmentation
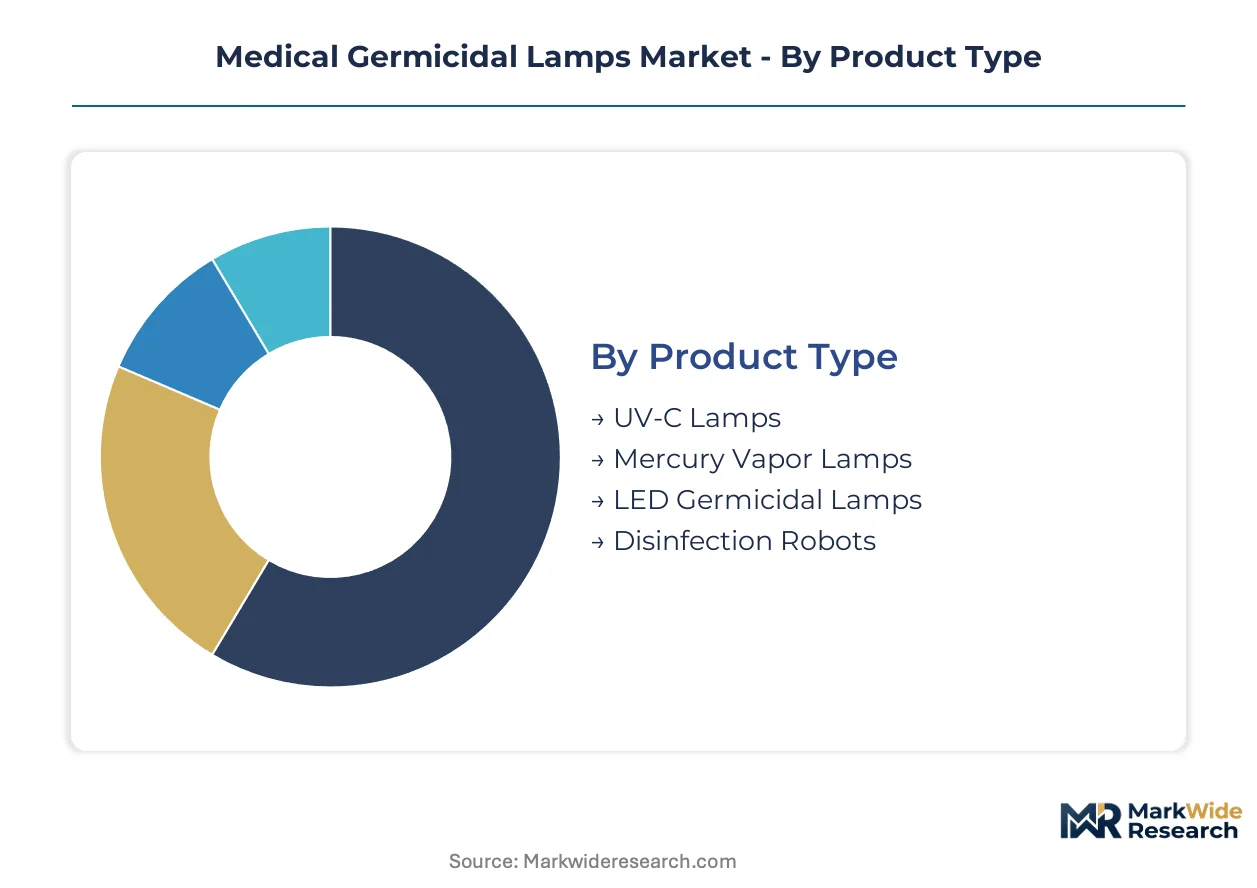
Medical germicidal lamp procurement channels diverge sharply by segment—hospital engineering departments source certified UV-C systems through group purchasing organizations, while water treatment utilities negotiate directly with manufacturers for high-throughput mercury vapor installations. Understanding these channel dynamics reveals where pricing power concentrates and which segments drive replacement cycle revenue.
Product Type:
Hospital procurement channels favor certified UV-C systems through group purchasing organizations, while water treatment utilities source high-capacity mercury vapor lamps through direct manufacturer negotiations.
- UV-C Lamps:Sealed ultraviolet radiation sources operating at 253.7 nanometers wavelength, constructed from fused quartz envelopes with mercury amalgam fills. Hospital procurement across Germany concentrates demand for these systems as clinical infrastructure modernization programs prioritize infection control upgrades.
- LED Germicidal Lamps:Solid-state semiconductor arrays emitting at 265-280 nanometer wavelengths without mercury content. Replacement demand accelerates in healthcare facilities preempting EU RoHS mercury exemption deadlines, though photon flux density limitations constrain high-throughput water sterilization applications.
- Mercury Vapor Lamps:Specialized low-pressure mercury vapor expertise anchors Asian production capacity for legacy installations.
- Disinfection Robots:Autonomous mobile platforms integrating UV-C or pulsed xenon sources for room-scale treatment.
UV-C Lamps dominate installed base. LED Germicidal Lamps are where expansion concentrates.
Application:
Cost tier stratification separates premium surgical suite systems from standard HVAC retrofit modules, with water treatment commanding the highest unit economics due to throughput requirements.
- Healthcare Facilities:Acute care installations spanning patient rooms, operating theaters, and sterile processing departments. German clinical procurement specifications now prioritize mercury-free certification in tender evaluations, shifting supplier qualification criteria toward solid-state platforms.
- Water Treatment:Municipal and industrial sterilization systems requiring continuous high-dose UV exposure. Mercury amalgam fills retain performance advantages in high-throughput applications where photon flux density requirements exceed current LED capabilities.
- Air Purification:HVAC-integrated and standalone units for occupied space disinfection.
- Surface Disinfection:Targeted treatment systems for medical equipment and high-touch environments.
Healthcare Facilities command premium pricing tiers. Water Treatment represents the steepest expansion trajectory for high-capacity system deployments.
Technology:
Application context dictates technology selection—rapid cycle turnover in surgical suites favors pulsed xenon, while continuous-duty water treatment relies on conventional UV architectures.
- Conventional UV:Continuous-wave mercury-based or LED emission at biocidal wavelengths. Hospital engineering departments accelerate replacement schedules to preempt RoHS compliance deadlines, compressing maintenance contract structures around solid-state reliability claims.
- Pulsed Xenon:High-intensity flash discharge systems delivering rapid microbial inactivation. Operating theater applications command premium positioning where treatment speed differentiates competitive offerings.
- Ozone-Free Technology:Wavelength-filtered emission below 200 nanometers to prevent ozone generation.
- Hybrid Solutions:Multi-modal platforms combining UV-C with filtration or chemical augmentation.
Conventional UV retains volume leadership. Pulsed Xenon is gaining share fastest in premium surgical applications.
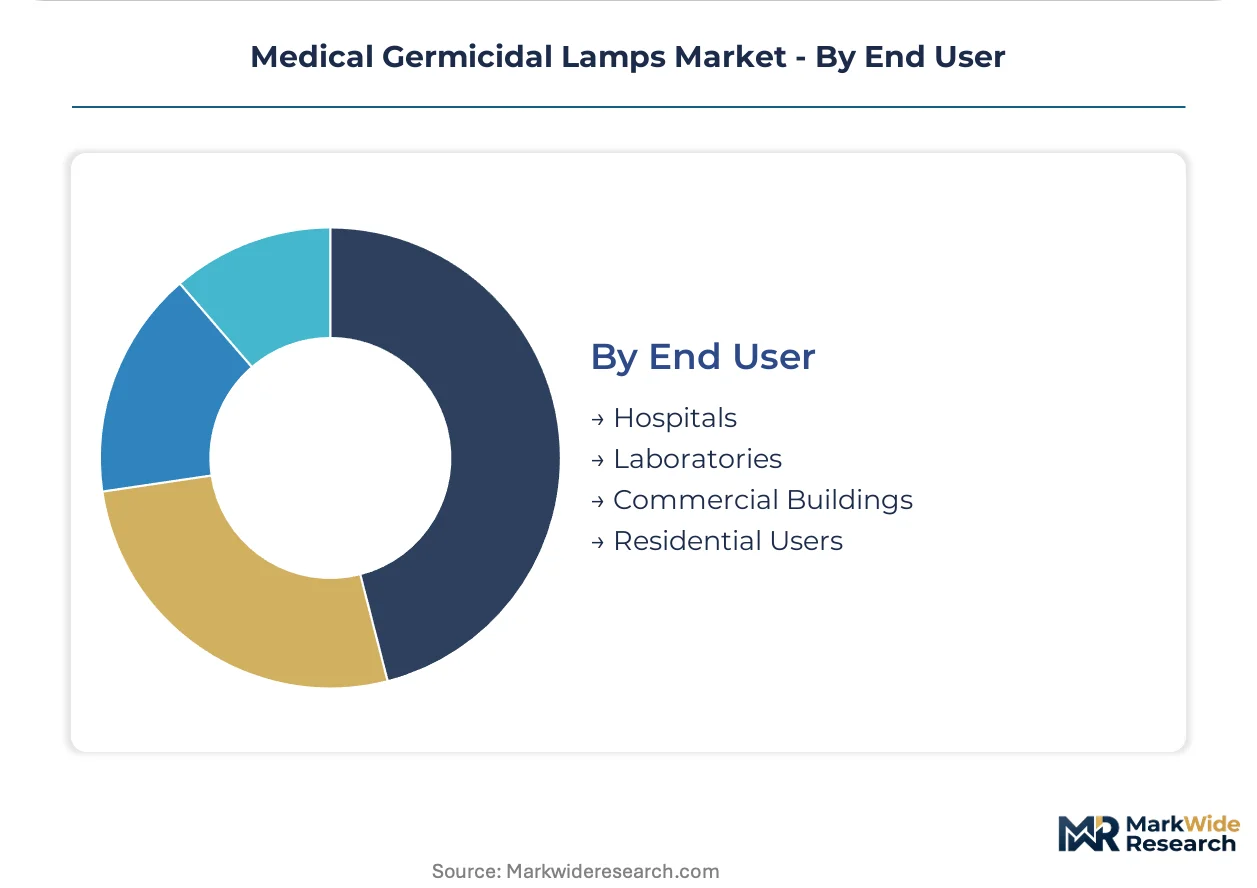
End User:
Customer type determines specification authority—hospital headquarters centralize purchasing decisions while residential users buy through retail channels with minimal technical oversight.
- Hospitals:Acute care and ambulatory facilities with centralized procurement through integrated delivery networks. Equipment specification authority concentrates at health system headquarters across the United States, displacing individual hospital engineering autonomy.
- Laboratories:Research and diagnostic facilities requiring precision-controlled sterilization environments. FDA radiation safety standards tighten performance benchmarks, filtering substandard products and elevating certified manufacturer market position.
- Commercial Buildings:Office, hospitality, and institutional installations with HVAC-integrated systems.
- Residential Users:Consumer-grade portable units distributed through retail channels.
Hospitals anchor procurement volume. Laboratories are where premium positioning concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized low-pressure mercury vapor expertise concentrates in Asian manufacturing clusters, while German clinical infrastructure programs and American domestic supply commitments reshape procurement geography. FDA radiation safety standards and EU RoHS mercury exemption timelines create divergent compliance pathways across national markets.
United States
Hospital procurement of UV-C air disinfection systems is expanding across acute care facilities, with integrated delivery networks centralizing equipment specification authority at health system headquarters. FDA updated medical device radiation safety standards tighten performance benchmarks for germicidal equipment, filtering substandard products from the market. American Ultraviolet leverages its domestic manufacturing base to sustain supply commitments for healthcare procurement in the Midwest and Southeast corridors.
Germany
Clinical infrastructure modernization programs prioritize infection control upgrades, driving concentrated demand for certified UV-C systems across Bavaria and North Rhine-Westphalia. EU RoHS mercury exemption timelines pressure manufacturers toward solid-state platform transitions, with German tender evaluations now prioritizing mercury-free certification. Herolab GmbH anchors specialized production capacity in the Baden-Württemberg medical technology cluster.
Japan
Sankyo Denki anchors Asian production capacity with specialized low-pressure mercury vapor expertise, serving legacy installation demand across East Asian healthcare systems. METI industrial standards shape procurement specifications for medical device radiation safety in Tokyo-Osaka corridor facilities. The Kanto region concentrates semiconductor-based germicidal research investments as manufacturers anticipate mercury-phaseout directives.
China
Domestic healthcare infrastructure expansion drives procurement volume for conventional UV-C systems in tier-one hospital networks across the Yangtze River Delta. NMPA medical device registration requirements extend validation timelines for imported germicidal equipment. Shenzhen and Shanghai manufacturing clusters specialize in LED germicidal array assembly for export markets preempting RoHS compliance deadlines.
United Kingdom
NHS infection control procurement frameworks standardize UV-C system specifications across England's acute trust networks, consolidating demand through centralized tender processes. MHRA conformity assessment procedures align with EU MDR transition timelines for medical device radiation-emitting products. The Oxford-Cambridge-London arc concentrates research investments in broad wavelength disinfection protocols addressing resistant pathogen strains.
Medical Germicidal Lamps Market Competitive Landscape
Concentration sits with diversified lighting conglomerates and specialized ultraviolet equipment fabricators competing across distinct technology platforms. The vendor base spans mercury-based legacy specialists, solid-state semiconductor developers, and pulsed xenon surgical suite innovators. Two strategic archetypes dominate: manufacturers with captive fused quartz supply chains defending high-throughput water treatment positions, and LED platform developers capturing accelerated healthcare replacement cycles. Competitive moves center on backward integration into semiconductor epitaxy and strategic partnerships with group purchasing organizations.
Among North American ultraviolet specialists, American Ultraviolet and Atlantic Ultraviolet occupy positions within the legacy equipment tier, while Philips Lighting represents the diversified conglomerate archetype spanning conventional and solid-state platforms. Sankyo Denki exemplifies the Asian manufacturing concentration model for specialized mercury vapor expertise. These three anchors illustrate how geographic production clustering and technology platform breadth define competitive differentiation in procurement channels tightening around certification compliance and supply security.
| Leading Market Players |
|---|
| American Ultraviolet |
| Atlantic Ultraviolet |
| Steril-Aire |
| Light Sources |
| Spectronics Corporation |
| Herolab GmbH |
| UVP |
| Sankyo Denki |
| Philips Lighting |
| Others |
Supply & Pricing Matrix
Long-term service contracts with health system group purchasing organizations lock in multi-year supply commitments while capping price volatility for certified UV-C system manufacturers. These arrangements bundle equipment procurement with preventive maintenance schedules, creating predictable revenue streams that offset raw material cost fluctuations in fused quartz and semiconductor substrates.
Pricing Analysis
FDA radiation safety standards dictate the pricing tier structure across medical germicidal lamp procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared surgical suite systems from general HVAC retrofit modules and uncertified consumer-grade units. Price differentiation stems from ISO 15858 compliance certification and captive fused quartz supply chain control. Cost compression in the standard tier is intensifying because LED platform transitions require upfront R&D amortization. Water treatment utilities demonstrate lowest price sensitivity due to throughput-critical performance requirements, while residential retail channels face acute margin pressure.
Supply Chain Analysis
Strategic stockpiling of mercury amalgam fills and fused quartz envelopes characterizes procurement behavior among legacy UV-C lamp manufacturers confronting EU RoHS exemption deadlines. Geographic supply concentration centers on Japan, China, and Germany for specialized low-pressure mercury vapor expertise, semiconductor epitaxy, and precision glassblowing respectively. Raw material dependencies draw from high-purity fused quartz, mercury amalgam formulations, and aluminum nitride substrates for LED arrays. Single-source vulnerability concentrates in Asian mercury vapor processing capabilities. Distribution runs through health system group purchasing organizations and direct manufacturer negotiations with municipal water utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maintenance contract bundling and recertification services are expanding faster than hardware sales as hospital engineering departments outsource UV-C system lifecycle management. This service-attach dynamic restructures vendor economics toward recurring revenue models.
For Market Incumbents: Consolidate backward integration into fused quartz envelope manufacturing to defend water treatment market position against LED substitution threats. Acquire semiconductor epitaxy capabilities in the Kanto region to secure solid-state platform transitions ahead of RoHS deadlines. Channel control through exclusive GPO partnerships remains the critical defensive lever. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for mercury-free LED germicidal arrays open immediate access to German hospital procurement channels. Target underpenetrated ambulatory surgical centers in the American Midwest where centralized health system purchasing has not yet consolidated. Position through subscription-based equipment-plus-service models that bypass capital budget constraints. For Investors and Strategic Acquirers: Specialized quartz-to-semiconductor transition specialists with captive hospital service contracts represent the highest-conviction acquisition archetype. Long-term viability hinges on successful platform migration before mercury exemption expiration. Monitor FDA enforcement discretion letters on LED efficacy claims as the critical inflection signal for technology winner determination.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fused Quartz | Captive envelope supply secures water treatment pricing power against LED competitors. |
| FDA 510(k) Fast-Track Submission | Accelerated clearance unlocks German hospital procurement ahead of RoHS deadlines. |
| Hospital System Partnership | Exclusive GPO contracts displace competing vendors from integrated delivery networks. |
| Semiconductor Epitaxy Investment | In-house LED chip production reduces dependency on Asian substrate suppliers. |
| Maintenance Contract Bundling | Recurring service revenue stabilizes cash flows through equipment replacement cycles. |
Research Methodology
A spread of perspectives from hospital biomedical engineers, GPO contracts managers, UV-C system manufacturers, and water treatment utility procurement directors converged on the working assumptions. Primary field engagement combined with secondary validation from FDA 510(k) filings, EPA mercury handling compliance records, EU RoHS exemption registry updates, and hospital procurement database extracts. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product architecture, application environment, emission technology, and end-user procurement authority. CAGRs derived from installed base turnover rates, replacement cycle compression, and regulatory-driven platform transition timelines. Forecast inputs incorporated EU mercury exemption phaseout schedules and FDA radiation safety standard revision trajectories throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained healthcare capital expenditure levels and statutory mercury exemption timelines would require recalibration. Forecasts reflect documented assumptions on LED efficacy improvement curves and hospital consolidation patterns. Revision becomes warranted when FDA enforcement posture on solid-state germicidal claims crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Fracture Fixation Products Market
Medical Devices
Blood Warmers Market
Medical Devices
Latin America General Surgical Devices Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Vascular Boot Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Walking Aids Market
Medical Devices
Skincare Devices Market
Medical Devices
Acoustic Puncture Assist Devices Market
Medical Devices
General Surgical Devices Market
Medical Devices
Illuminating Eye Massagers Market