
 Wire and Cable Materials Market | 2026-2036
Wire and Cable Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Wire and Cable Materials Market Outlook
China is narrowing its dependence on imported high-performance polymer compounds through domestic capacity expansions in Zhejiang and Jiangsu provinces. DuPont de Nemours leverages its fluoropolymer expertise to dominate aerospace and data center cable jacketing segments. Solvay anchors European supply of sulfone-based insulation resins for high-temperature automotive wiring. Mitsubishi Chemical Corporation specializes in halogen-free flame-retardant compounds serving Japanese rail and nuclear infrastructure standards.
Wire and cable materials encompass conductive metals, insulating polymers, and protective sheathing engineered to transmit electrical power or optical signals across specified voltage ratings, temperature ranges, and environmental exposure conditions. Copper and aluminum conductors remain dominant in power transmission due to conductivity-to-cost ratios, while fiber optic glass and polymer coatings serve bandwidth-intensive telecommunications backbones. XLPE insulation commands premium positioning in medium-voltage distribution networks where thermal aging resistance determines replacement cycles. PVC compounds occupy volume-driven construction segments where cost minimization overrides extended service life requirements. Fiber optic materials represent the fastest-expanding margin pool as 5G densification and hyperscale data center builds strain silica supply chains.
China's SAMR enforces GB/T standards for low-smoke zero-halogen cable performance in public infrastructure, redirecting formulation demand toward phosphorous-nitrogen systems. The EU RoHS directive and REACH chemical restrictions constrain legacy plasticizer and heavy-metal stabilizer use across European cable manufacturing. The US National Electrical Code, administered by the NFPA, mandates specific insulation ratings for building wire that shape domestic PVC and XLPE compound specifications. Stakeholders must monitor how diverging regional flammability and substance restrictions fragment material qualification requirements across export-oriented supply chains.
Market Dynamics
Flame-retardant material compliance divergence across China's GB standards, EU RoHS, and US NEC codes is fragmenting supplier qualification requirements and forcing parallel formulation tracks for export-oriented cable manufacturers.
Growth Catalysts
- Renewable energy grid interconnection:Offshore wind farms and solar utility-scale deployments in Germany, the United States, and India are accelerating consumption of copper and aluminum conductors rated for high-voltage transmission.
- REACH chemical restrictions:The EU's phased elimination of legacy plasticizers and heavy-metal stabilizers is redirecting formulation demand toward phosphorous-nitrogen halogen-free systems with superior smoke density performance.
- 5G densification:Hyperscale data center construction across Singapore, Ireland, and Virginia is straining silica supply chains for fiber optic glass and polymer coatings serving bandwidth-intensive telecommunications backbones.
Market Restraints
- Copper price volatility:Concentration of mined supply in Chile and Peru exposes conductor manufacturers to exchange-traded commodity swings that compress margin predictability on fixed-price infrastructure contracts.
- Fluoropolymer supply concentration:Aerospace and data center cable jacketing segments depend on a narrow supplier base for high-performance resins, creating qualification bottlenecks during demand surges.
- XLPE thermal aging trade-offs:Medium-voltage distribution networks face replacement cycle uncertainty where accelerated thermal degradation in humid environments limits service life guarantees.
Strategic Opportunities
- Vietnam and Thailand manufacturing clusters:Southeast Asian industrial zones are concentrating demand for sheathing compounds that meet dual export compliance to both EU RoHS and China's GB/T standards.
- Low-smoke zero-halogen mandates:China's SAMR enforcement of GB/T standards in public infrastructure creates formulation pull-through for phosphorous-nitrogen systems displacing legacy halogenated compounds.
- Silica-polymer coating convergence:Fiber optic cable producers are integrating advanced polymer buffer layers with pure silica cores to reduce signal attenuation in subsea and arctic deployments.
Industry Challenges
- Formulation chemist scarcity:Cable compound manufacturers face recruitment gaps for specialists capable of balancing flame-retardant performance with mechanical flexibility across temperature ranges.
- Multi-jurisdiction certification timelines:Simultaneous qualification for China's GB standards, EU CE marking, and US UL listings extends product launch cycles by 18-24 months for new insulation systems.
- Legacy PVC infrastructure integration:Building wire installers encounter compatibility friction when specifying XLPE or halogen-free alternatives in retrofit projects designed around established PVC termination practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire and Cable Materials Market |
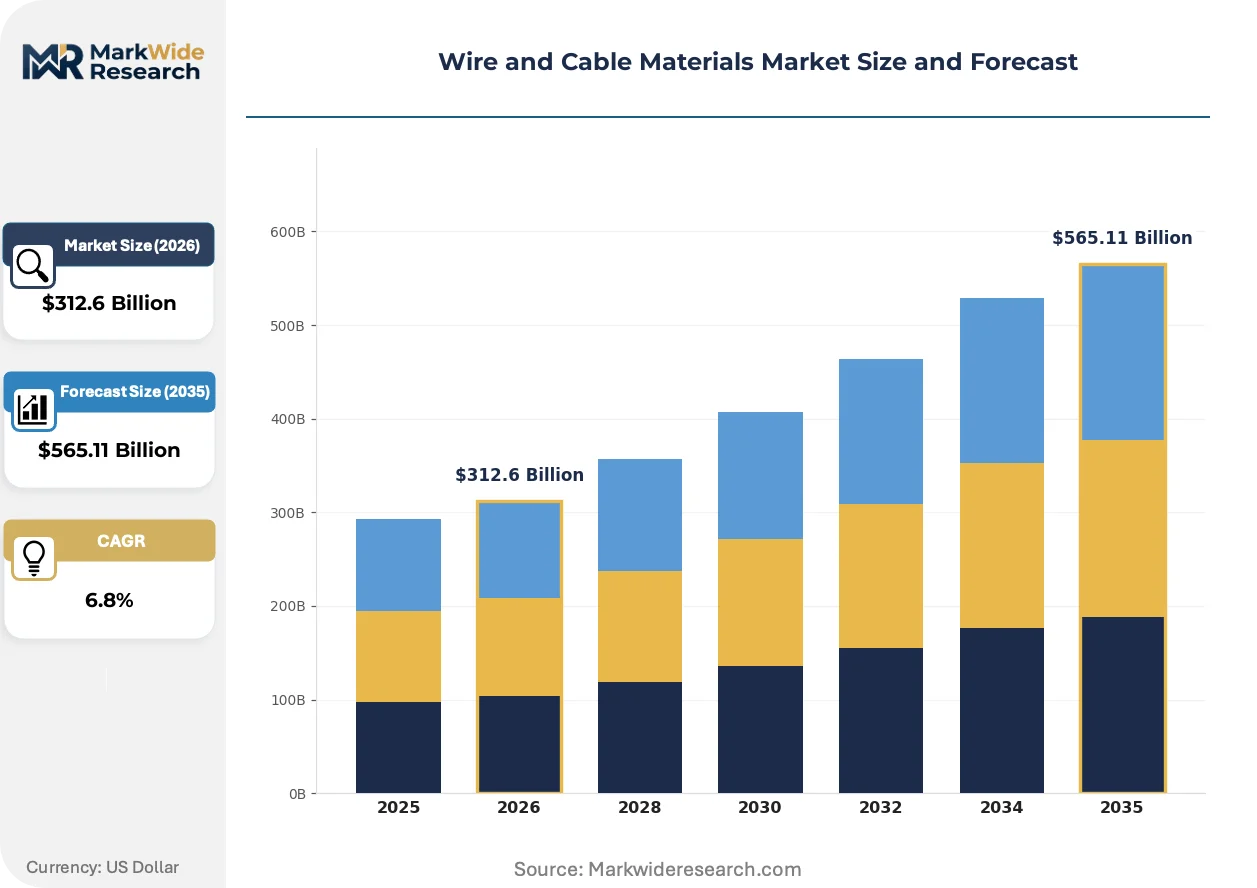
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Copper, Aluminum, Fiber Optic, Steel Insulation Type: PVC, XLPE, PE, Rubber Application: Construction, Automotive, Telecommunications, Industrial End User: OEMs, Electrical Contractors, Utility Companies, Telecommunications Providers |
| Companies Covered | Evonik Industries, Solvay, Exxon Mobil Corporation, Avient Corporation, Hanwha Solutions Corporation, Mitsubishi Chemical Corporation, DuPont de Nemours, Borouge, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire and Cable Materials Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape conductor insulation and protective sheathing specifications across power transmission, telecommunications, and transportation infrastructure verticals.
Cross-linked polyethylene (XLPE) insulation is digitizing medium-voltage distribution network monitoring through embedded fiber optic sensing strands that enable real-time thermal profiling. European grid operators in Germany and the Netherlands are adopting these smart cable systems at accelerated procurement cycles. The technology is digitizing asset management practices by compressing fault detection response times from hours to seconds.
China's SAMR has tightened GB/T 19666 enforcement for low-smoke zero-halogen performance in subway, airport, and hospital cable installations. Domestic manufacturers in Zhejiang and Jiangsu provinces are retooling compounding lines to meet phosphorous-nitrogen formulation requirements. Public infrastructure project tenders now disqualify halogenated alternatives, redirecting volume toward qualified domestic suppliers.
Utility procurement departments are consolidating cable specifications around lifecycle cost models that weight thermal aging resistance against initial capital outlay. Industrial buyers in Japanese rail and nuclear sectors now require 40-year service life guarantees backed by accelerated aging test data. This specification compression is most visible in procurement contracts issued by Tokyo Metro and Kansai Electric Power.
Wire and Cable Materials Market Segmentation
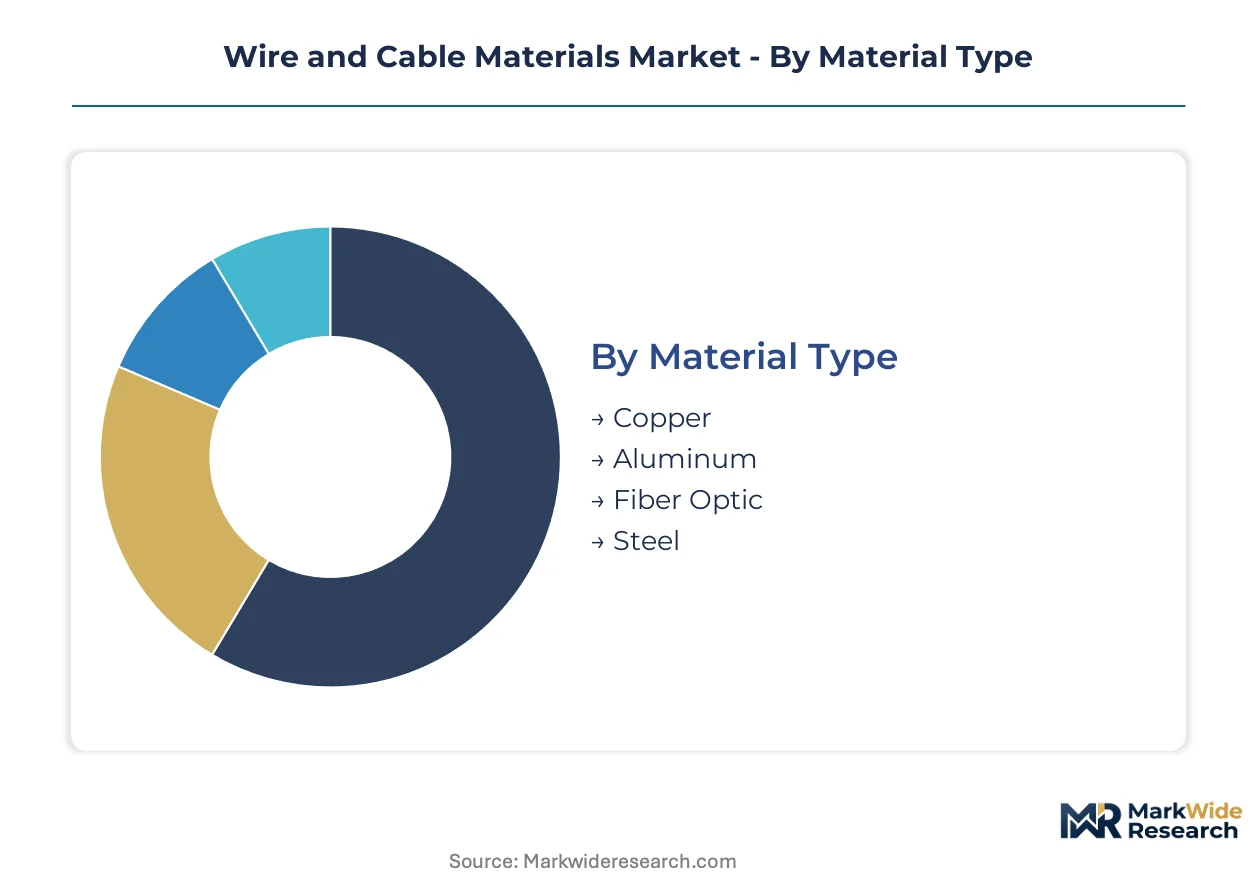
Wire and cable materials fragment across four distinct classification axes, each carrying different margin profiles and qualification burdens. Procurement departments prioritize material type and insulation chemistry for total cost of ownership calculations, while application and end-user segmentation determines compliance pathway complexity.
Material Type:
After-sales service intensity varies sharply across conductor chemistries, with fiber optic deployments demanding specialized splicing expertise and copper networks requiring corrosion monitoring protocols that aluminum and steel systems rarely match.
- Copper:High-conductivity electrolytic grades dominate medium-voltage distribution and building wire specifications where termination reliability is non-negotiable. German grid operators and Indian utility companies are accelerating procurement of copper conductors for offshore wind interconnection projects where salt exposure accelerates alternative metal degradation.
- Aluminum:Lightweight conductivity ratios favor overhead transmission lines and automotive wiring harnesses where mass reduction directly impacts energy efficiency. Vietnam's manufacturing clusters are concentrating demand for aluminum alloy conductors that meet both China's GB/T standards and EU RoHS compliance for export-oriented cable assemblies.
- Fiber Optic:Pure silica cores with polymer buffer layers serve bandwidth-intensive telecommunications infrastructure where signal attenuation determines maximum span lengths.
- Steel:High-tensile strength armoring protects subsea and direct-burial cables against mechanical stress and rodent damage in harsh installation environments.
Copper holds the largest share; momentum sits with fiber optic as 5G densification strains silica supply chains.
Insulation Type:
Cost tier stratification separates commodity compounds from engineered systems, with PVC occupying volume-driven construction segments and XLPE commanding premium positioning in utility-scale procurement.
- PVC:Plasticized polyvinyl chloride compounds dominate residential and commercial building wire where cost minimization overrides extended service life requirements. REACH chemical restrictions are forcing European manufacturers toward non-phthalate plasticizers that maintain flexibility across temperature ranges.
- XLPE:Cross-linked polyethylene insulation delivers superior thermal aging resistance for medium-voltage distribution networks where replacement cycle economics favor higher initial capital outlay. Japanese rail operators including Tokyo Metro now require 40-year service life guarantees backed by accelerated aging test data for XLPE-sheathed traction power cables.
- PE:Linear low-density polyethylene serves low-voltage telecommunications and rural electrification projects where moisture resistance and dielectric stability suffice.
- Rubber:Ethylene-propylene and chloroprene compounds flex through repeated bending cycles in portable power, mining, and renewable energy maintenance applications.
XLPE captures the steepest expansion trajectory in utility procurement; PVC retains volume leadership in residential construction.
Application:
Customer type heterogeneity drives specification divergence, with industrial buyers demanding lifecycle cost models and construction contractors prioritizing installation speed and termination compatibility.
- Construction:Building wire specifications follow national electrical codes that fragment compound qualification requirements across export markets. China's SAMR enforcement of GB/T 19666 for low-smoke zero-halogen performance in public infrastructure is displacing halogenated alternatives in airport and hospital projects.
- Automotive:High-temperature automotive wiring demands sulfone-based and fluoropolymer insulation systems that withstand engine compartment thermal cycling. European supply chains anchored by Solvay are concentrating sulfone resin production for electric vehicle high-voltage harnesses.
- Telecommunications:Hyperscale data center construction across Singapore, Ireland, and Virginia is pulling fiber optic materials with advanced polymer buffer layers.
- Industrial:Process automation and heavy machinery require sheathing compounds that resist chemical exposure, abrasion, and flex fatigue in manufacturing environments.
Construction absorbs the greatest material volume; telecommunications is climbing the fastest as bandwidth infrastructure investment accelerates.
End User:
Supply concentration patterns favor direct relationships with utility companies and telecommunications providers, while electrical contractors and OEMs fragment procurement across distributor networks.
- OEMs:Original equipment manufacturers specify custom cable assemblies for automotive, appliance, and industrial machinery integration where termination geometry and flex life are design-critical. Japanese automotive OEMs are consolidating halogen-free compound specifications to meet domestic rail and nuclear infrastructure standards.
- Electrical Contractors:Installation firms encounter compatibility friction when specifying XLPE or halogen-free alternatives in retrofit projects designed around established PVC termination practices.
- Utility Companies:Power transmission and distribution operators are consolidating procurement around smart cable systems with embedded fiber optic sensing for real-time thermal profiling.
- Telecommunications Providers:5G network operators and submarine cable consortiums drive silica supply chain investment for bandwidth expansion.
Utility companies command the largest procurement scale; telecommunications providers are gaining share fastest as infrastructure investment cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes wire and cable materials at manufacturing scale, while Germany and the United States prioritize high-performance insulation systems for grid modernization. Japan and Vietnam represent contrasting demand profiles—mature infrastructure replacement versus export-oriented manufacturing expansion.
China
Offshore wind interconnection projects along the Fujian and Guangdong coasts are accelerating copper conductor procurement. SAMR enforces GB/T 19666 low-smoke zero-halogen standards in subway and hospital installations. Zhejiang and Jiangsu provinces host domestic capacity expansions for high-performance polymer compounds that narrow import dependence.
Germany
Grid operators in North Rhine-Westphalia and Bavaria deploy smart cable systems with embedded fiber optic sensing for real-time thermal profiling. ECHA REACH restrictions eliminate legacy plasticizers and heavy-metal stabilizers from cable formulations. Industrial clusters around Cologne and Hamburg concentrate sulfone-based insulation resin production for automotive wiring harnesses.
United States
Hyperscale data center construction in Virginia and Texas strains silica supply chains for fiber optic glass and polymer coatings. NFPA-administered National Electrical Code mandates specific insulation ratings for building wire that shape domestic PVC and XLPE compound specifications. Utility procurement departments in California and New York consolidate around lifecycle cost models weighting thermal aging resistance.
Japan
Tokyo Metro and Kansai Electric Power require 40-year service life guarantees backed by accelerated aging test data for XLPE-sheathed cables. METI oversees JIS standards alignment with halogen-free compound specifications for rail and nuclear infrastructure. Osaka-based manufacturers specialize in phosphorous-nitrogen flame-retardant systems serving domestic public infrastructure tenders.
Vietnam
Manufacturing clusters in Binh Duong and Dong Nai provinces concentrate demand for industrial-grade cable sheathing compounds meeting dual export compliance. Cable assemblers serving EU and Chinese markets simultaneously navigate RoHS chemical restrictions and GB/T standards. Aluminum alloy conductors gain preference in overhead transmission lines where mass reduction impacts energy efficiency.
Wire and Cable Materials Market Competitive Environment
Capability concentration sits with integrated polymer specialists; scale advantage sits with diversified chemical conglomerates. The market structures around three tiers: global material science leaders with fluoropolymer and sulfone expertise, regional compounders serving construction and automotive volume, and niche specialists in halogen-free formulations. Strategic moves center on backward integration into resin production and geographic expansion into Southeast Asian manufacturing zones.
Among the integrated specialists, DuPont de Nemours and Solvay occupy positions defined by high-performance resin expertise. DuPont exemplifies the fluoropolymer-dominant archetype serving aerospace and data center cable jacketing segments. Solvay anchors European supply of sulfone-based insulation resins. Mitsubishi Chemical Corporation represents the Asia-Pacific specialist tier with halogen-free compound capabilities aligned to Japanese rail and nuclear standards.
| Leading Market Players |
|---|
| Evonik Industries |
| Solvay |
| Exxon Mobil Corporation |
| Avient Corporation |
| Hanwha Solutions Corporation |
| Mitsubishi Chemical Corporation |
| DuPont de Nemours |
| Borouge |
| Sumitomo Electric Industries |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Zhejiang and Jiangsu polymer compounding corridors is compressing margins for halogen-free flame-retardant suppliers while simultaneously accelerating price competition for export-oriented cable manufacturers seeking dual GB/T and RoHS compliance.
Pricing Analysis
Long-term offtake contracts dominate copper and aluminum conductor procurement by German grid operators and Indian utilities, insulating these buyers from spot market volatility that punishes smaller cable assemblers in Vietnam and Thailand. Three-tier pricing structure across premium, standard, and economy levels separates XLPE insulation systems with 40-year service guarantees from commodity PVC compounds in residential construction. Pricing pressure stems from REACH-mandated plasticizer substitutions that raise European compound production costs without commensurate pass-through elasticity. Electrical contractors exhibit highest price sensitivity, while Japanese rail operators and nuclear utilities prioritize lifecycle cost models over initial capital outlay.
Supply Chain Analysis
Contract manufacturing concentration in China's Jiangsu province, South Korea's Ulsan petrochemical cluster, and Germany's Cologne industrial zone controls global supply of sulfone-based insulation resins and fluoropolymer jacketing compounds. Raw material dependencies center on Chilean and Peruvian copper concentrates, high-purity silica for fiber optic cores, and phosphorous-nitrogen flame-retardant precursors. Single-source vulnerability concentrates in aerospace-grade fluoropolymer supply where DuPont de Nemours maintains dominant capacity. Distribution runs through regional compounders serving construction and automotive volume, with direct OEM relationships commanding premium positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from aluminum alloy conductors displacing copper in overhead transmission where mass reduction drives procurement decisions, alongside fiber optic sensing integration threatening conventional insulation monitoring revenues.
For Market Incumbents: Entrench fluoropolymer and sulfone resin expertise through backward integration into monomer production, securing captive supply for aerospace and data center cable jacketing segments. Expand compounding capacity in Vietnam's Binh Duong province to capture dual-compliance demand from export-oriented cable assemblers navigating both EU RoHS and China's GB/T standards. Prioritize certification investment for phosphorous-nitrogen halogen-free systems ahead of tightening SAMR enforcement in public infrastructure tenders. For New Entrants and Emerging Players: Southeast Asian manufacturing clusters present underpenetrated white space for industrial-grade sheathing compounds meeting simultaneous EU and Chinese compliance requirements. Target Vietnam and Thailand cable assemblers with formulation services bridging GB/T 19666 and RoHS chemical restrictions, avoiding direct confrontation with integrated polymer specialists. Pursue partnership-based go-to-market models with regional distributors lacking technical compounding capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fiber optic silica purification and phosphorous-nitrogen flame-retardant synthesis as 5G densification strains supply chains. Position for long-term viability by acquiring mid-cap compounders with demonstrated dual-certification capabilities and established relationships with Japanese rail or nuclear infrastructure buyers. Monitor copper-aluminum substitution rates in German and Indian offshore wind interconnection projects as early indicators of conductor demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive supply of sulfone and fluoropolymer monomers insulates margins from ECHA REACH-driven raw material constraints. |
| Dual-Certification Capacity Expansion | Zhejiang and Jiangsu compounding lines qualified for both GB/T 19666 and RoHS capture Southeast Asian export demand. |
| Smart Cable System Development | Embedded fiber optic sensing in XLPE insulation enables real-time thermal profiling for German and Dutch grid operators. |
| Halogen-Free Formulation Investment | Phosphorous-nitrogen systems displace legacy compounds in China's subway and hospital installations under SAMR enforcement. |
| Southeast Asian Manufacturing Footprint | Binh Duong and Dong Nai facilities reduce logistics costs for cable assemblers serving EU and Chinese markets simultaneously. |
Study Parameters
Cross-validation between primary interviews with polymer compounding plant managers, cable OEM procurement leads, and utility grid planning officers anchors the qualitative findings against secondary validation from customs trade data, SEC 10-K filings of listed chemical conglomerates, and SAMR regulatory bulletins. Bottom-up triangulation aggregates individual facility capacity announcements and tender awards, while top-down analysis reconciles these against national grid investment disclosures and hyperscale data center construction permits. Primary fieldwork concentrated on formulation chemists and technical R&D directors capable of articulating flame-retardant performance trade-offs across temperature ranges.
Calibration against historical replacement cycles for medium-voltage distribution networks and fiber optic deployment trajectories in Singapore, Ireland, and Virginia informs the analytical framework across the analysis window. Segmentation dimensions include material type, insulation chemistry, application vertical, and end-user procurement archetype, with regional regulatory clusters treated as distinct demand drivers. CAGRs derive from elasticity-adjusted consumption models incorporating copper price volatility coefficients and silica supply chain constraints. Industry-specific forecast inputs encompass accelerated aging test data requirements from Tokyo Metro and Kansai Electric Power, alongside ECHA phased elimination timelines for legacy plasticizers.
Practitioners should monitor copper concentrate export disruptions from Chile and Peru, SAMR enforcement intensity for GB/T 19666 compliance, and fiber optic silica purification capacity additions as revision triggers for early signals of demand inflection. Forecasts reflect assumptions regarding sustained offshore wind interconnection investment in Germany, the United States, and India, alongside continued 5G densification driving bandwidth infrastructure expenditure. Quarterly review of utility procurement contract specifications, chemical regulatory bulletins from ECHA and SAMR, and hyperscale data center capex disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Data Center Wire and Cable Market
Cables
Active Optical Cable Market
Cables
Radio Frequency Cables Market
Cables
Latin America Wire and Cable Market
Cables
United States Cable Accessories Market
Cables
EPR Cable Market
Cables
Electric Submersible Cables (ESP) Market
Cables
Europe Cable Joints Market
Cables
Instrumentation Cables Market
Cables
Fire Resistance Cable Market
Cables
Military Cable Market
Cables
Coaxial Cable Market
Cables
Industrial Cable Reels Market
Cables
India Wire and Cable Market
Cables
Sensing Cable Market
Cables
High Voltage Cables Market